

Key Takeaways
- Morgan Stanley cut its DraftKings price target to $31 from $36 on Oct. 19 and kept its Overweight rating, a call that still implies 57% upside.
- DraftKings shares have lost 46% over the past year on worries about prediction markets and a second quarter in which adjusted EBITDA fell to $115 million from $301 million.
- Analysts have cut their 2026 earnings estimate to $0.88 a share from $1.03 three months ago, but their $1.70 estimate for 2027 hasn’t moved.
- The call looks plausible but stretched: $31 is 28.5x next-twelve-months earnings against about 17x today, so it needs a higher multiple or 2027’s earnings to arrive on schedule.
DraftKings (DKNG) has lost 46% over the past year, and Wall Street keeps cutting its price targets while telling investors to buy.
On Oct. 19, Morgan Stanley analyst Stephen Grambling cut his target to $31 from $36 and kept his Overweight rating. With shares around $19.75 today, that’s still 57% upside.
Predictions spooked the market
The trouble started with prediction markets. As CEO and co-founder Jason Robins put it on the Aug. 7 earnings call, “everyone was worried about Predictions cannibalization.”
The second quarter didn’t help. Revenue fell 5% to $1.44 billion, and adjusted EBITDA dropped to $115 million from $301 million a year earlier, which the company put down to sports outcomes that went bettors’ way and heavier promotions to sign up new Sportsbook and Predictions customers.
And it’s spending more. Robins said DraftKings plans to invest an extra $200 million to $300 million in Predictions this year.
Lower target, same rating
Morgan Stanley lowered its estimates along with its target, and it has company: Citi, Susquehanna and Guggenheim all cut their targets this month and kept Buy ratings (TIKR looked at Guggenheim’s call on Oct. 8).
Does $31 add up?
Analysts’ average target has fallen from $51 a year ago to $34 today…
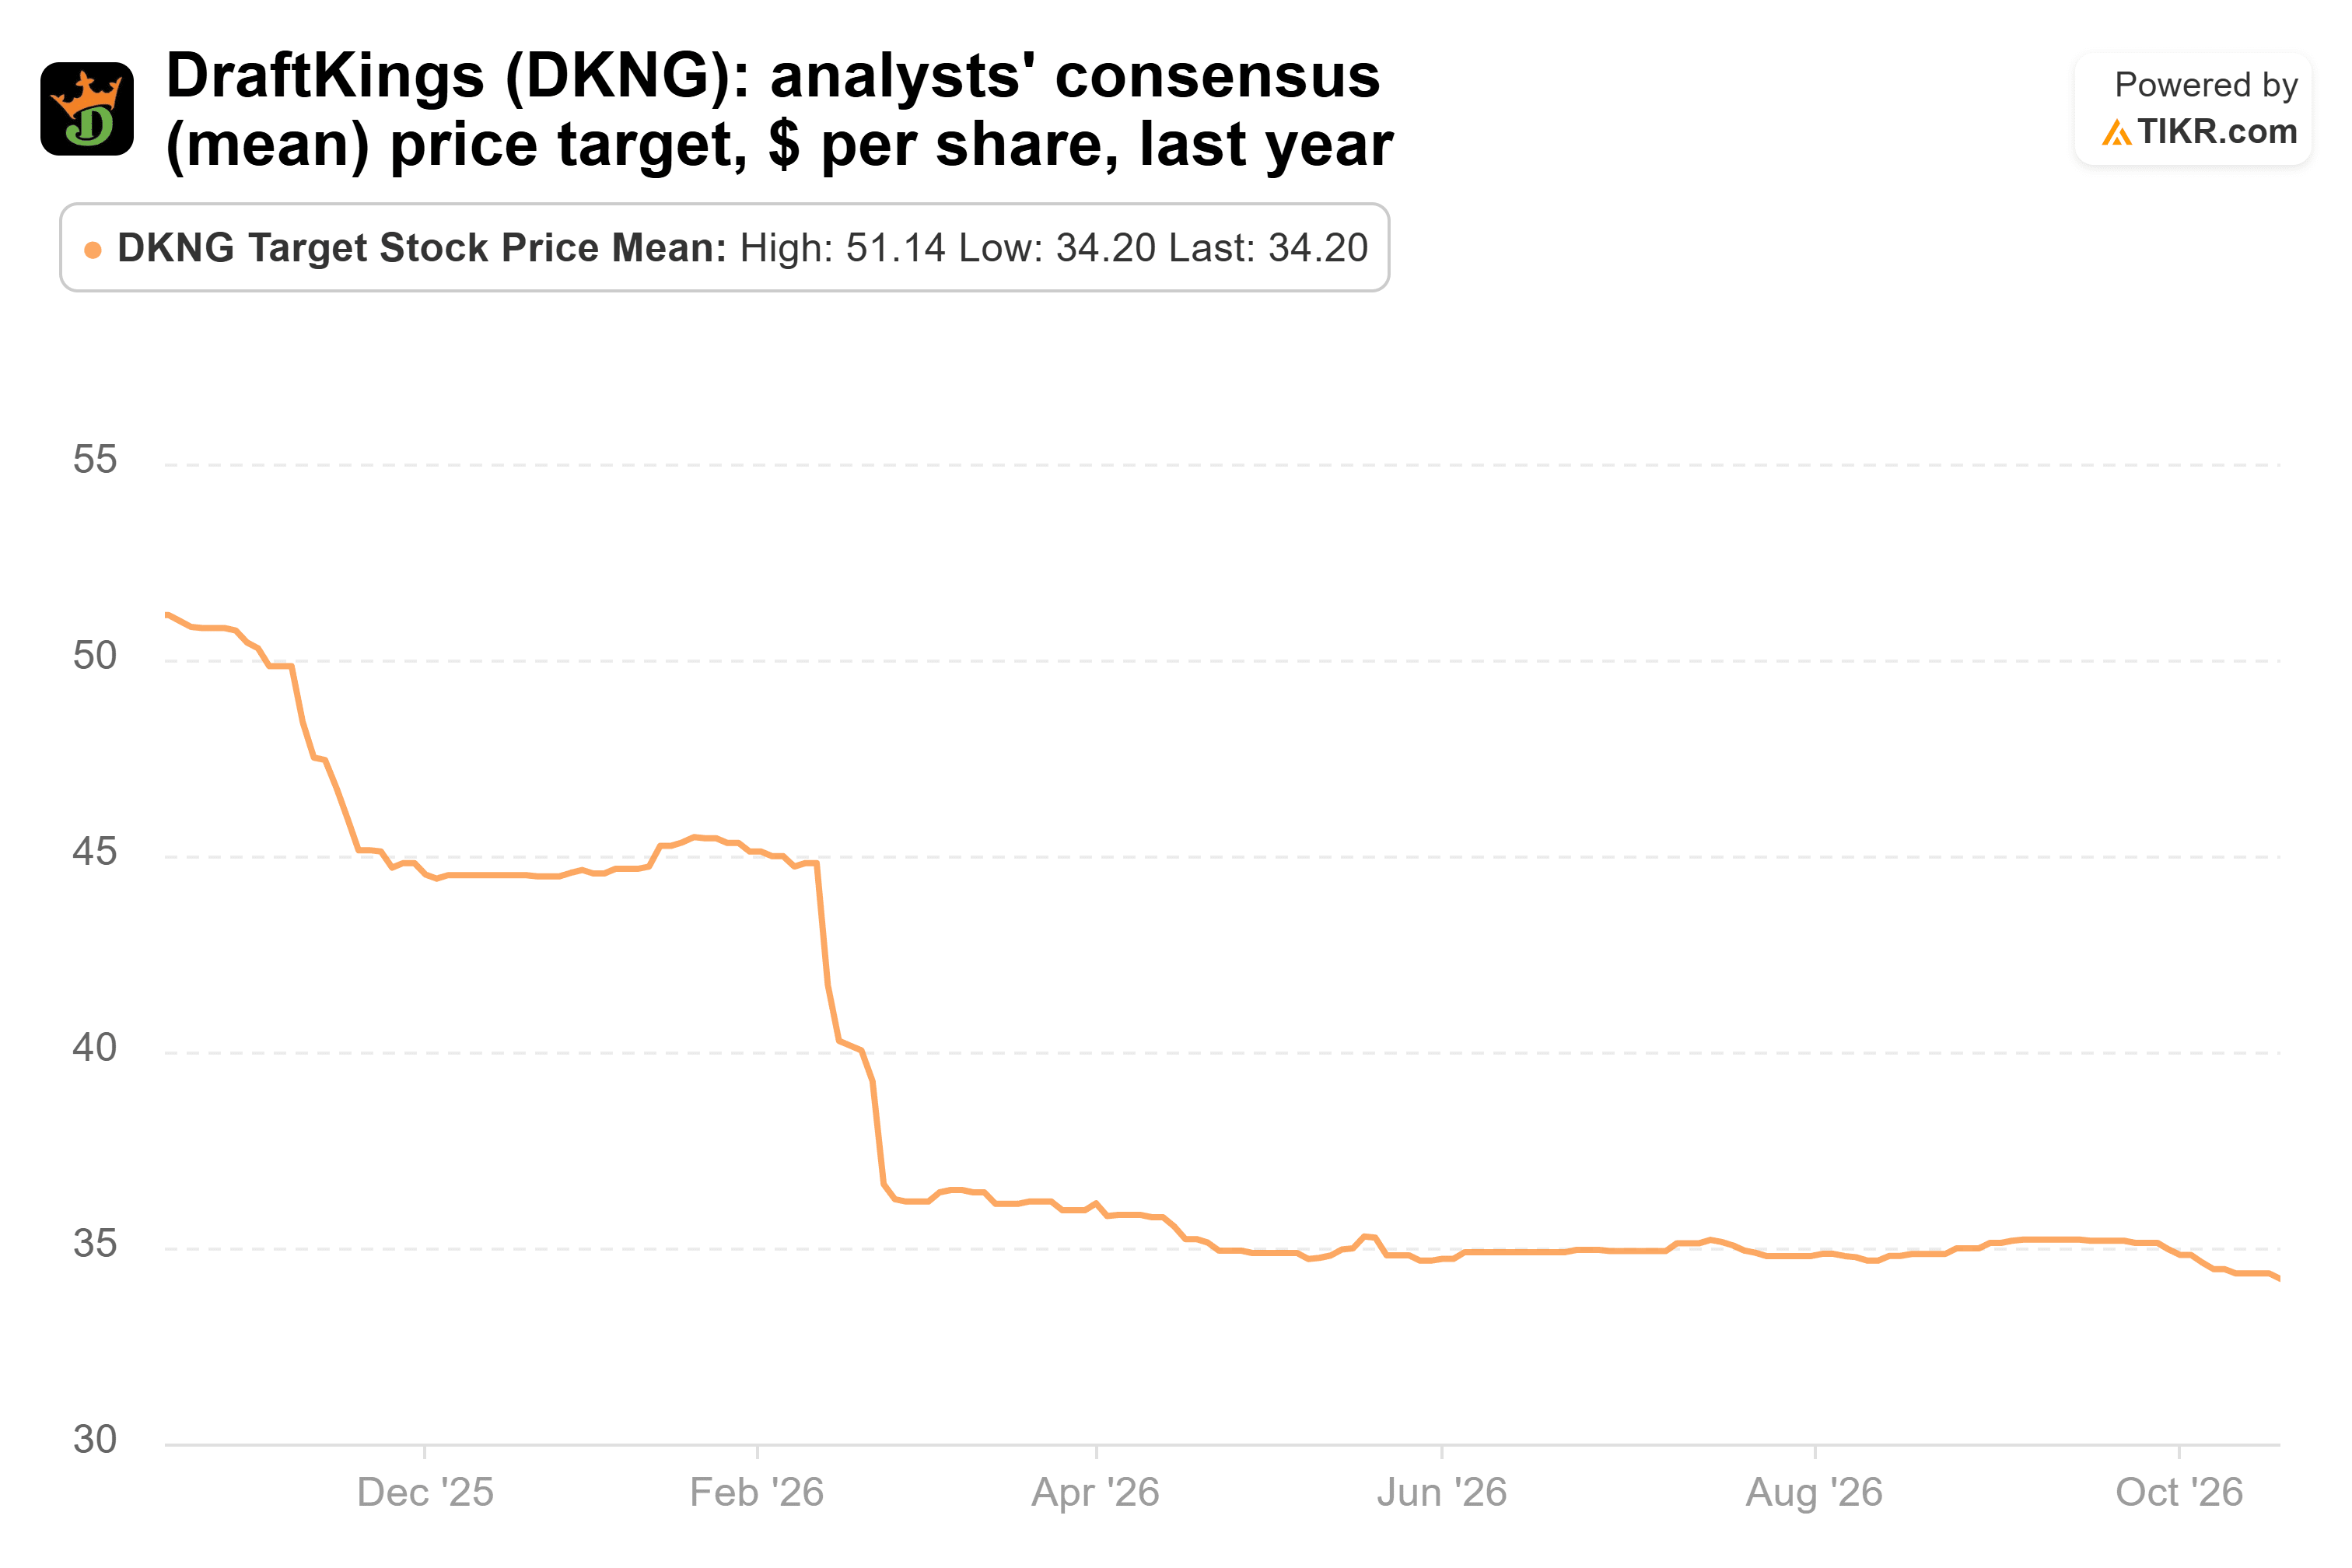
Morgan Stanley’s $31 sits below that consensus, in a range that runs from $20 to $76. Yet 31 of the 37 analysts still rate the stock Buy or Outperform.
The cuts are to this year’s earnings. The consensus for 2026 has slipped to $0.88 a share from $1.03 three months ago, but the $1.70 analysts expect for 2027 is right where it was then…

So analysts read 2026 as a year of spending, and still expect earnings to nearly double in 2027.
At the Oct. 16 close, though, DraftKings traded at about 17x forward earnings. Morgan Stanley’s $31 works out to 28.5x the $1.09 a share analysts expect over the next twelve months.
Plausible, if 2027 shows up
The risk is the one that started the slide: if prediction markets take more share, or the Predictions bill runs past the top of its plan, 2027 slips too.
I think Morgan Stanley’s call is plausible but stretched, and the third-quarter report is the next test. If DraftKings holds its $700 million to $900 million adjusted EBITDA guidance and keeps the Predictions spend inside its range, $31 starts to look a lot more reasonable.
So what is DraftKings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DraftKings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


