

Key Takeaways
- Datadog shares rose 6% today after Bernstein upgraded the stock to Outperform and raised its price target to $350 from $237.
- Bernstein’s case for faster AI-driven growth looks well-founded, but the stock already prices in a lot of it.
- Analysts expect revenue to grow about 30% this year, then slow to about 23% a year through 2028.
- Third-quarter results on Nov. 4 are the first real test of whether AI-native customers can make up for slower traditional customers.
Datadog (DDOG) shares are up 6% today. Before the open, Bernstein upgraded the stock to Outperform from Market Perform and raised its price target to $350 from $237.
The bounce follows a drop of about 14% last week in a broad tech selloff.
Bernstein changes its mind
It’s quite the reversal. Bernstein downgraded Datadog last quarter for two reasons. Its largest “Born in AI” customer (widely reported to be OpenAI) cut about $100 million of annual recurring revenue. And demand looked softer among the traditional customers that make up around 85% of revenue. At the time, Bernstein expected growth from AI-native customers to slow to 50%-60% in 2027, from 80%-90% this year.
Now Bernstein analyst Peter Weed says that view was too conservative:
“Our alt data signals suggest enterprise token consumption appears to have grown at least 50% [quarter over quarter] among the largest AI Labs (and perhaps even faster in their smaller ‘Born in AI’ customers).”
He added that consumer AI agents like Muse and Dots could raise the monitoring needs of Datadog’s traditional customers too.
The Street already expects plenty
Wall Street’s estimates already have Datadog growing fast for years…
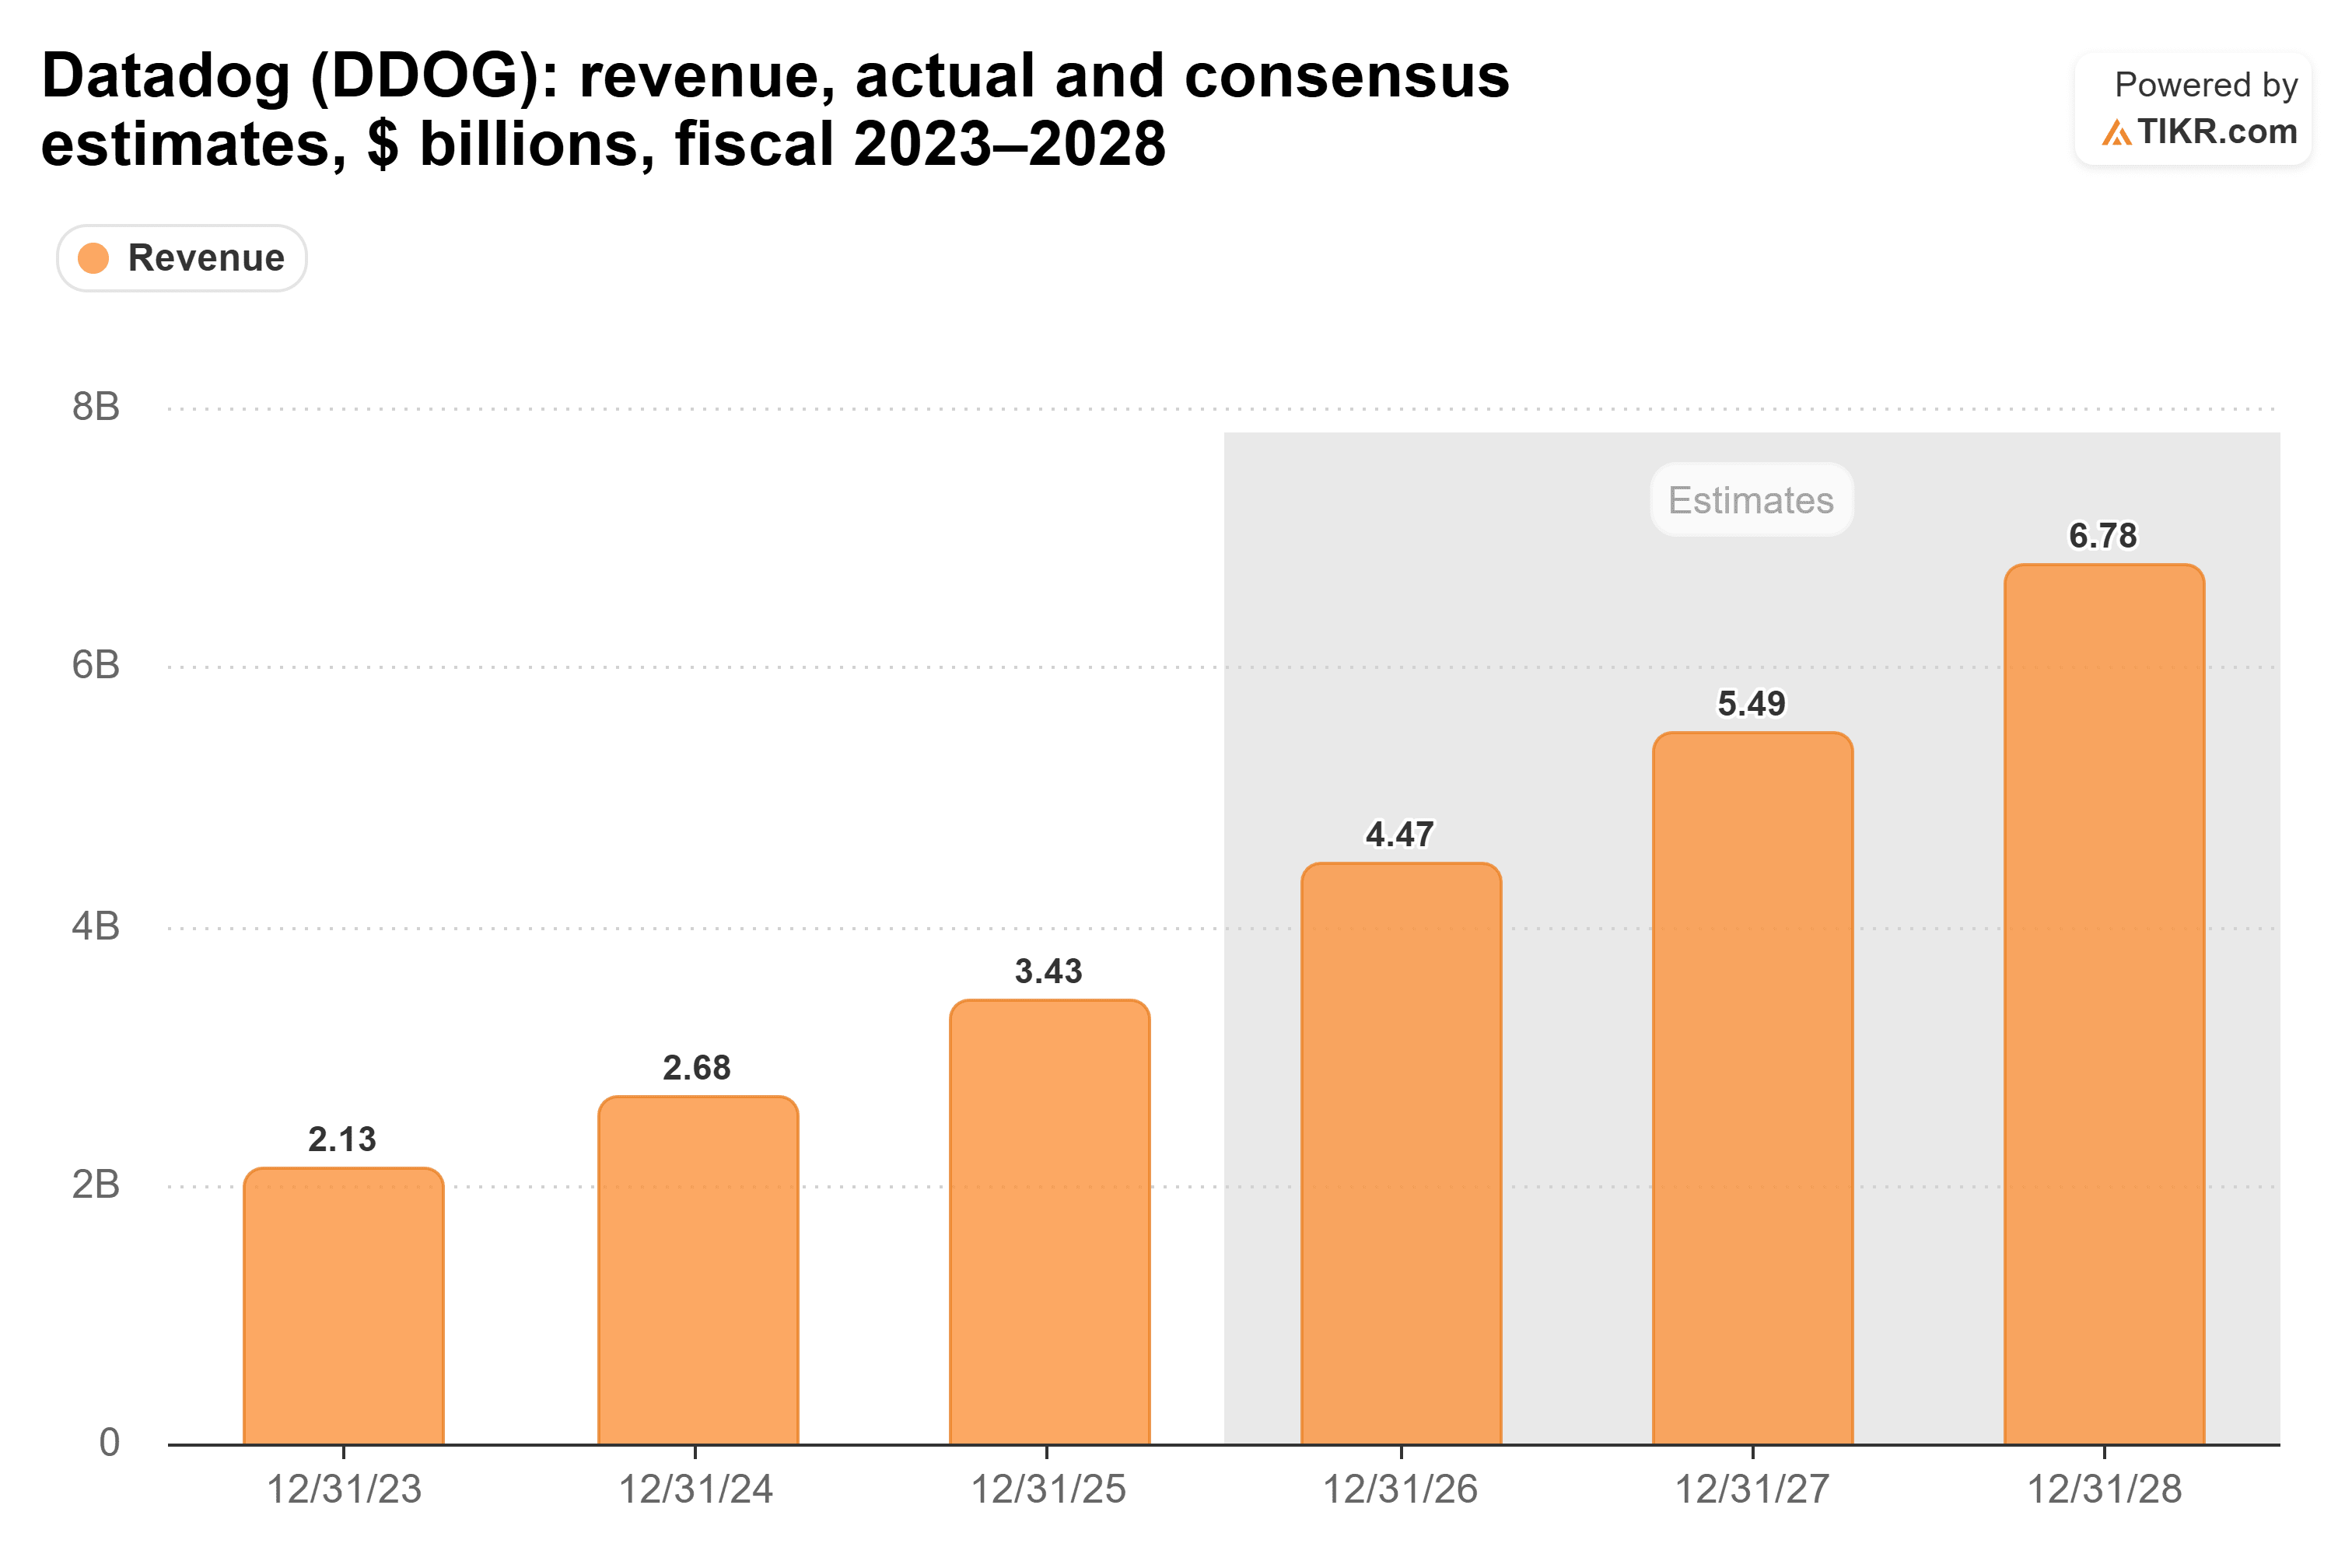
Consensus has revenue climbing about 30% this year to $4.47 billion, then slowing to about 23% a year, reaching $6.78 billion in 2028. Bernstein is betting against that slowdown. If the biggest AI labs keep adding usage at anything like 50% a quarter, those later years look conservative to me.
Of course, more tokens don’t turn straight into Datadog revenue. And Weed himself points out that customers who get big enough have tended to move monitoring in-house.
You’re paying up for it
Shares were up about 82% this year through Friday’s close, and the valuation has followed…

At Friday’s close, Datadog traded at 93.2x forward earnings, and after today’s jump it’s closer to 99x. That’s under its five-year average of 107.6x, which the 2021 bubble pushed up. But it’s about double the 47.4x the stock hit in February.
Nov. 4 is the test
My take: Bernstein’s upgrade looks well-founded. If AI-native customers keep growing like this, Datadog’s revenue should beat what the Street expects for 2027 and 2028.
But at nearly 100x forward earnings, the stock needs proof. Datadog reports third-quarter results on Nov. 4. That will be the first real look at whether its AI-native customers are making up for any slowdown among its traditional ones.
So what is Datadog stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Datadog could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


