

Key Takeaways
- Micron fell 17.5% on Thursday, Nov. 5, rebounded 5.1% the next day, and traded at 3.9x forward earnings as of Friday.
- A reverse DCF shows the price needs less than 2% yearly free cash flow growth from a record base, making the stock a bet on how long the memory shortage lasts.
- At 6.6x, the low end of Micron’s quarter-end multiples this year, the stock would be about 70% higher on the same estimates.
Micron Technology (MU) dropped 17.5% on Thursday, Nov. 5, and won back 5.1% on Friday. Rival SK hynix (SKHY) says the memory shortage behind Micron’s record year runs through 2030, and one Reddit investor can’t see why Micron isn’t higher.
“It’s selling at roughly 7x TTM Operating Income which is insane to me,” they wrote on r/ValueInvesting, asking why Micron trades so cheaply “with a lot of that revenue committed.”
Their “3x forward PE” is a little low, but not by much: Micron traded at 3.9x forward earnings as of Friday, after earning $85.0 billion in fiscal 2026. Hard to argue with “insane.”
Micron’s Earnings Keep Climbing
Analysts see normalized EPS more than doubling from fiscal 2026’s $75.52 in the year to August 2027, then rising again in fiscal 2028:
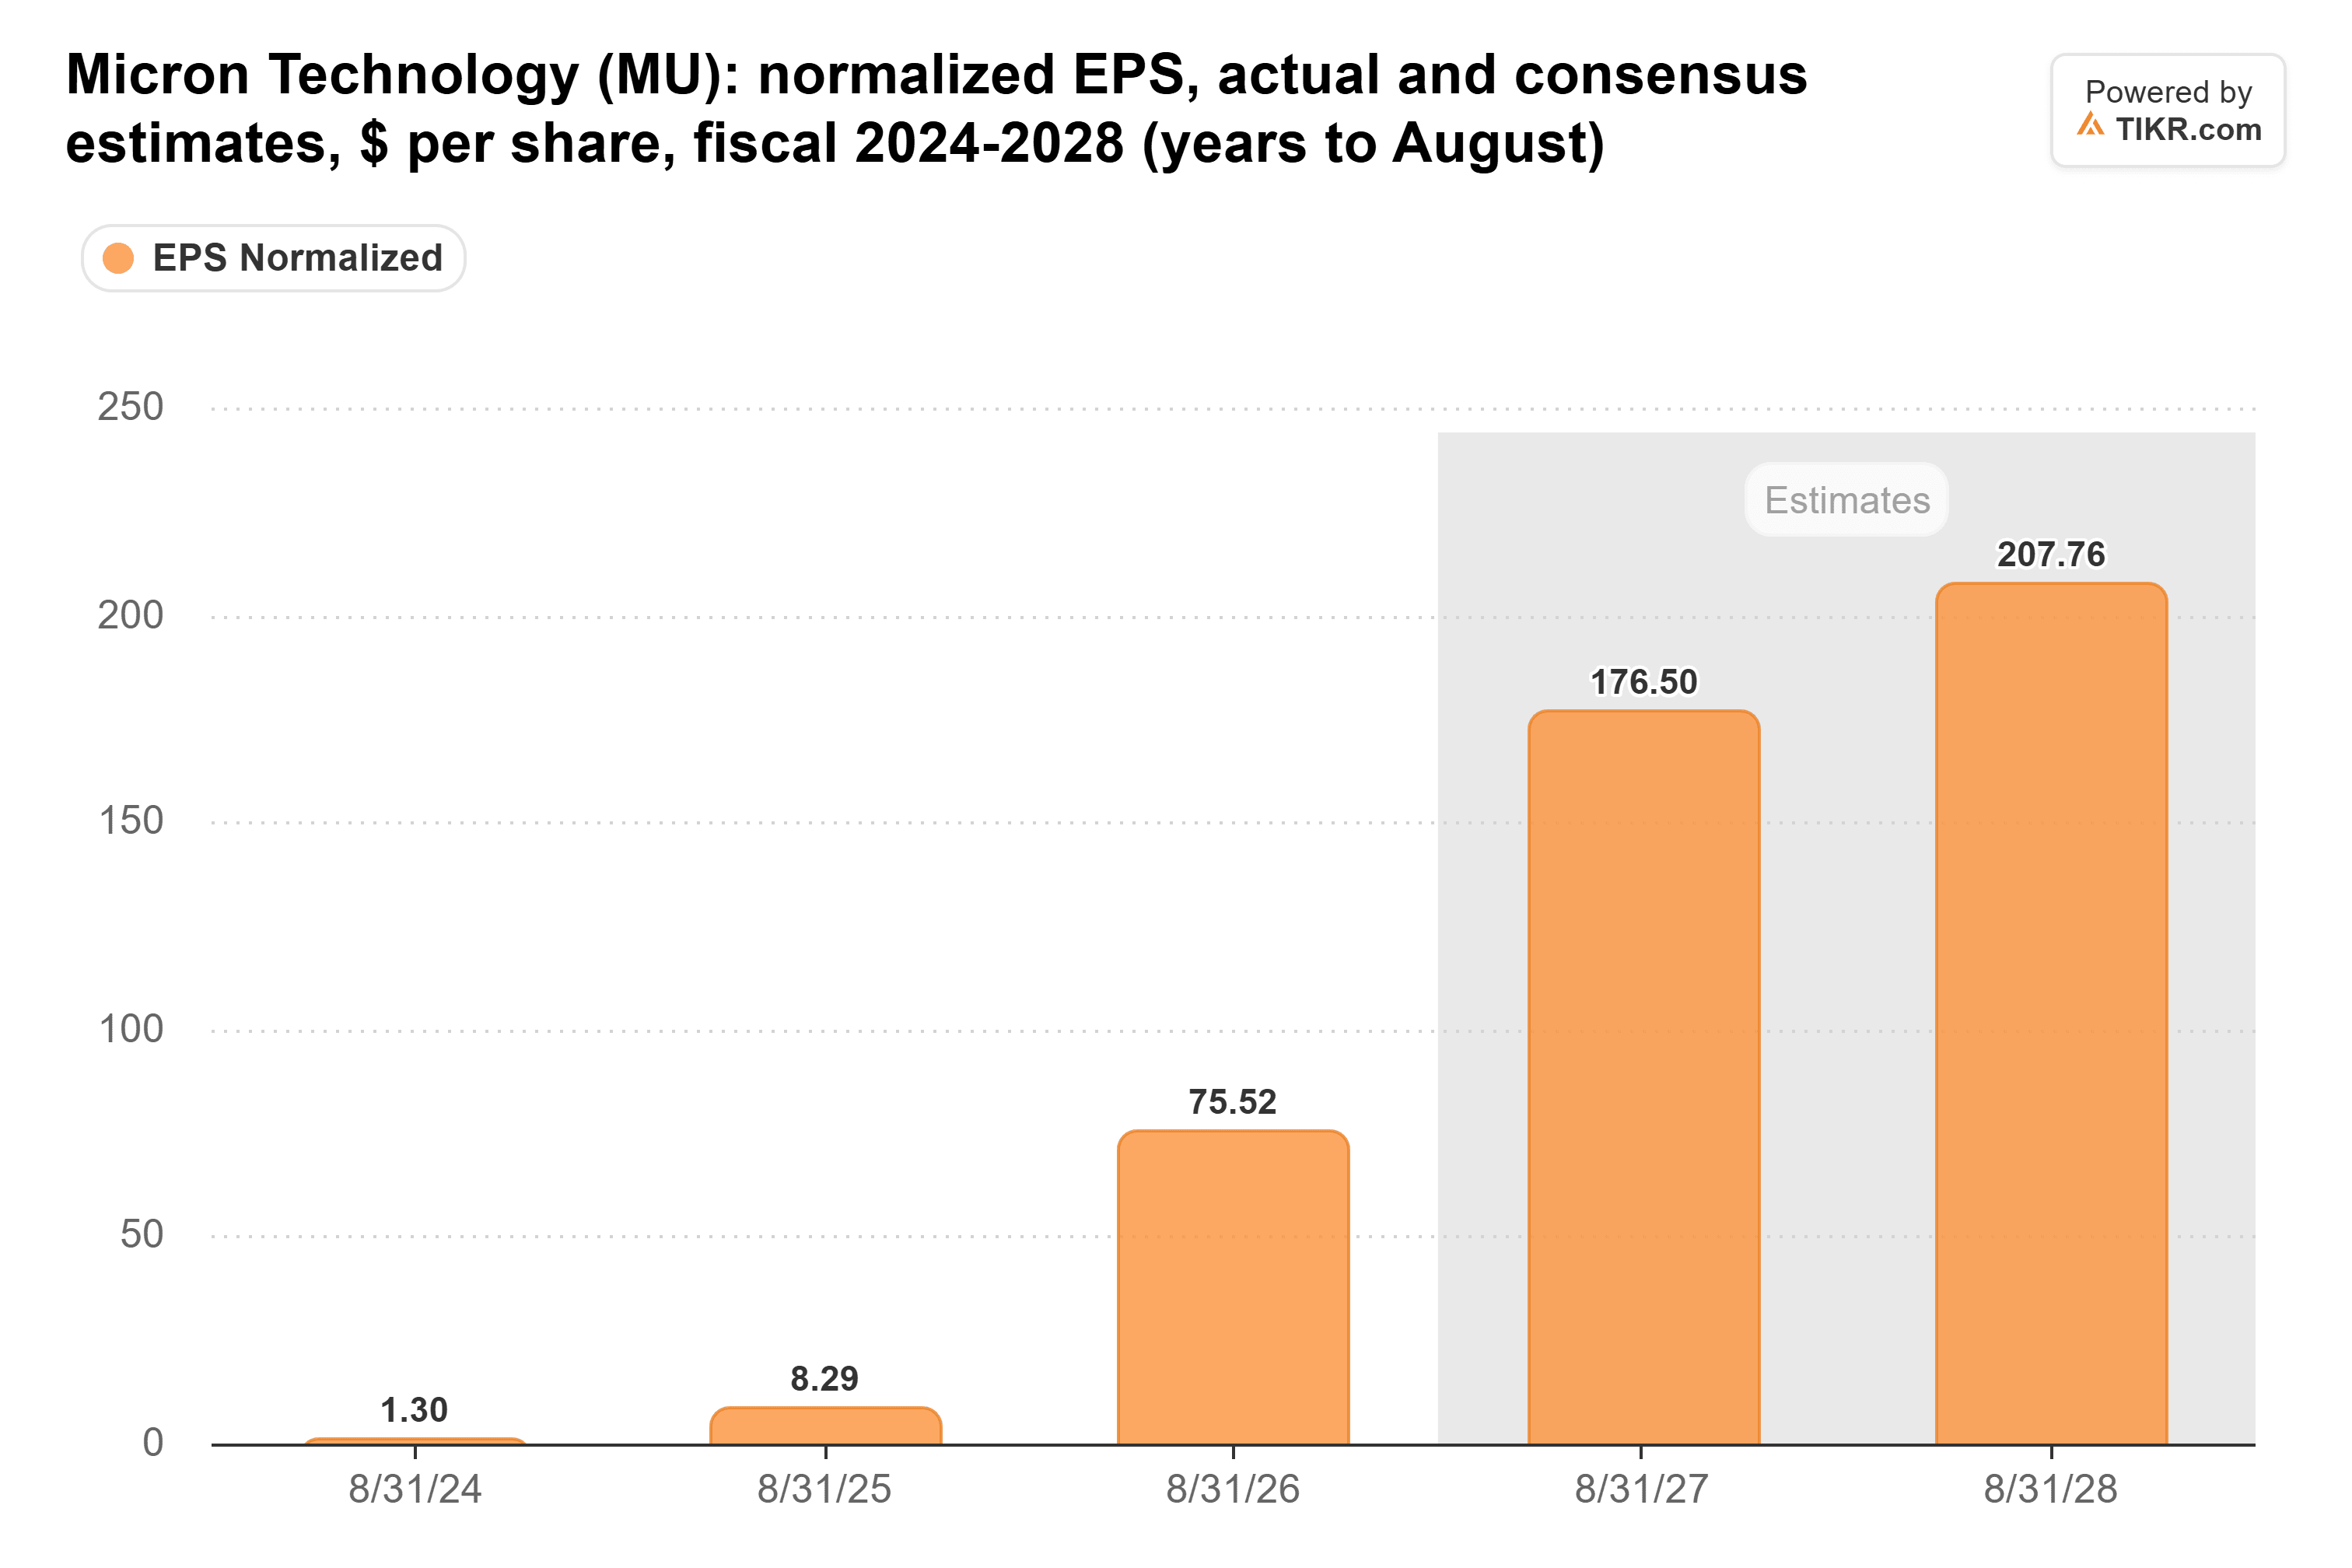
Revenue jumped to $133.2 billion in fiscal 2026 from $37.4 billion, and higher prices did nearly all the work. The estimates already assume fading: consensus gross margin slides from 87.0% in fiscal 2027 to 65.5% by fiscal 2030.
Investors Are Pricing In Almost No Growth
An r/stocks poster flipped the usual question with a reverse DCF: how fast does free cash flow have to grow to justify the price? Running it on trailing free cash flow, Thursday’s close and a 9% discount rate, Micron needs less than 2% a year for a decade, then nothing after.
That starts from a huge base. Trailing free cash flow is fiscal 2026’s record $59.0 billion, after years of very little:
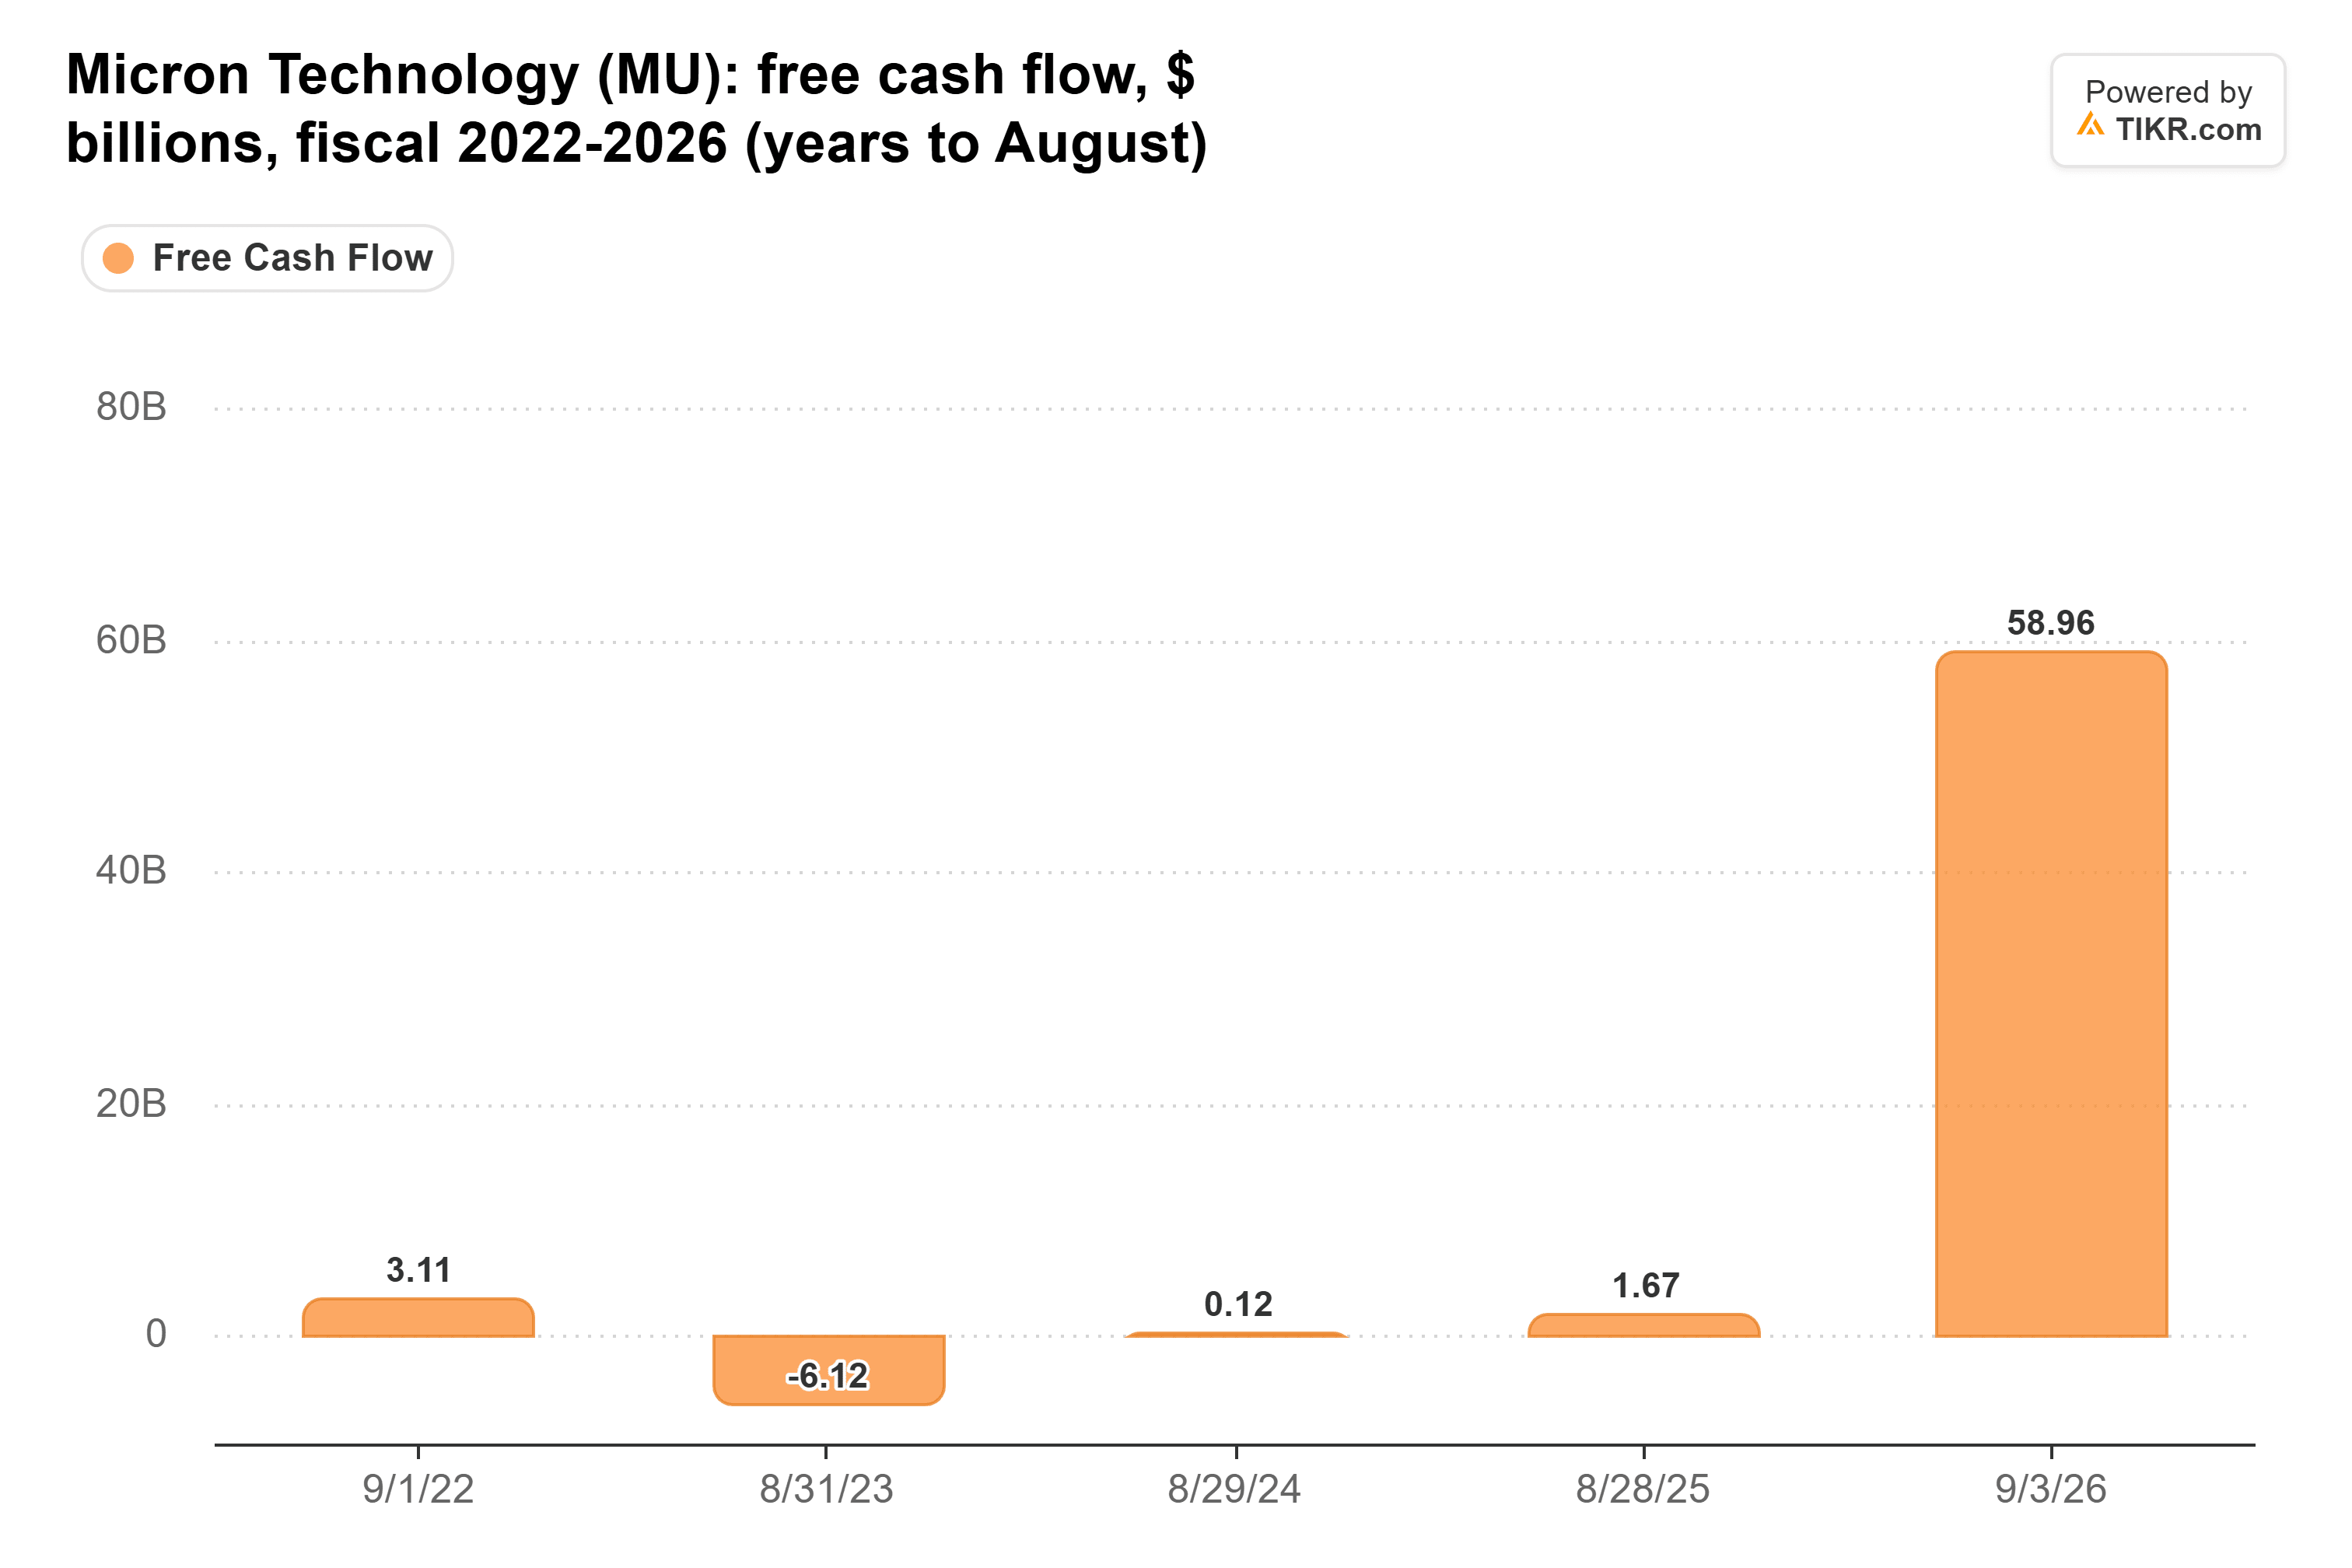
Micron produced $16.7 billion of free cash flow in the nine years before that combined, so the market is treating 2026 as a peak. The last time Micron was this cheap on forward earnings, in 2017 and 2018, its quarter-end multiple ran 3.7x to 5.3x just as that cycle peaked.
Most of 2027 Is Already Spoken For
A veteran investor argued last week that customers have walked away from long-term agreements whenever prices fell more than 60% from the peak. But prices would have to collapse first, and over 75% of Micron’s 2027 output is committed, with its new capacity arriving only from mid-2027. SK hynix has more than half of its 2027-2028 capacity under long-term deals.
TIKR Tracks 49 Analysts on Micron. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Analysts expect $142.9 billion of free cash flow in fiscal 2027 and $175.6 billion in fiscal 2028. That’s $318.5 billion, more than five years of the fiscal 2026 cash flow today’s price rests on. Micron traded between 6.6x and 10x forward earnings at quarter-ends earlier this year. At 6.6x on the same estimates, the stock would be about 70% higher, and still below its 9.9x median since 2014.
Conclusion
The risk is that data centers stop going up. Thursday’s drop came as the Democrats’ midterm sweep stoked fears of limits on new data centers, and UBS says construction pauses could threaten about 30% of the US capacity additions expected in 2028, Micron’s peak EPS year.
Still, at 3.9x, Micron is priced as if the shortage ends almost immediately, while its order book and SK hynix’s point to two more very strong years. The first test comes in mid-to-late December: management guided its fiscal first quarter to about 86.25% non-GAAP gross margin and calls it the floor for fiscal 2027. A miss driven by weaker pricing, not startup or pay costs, would be the clearest sign the shortage is ending early.
So What Is Micron Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


