Key Takeaways
- Snap-on raised its quarterly dividend 12.7% to $2.75 a share, which is smaller than each of its four previous raises of 14% to 15%.
- Snap-on’s Tools Group had a weak third quarter as franchisees cut inventory, but O’Reilly Automotive’s growing professional business shows repair shops stayed busy, and Stanley Black & Decker’s tool sales grew too.
- Free cash flow covered the dividend more than twice over in the last four quarters, but normalized EPS was flat from fiscal 2023 to fiscal 2025.
- The dividend looks safe and still growing, but with earnings expected to grow 8% next year, more raises of 14% or more would keep narrowing the coverage.
Snap-on (SNA) raised its quarterly dividend 12.7%, to $2.75 a share from $2.44. The new dividend is payable Dec. 10 to shareholders of record on Nov. 20. This is its 17th consecutive annual increase, and it has paid a quarterly dividend without interruption or reduction since 1939.
That’s still a big raise. But it’s the smallest of Snap-on’s last three, and more importantly…it’s growing faster than earnings. (More on this in a moment.)
The slowdown follows a rough quarter for Snap-on’s van business, even though the shops its franchisees call on stayed busy. O’Reilly Automotive (ORLY) grew its professional business by double digits in the third quarter, and Stanley Black & Decker (SWK) grew its Tools & Outdoor sales 4% organically.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Diesel hit the vans
Snap-on’s third-quarter organic sales fell 2.8%, and the Tools Group took the hit. Its organic sales fell 7.0%, and its operating margin dropped to 18.0% from 21.7%. Chairman and CEO Nick Pinchuk blamed the “unprecedentedly accelerated rise in diesel prices,” which he said “prompted franchisees to reduce inventories despite very stable demand from their technician customers.”
O’Reilly’s quarter backs him up. Its comparable-store sales rose 7.2%, with professional customers leading the way, so repair bays had plenty of work. Stanley’s tool sales grew too, though mostly through U.S. retail and commercial and industrial channels, so they say less about the mechanics Snap-on’s vans call on.
Diluted EPS fell to $4.64 from $5.02, though last year’s figure included a $0.31 benefit from a legal settlement. And the Commercial & Industrial Group had a record quarter, with organic sales up 7.4%.
Unfortunately, earnings haven’t kept up
Snap-on’s last four raises ran 14% to 15% each, while its normalized EPS went from $18.76 in fiscal 2023 to $18.88 in fiscal 2025. Analysts expect normalized EPS to grow from here:
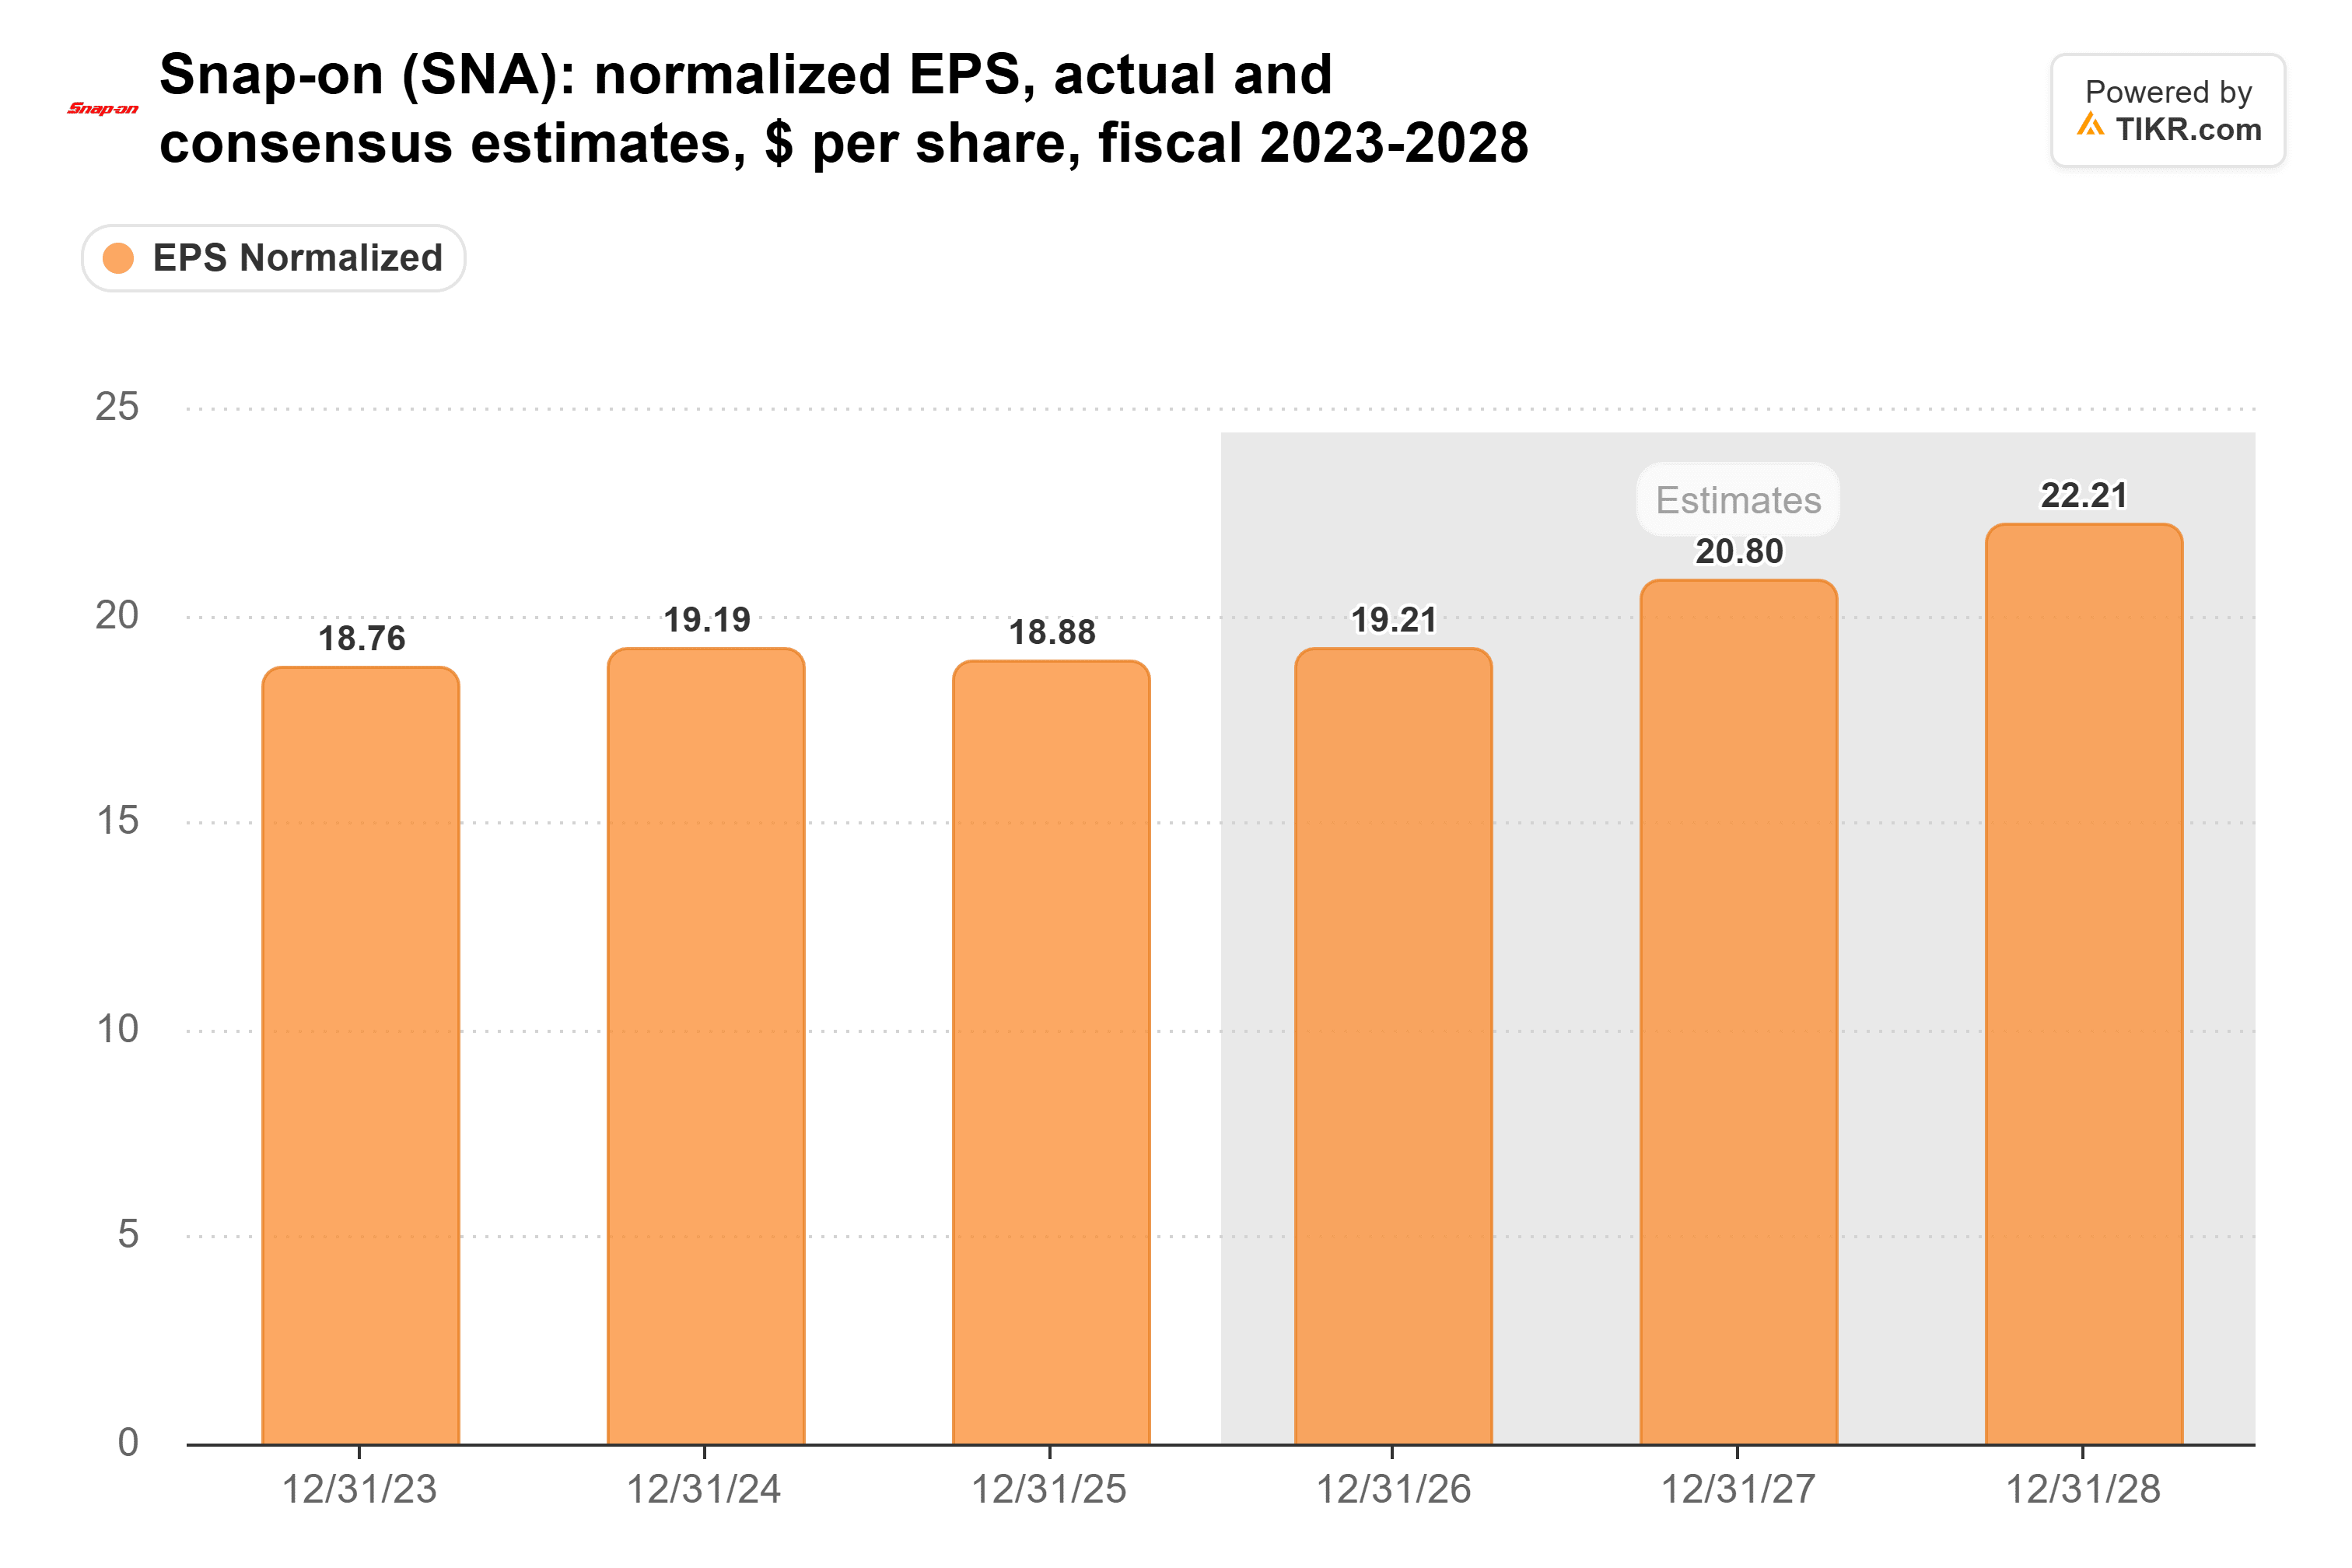
The consensus calls for $19.21 this year and $20.80 in fiscal 2027, which would be 8% growth. The new $11.00 annual rate is 57% of this year’s estimate and 53% of next year’s. Raise the dividend 14% a year on 8% earnings growth and that share climbs fast, so a smaller raise makes sense to me.
Free cash flow covers it twice over
Snap-on pays its dividend from free cash flow, and there’s plenty of it. Over the last four quarters, it generated $1.07 billion of free cash flow and paid $506 million in dividends, a well-covered 47%. Free cash flow has been bigger than the dividend in every one of the last 10 fiscal years:
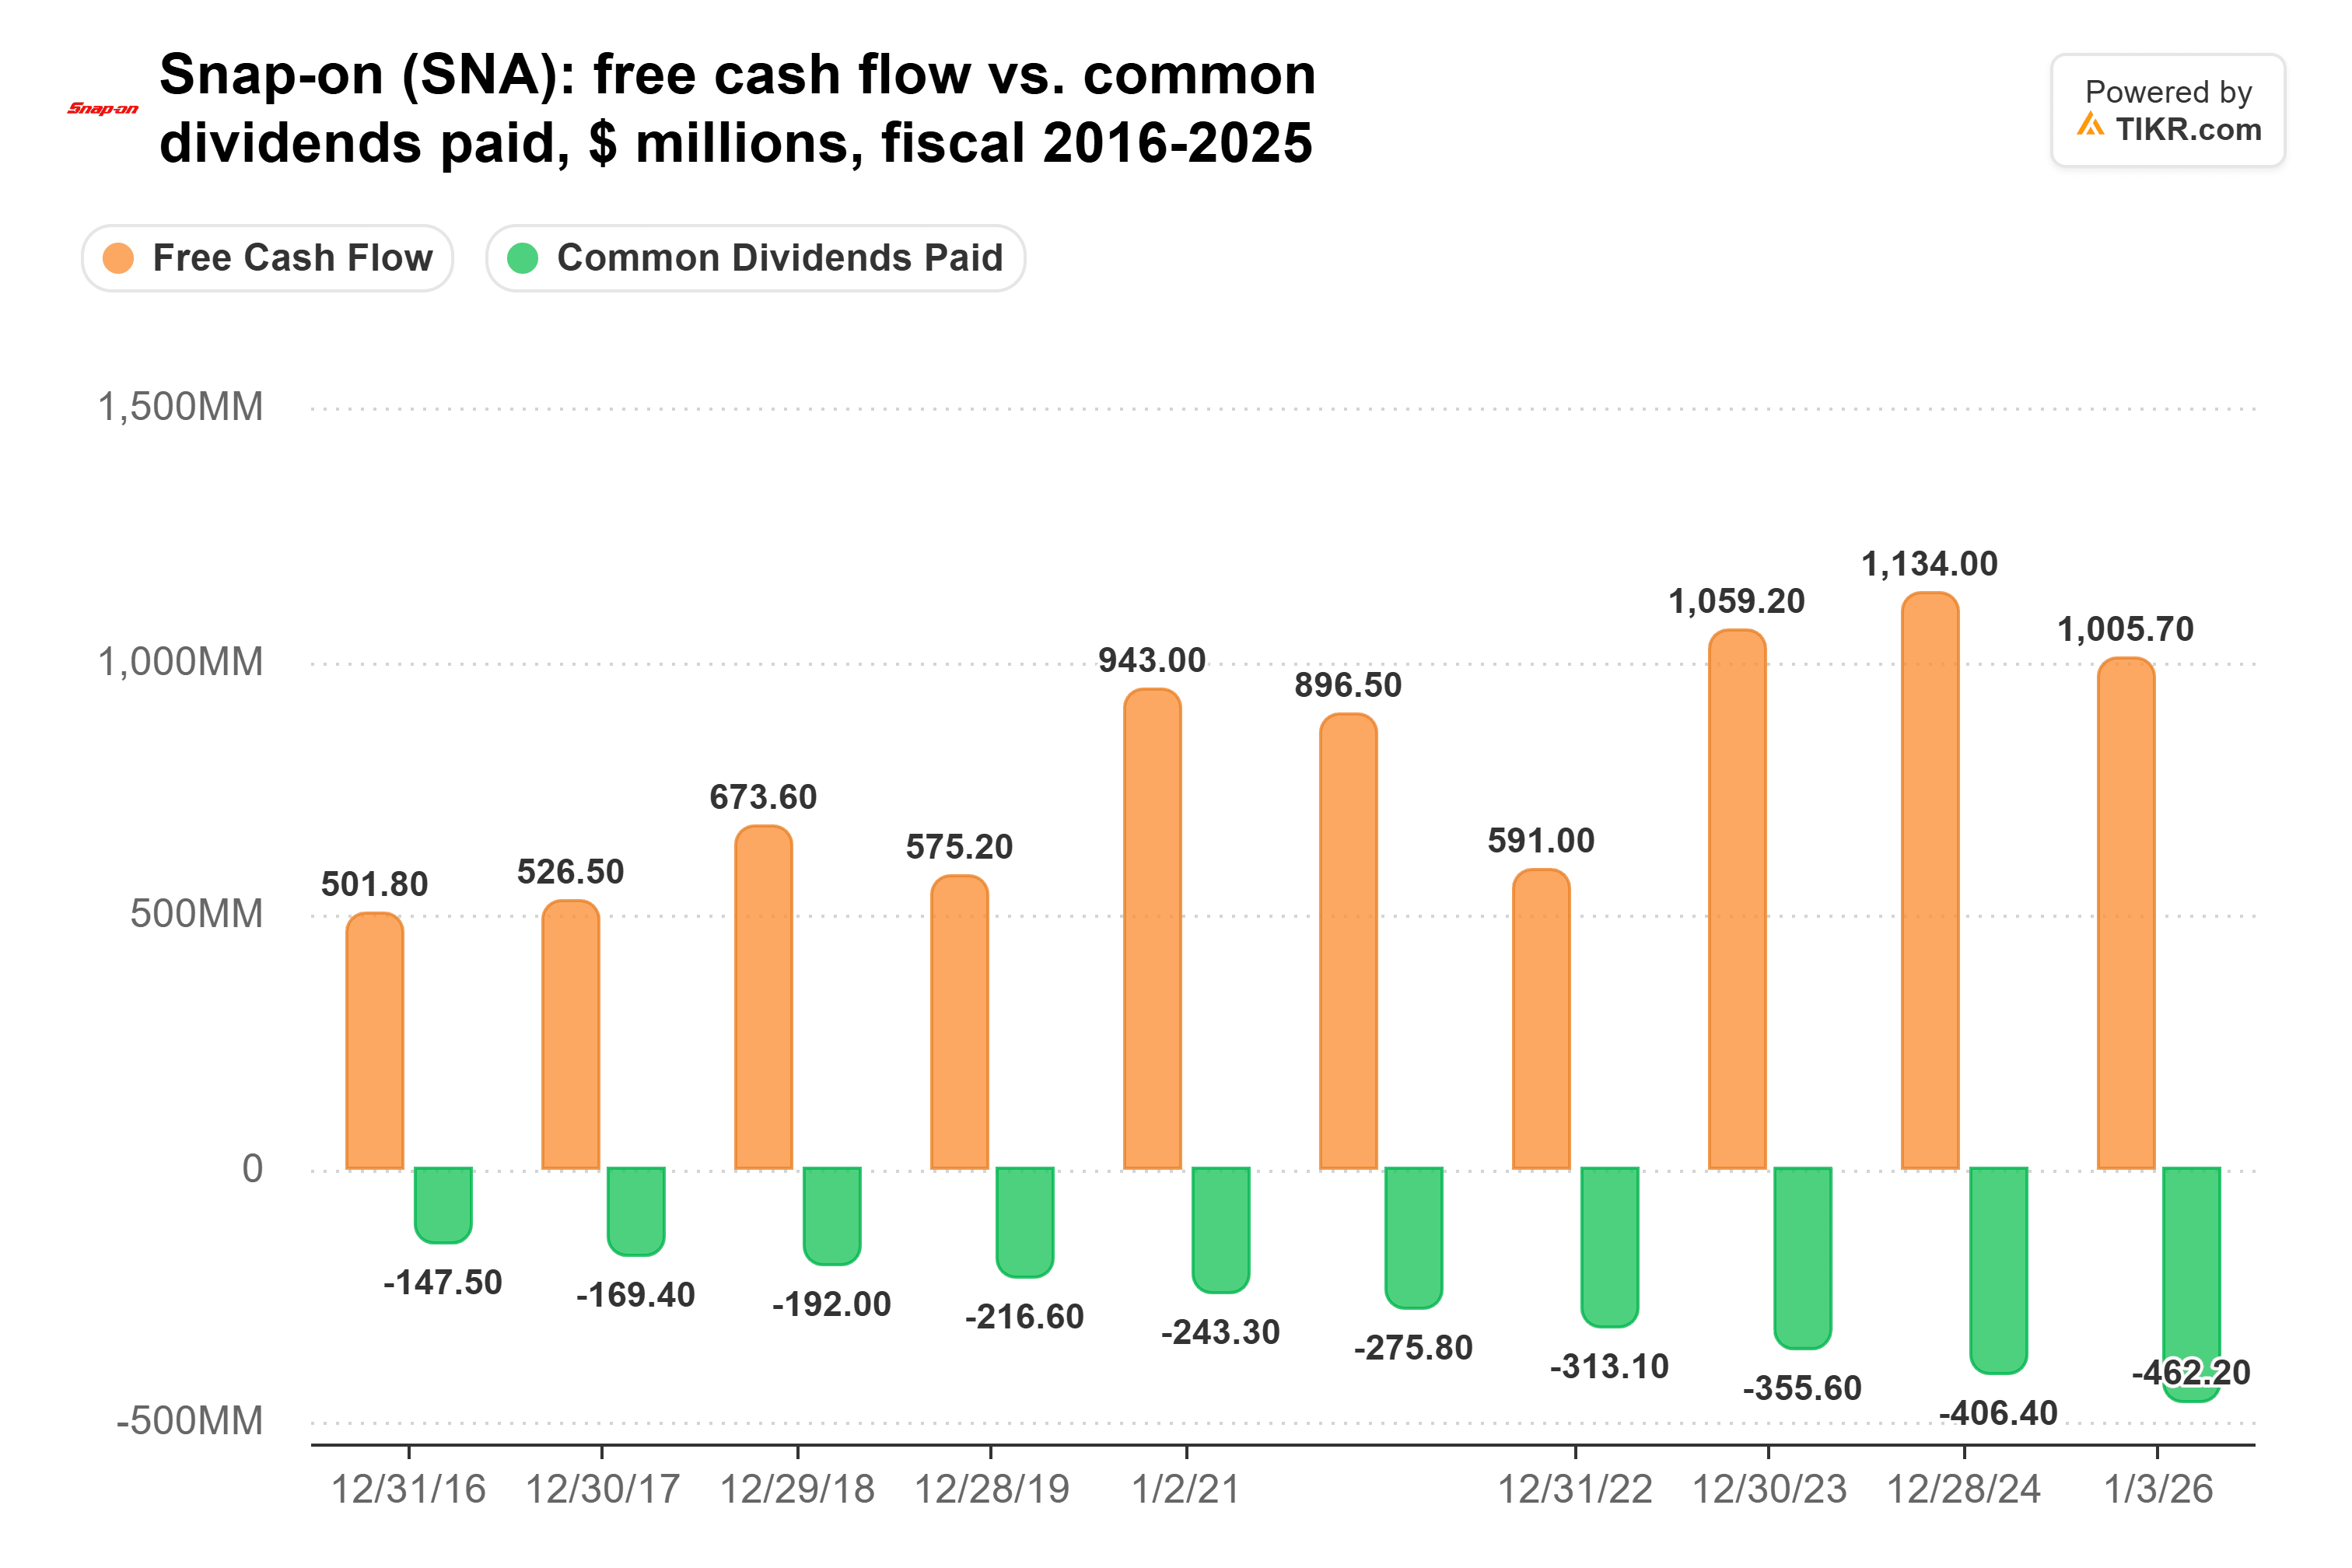
Dividends paid more than tripled from $148 million in fiscal 2016 to $462 million in fiscal 2025, while free cash flow doubled from $502 million to $1.01 billion. That took the dividend’s share of free cash flow from 29% to 46%, which still leaves a wide cushion.
Safe, and still growing
The 3% forward yield doesn’t come from a beaten-down stock. Snap-on’s forward P/E sits well above its five-year average:
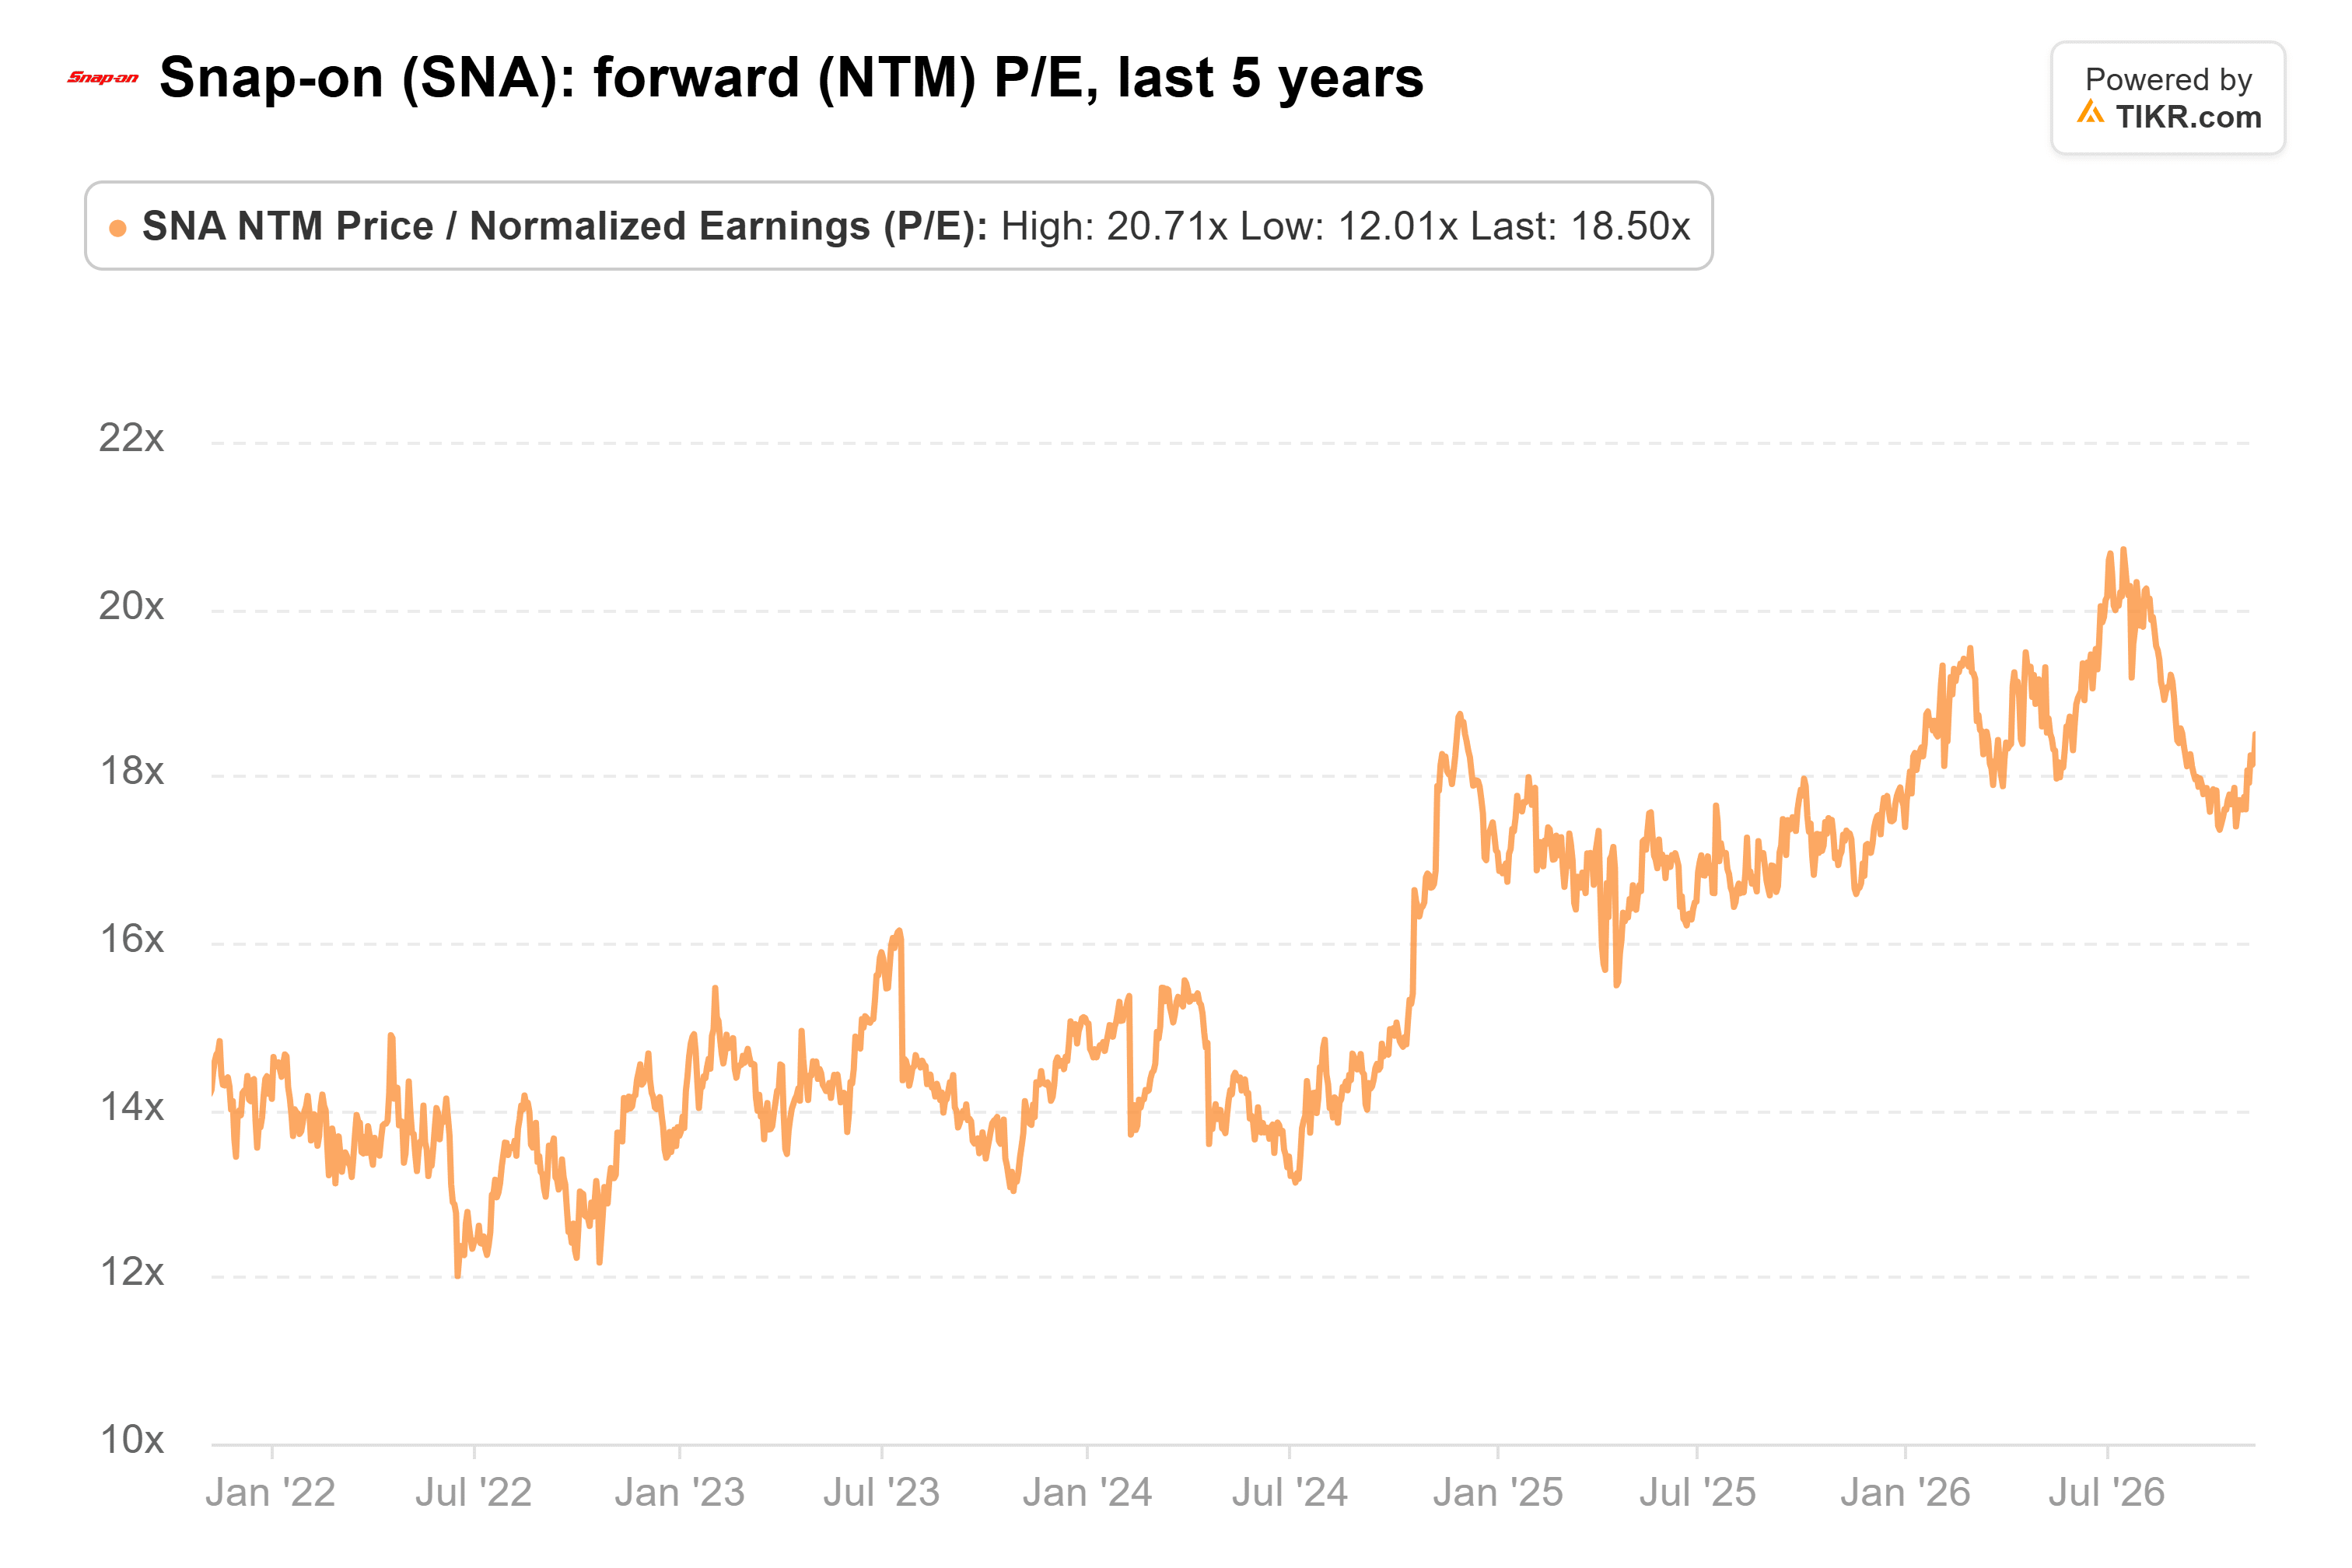
At 19x, it’s below July’s 21x high but well above the 16x average. So the yield got to 3% on Snap-on’s raises, and investors are already paying up for them.
I’d call this dividend safe and still growing. The Tools Group’s slump looks like franchisees running down inventory while technicians keep working. But with analysts expecting 8% earnings growth next year, I wouldn’t count on another 14% raise until earnings speed up.
The Tools Group is the one to watch. Pinchuk expects it “to drive progress as the wave passes.” Snap-on’s fourth-quarter report, due early next year, should show whether franchisees have started restocking.
Forget Snap-on: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Snap-on isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!