Key Takeaways
- Intel stock is up 61% in 2026, but it’s down 58% from its June 30 high after a weak fourth-quarter outlook on Oct. 29.
- Intel isn’t broken: data center and AI revenue rose 78% last quarter, and the company can’t make enough server chips to meet demand.
- That supply gap is helping AMD win server orders, and analysts have cut Intel’s 2027 earnings estimate.
- At 40x forward earnings the stock is still priced for a recovery, so the late-January report needs to show supply and margins coming back.
Intel (INTC) stock is up 61% in 2026. That’s what’s left of a run that nearly quadrupled the stock by its June 30 high. It’s now down 58% from that peak, and 43% in the past month, after a weak fourth-quarter outlook on Oct. 29.
Meanwhile, Advanced Micro Devices (AMD) is there to take the server orders Intel can’t fill.
Jim Cramer didn’t hold back on Mad Money the next night: “it’s a broken company because the company guided for a very weak 2027.”
I think “broken” goes too far. But I’m not ready to buy yet, either.
A real recovery, paid for with new shares
Intel had a big year before the guide. Second-quarter revenue rose 25% to $16.1 billion, data center and AI revenue jumped 59%, and non-GAAP gross margin climbed to 41.8% from 29.7% a year earlier. The third quarter beat Intel’s own guidance, with revenue up 21% to $16.5 billion, data center and AI revenue up 78% to $7.3 billion, and non-GAAP gross margin at 44.1%.
Intel is paying for more capacity partly with new shares. In August, it sold stock at $95 a share and upsized the offering to $20 billion from $15 billion. Its third-quarter release puts the final total at $23 billion.
TIKR tracks 49 analysts on Intel. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intel, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intel’s Analyst Ratings
Then the guide came up short
Intel guided fourth-quarter revenue to $15.0 billion to $16.0 billion, against the roughly $17.1 billion analysts expected. It also guided non-GAAP gross margin down to 38% and non-GAAP EPS to $0.25. CFO David Zinsner said Intel sees “the PC slowdown continuing at least through the first half of next year.”
Supply hurt too. An Oct. 14 explosion shut Intel’s Kiryat Gat fab in Israel for about two weeks, at a cost of about $300 million of revenue. And short supplies of substrates are capping its Xeon server chip shipments. Management also called 2027 an “investment year.”
The stock fell 29% on Oct. 30, and BofA cut it to Neutral.
Intel can’t make enough chips
That’s why “broken” doesn’t fit. CEO Lip-Bu Tan said in the third-quarter release, “Our immediate priority is to unlock additional supply to meet extraordinary demand for our Xeon family.”
AMD is happy to fill in. Its data center revenue rose 97% to $8.5 billion in the third quarter on record server CPU sales, it reported on Nov. 3. Morgan Stanley sees AMD’s server CPU revenue growing 100% in 2027. AMD stock is up 138% in 2026.
Tan is betting Intel can fix this. He bought 150,000 shares on Nov. 2 for about $9.7 million, or roughly $64.73 a share. That’s about two-thirds of August’s $95 offering price.
Still priced for a turnaround
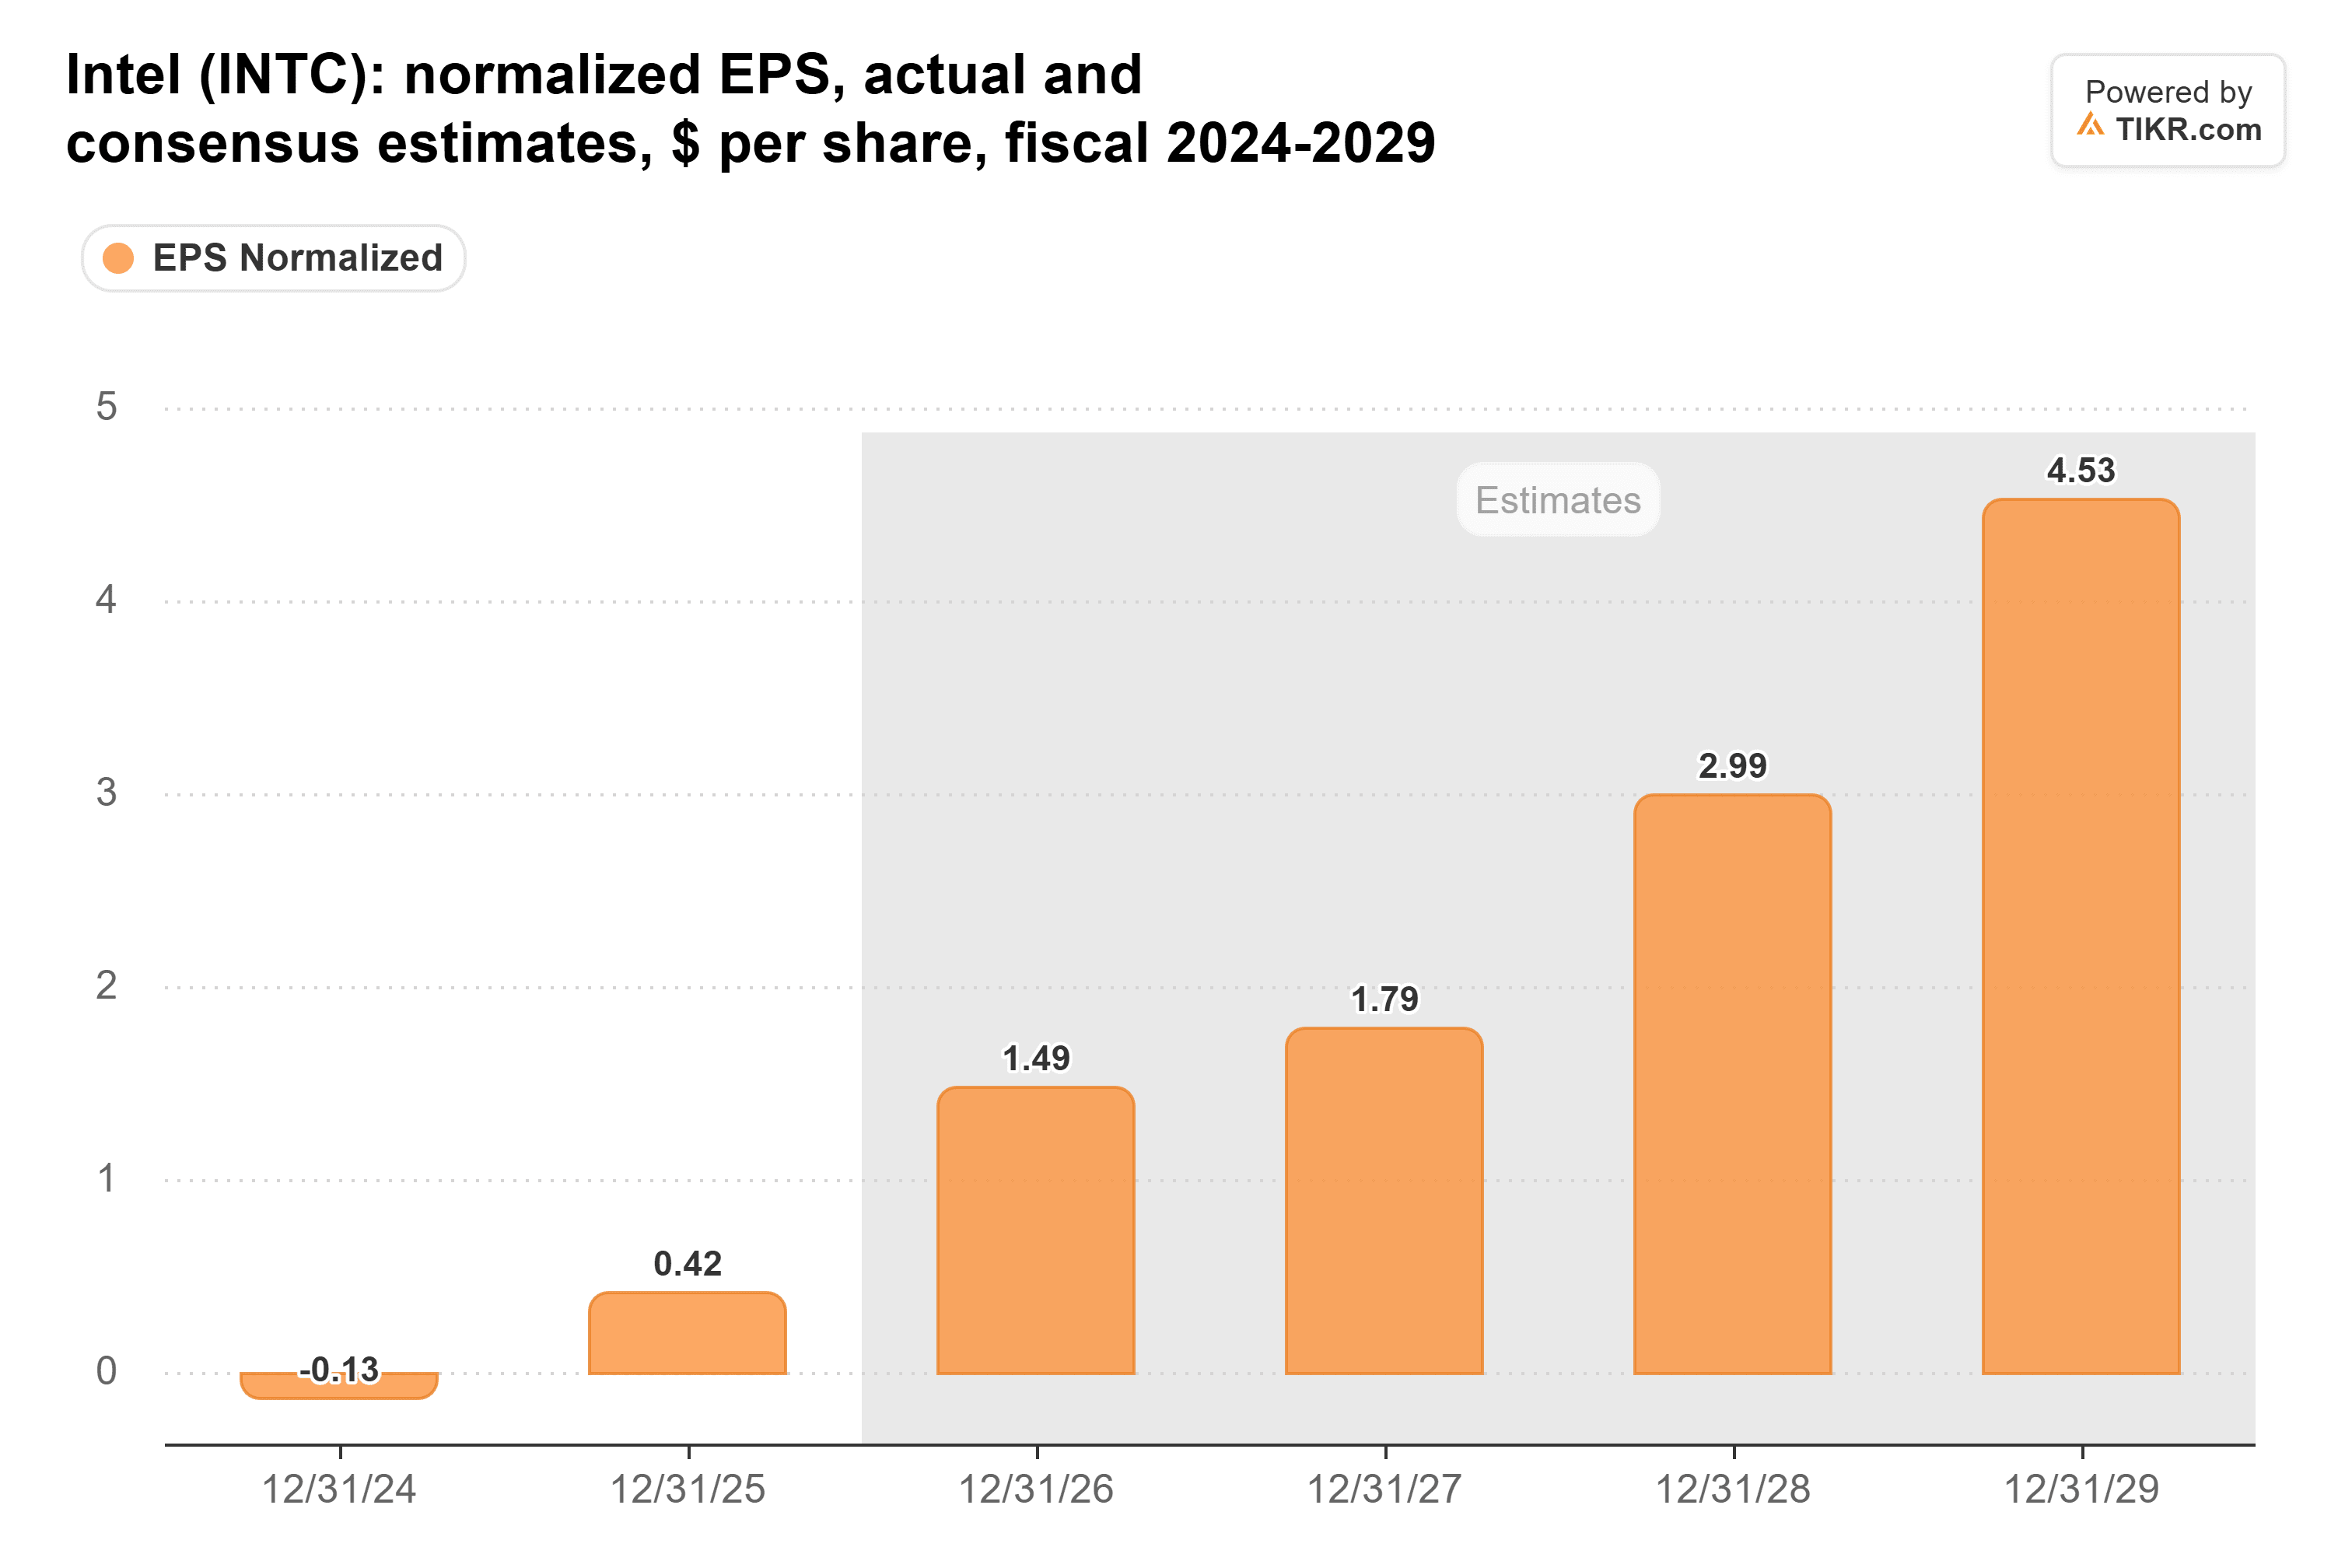
Analysts have cut their 2027 normalized EPS estimate to $1.79, from $2.11 before the report. But they still see Intel earning $2.99 a share in 2028:
Intel traded at 40x forward earnings on Nov. 6, below its five-year average of 50x:
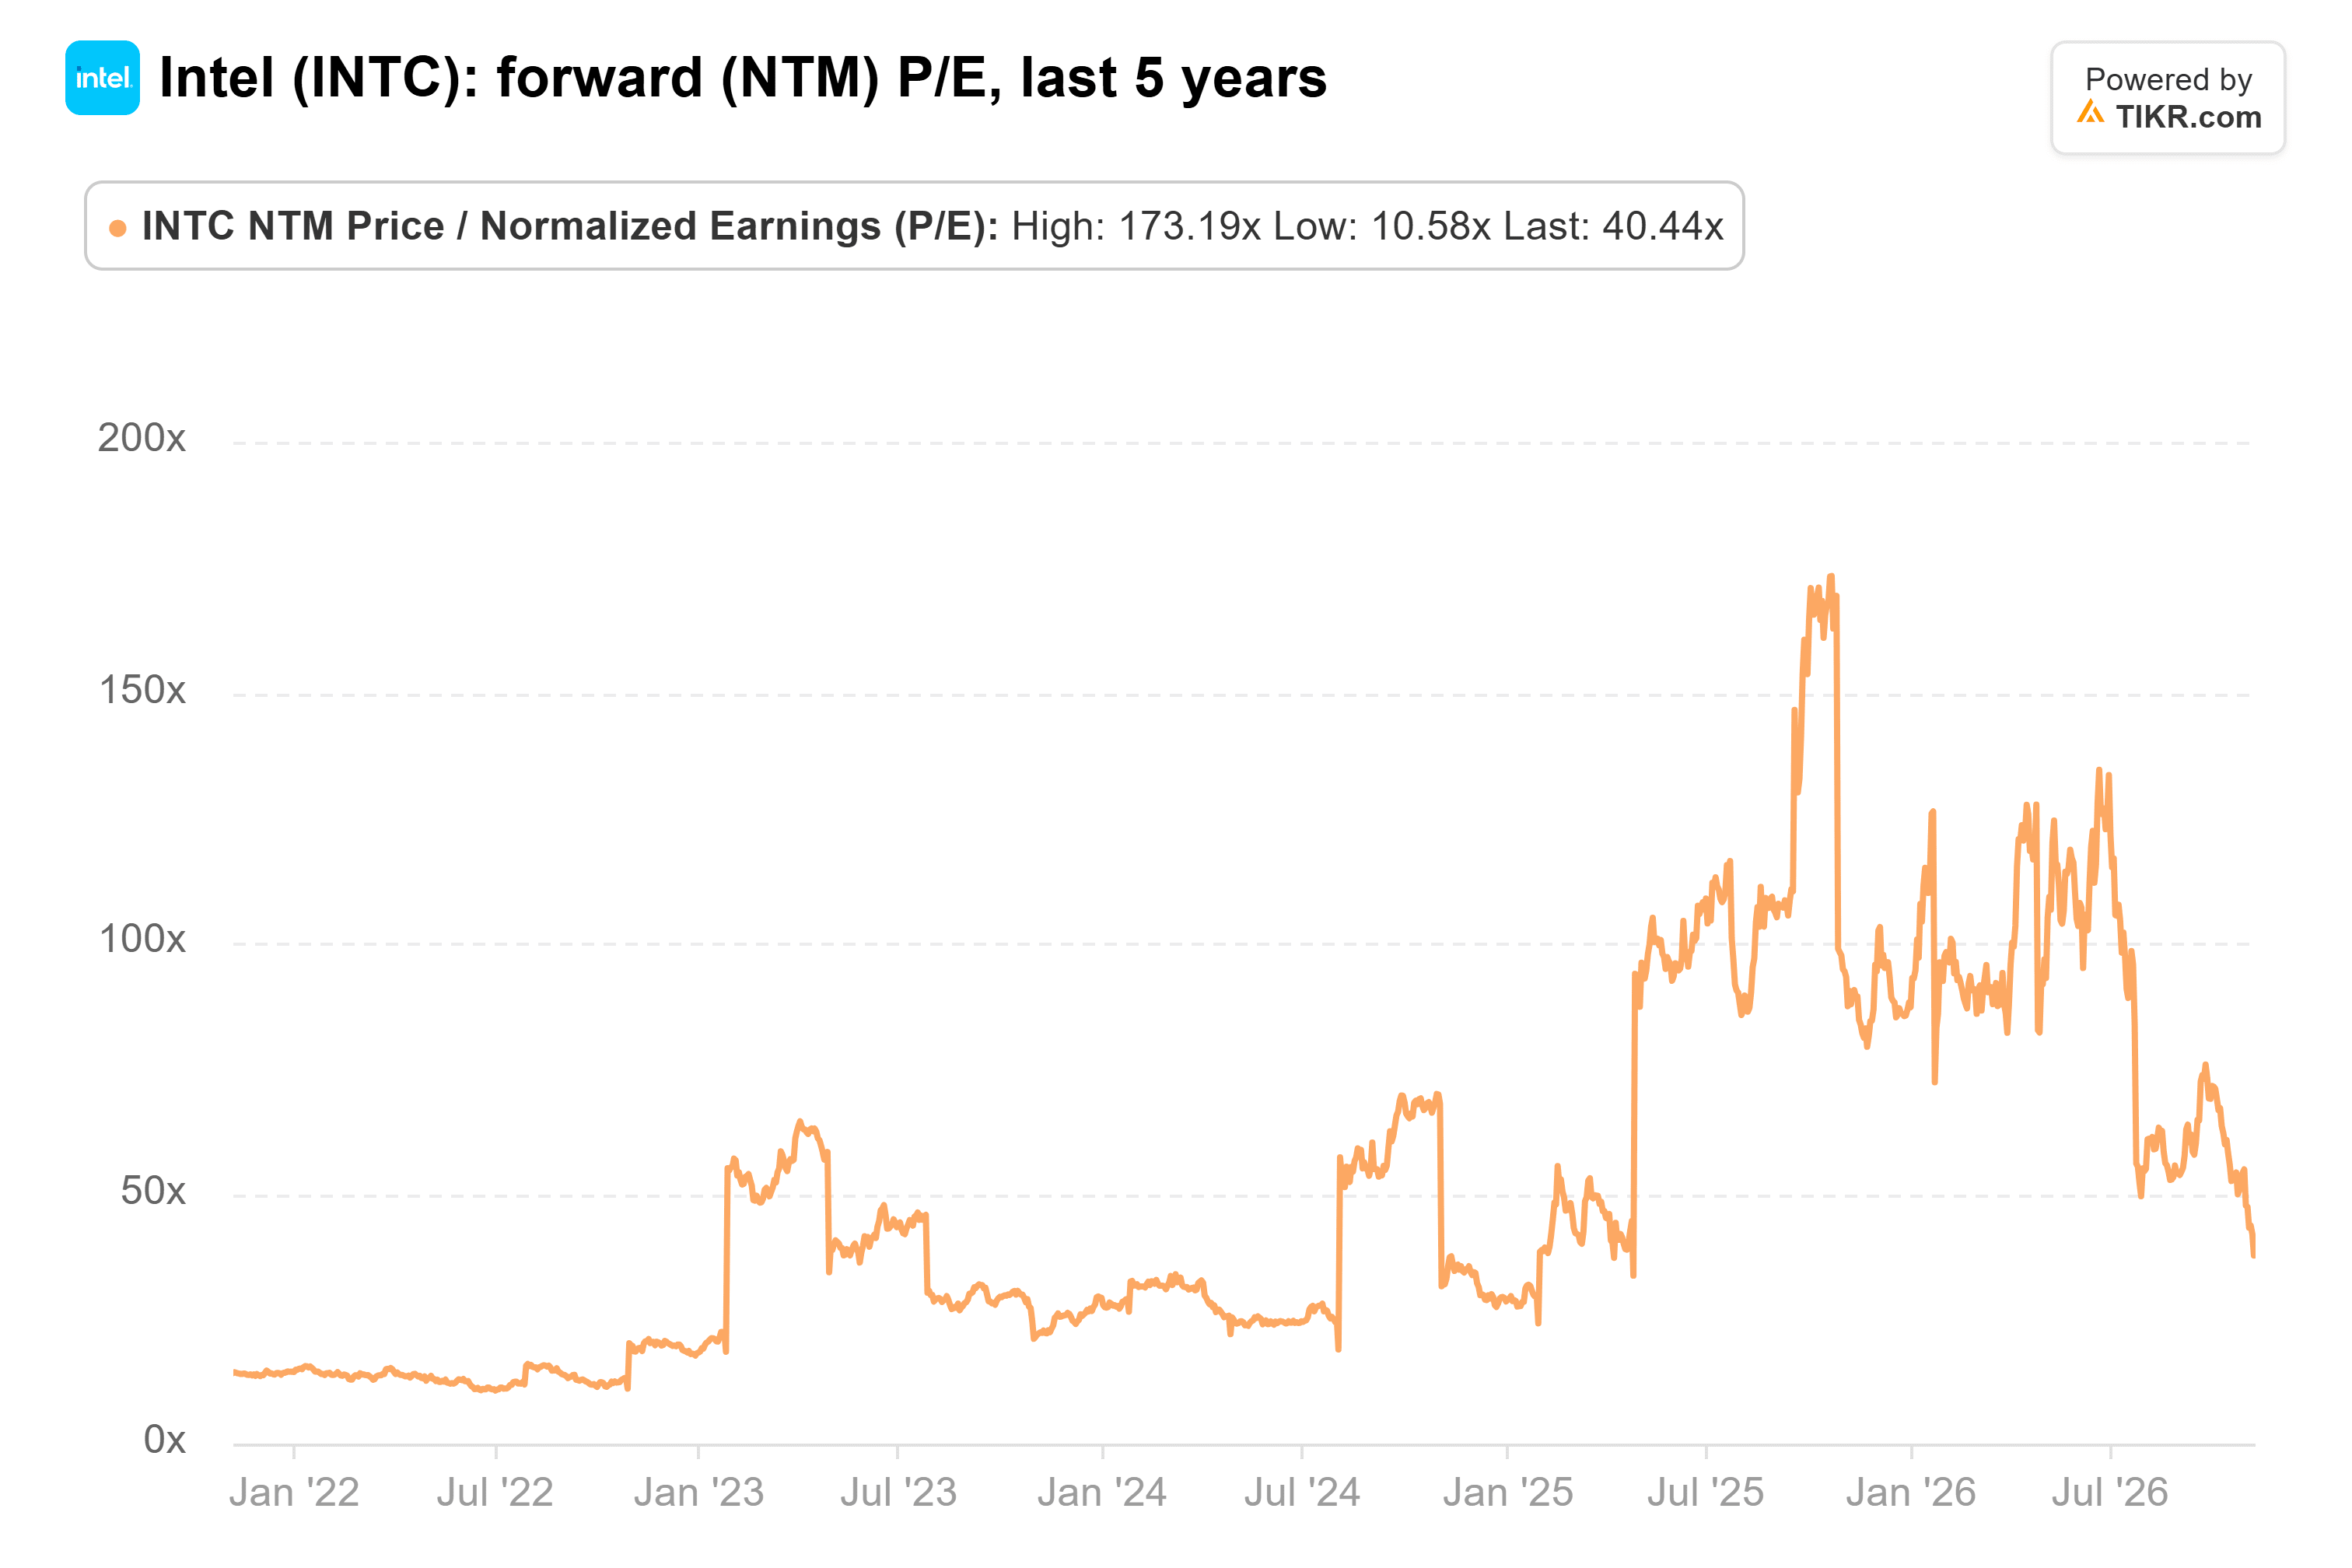
From 2014 to 2022, though, it traded at 10x to 18x. So even after the crash, investors are paying for a turnaround that’s only partway done. KeyBanc, which rates Intel Overweight, cut its target to $140 on Oct. 30, while Barclays rates it Hold with a $75 target.
Bottom line: Intel has a supply problem, and that’s a lot easier to fix than a demand problem. But at 40x forward earnings, I’d wait for proof. The fourth-quarter report, likely in late January, needs to show Xeon shipments picking up and non-GAAP gross margin at 38% or better. Of course, if Intel’s heavy 2027 spending doesn’t bring supply back quickly, analysts could cut their estimates again.
So what is Intel stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intel could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!