Key Takeaways
- President Donald Trump’s brokerage accounts sold between $251,000 and $515,000 of Micron stock in August, his federal financial disclosures show.
- The sale looks like routine portfolio management by his advisers, and it’s a weak signal of where Micron goes from here.
- Micron trades at 3.9x forward earnings, close to where it sat in 2017 and 2018, when the last memory cycle peaked, so investors already expect its record earnings to fall.
- Micron’s fiscal first-quarter report in December, which management calls the fiscal 2027 gross-margin floor, is the next test of that doubt.
President Donald Trump’s brokerage accounts sold between $251,000 and $515,000 of Micron Technology (MU) stock in August, according to his federal financial disclosures. Memory stocks crashed on Thursday and bounced on Friday, so it’s fair to wonder whether his investment team saw trouble coming.
But the market has been asking that question for months. CNBC’s Mike Santoli argued on Friday’s Closing Bell Overtime that investors have long doubted big tech earnings will last, and he pointed to Micron:
“Micron’s under four times forward earnings. If the market believed the earnings, it wouldn’t be under four times.”
So Trump’s advisers have plenty of company.
Don’t read too much into the trade
The sale came on Aug. 21, and presidential disclosures can be filed up to 45 days after a trade, so this one is about two and a half months old. The disclosure gives the sale as a range, and it doesn’t show whether the accounts still hold any Micron. Advisers sell good stocks all the time for reasons that have nothing to do with the business, like rebalancing, diversification and taxes. And after the run Micron’s shares had in the 12 months before the sale, taking some profit would be about as ordinary as it gets.
TIKR tracks 49 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Investors already expect the earnings to fall
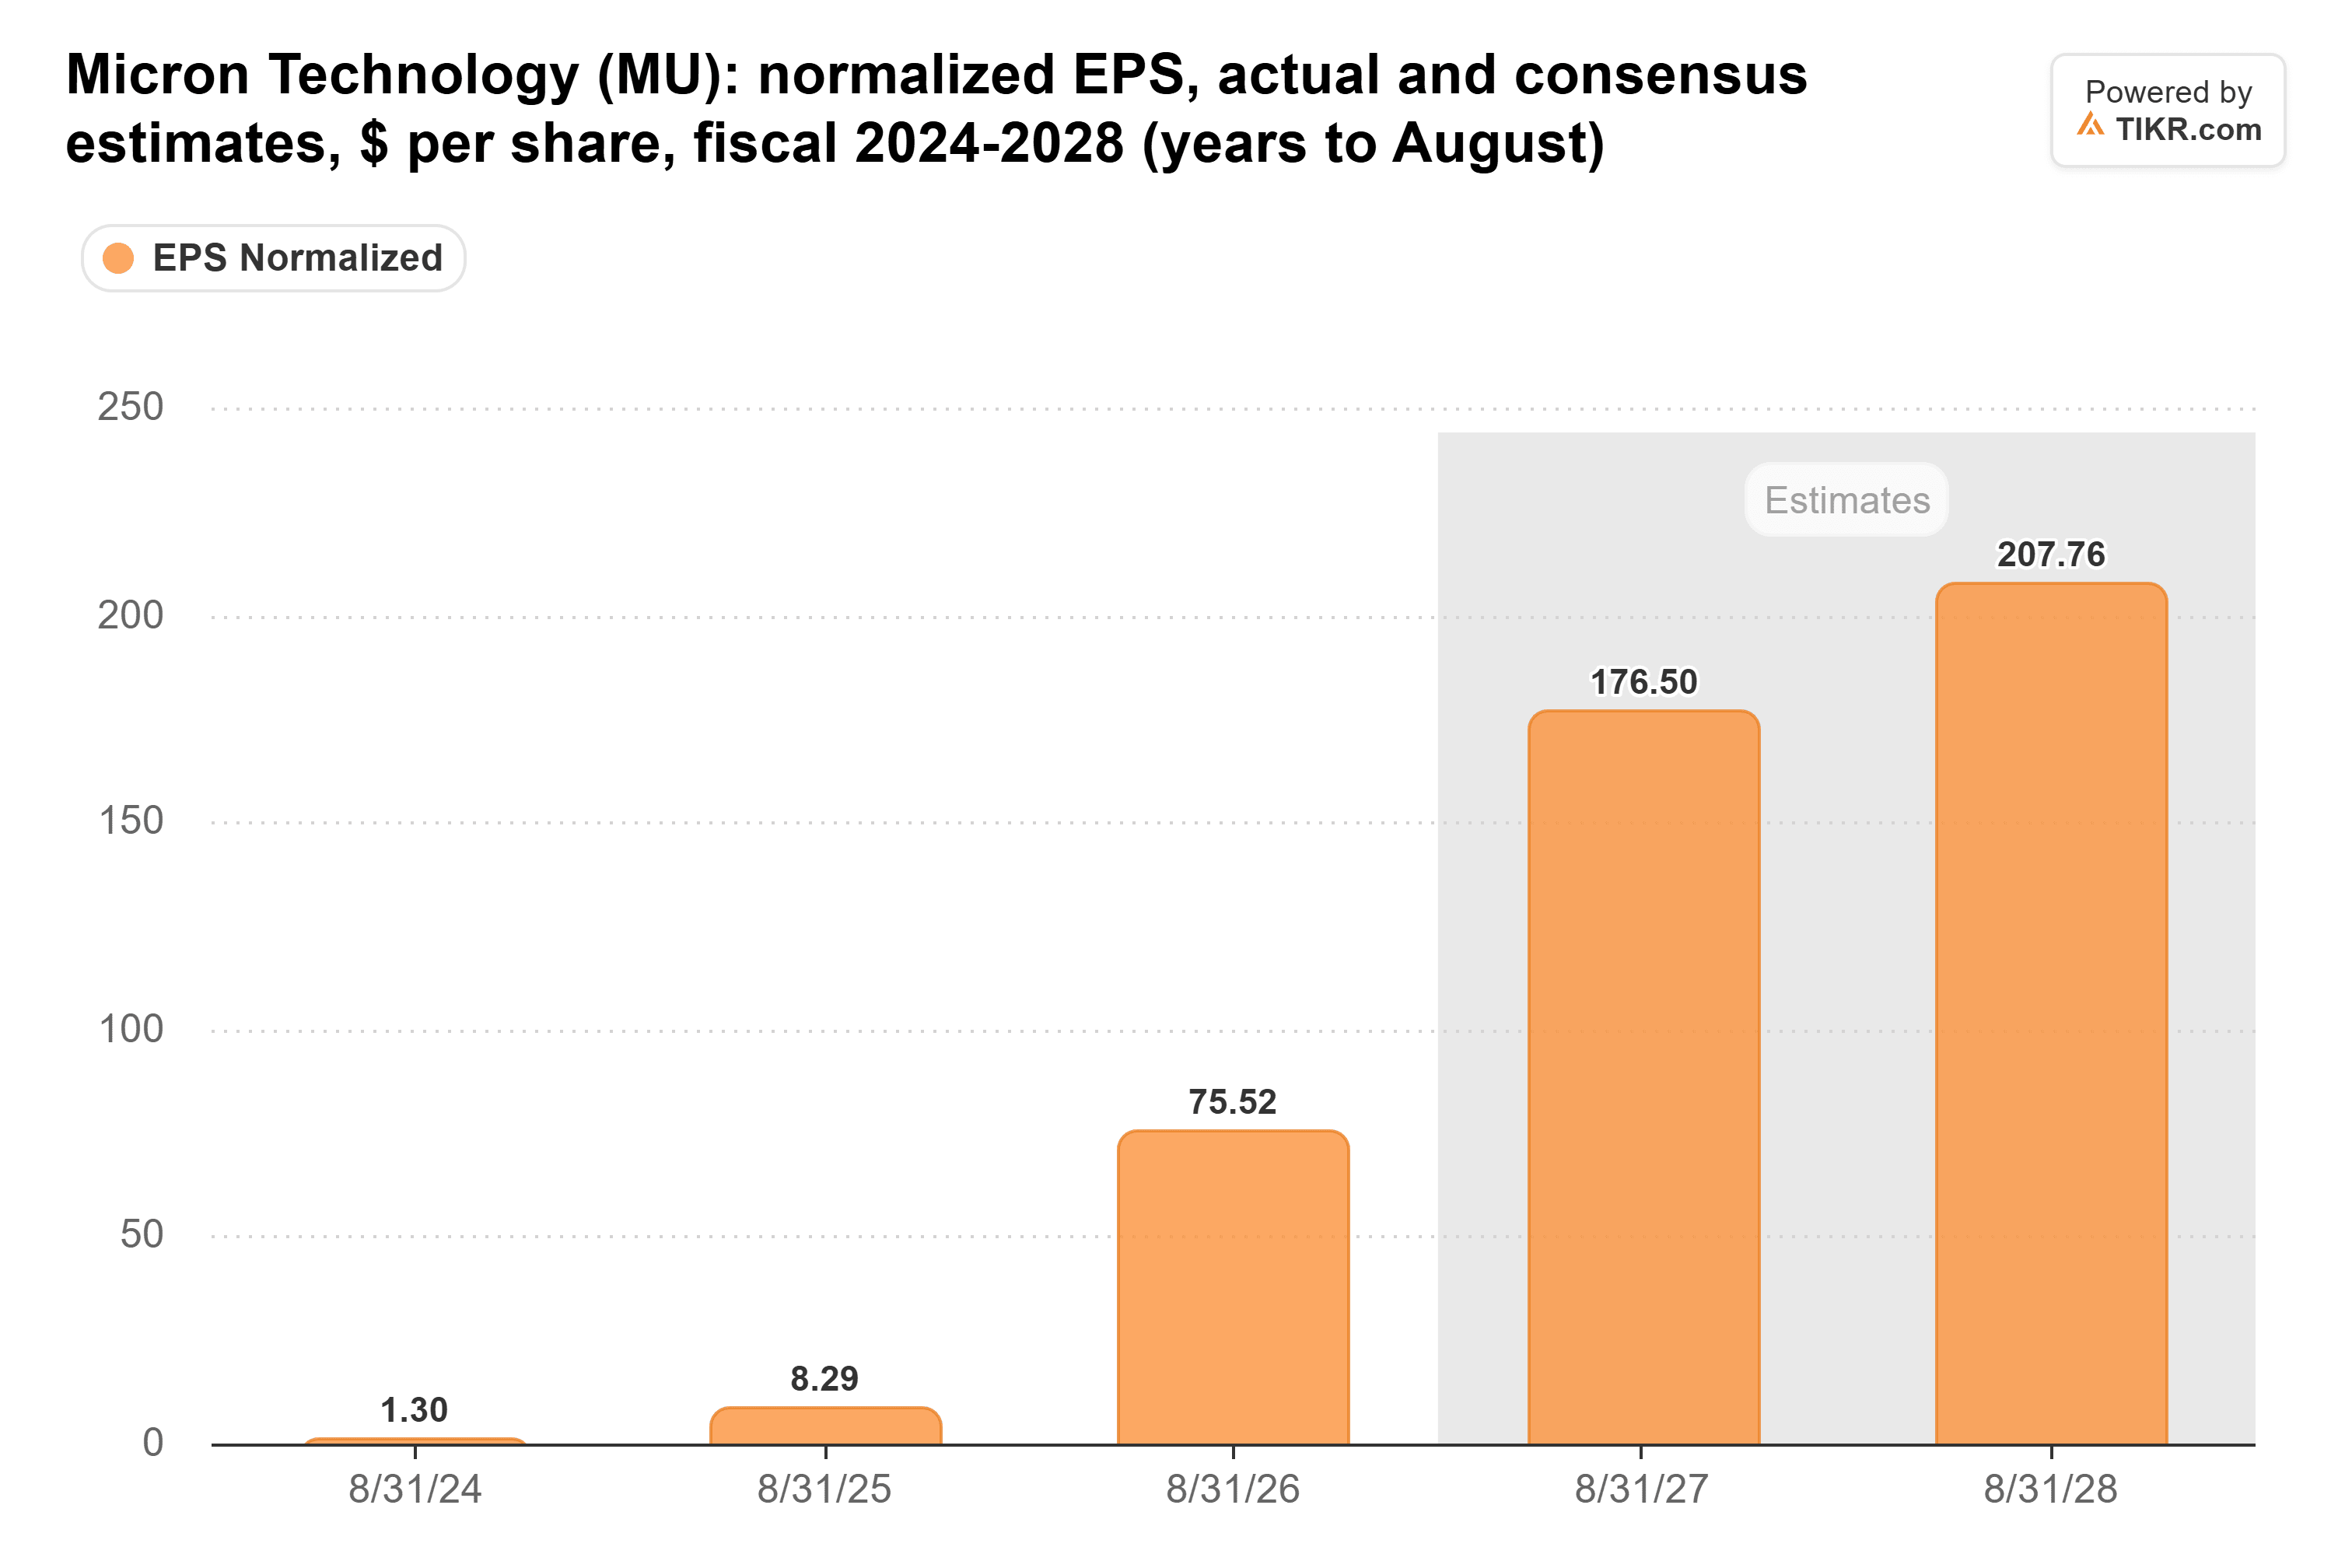
Analysts expect Micron’s normalized earnings per share to climb from $75.52 in fiscal 2026, which ended Sept. 3, to $176.50 in fiscal 2027 and $207.76 in fiscal 2028:
Investors don’t buy it. Micron trades at 3.9x its next twelve months of expected earnings, below any quarter-end reading in the past five years:
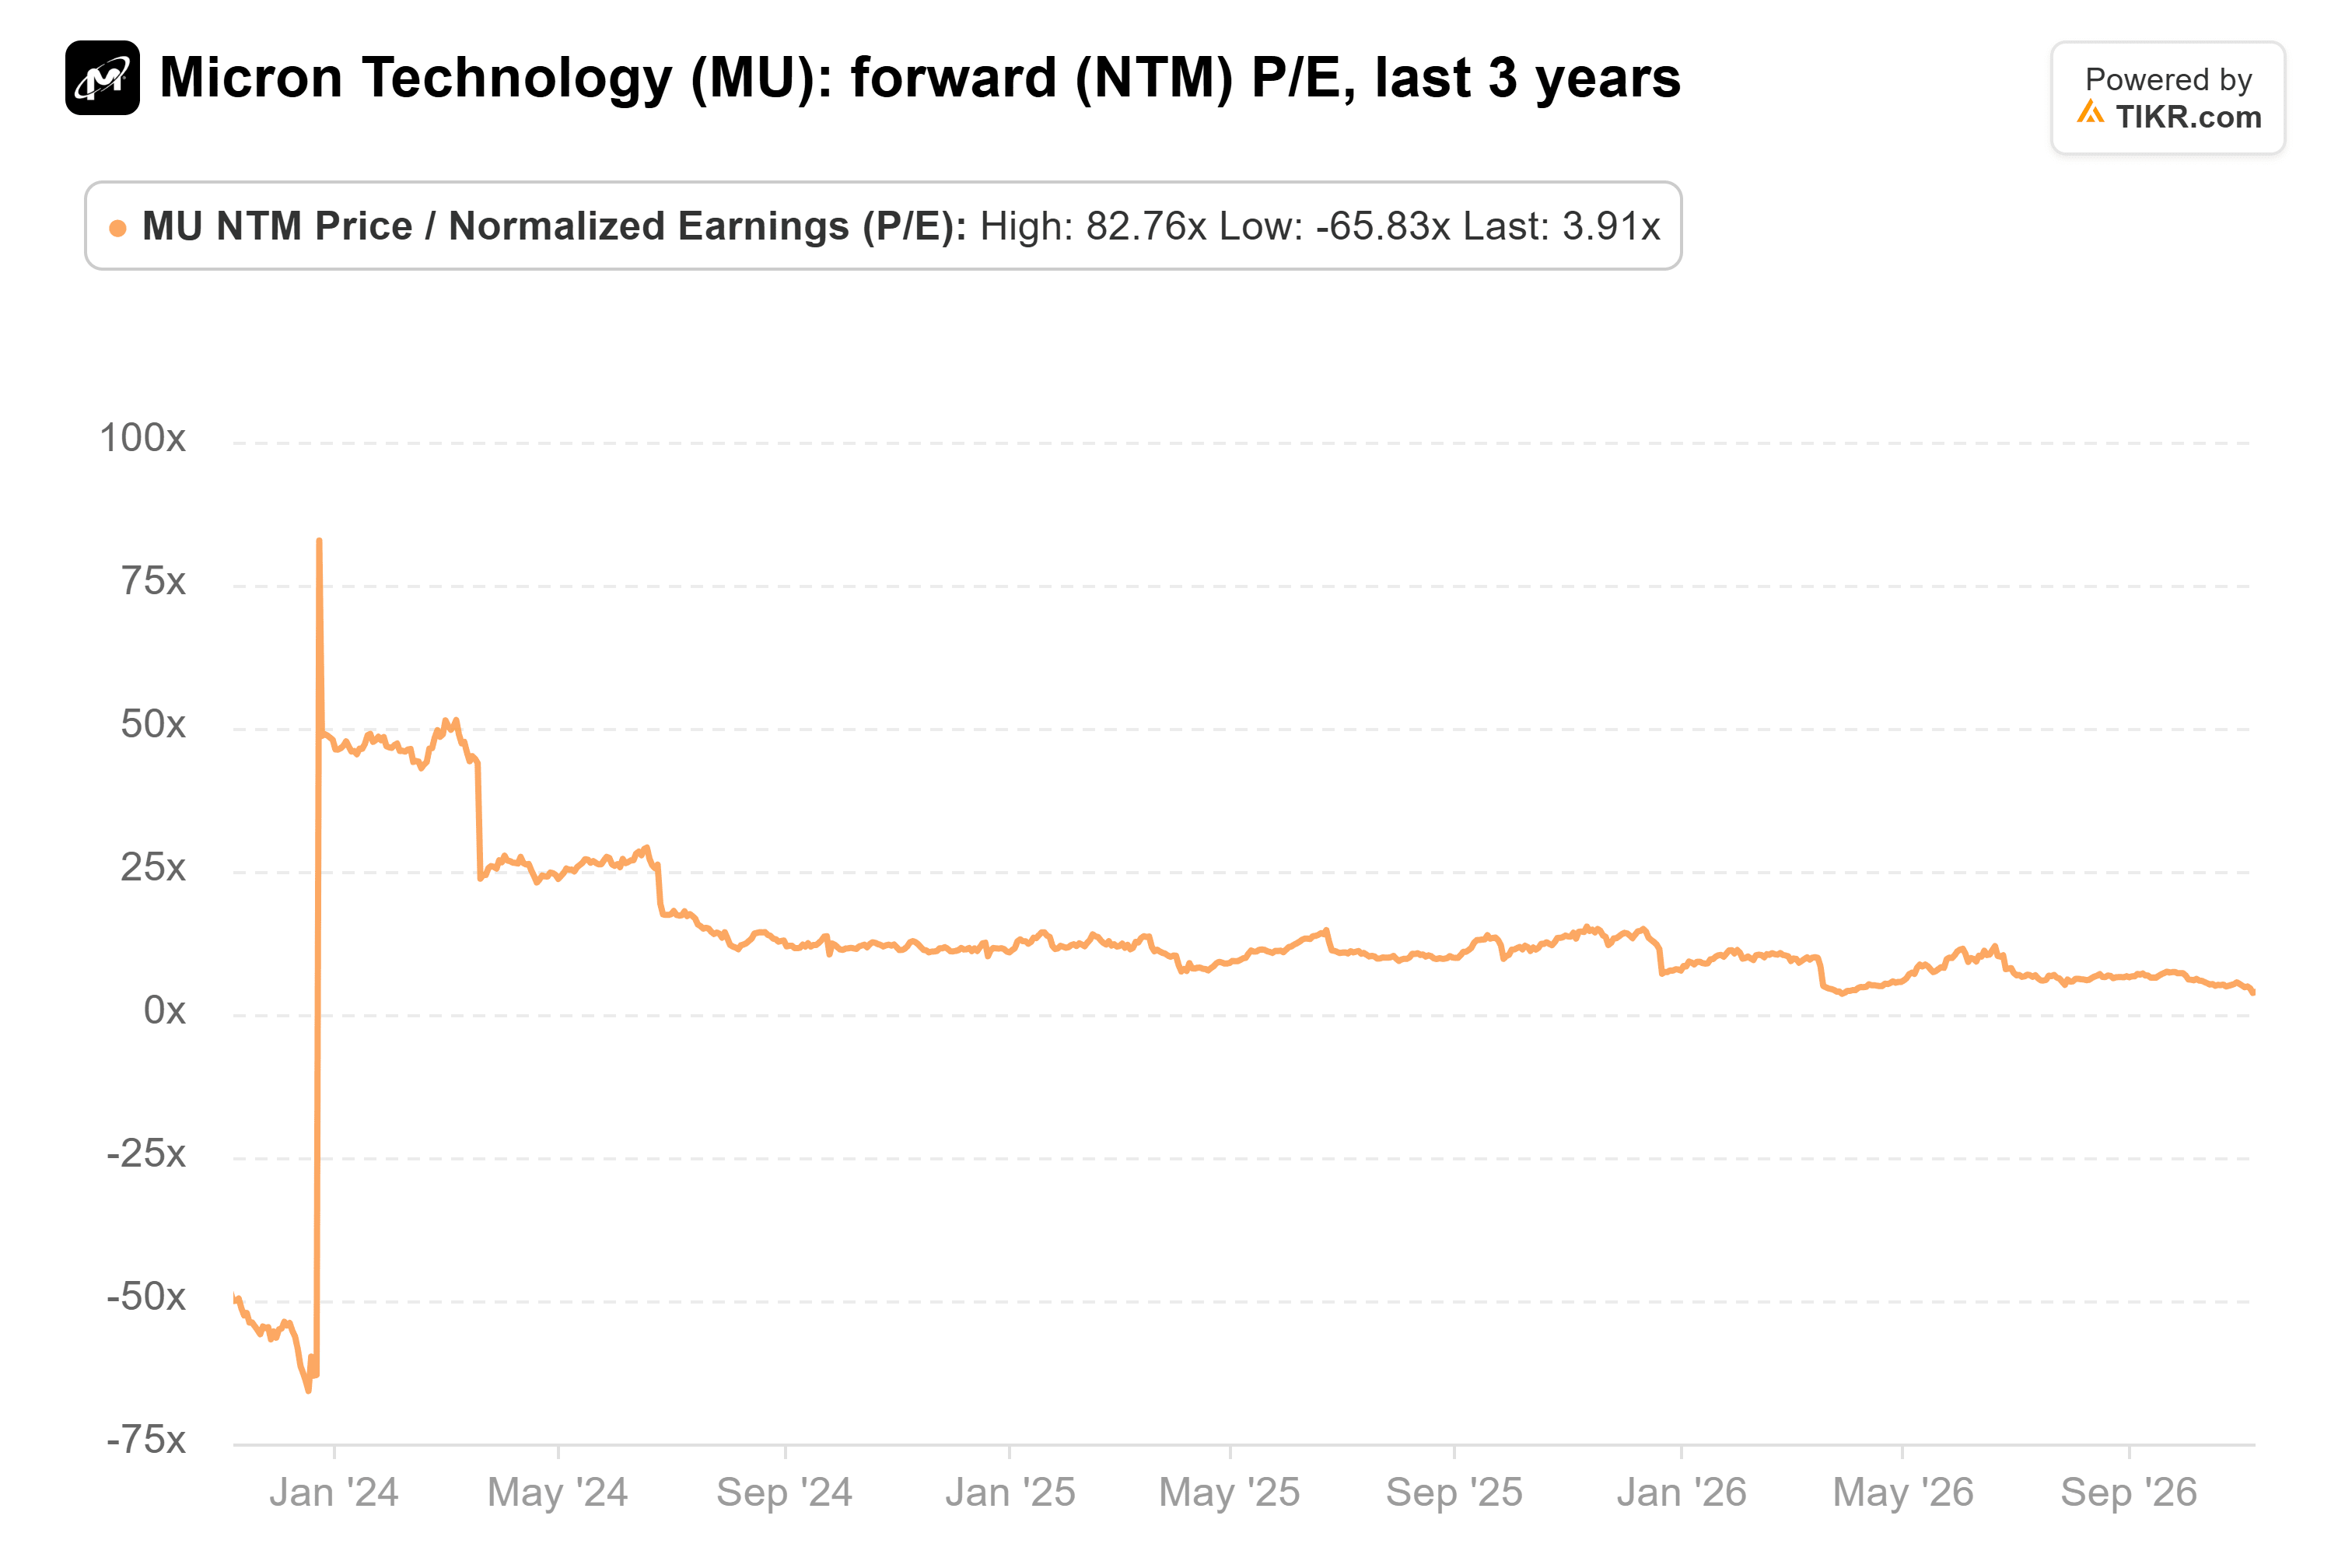
That’s close to where it sat in 2017 and 2018, when the last memory cycle peaked. Micron’s earnings per share then fell 79%, from $11.51 in fiscal 2018 to $2.37 in fiscal 2020. Santoli went further on Squawk on the Street earlier Friday, saying the market expects these earnings to be an anomaly, with losses somewhere down the line in the cycle.
2028 is the year to worry about
Memory has gone bust before, and fast. Micron’s revenue halved in fiscal 2023, then reached more than four times its old peak by fiscal 2026:
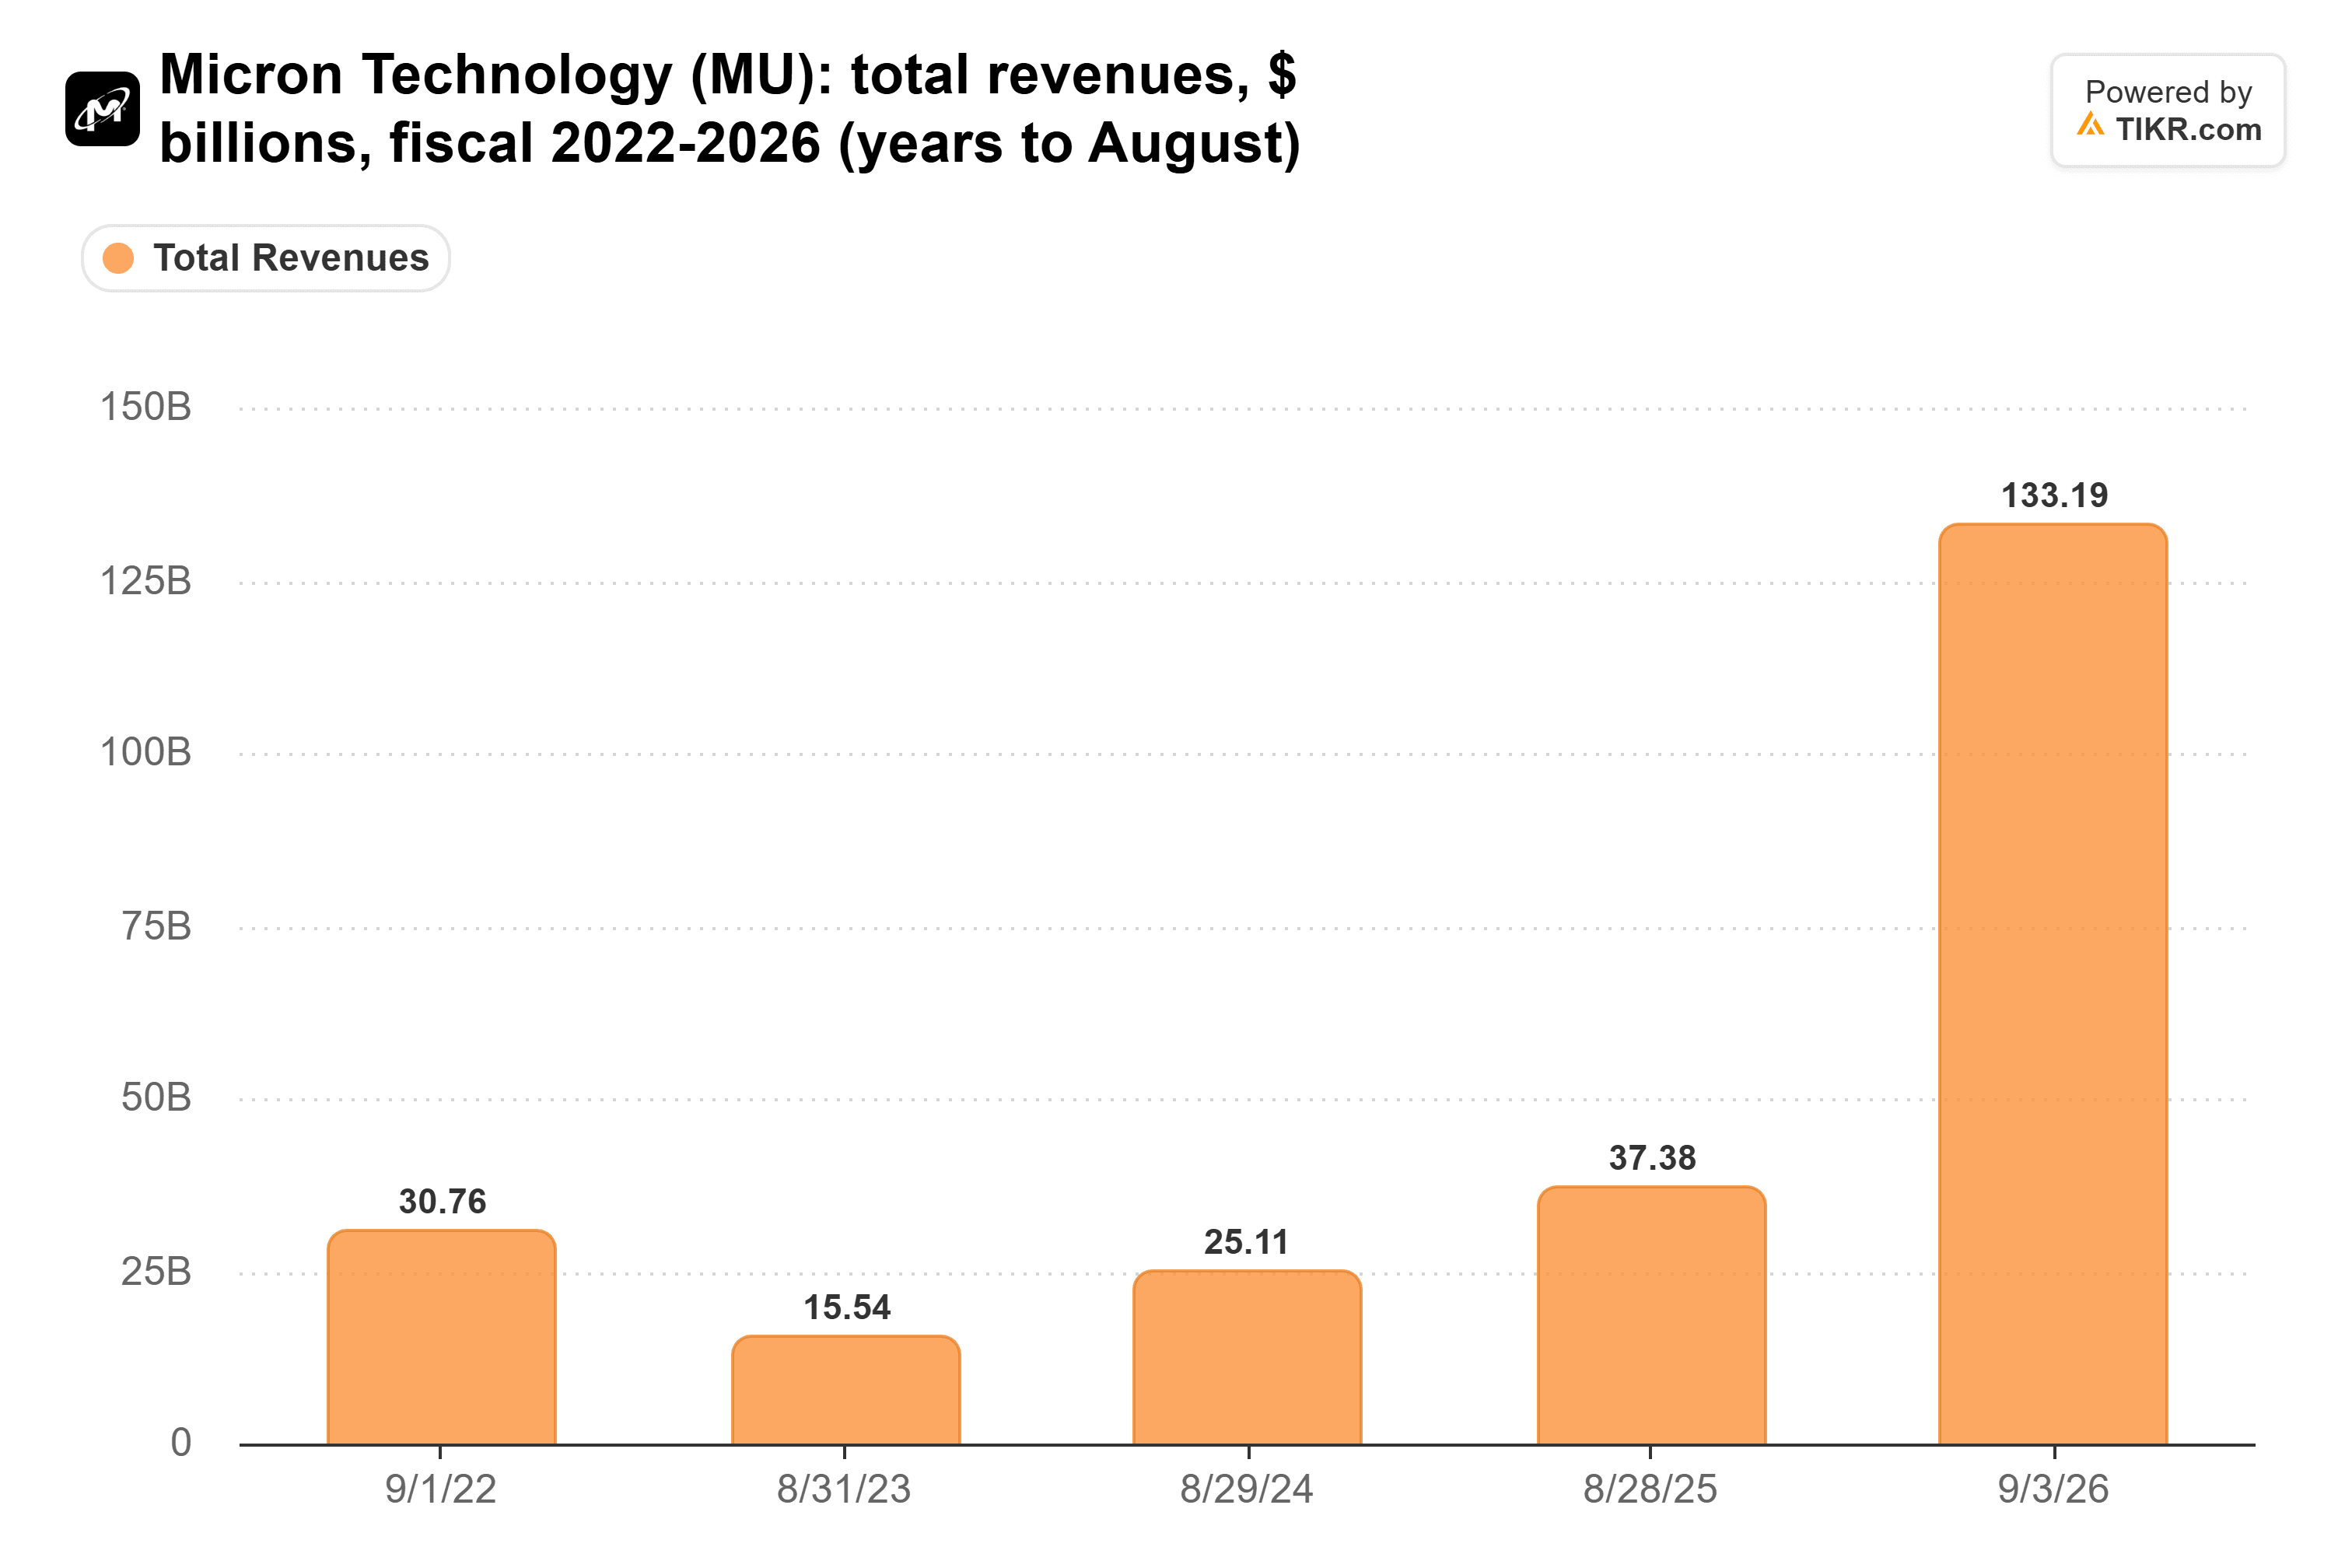
Its GAAP gross margin went from 45.2% in fiscal 2022 to 2.7% in fiscal 2023, then rebounded to 80.7% in fiscal 2026.
This time, the worry is supply. Micron’s own new fabs start adding output in mid-2027 and late 2028, and China’s ChangXin Memory Technologies is building too. Demand could also slip: UBS analysts estimate that construction pauses after the Democrats’ midterm sweep could threaten about 30% of the US data-center capacity expected in 2028. That’s the year analysts expect Micron’s record earnings.
Management is counting on its contracts. Micron has signed 26 multi-year take-or-pay agreements, which it estimates will cover over 35% of revenue through 2030, and it says over 75% of its 2027 output is already committed. Most of its sales would still reprice with the market.
Don’t follow this trade
I wouldn’t read anything into the sale. At 3.9x, investors already expect Micron’s earnings to fall hard. If expected earnings were cut in half, the stock would still trade under 8x, below the roughly 10x median of its quarter-end readings since 2014.
The way I see it, today’s price only looks expensive if earnings collapse the way they did last cycle. With the contracts in place, a fall that deep looks less likely this time. I’d rather be buying Micron here than selling it.
Of course, the trouble the market fears could still come, and December’s fiscal first-quarter report is the next check. Management calls that quarter fiscal 2027’s gross-margin floor and guides to a non-GAAP gross margin of 86.25%. If Micron misses that, or raises its outlook for 2028 industry supply, investors’ doubts will look a lot smarter than Trump’s trade.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!