Key Takeaways
- ExxonMobil raised its quarterly dividend 4% to $1.07 a share on Oct. 30, its 44th yearly increase in a row, yet it yields 2.4% against Enbridge’s 5.7%.
- Exxon’s dividend took 40% of its free cash flow over the past year, and the company carries almost no net debt.
- Enbridge’s distributable cash flow has covered its dividend every year for a decade, though its net debt runs 6.3x EBITDA.
- The things to watch are whether Enbridge’s debt comes down after its September deal and share sale, and whether Exxon’s cash holds up as oil prices ease.
ExxonMobil (XOM) raised its dividend for the 44th year in a row on Oct. 30, by 4% to $1.07 a share each quarter. But the stock still yields just 2.4%.
Enbridge (ENB) yields 5.7% and has raised its own dividend 31 years running. So if I could only hold one of them for the next 10 years, which would it be?
| Metric | ExxonMobil (XOM) | Enbridge (ENB) |
|---|---|---|
| Dividend yield | 2.4% | 5.7% |
| Dividend growth, fiscal 2020-2025 | 2.8% a year | 3.1% a year (in C$) |
| Yearly raises in a row (company’s count) | 44 | 31 |
| Coverage, last reported | Cash dividend payout ratio: 40% (TTM to Sept. 30, 2026) | Distributable cash flow coverage: 1.5x (fiscal 2025) |
| Net debt / EBITDA (LTM) | 0.3x | 6.3x |
| Interest coverage (LTM) | 58.7x | 2.3x |
Source: TIKR, Nov. 5, 2026; raises from each company’s own releases.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Exxon raises slowly, on purpose
Exxon brought in $19.1 billion of free cash flow in the third quarter of 2026 and paid $4.3 billion of it out as dividends. Growth came from record fuels output at its refineries and from Guyana and the Permian, while the Middle East conflict cut its volumes in Qatar.
Over the twelve months to Sept. 30, 2026, the dividend took a comfortable 40% of free cash flow. That ratio moves a lot, though: it went from 25.6% in fiscal 2022 to a much tighter 73.0% in fiscal 2025.
Exxon’s free cash flow has swung far more than its dividend over the past decade:
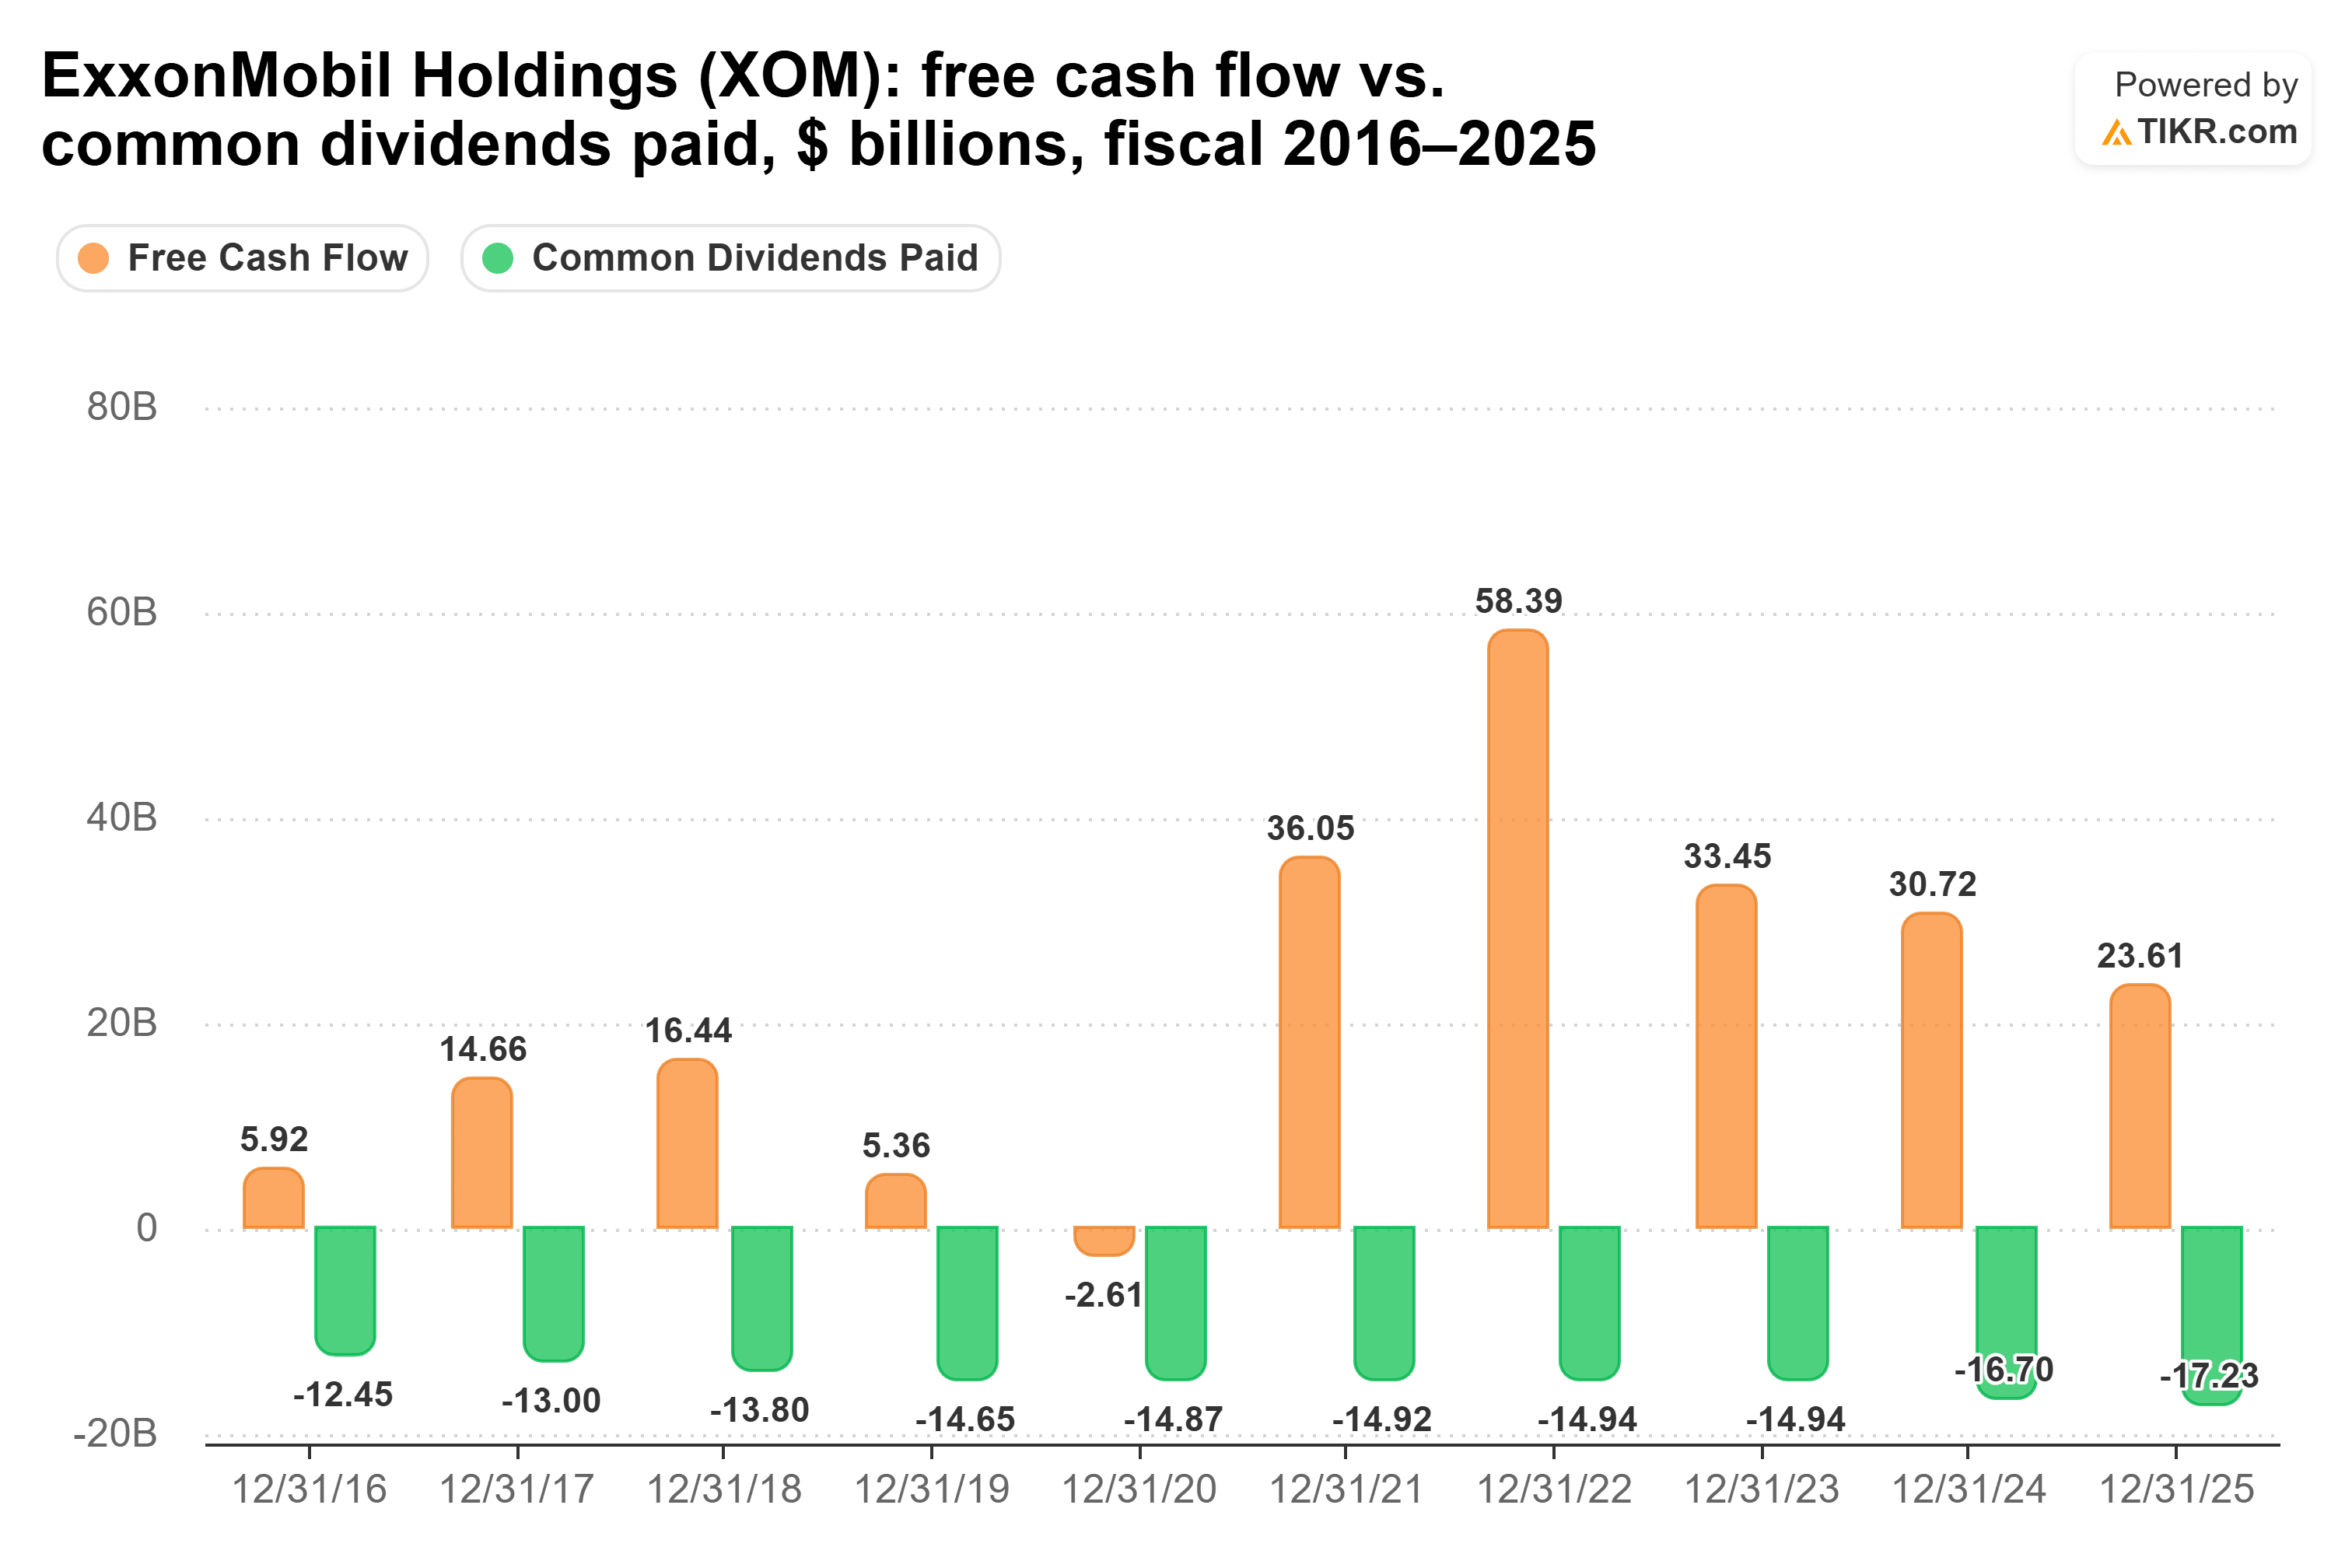
It fell short of the dividend in fiscal 2016, 2019 and 2020, and Exxon kept raising anyway. CEO Darren Woods explained why the raises stay small on the third-quarter call: “we’re not going to ever cut our dividend. So any increases we add becomes an obligation that we’ve got to commit to the future.”
So the dividend grew just 2.8% a year from fiscal 2020 to fiscal 2025 ($3.48 to $4.00 a share), and buybacks do the rest: Exxon plans $20 billion of them in 2027, market conditions permitting.
The risk is that some of 2026’s cash came from war-lifted oil and refining prices, and Brent fell more than 4% on Nov. 3 on hopes that those supply disruptions would ease.
Enbridge pays more, and borrows more
Exxon’s free cash flow swings with prices, but Enbridge’s cash has climbed far more steadily. Its gas pipelines are growing on customer demand, and its gas utilities on rate increases.
Distributable cash flow covered the dividend 1.5x in fiscal 2025, at C$5.71 a share against C$3.77, and it has covered it every year for a decade:
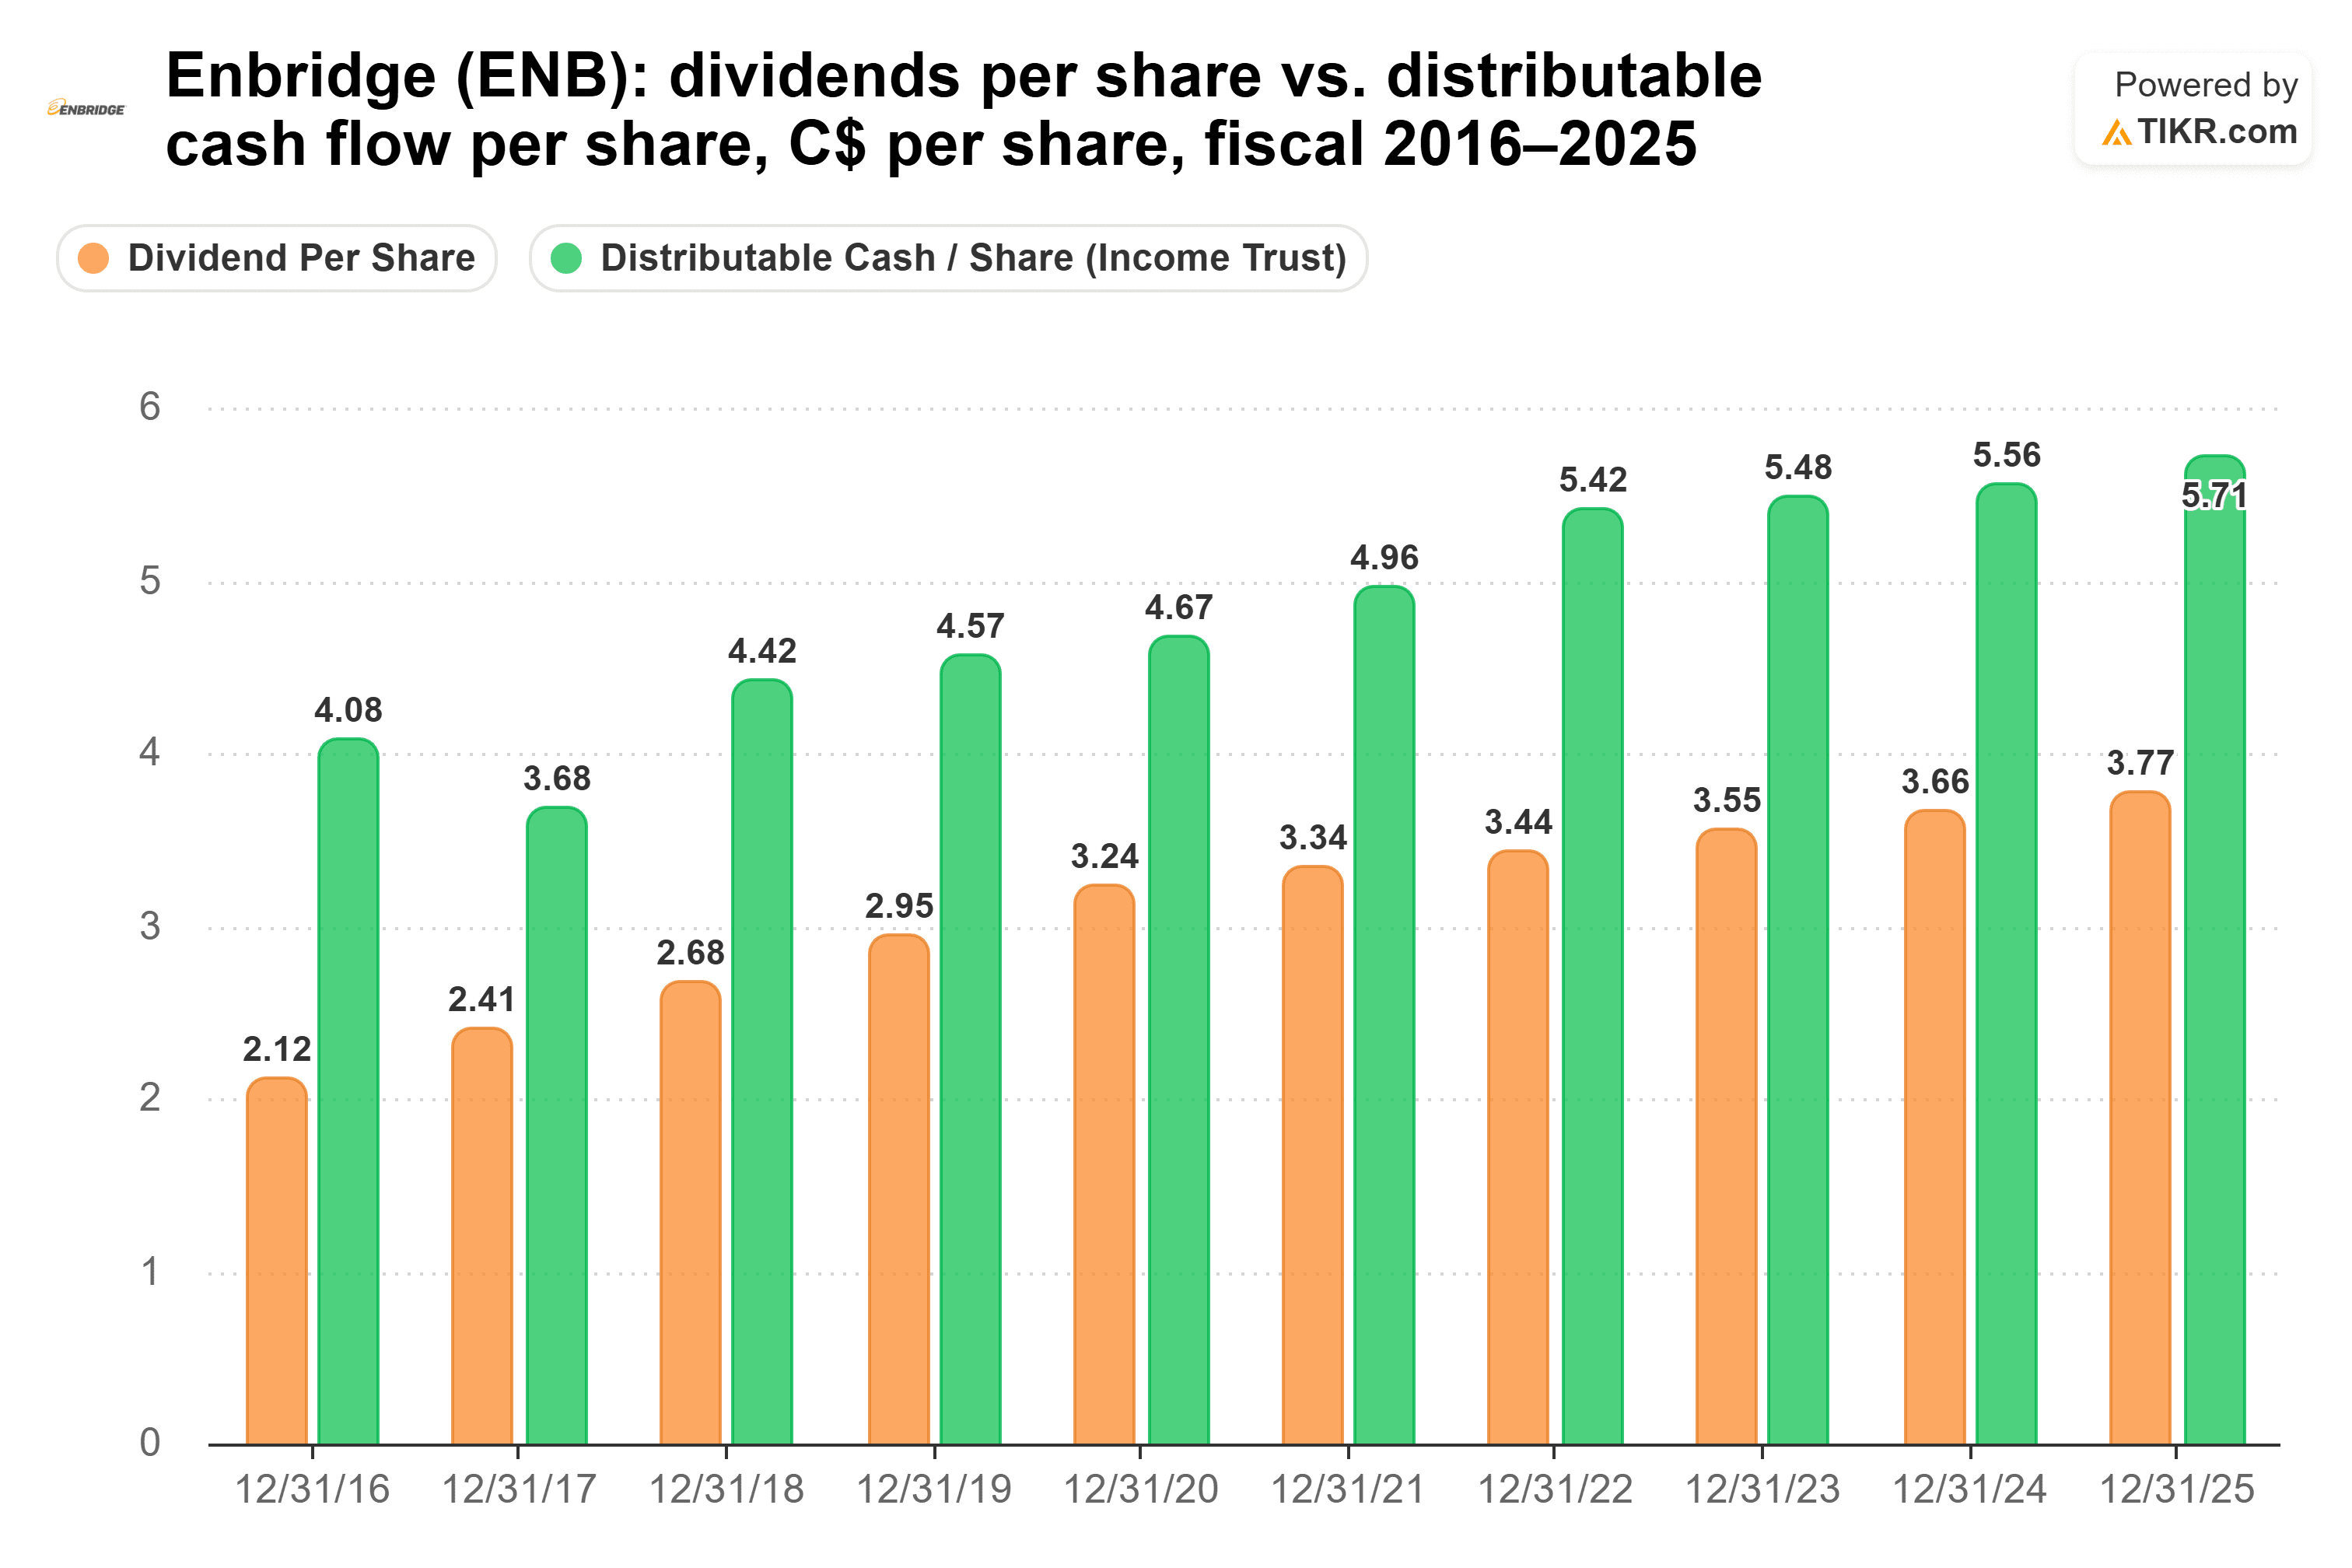
Coverage ranged from a low of 1.4x in fiscal 2020 to a high of 1.9x in fiscal 2016, as distributable cash flow per share rose from C$4.08 to C$5.71. Management has reaffirmed 2026 guidance of C$5.70 to C$6.10 a share, with about 5% a year of growth after that.
Its last raise, on Dec. 3, 2025, was 3%, to C$0.97 a quarter, in line with its 3.1% a year from fiscal 2020 to fiscal 2025 (C$3.24 to C$3.77).
The catch is debt. Net debt runs 6.3x EBITDA, and EBIT covers interest just 2.3x. On Sept. 9, Enbridge agreed to buy Tallgrass Energy’s crude business for US$2.55 billion, and it sold C$2.6 billion of new shares to help pay for that deal and an earlier one. CEO Greg Ebel retires at year-end, and Michele Harradence, who runs the gas utilities, takes over in January.
Enbridge pays in Canadian dollars, so the US-dollar amount moves with the exchange rate, and Canada withholds tax from dividends paid to US holders.
So which dividend wins?
If I can only hold one dividend stock for the next 10 years, it’s Enbridge.
At each stock’s five-year growth rate, $10,000 in Enbridge pays about $6,557 in dividends over the decade, $3,828 more than the $2,729 Exxon pays. By year 10, Enbridge would pay about $749 a year, a 7.5% yield on the original $10,000, against about $308, or 3.1%, for Exxon. (Enbridge’s figures are in Canadian dollars.)
Enbridge only needs to keep raising at the pace it already does, and management expects its cash flow to grow faster than the dividend.
Exxon has a strong case too. Its dividend takes 40% of free cash flow, its debt is minimal, and its $20 billion of 2027 buybacks put even more money in shareholders’ hands. But Exxon would need to raise its dividend far faster than its 2.8% pace to close a gap that wide, and its own policy keeps raises small.
Of course, Enbridge still has to bring that debt down. Its last raise came in early December, and this year’s will show whether the Tallgrass deal and the new shares changed anything.
Forget Enbridge: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Enbridge isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!