


Key Takeaways
- Four of the five stocks Bill Ackman’s Pershing Square bought or added to in the second quarter are up since June 30: Mastercard, Visa, S&P Global and Meta Platforms. Netflix is down 11%.
- Mastercard has done best, up 27% since the quarter ended, and much of that came from investors paying a higher multiple for its earnings.
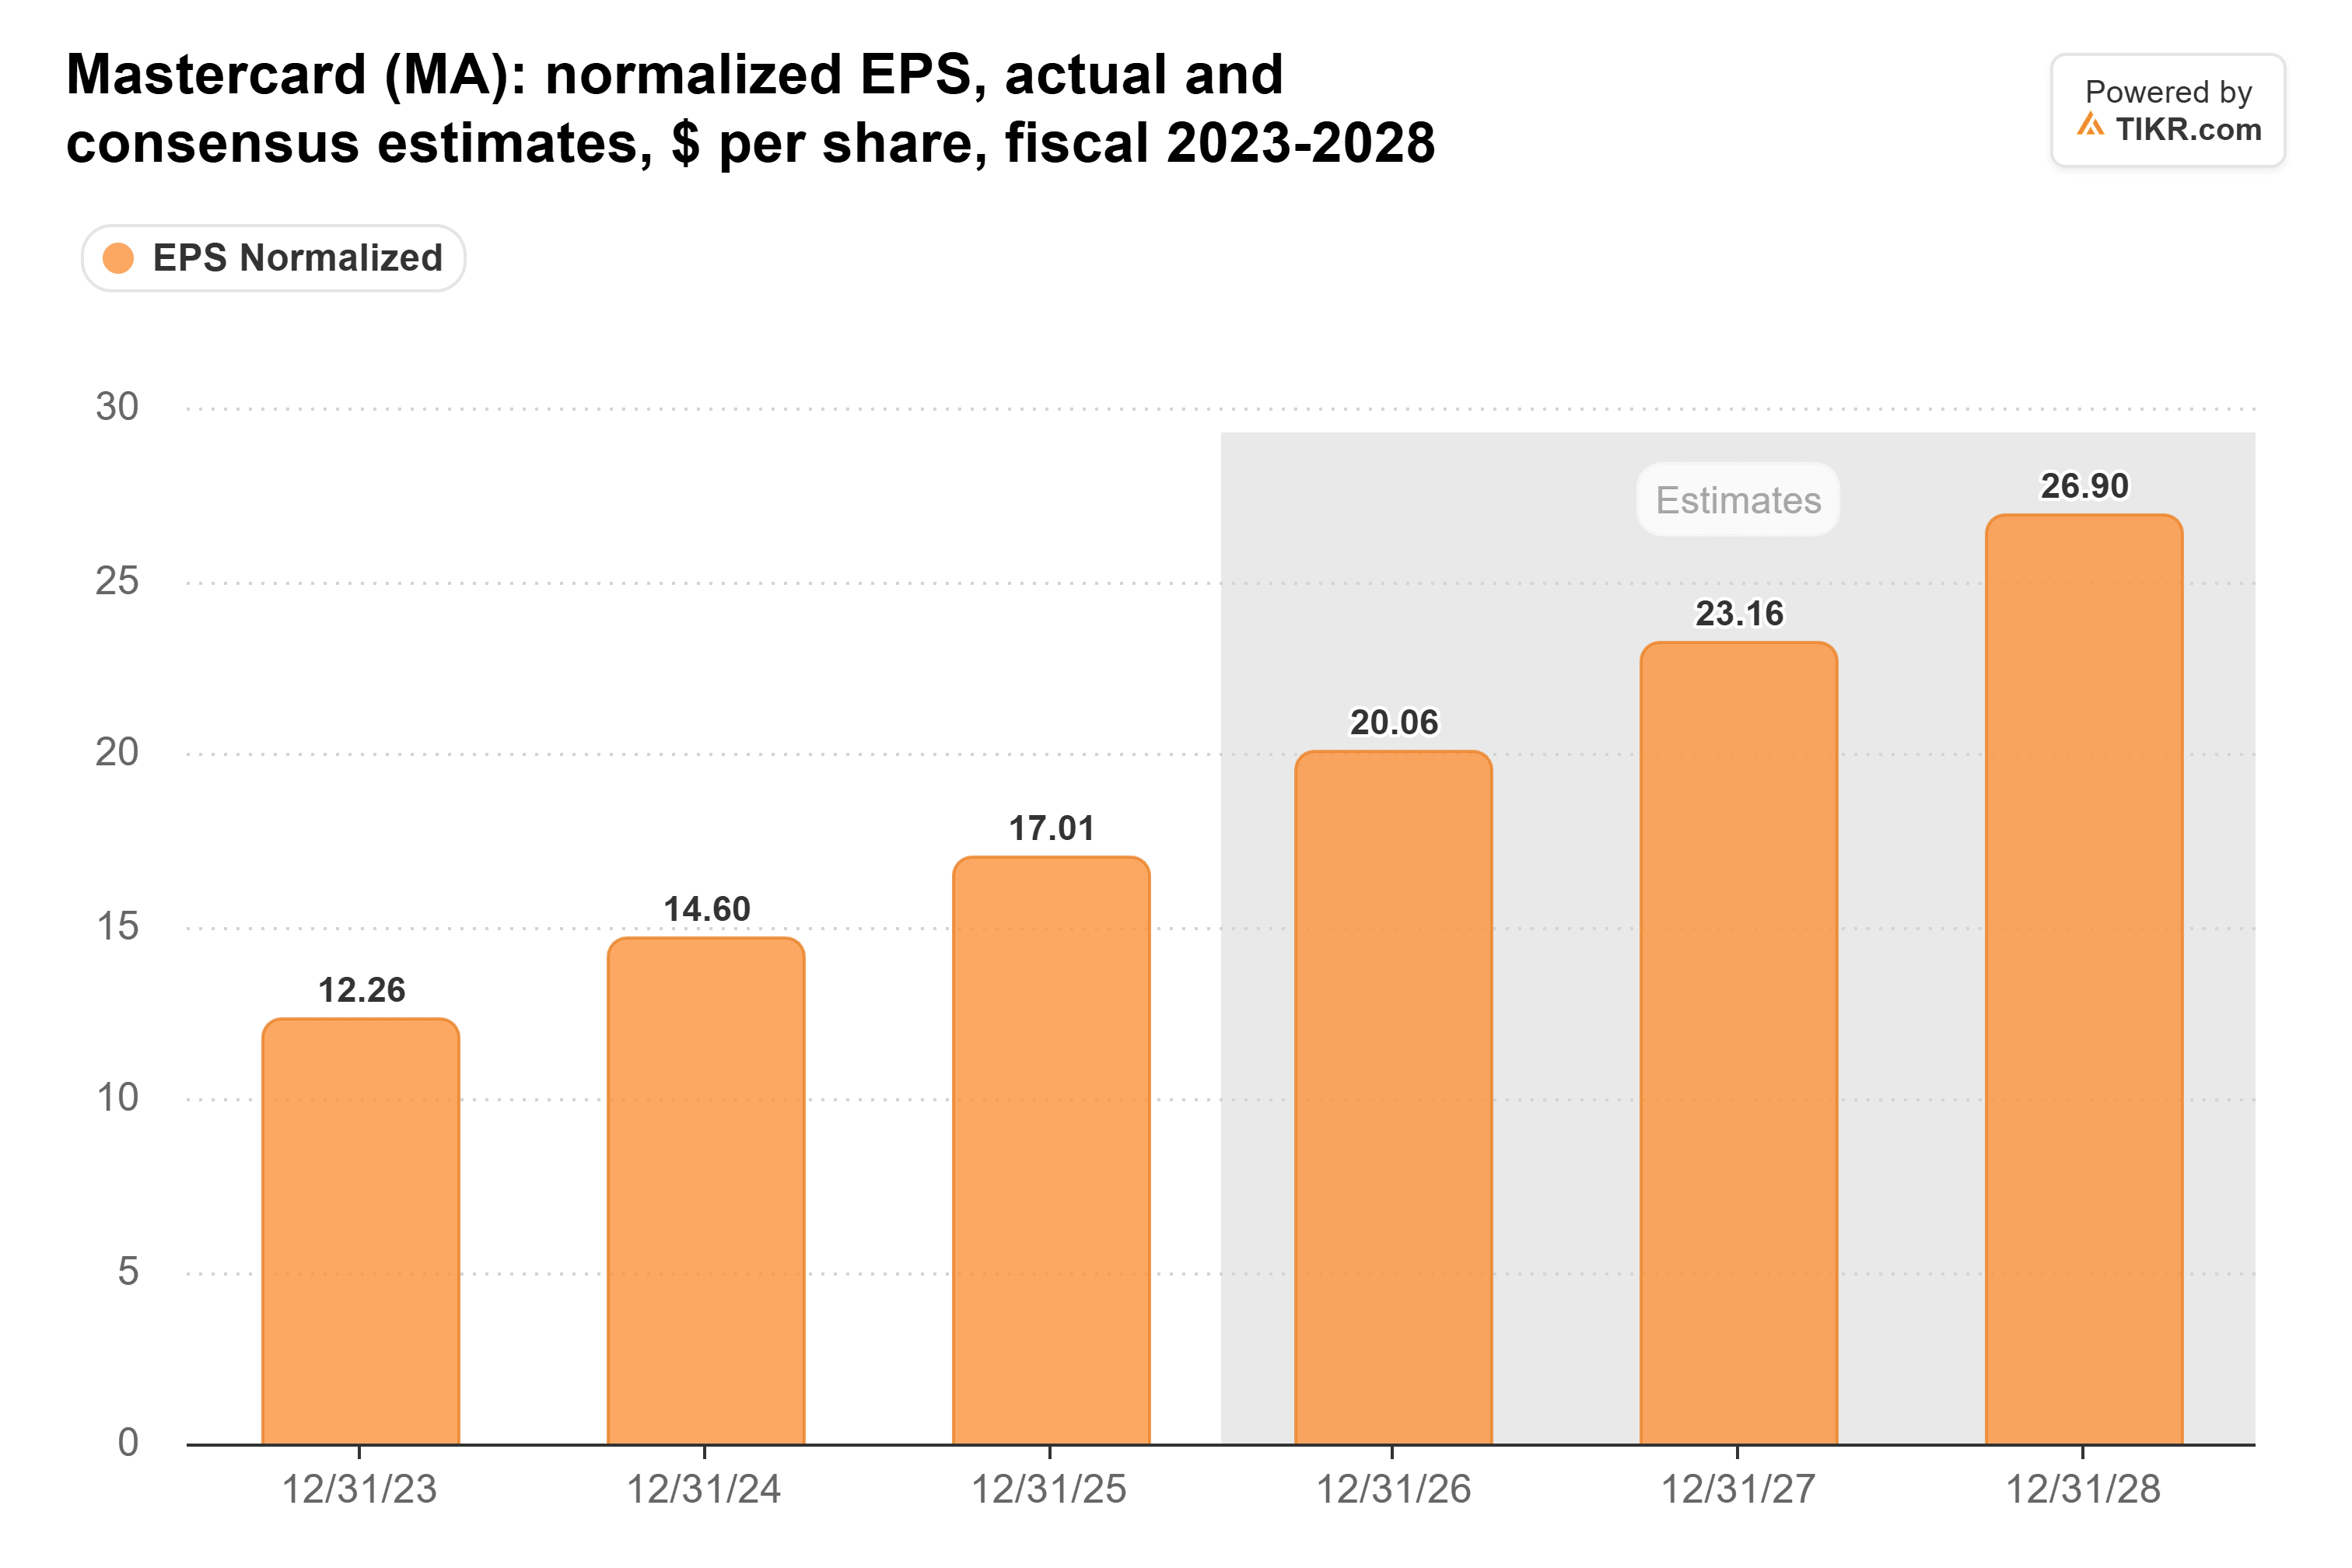
- Analysts expect Mastercard’s earnings per share to grow about 16% a year through 2028, and their average price target is 10% above the last close.
- Mastercard still looks fairly priced for its growth, so it isn’t too late to follow Ackman in, but from here its returns will likely track its earnings.
Bill Ackman’s Pershing Square has to file its next 13F by Nov. 16, and most of the stocks its last filing showed it buying have gone up since. Mastercard (MA) has gone up the most.
Four winners and one laggard
Pershing Square’s 13F for the quarter ended June 30, filed Aug. 14, shows four new positions and one it added to. Here’s each position at June 30, and how each stock has moved from its June 30 price to the last close:
- Mastercard: 2.12 million shares worth $1.09 billion, 5.6% of its 13F stocks; up 27%
- Visa (V): 3.27 million shares worth $1.12 billion, 5.8%; up 23%
- S&P Global (SPGI): 2.59 million shares worth $1.06 billion, 5.4%; up 15%
- Meta Platforms (META): 3.20 million shares worth $1.80 billion, 9.2%, after a 20% increase in its share count; up 8%
- Netflix (NFLX): 13.08 million shares worth $934 million, 4.8%; down 11%
Together, the five made up about 31% of the $19.47 billion of US stocks in the filing. Those figures are each stock’s move since the quarter ended. A 13F doesn’t show what Pershing paid, or whether it still holds every share.
TIKR tracks 40 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Mastercard’s quarter backed him up
Ackman said on CNBC’s Squawk Pod this month that he bought Visa and Mastercard this year after years of finding them too expensive, and he called Visa “a royalty on people spending money.” Mastercard’s third quarter showed what he was paying for. Revenue rose 14% to $9.81 billion, services grew 19% on a currency-neutral basis, and adjusted EPS rose 21% to $5.31, ahead of the $5.17 analysts expected.
Analysts expect earnings per share to keep growing about 16% a year, from $17.01 in 2025 to $26.90 in 2028:
Part of the beat came from services projects and network deals pulled forward from the fourth quarter, though, and CFO Ling Hai warned on the call that “you will see a similar offset in Q4.” Analysts moved their estimates by less than 0.5% after the report, so I’d read the warning as already in their numbers.
Investors are paying up again
Mastercard’s forward P/E was 25x at the end of June, near the bottom of its five-year range. It has since climbed to 29x, just under its five-year average of 31x:
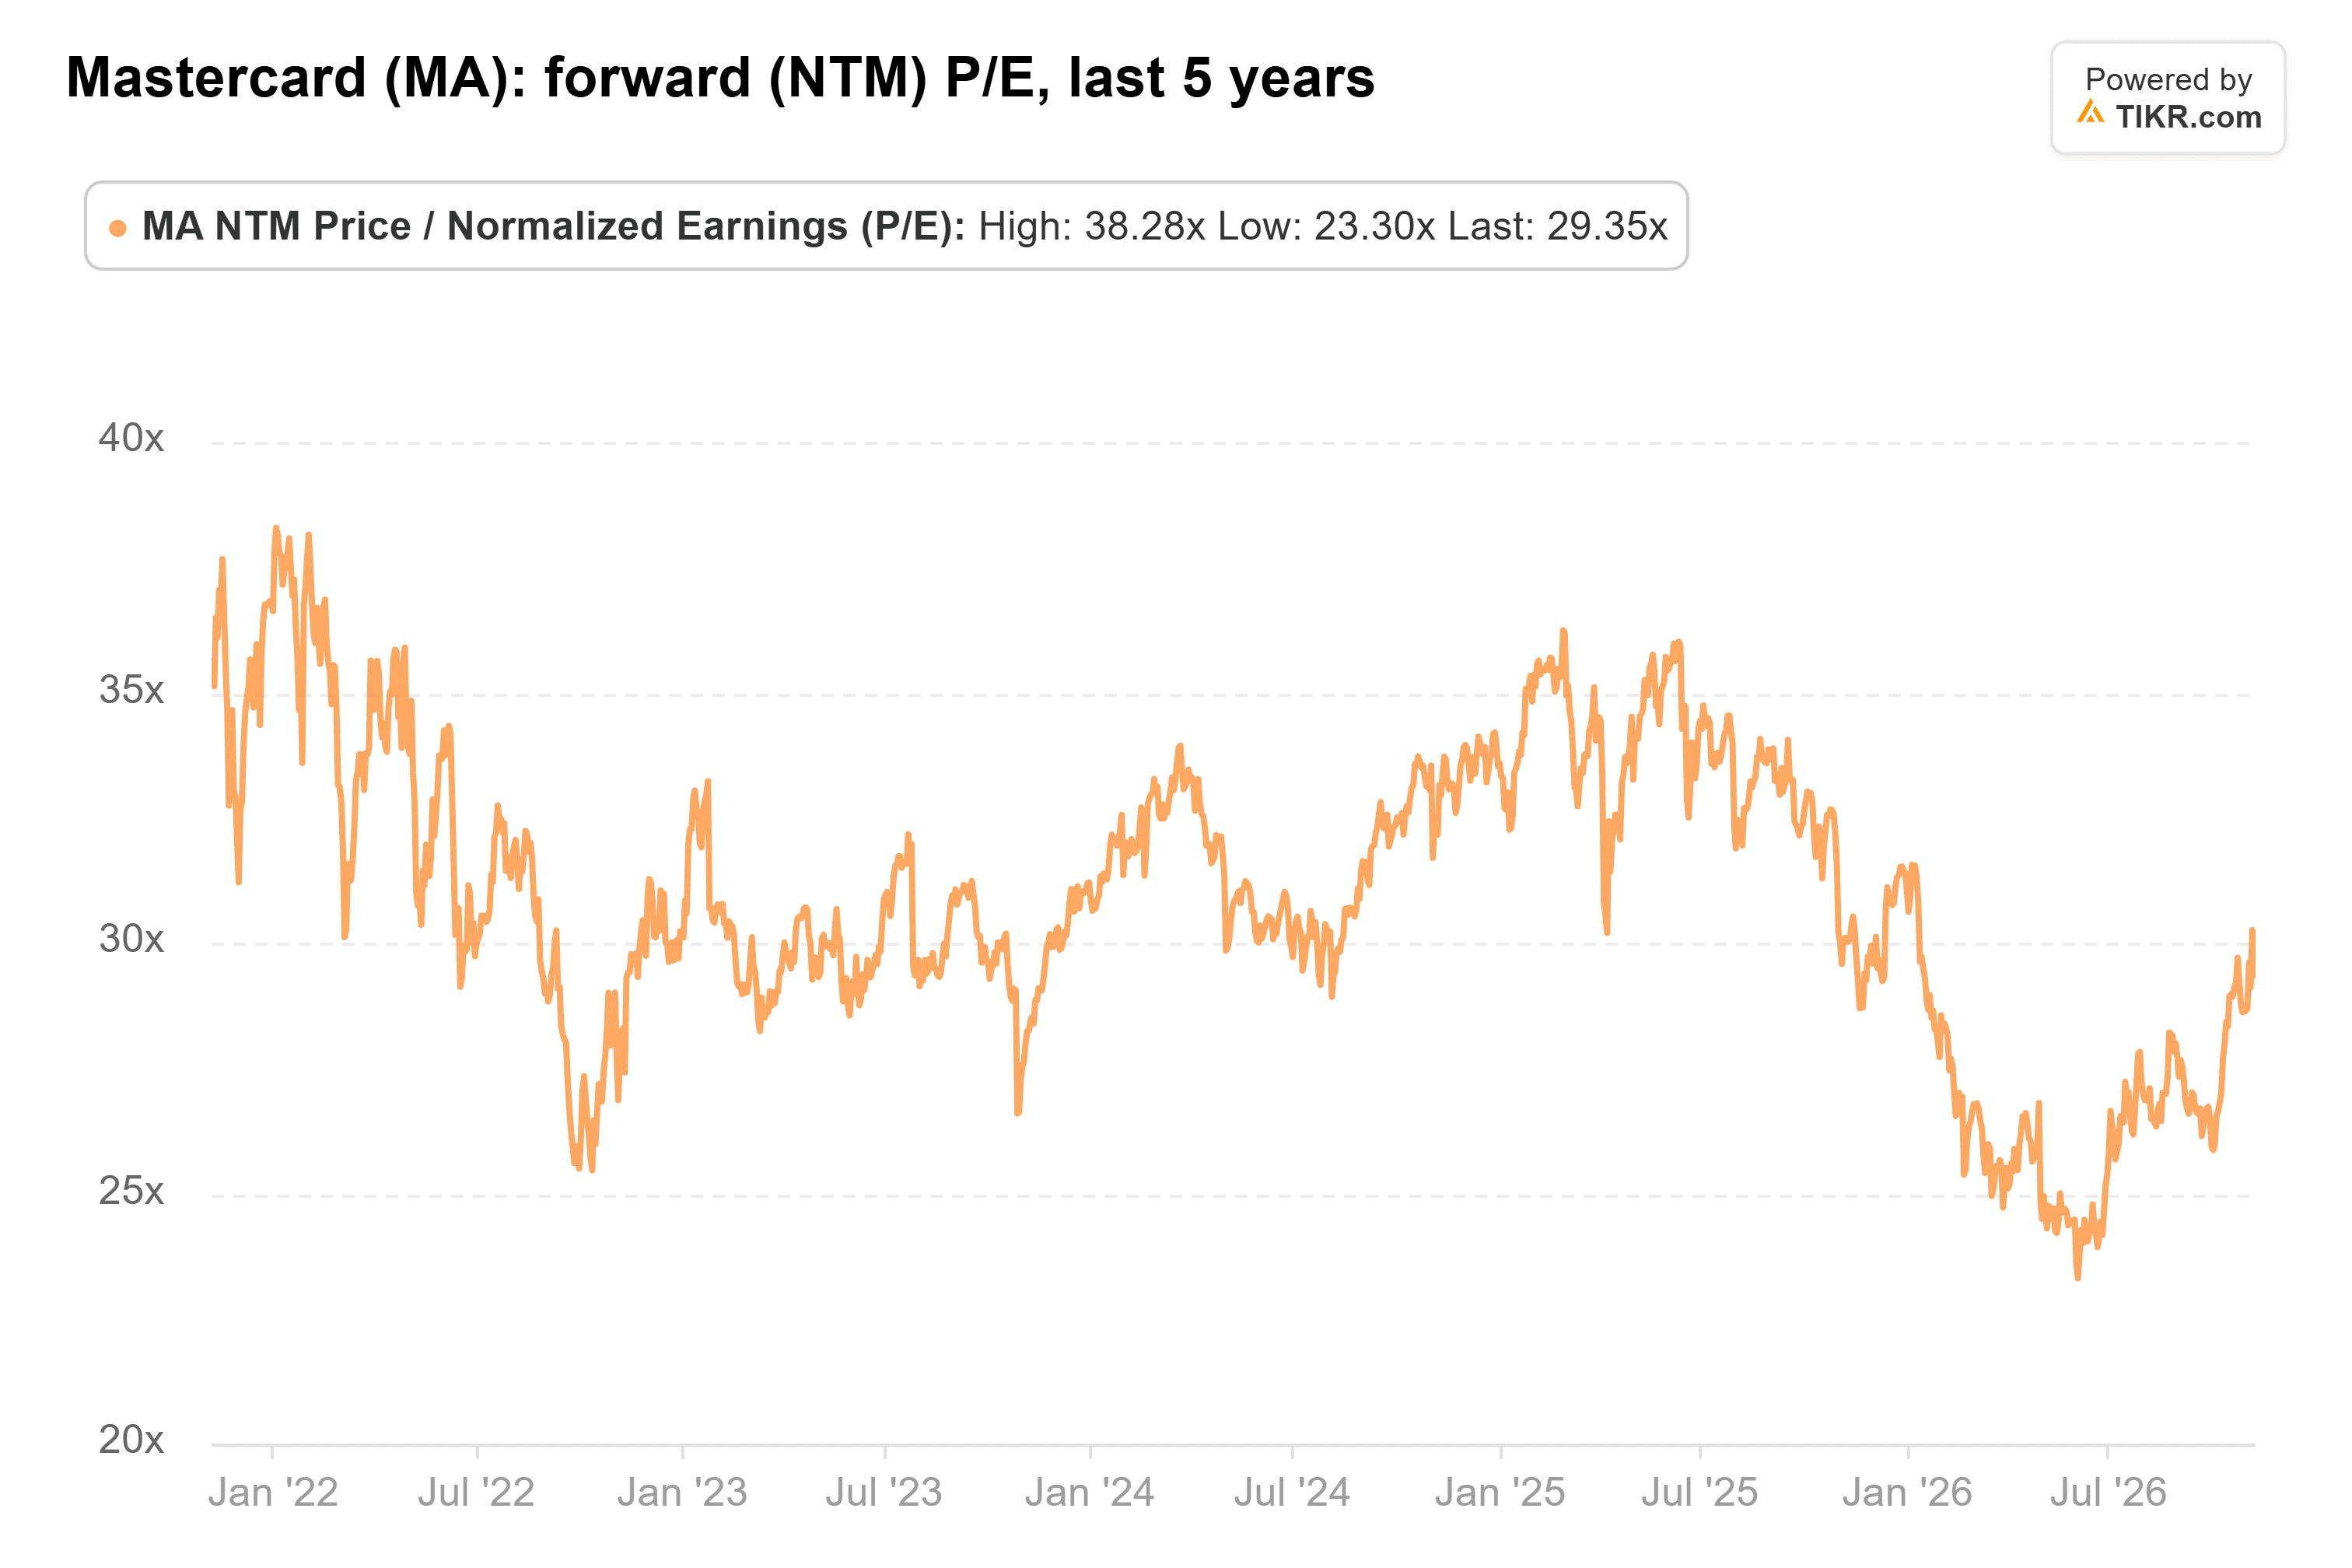
So investors are paying about 16% more for each dollar of Mastercard’s expected earnings than they were on June 30, and that explains much of the stock’s gain.
Analysts have followed the stock up. More than a dozen firms raised their targets after the third quarter, and the consensus target reached $716 this month, up from $657 a year ago:
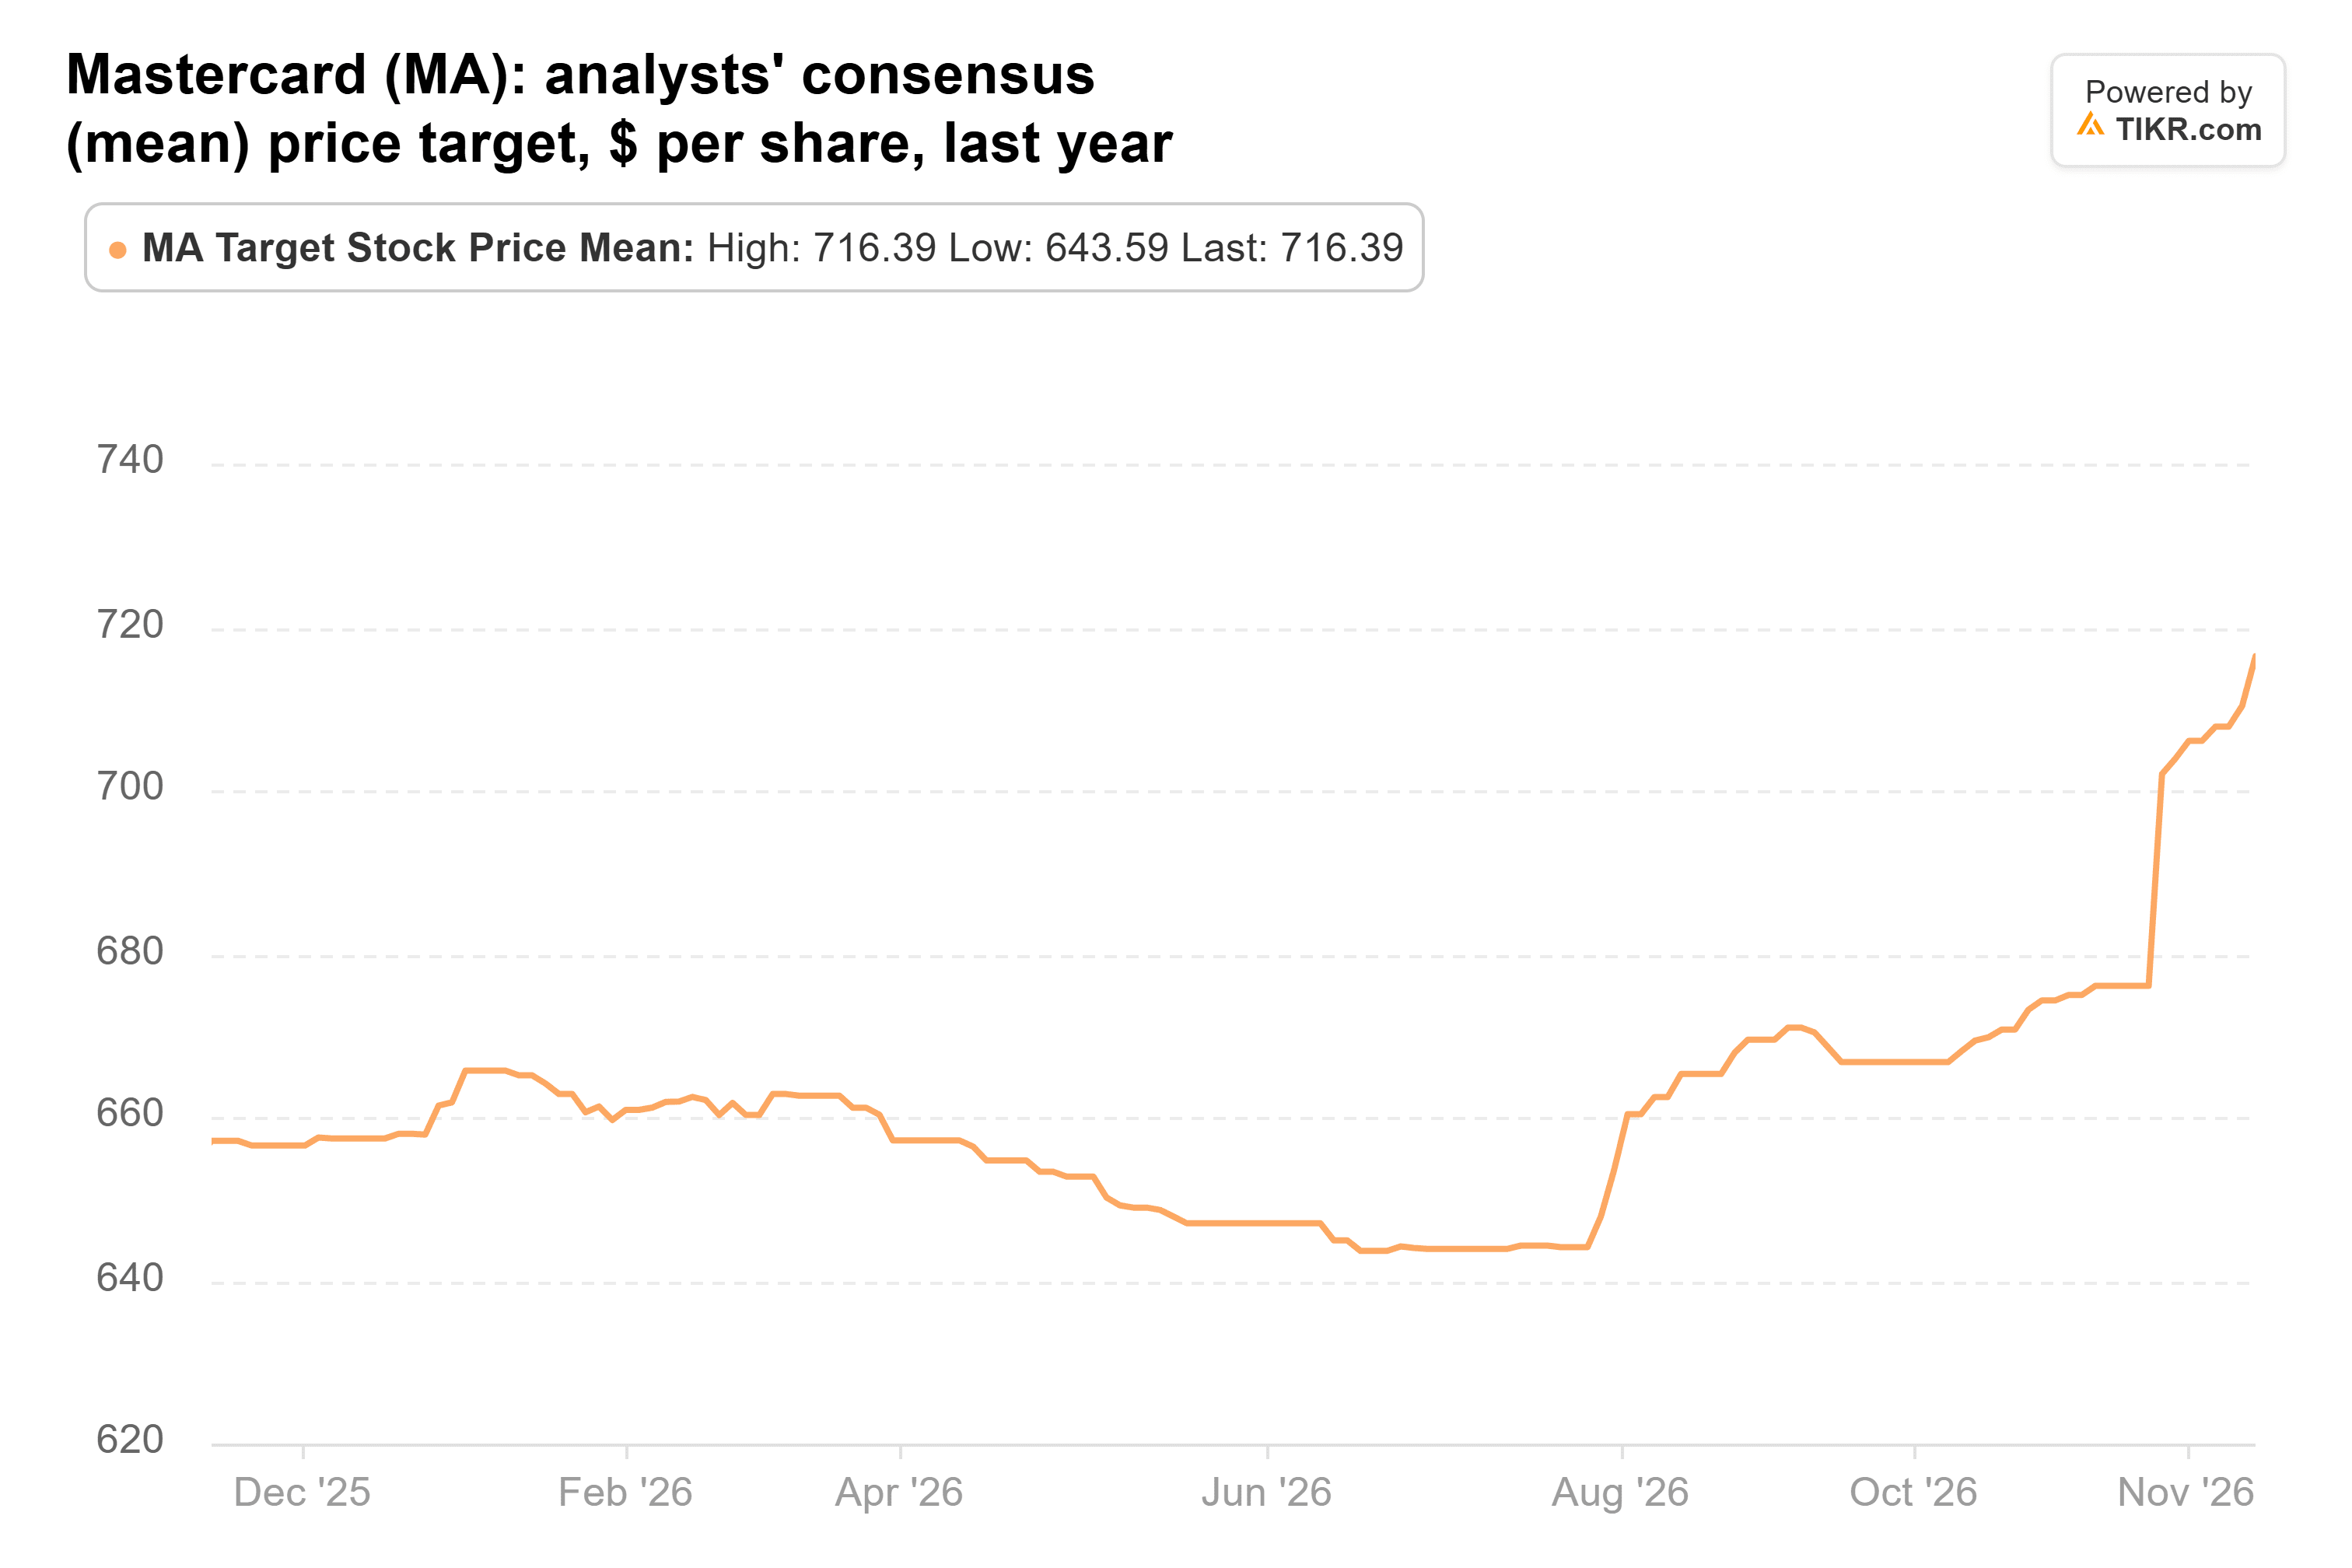
That’s 10% above the last close, with individual targets running from $550 to $800.
Where I’d follow him now
At that multiple, Mastercard is fairly priced for earnings growing in the mid-teens, so it isn’t too late to follow Ackman in. With the multiple back near its average, though, I’d expect the stock to rise about as fast as its earnings from here. The main risk is the incentives Mastercard pays banks to carry its cards. Those rose 18% in the third quarter and will take a bigger share of its fees in the fourth.
Visa has the same problem. Its client incentives jumped 21% in its fiscal fourth quarter, and it guided to only low-double-digit revenue growth for fiscal 2027.
Analysts see more upside in the laggards. The average target is 39% above the last close for Meta and 34% for Netflix. Ackman has said he bought Meta “at a huge discount” and called Netflix “an incredibly cheap stock.” Both face bigger questions, though. Meta’s third-quarter capex of $34.9 billion was more than its $32.8 billion of operating cash flow, and Netflix’s view hours grew just 2% in the first half of 2026. S&P Global’s average target is 13% above its last close, a little more than Mastercard’s.
If I were putting new money behind Ackman’s buys today, I’d still start with Mastercard. It’s the business I’m most confident will keep compounding, and I’m happy paying an average multiple for that. Pershing’s next 13F, due by Nov. 16, will show us whether it still held all five on Sept. 30. Mastercard also presents at Citi’s fintech conference on Nov. 9 and at KBW’s on Nov. 10, where management could update the fourth-quarter trends Hai warned about.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


