Key Takeaways
- Mastercard closed at $653, about 4% below its 52-week high, after a 33% climb since early May.
- Third-quarter net revenue rose 14% to $9.8 billion, with value-added services up about 19% against 11% for the payment network.
- At 29.4x forward earnings, near its five-year average, Mastercard’s $710 mean target implies only 9% upside, and Visa’s earnings are expected to grow slightly slower.
- Mastercard presents at Citi on Nov. 9 and KBW on Nov. 10, where fourth-quarter cross-border trends are the number to watch.
Mastercard (MA) closed at $653 on Friday, about 4% below its 52-week high of $682. Since early May, the stock has climbed 33%.
That’s a big run for a company growing revenue in the low teens. So the question is simple: how much good news is already in the price?
Third-quarter results on Oct. 29 gave bulls plenty. Net revenue rose 14% to $9.8 billion, and adjusted EPS of $5.31 beat the $5.16 estimate.
Visa (V) ran alongside it, and both networks rallied while chip stocks sold off. But analysts expect Mastercard’s earnings to grow a bit faster, about 16% a year through 2028 against roughly 14% for Visa.
Bill Ackman owns both. On CNBC’s Squawk Pod this week, he called Mastercard “one of the greatest businesses in the world.”
A clean beat on Oct. 29
The details were strong almost everywhere:
- Cross-border volume: up 11% on a local-currency basis
- Gross dollar volume: up 7%
- Adjusted EPS: up 21%, including a $0.16 lift from buybacks
Mastercard bought back $3.0 billion of stock and paid $763 million in dividends during the quarter. And GAAP operating margin reached 59.8%.
CEO Michael Miebach pointed to agentic commerce and the new BVNK money platform. “We’re not waiting for the future of commerce. We’re building it,” he said in the release.
Services did more of the lifting than the card network…
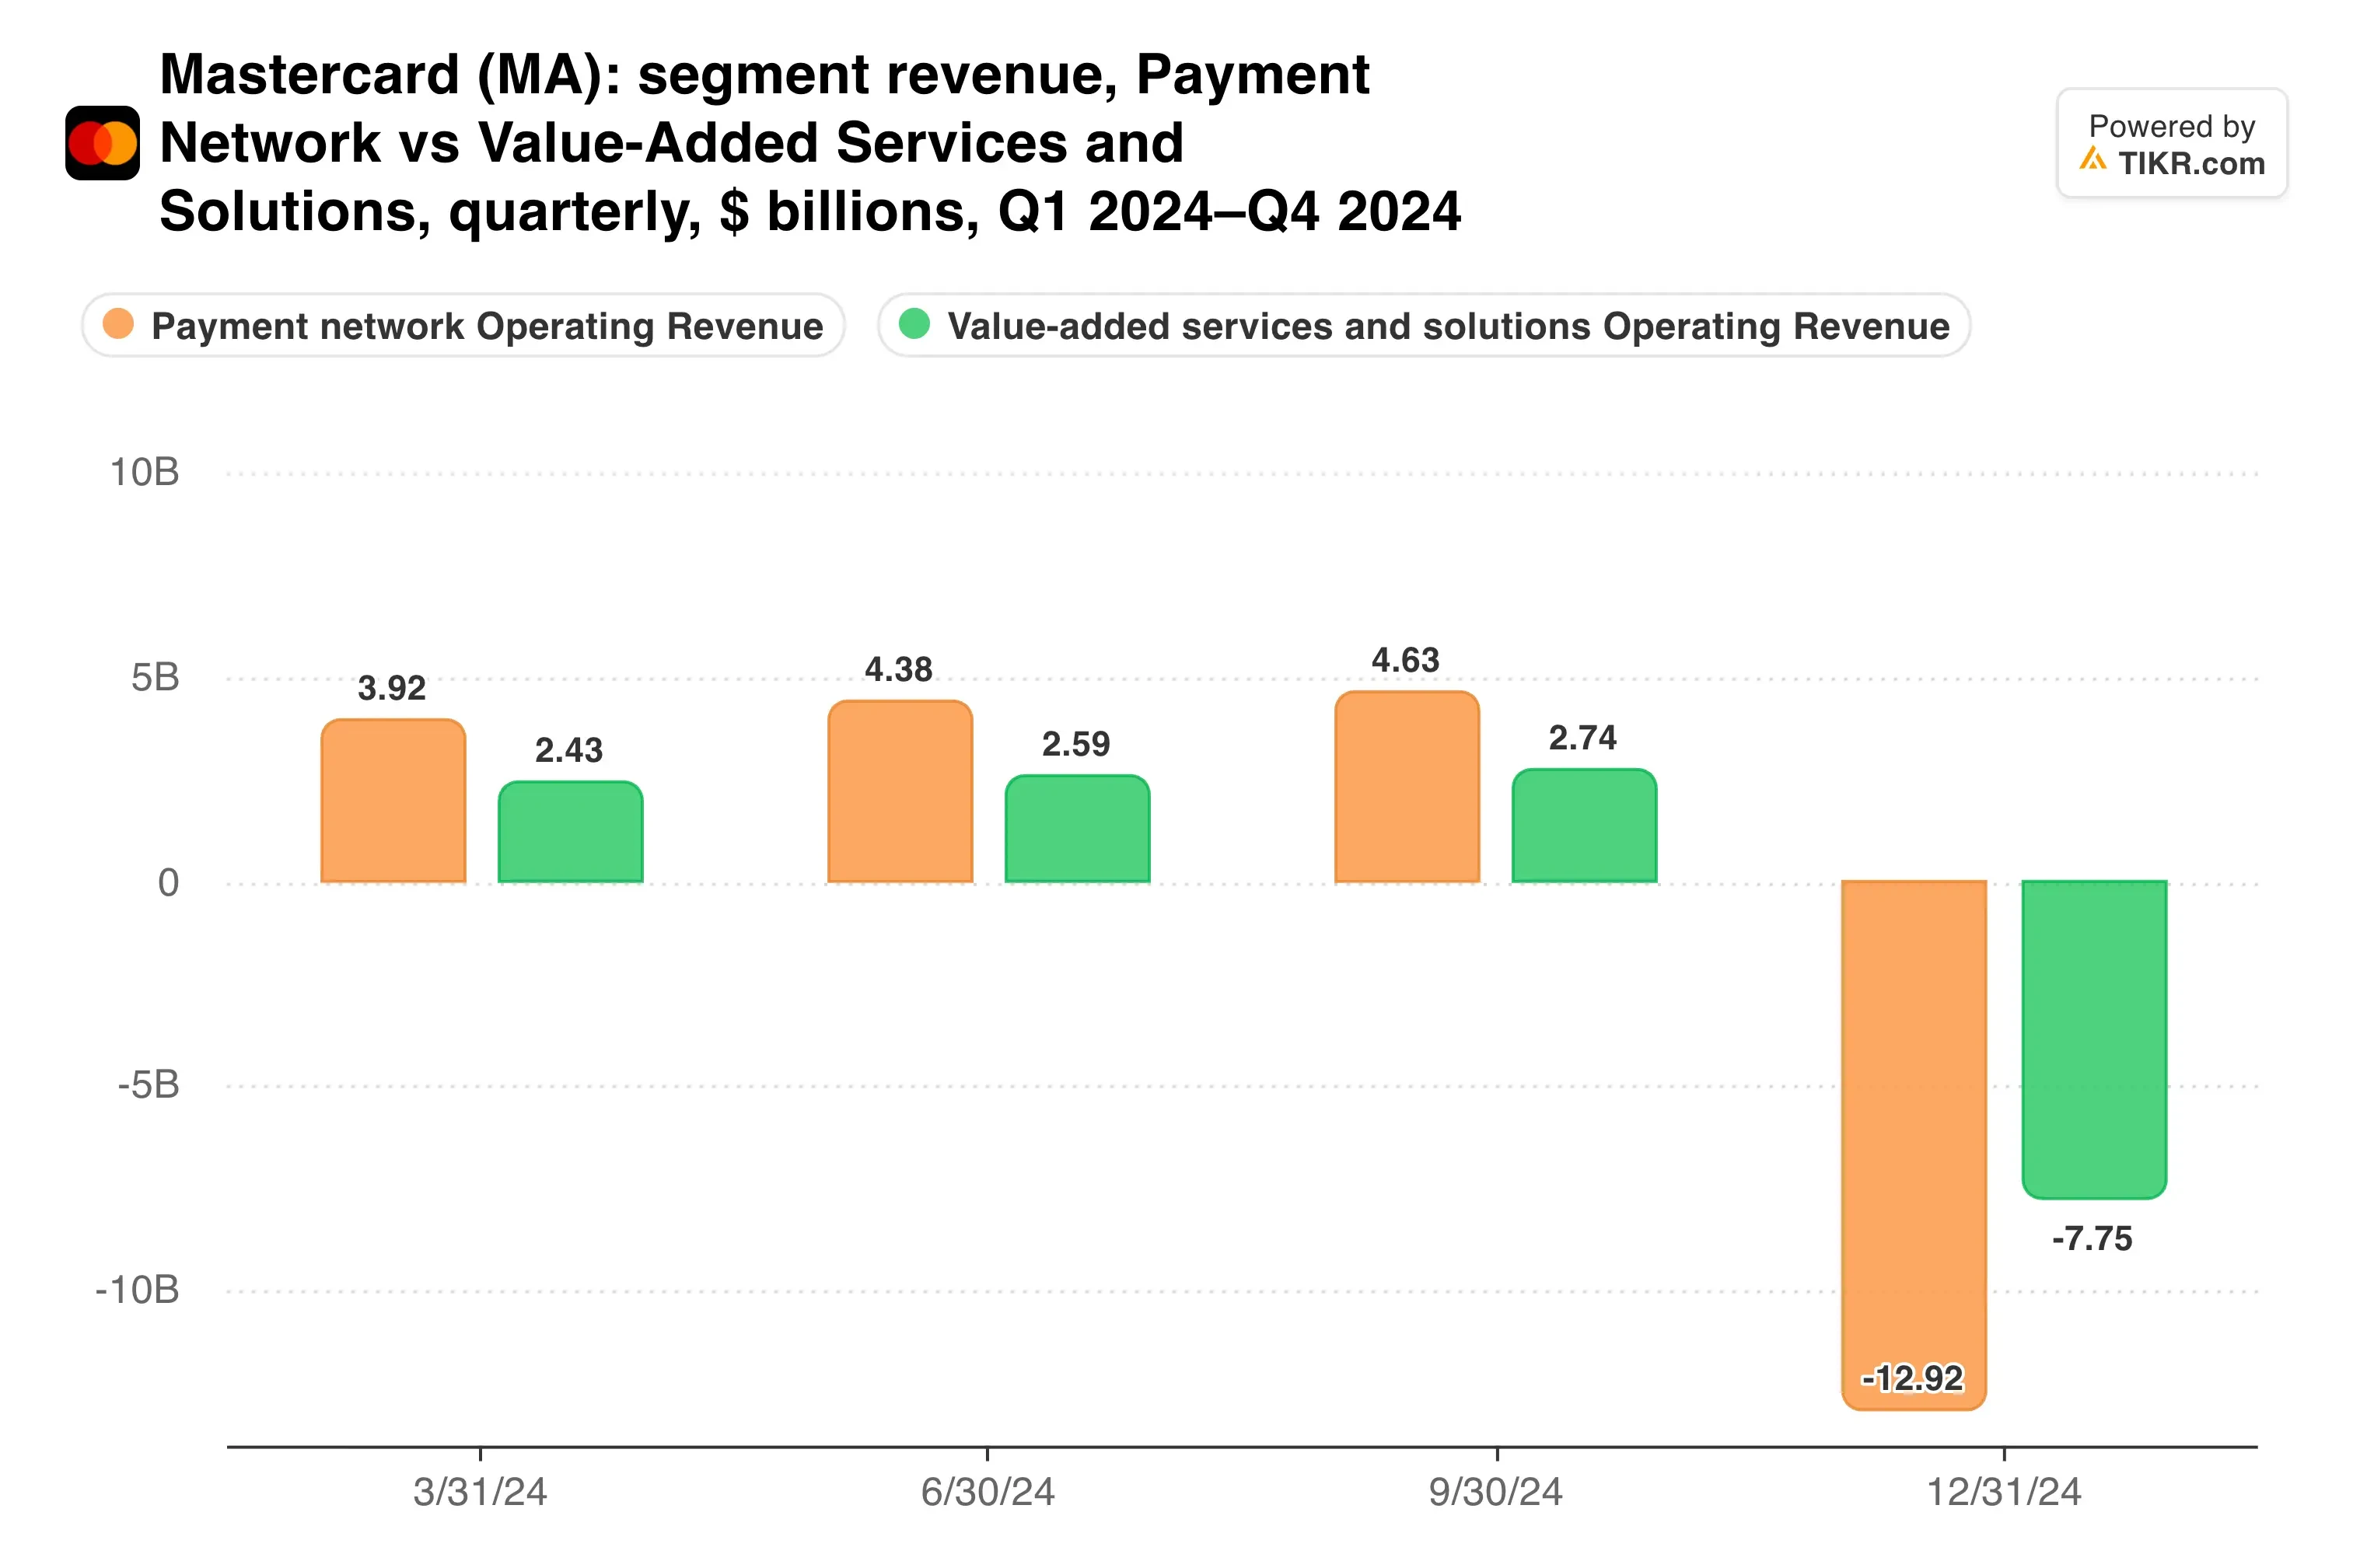
Value-added services revenue rose about 19% to $4.06 billion, while payment network revenue grew 11%.
Services carry the growth
Services now make up roughly 41% of net revenue. They also delivered more than half of the quarter’s $1.2 billion revenue increase.
That mix is the bull case. Fraud tools, data and now stablecoin rails grow faster than swipes, and they depend less on travel.
The cost side deserves attention too. Rebates and incentives paid to card issuers jumped 18% to $6.37 billion, and management expects them to rise again as a share of gross fees in the fourth quarter.
Banks have leverage, and Mastercard keeps paying up to win and keep them. Analysts still expect about $37.3 billion of revenue this year, up 14% from 2025.
Profitability has held up anyway:
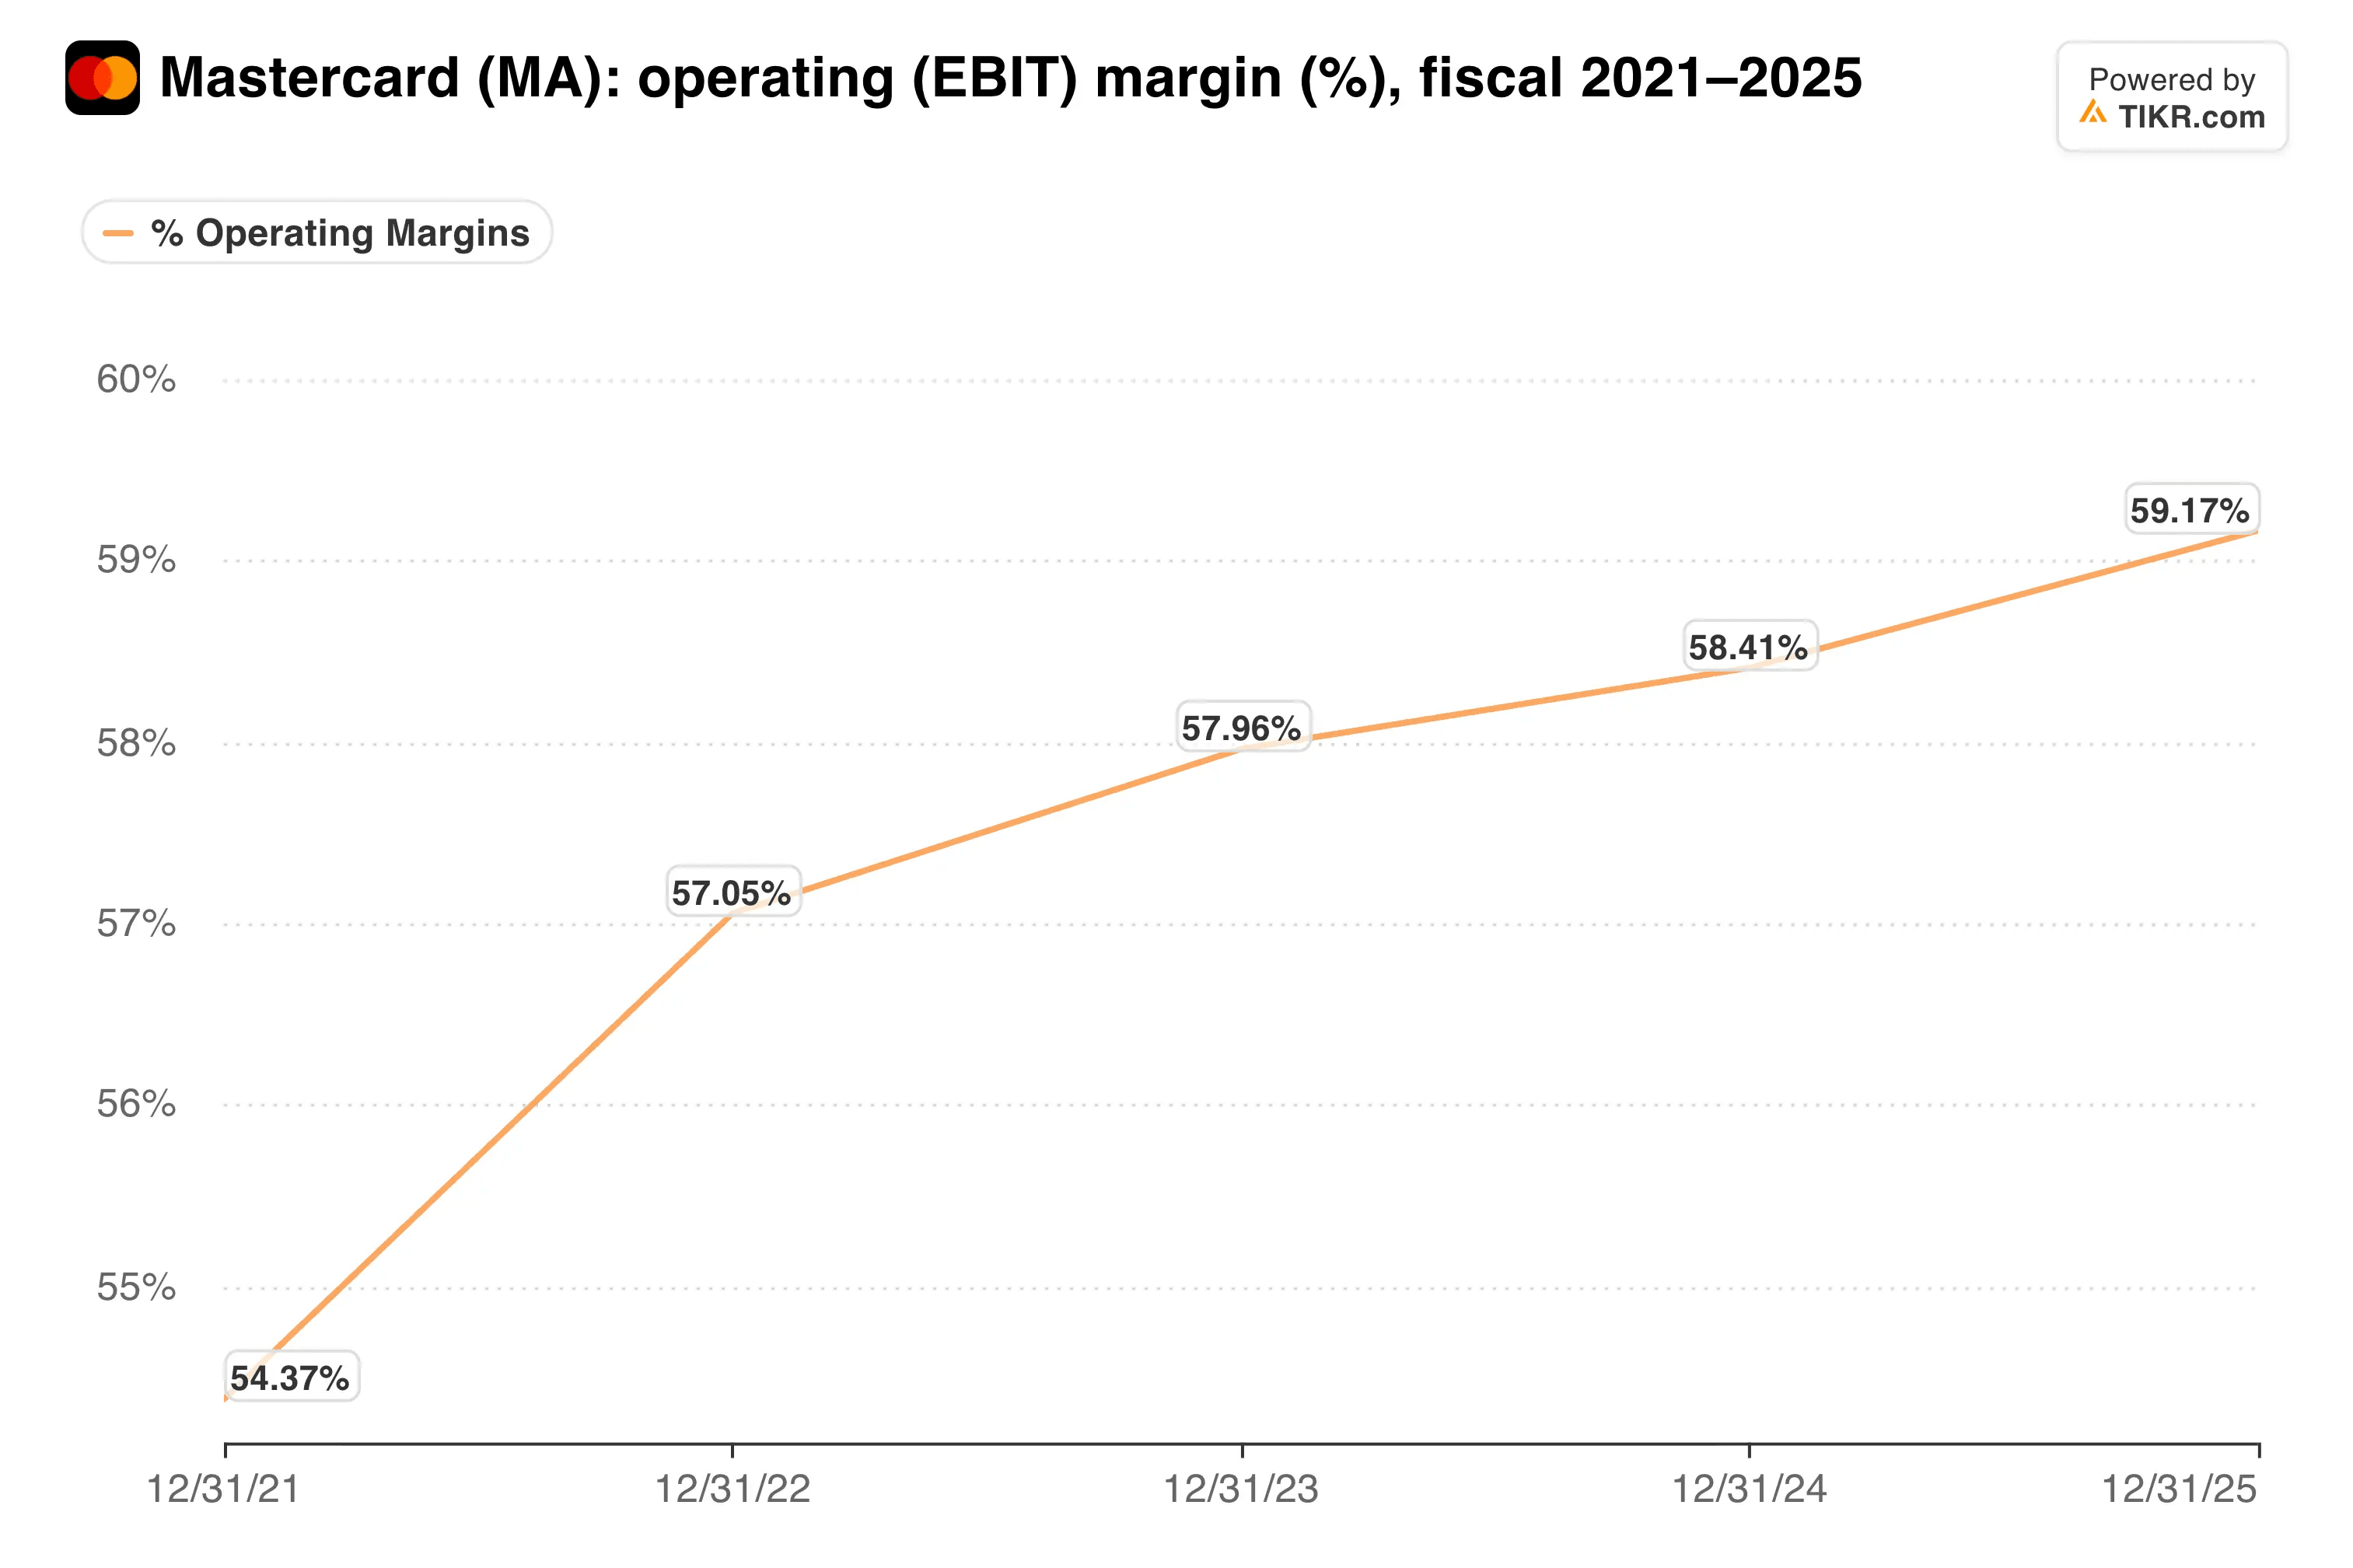
Operating margin has stayed near 60%, even with heavier incentives and acquisition costs.
TIKR tracks 39 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Paying a normal price for a great business
Mastercard now trades at 29.4x forward earnings. That’s close to its five-year average of about 31x, and well above the 23x it touched in June.
So most of the run came from the multiple recovering:
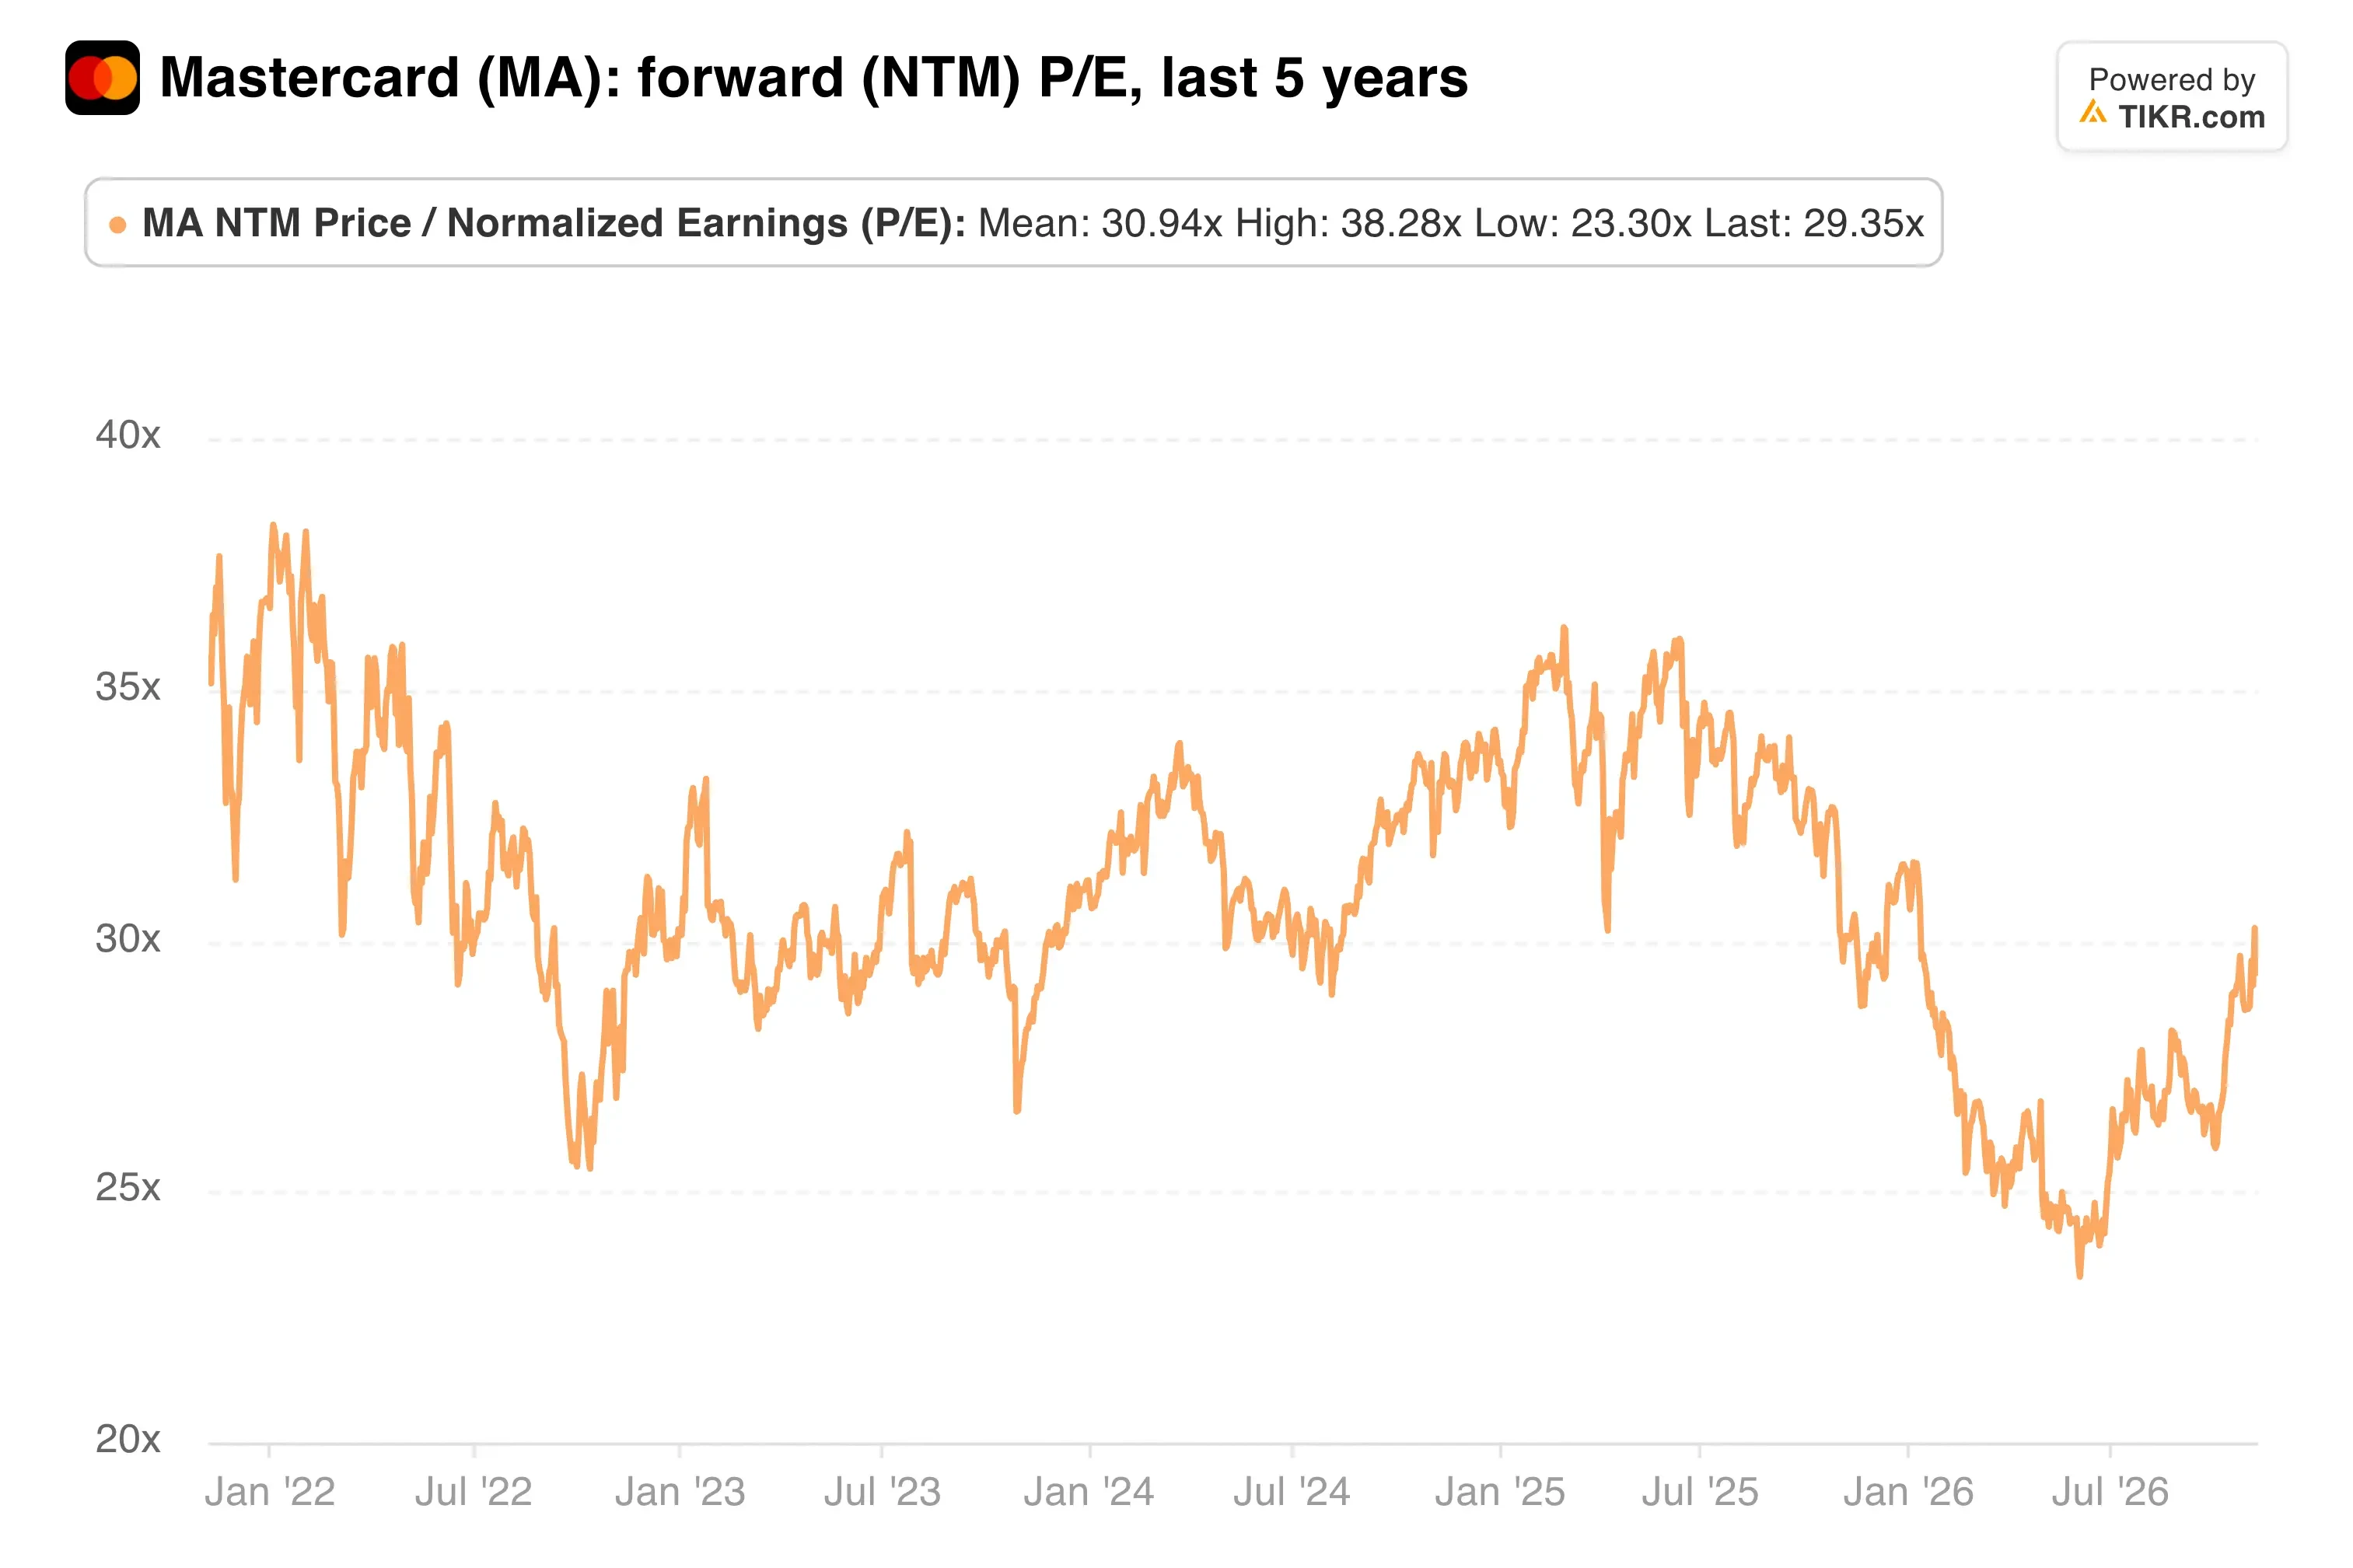
The Street’s mean target of $710 implies only 9% upside from here.
Meanwhile, CFO Ling Hai sold $5.54 million of stock this week, after a $2.68 million sale in October. Mastercard executives sell regularly, yet the timing near a high is worth noting.
My take: Mastercard earned this rally with a quarter that beat on revenue, earnings and services growth. At an average multiple, I wouldn’t sell it. But with the mean target 9% away and incentives rising, I’d wait for a pullback before adding.
The next read comes fast. Mastercard presents at Citi’s FinTech Conference on Nov. 9 and KBW’s on Nov. 10, where management could update fourth-quarter trends in cross-border spending.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!