Key Takeaways
- Moderna said on Nov. 6 that it and Merck plan to file intismeran, which cut melanoma recurrence or death risk 42% with Keytruda, this year.
- Merck splits intismeran’s profits with Moderna, and approval is only hoped for in 2027, so the stock turns on 2027 guidance due Feb. 2.
- Analysts expect 2027 EPS of $8.98, flat with 2025, while Merck trades at 17.5x forward earnings against a 14.3x five-year average.
Merck (MRK) got a firmer timeline for its melanoma bet on Nov. 6, when partner Moderna (MRNA) said the two plan to file intismeran this year. In the Phase 3 INTerpath-001 trial, the personalized therapy plus Keytruda cut the risk of recurrence or death 42% versus Keytruda alone.
The stock’s nearer question is earnings: Keytruda made 48.7% of Merck’s 2025 sales, and its U.S. compound patent expires in December 2028. Third quarters at Bristol Myers Squibb (BMY) and Pfizer (PFE) show where Merck’s next growth could come from.
At Two Years, Phase 3 Tracked Phase 2
Chief development officer David Berman said the trial enrolled more than 1,100 patients with surgically removed Stage IIB to IV melanoma:
- A 0.58 hazard ratio at the prespecified primary analysis
- 82.2% recurrence-free at two years, against 70% on Keytruda alone
President Stephen Hoge said the partners “would hope to see approval next year.”
That 0.58 sits close to Phase 2b’s 0.56 at similar follow-up. Investors weighed it against Phase 2b’s five-year 49% instead: on the Oct. 22 leak, Moderna fell 17.6% and Merck 1.76%.
Merck Already Leans on Qlex
When Merck beat estimates and raised its outlook on Oct. 29, Qlex sold $830 million, nearly 10% of Keytruda sales, while IV Keytruda fell 5% and the family grew 6% to $8.6 billion. Bristol saw the same shift: IV Opdivo fell 6% to $2.37 billion, while Opdivo Qvantig rose to $334 million from $67 million a year ago. (Halozyme’s German patent case against Merck’s version goes to appeal on Nov. 19.)
Every intismeran patient stays on Keytruda. The catch: Merck splits intismeran’s profits evenly with Moderna.
TIKR Tracks 28 Analysts on Merck. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Merck, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Merck’s Analyst Ratings
Analysts Expect a Flat 2027
Merck raised 2026 non-GAAP EPS guidance to $2.77-$2.82, from $2.66-$2.76, but about $550 million of third-quarter sales came from purchase timing, and $250 million of that reverses in 2027.
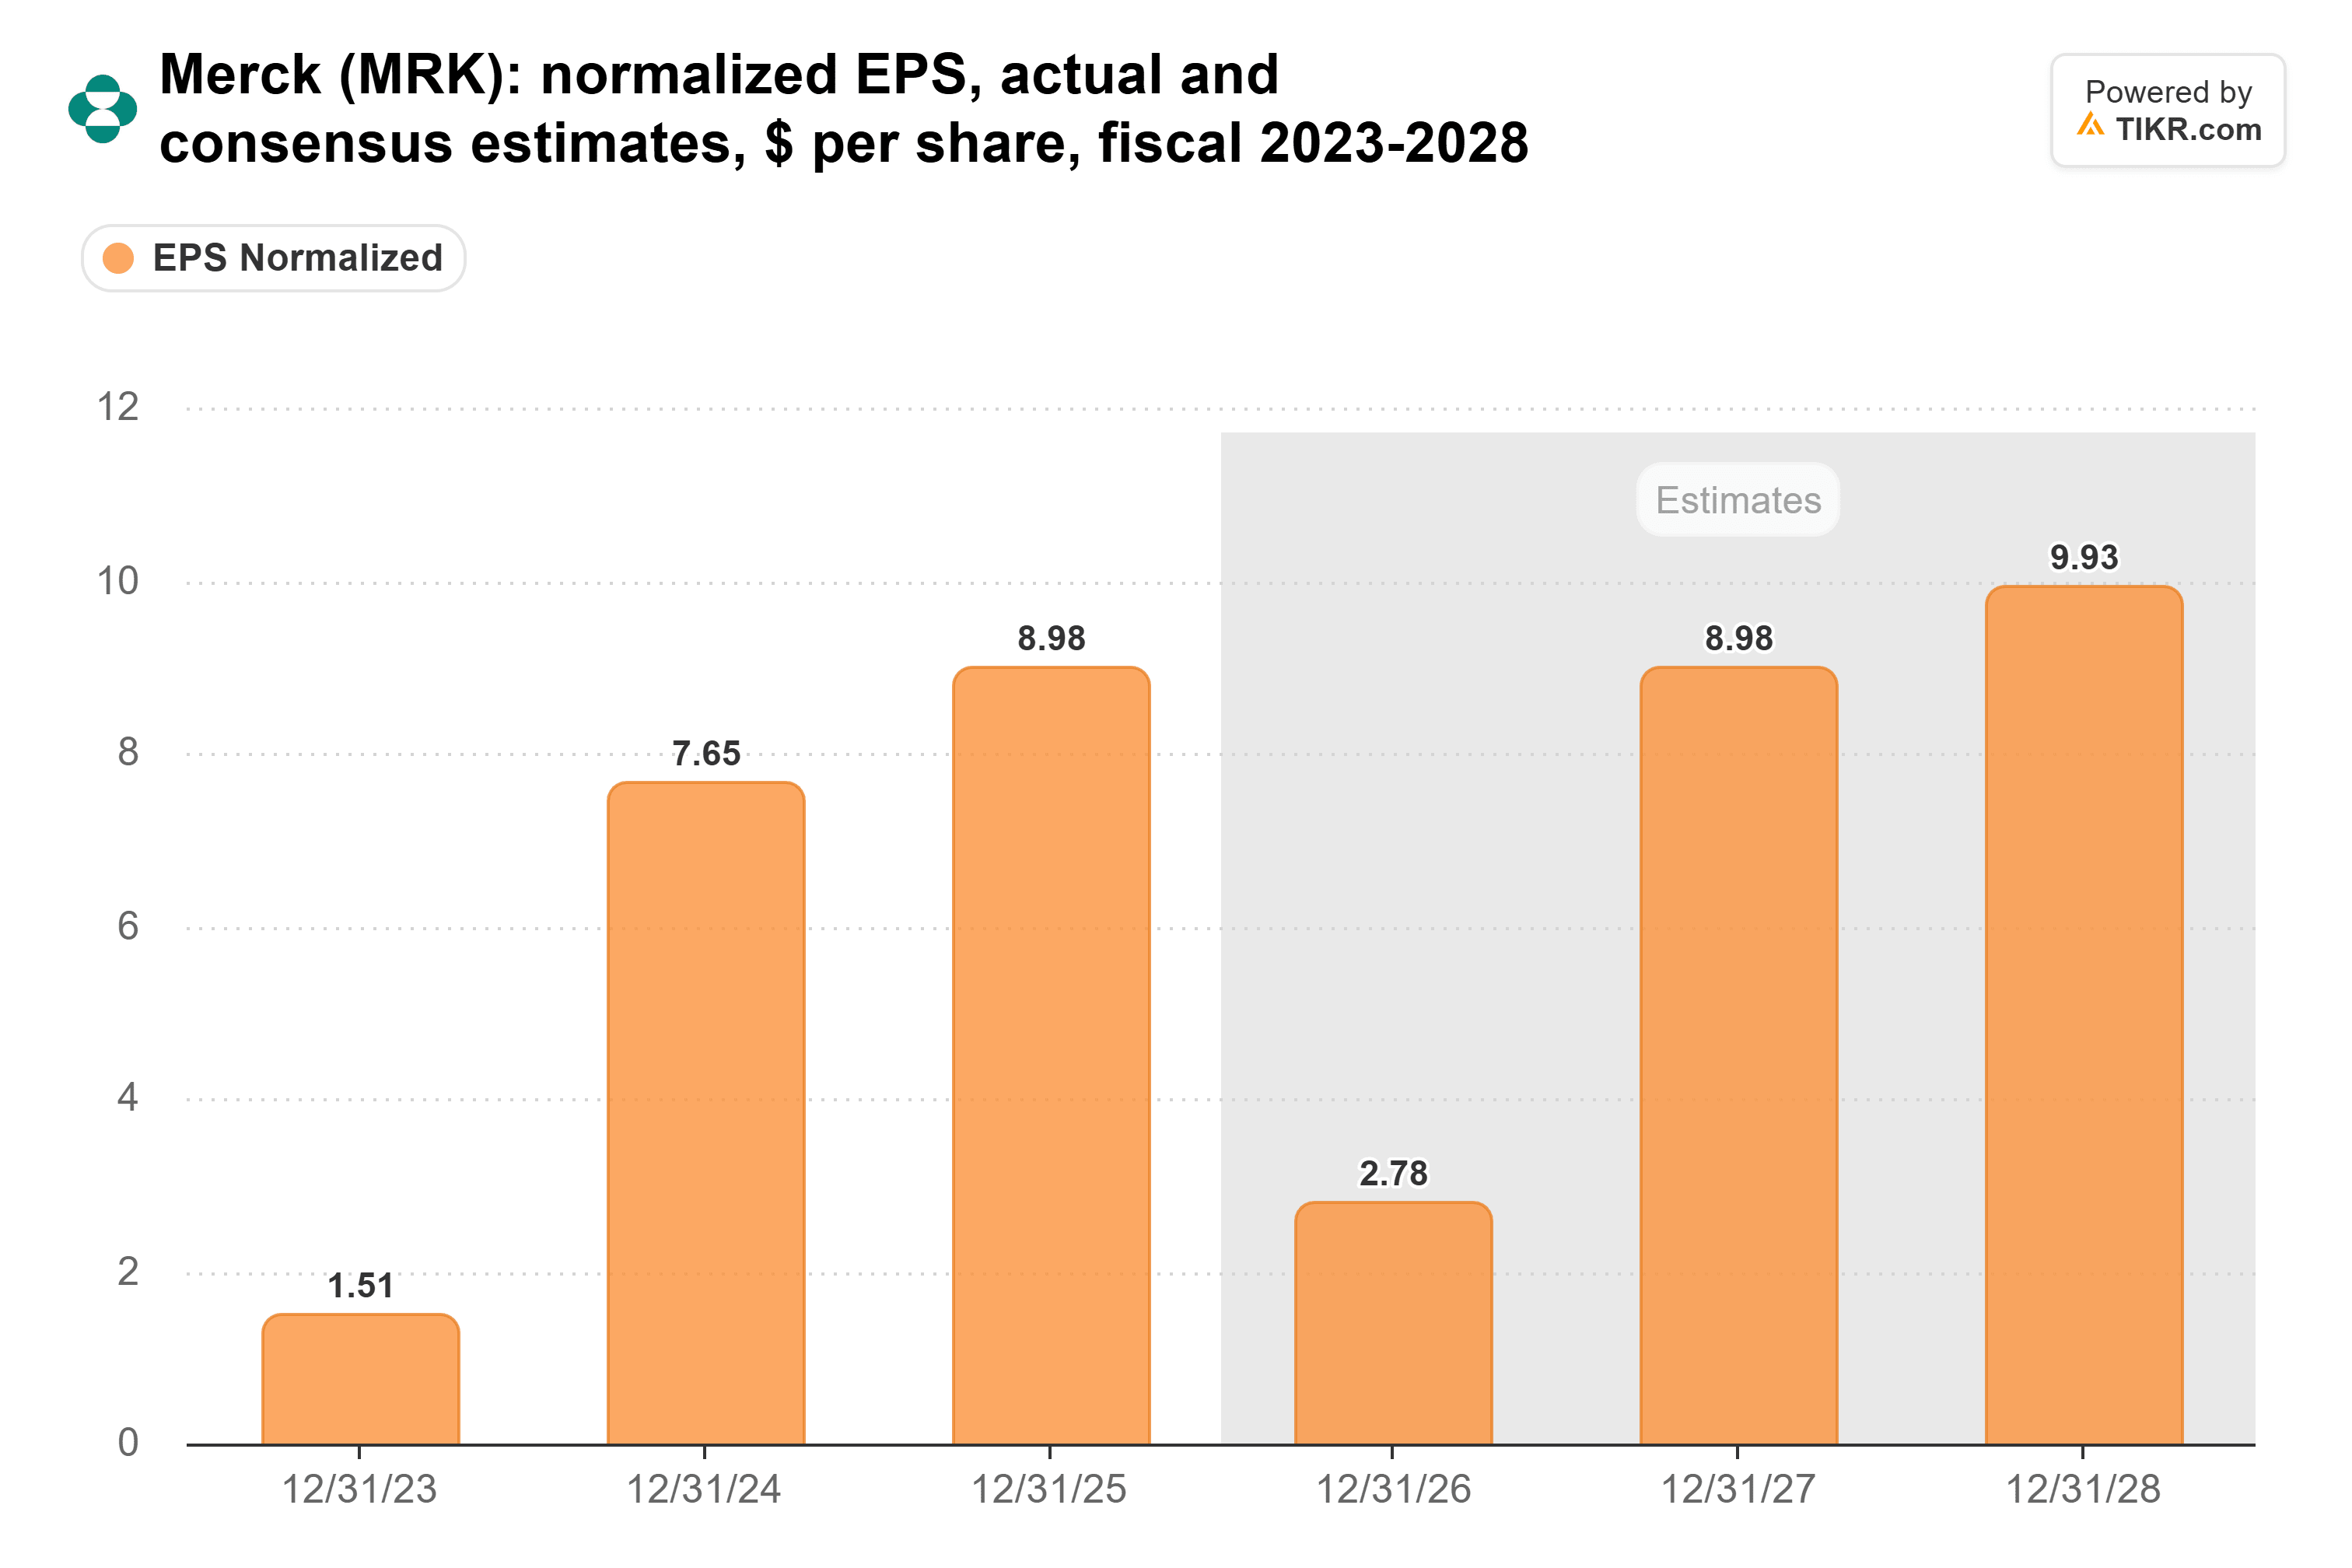
(2026’s dip is mostly $5.93 a share of charges for buying Cidara and Terns.)
The $8.98 consensus for 2027 matches 2025’s actual, down from $9.26 in late October. Merck expects underlying operating expenses to grow mid-to-high single digits in 2027, though a Keytruda royalty rolling off should lift gross margin.
Consensus has revenue rising every year, from $65.0 billion in 2025 to $73.7 billion in 2028, with no drop yet for Keytruda’s patent loss:
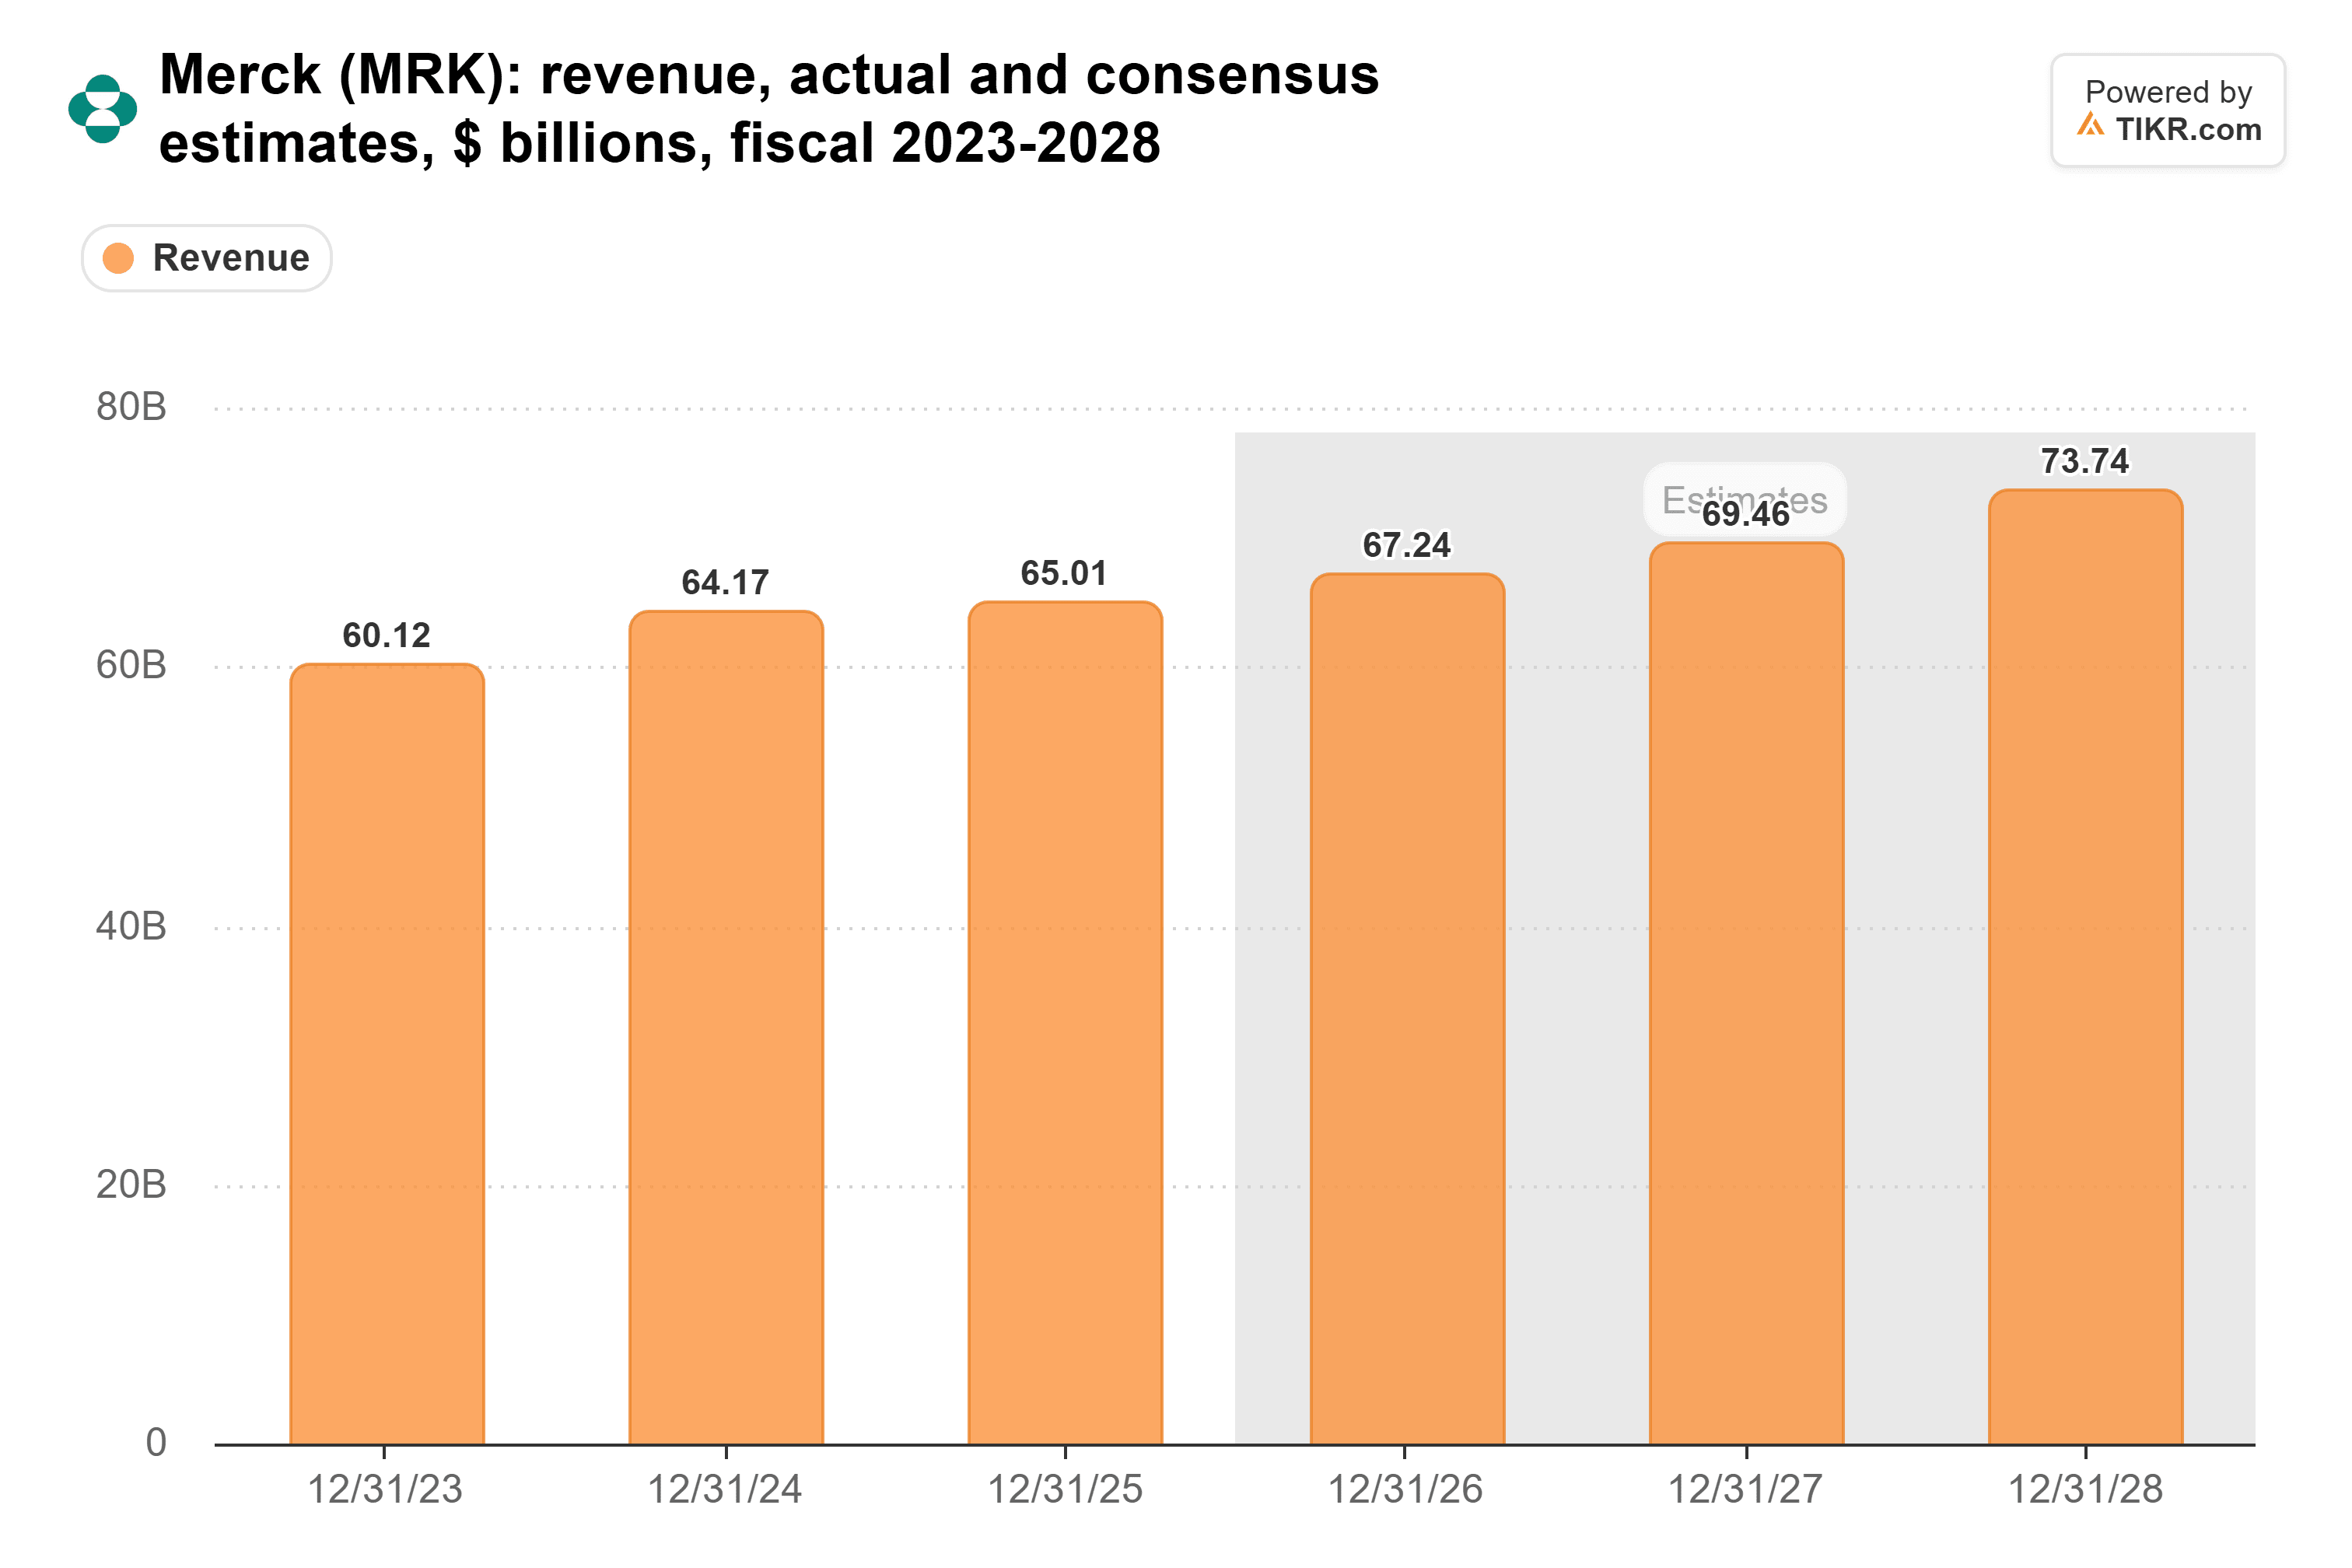
That rise depends on newer products. Pfizer’s Prevnar family fell 10% operationally in the third quarter, partly on adult share erosion. My read: Merck’s Capvaxive, its adult pneumococcal vaccine, is taking some of that share.
Merck’s February 2 Guide Has to Clear $8.98
Merck trades at 17.5x forward earnings, above its five-year average of 14.3x:

(2026’s deal charges inflate part of that premium until they roll out of the forward estimate.)
Merck gives 2027 guidance with its fourth-quarter report on Feb. 2. To hold a premium multiple, that guide needs to land at or above $8.98. Anything below would leave the stock expensive against earnings that haven’t grown in two years.
The melanoma data makes Merck’s 2030s look better, but it adds little to 2027, and at 17.5x there’s not much room for a soft guide.
So What Is Merck Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Merck could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!