Key Takeaways
- Mastercard reports third-quarter results on Thursday, Oct. 29, after a run that took the stock to a record.
- Its forward P/E has climbed from a five-year low of 23x in June to 29x, which is still below its five-year average of 31x.
- Analysts expect 2026 normalized EPS of $19.95, 17% above 2025, so the second half needs about 13% EPS growth after 22% in the first half.
- The quarter has to show margins holding above 60%, rebates under control, and full-year EPS estimates moving up.
Mastercard (MA) stock hit a record this month. On Thursday, Oct. 29, investors finally get hard numbers to check it against.
Mastercard reports its third-quarter results before the open, with a call at 9 a.m. ET. For anyone who rode Mastercard’s run of more than 12% in a month, it’s decision time: take profits, or add before the report?
Here’s what the quarter has to show.
The multiple still has room
Start with the price. Mastercard’s forward P/E hit bottom at 23x in early June, its lowest in five years. The run has lifted it back to 29x, which is still below its five-year average of 31x.

(It’s also nowhere near its January 2022 peak of 38x.)
So most of the record comes from earnings growth, with a partial bounce in the multiple on top. That means the earnings have to keep coming.
Estimates have to keep rising
Analysts expect normalized EPS of $19.95 for 2026, up 17% from 2025’s $17.01, and $23.07 for 2027:

The first half did a lot of the heavy lifting, with adjusted EPS up 22%. To reach the full-year consensus, second-half EPS has to grow about 13%.
That’s doable. Management guided third-quarter net revenue growth to the high end of a low-double-digit range (currency-neutral, excluding acquisitions), after 12% in each of the first two quarters. Services grew 18% currency-neutral in both.
But the 2026 estimate has crept up only 1.5% since the end of June. A quarter that pushes it higher gives a 29x multiple something new to stand on. A flat estimate gives holders a reason to cash in their gains.
TIKR tracks 40 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Margins have to hold above 60%
Mastercard’s operating margin has widened every year since 2021, from 54.4% to 59.2% in 2025.
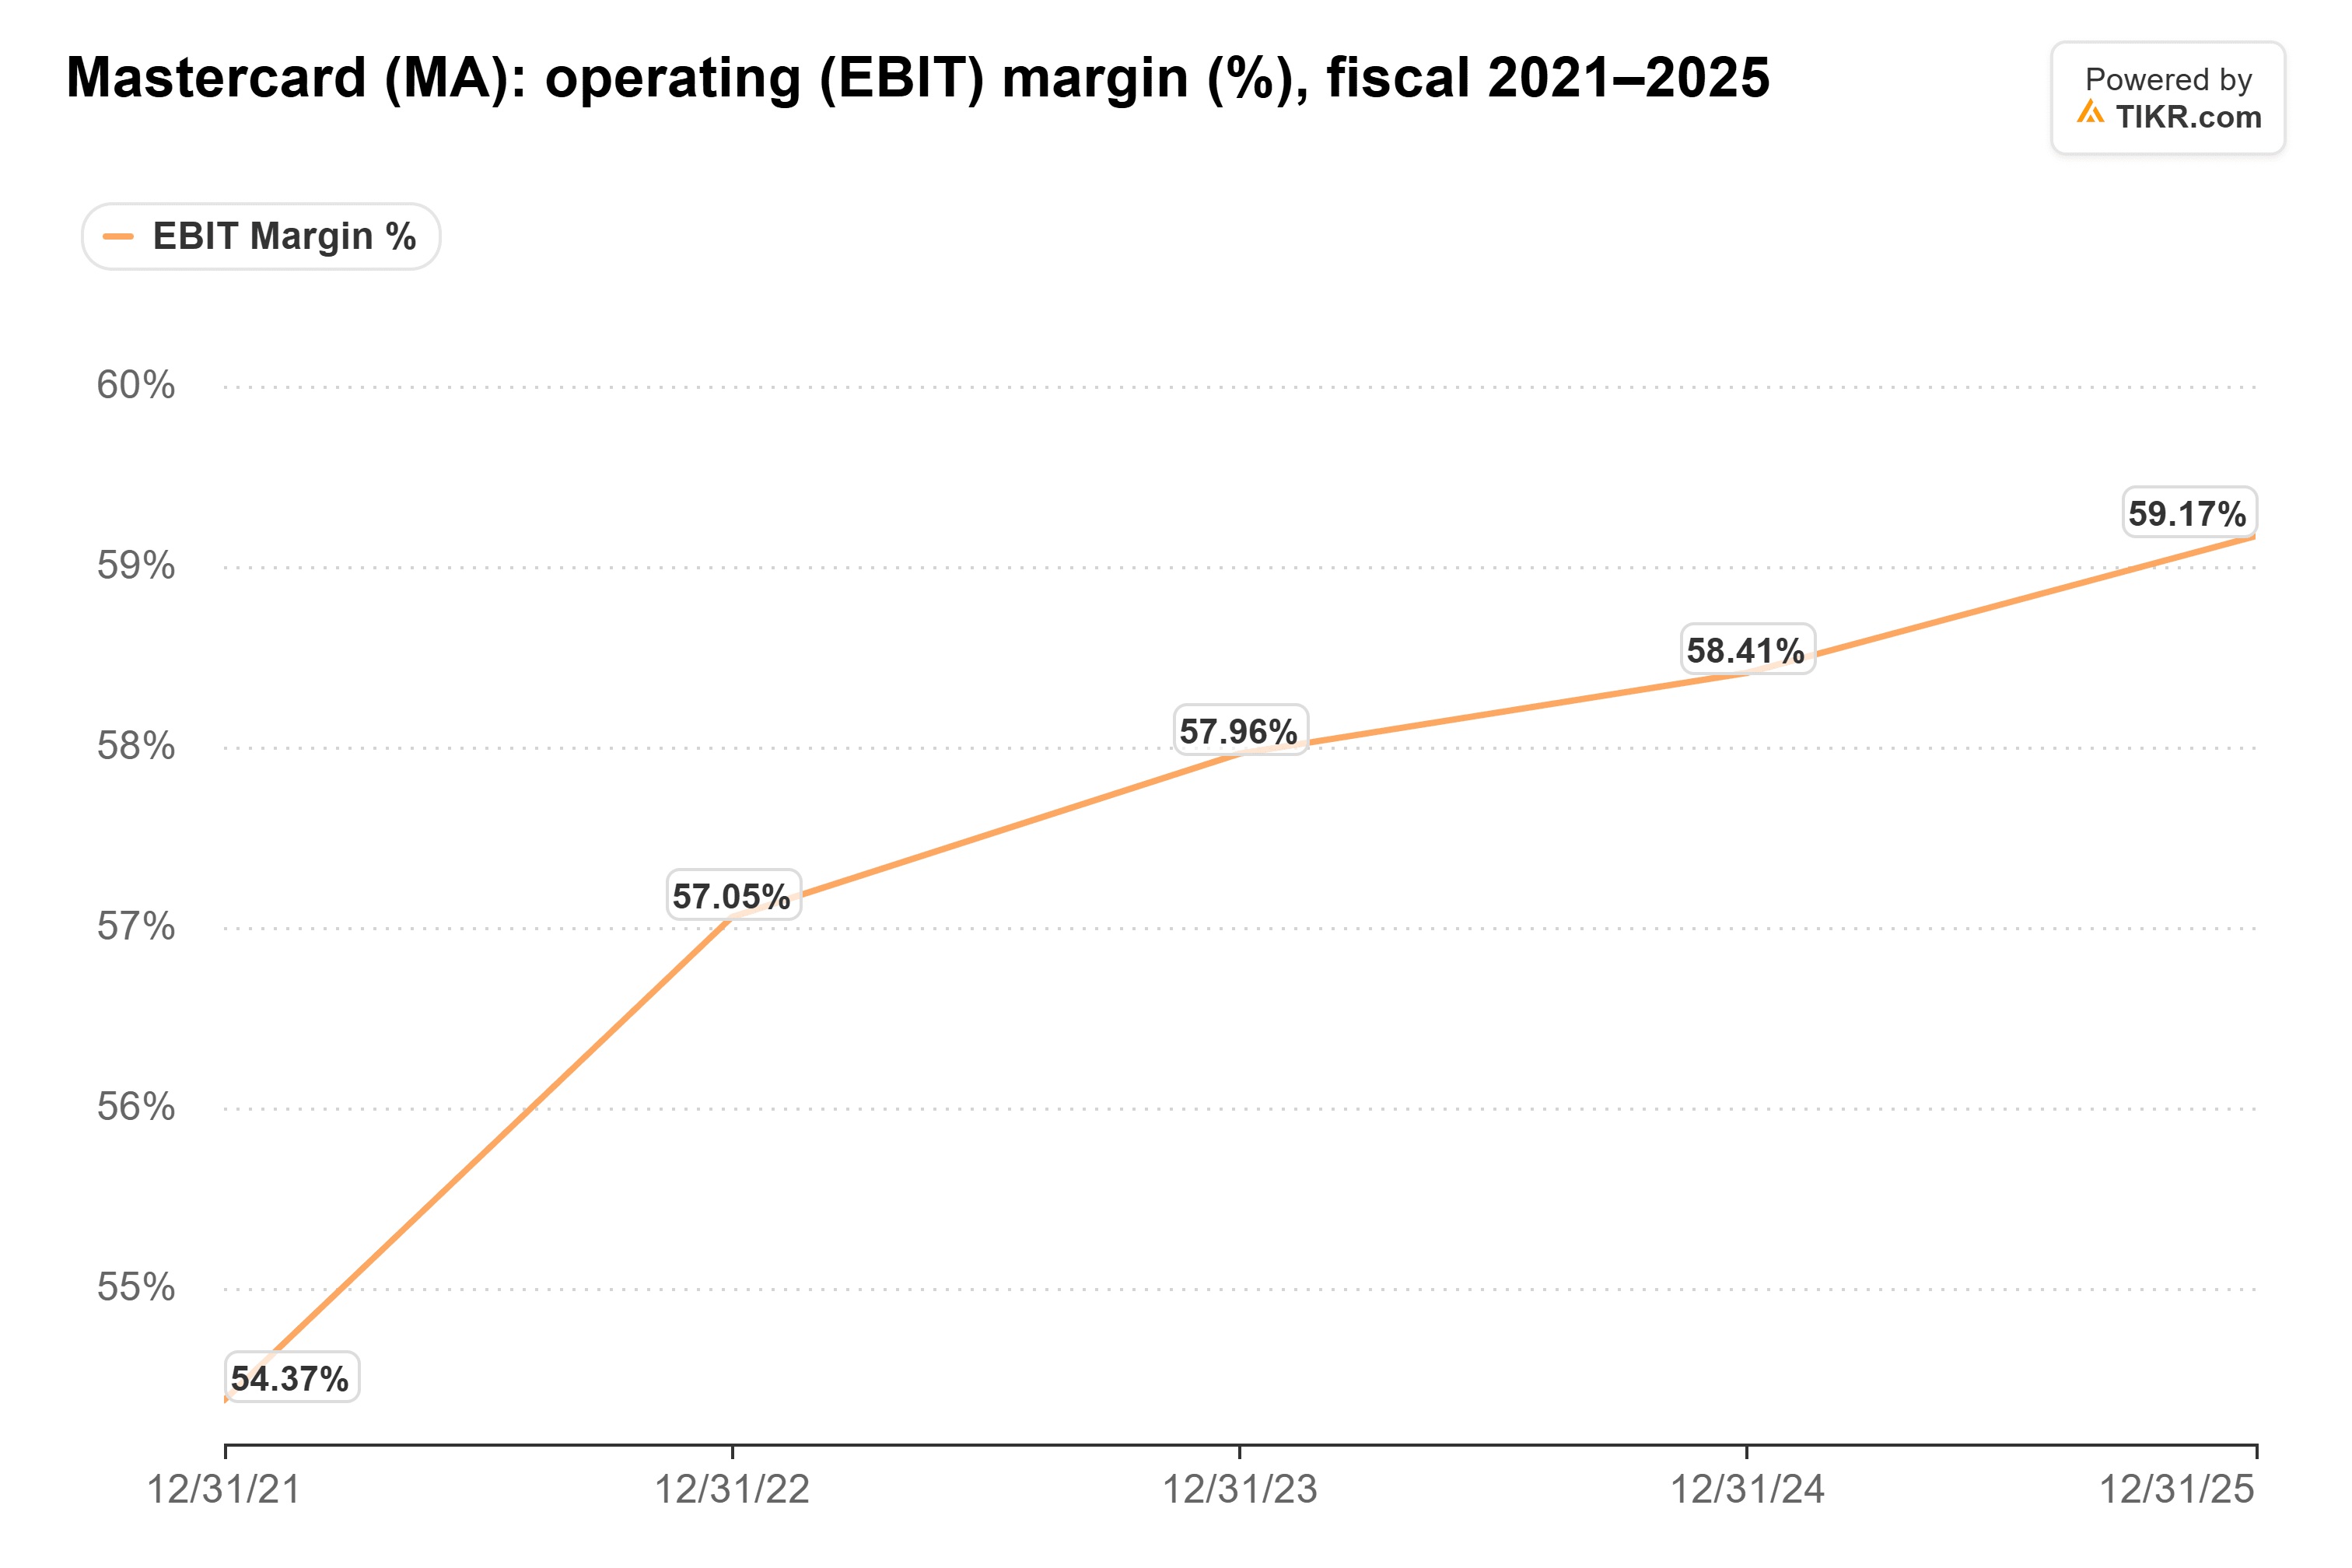
And it kept widening this year. The adjusted operating margin hit 61.0% in the first half, up from 59.6% a year earlier.
The pressure point is rebates and incentives, the money Mastercard pays banks to win and keep their card portfolios. They took 52.4% of gross network fees in the second quarter, up from 49.9% a year earlier, and management expects that share to rise slightly again in the third. A bigger jump than that would eat into the margin the EPS estimates lean on.
Washington and stablecoins can drown out a good quarter
Of course, the stock doesn’t trade on EPS alone. President Trump backed the swipe-fee bill again on Oct. 19, and the Nov. 3 midterms fall five days after the report. Mastercard’s BVNK deal, worth up to $1.8 billion, has also given investors a stablecoin story to price in. A clean quarter settles neither one.
A bar Mastercard can clear
My take: Mastercard should clear it. Management has already guided to the high end of its range, margins are still widening, and the multiple sits below its own five-year average, so the stock doesn’t need a blowout. It needs a quarter that keeps the second half on pace for 13% EPS growth and nudges the full-year estimate up.
The number I’d watch most closely is rebates. If their share of fees climbs well past 52.4%, margin growth stalls. And whatever Thursday’s report says, Nov. 3 could move the stock more.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!