Key Stats for JPMorgan Stock
- Current Price: $332.38
- Target Price (Mid): ~$447
- Street Target: ~$374
- Potential Total Return: ~35%
- Annualized IRR: ~7% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
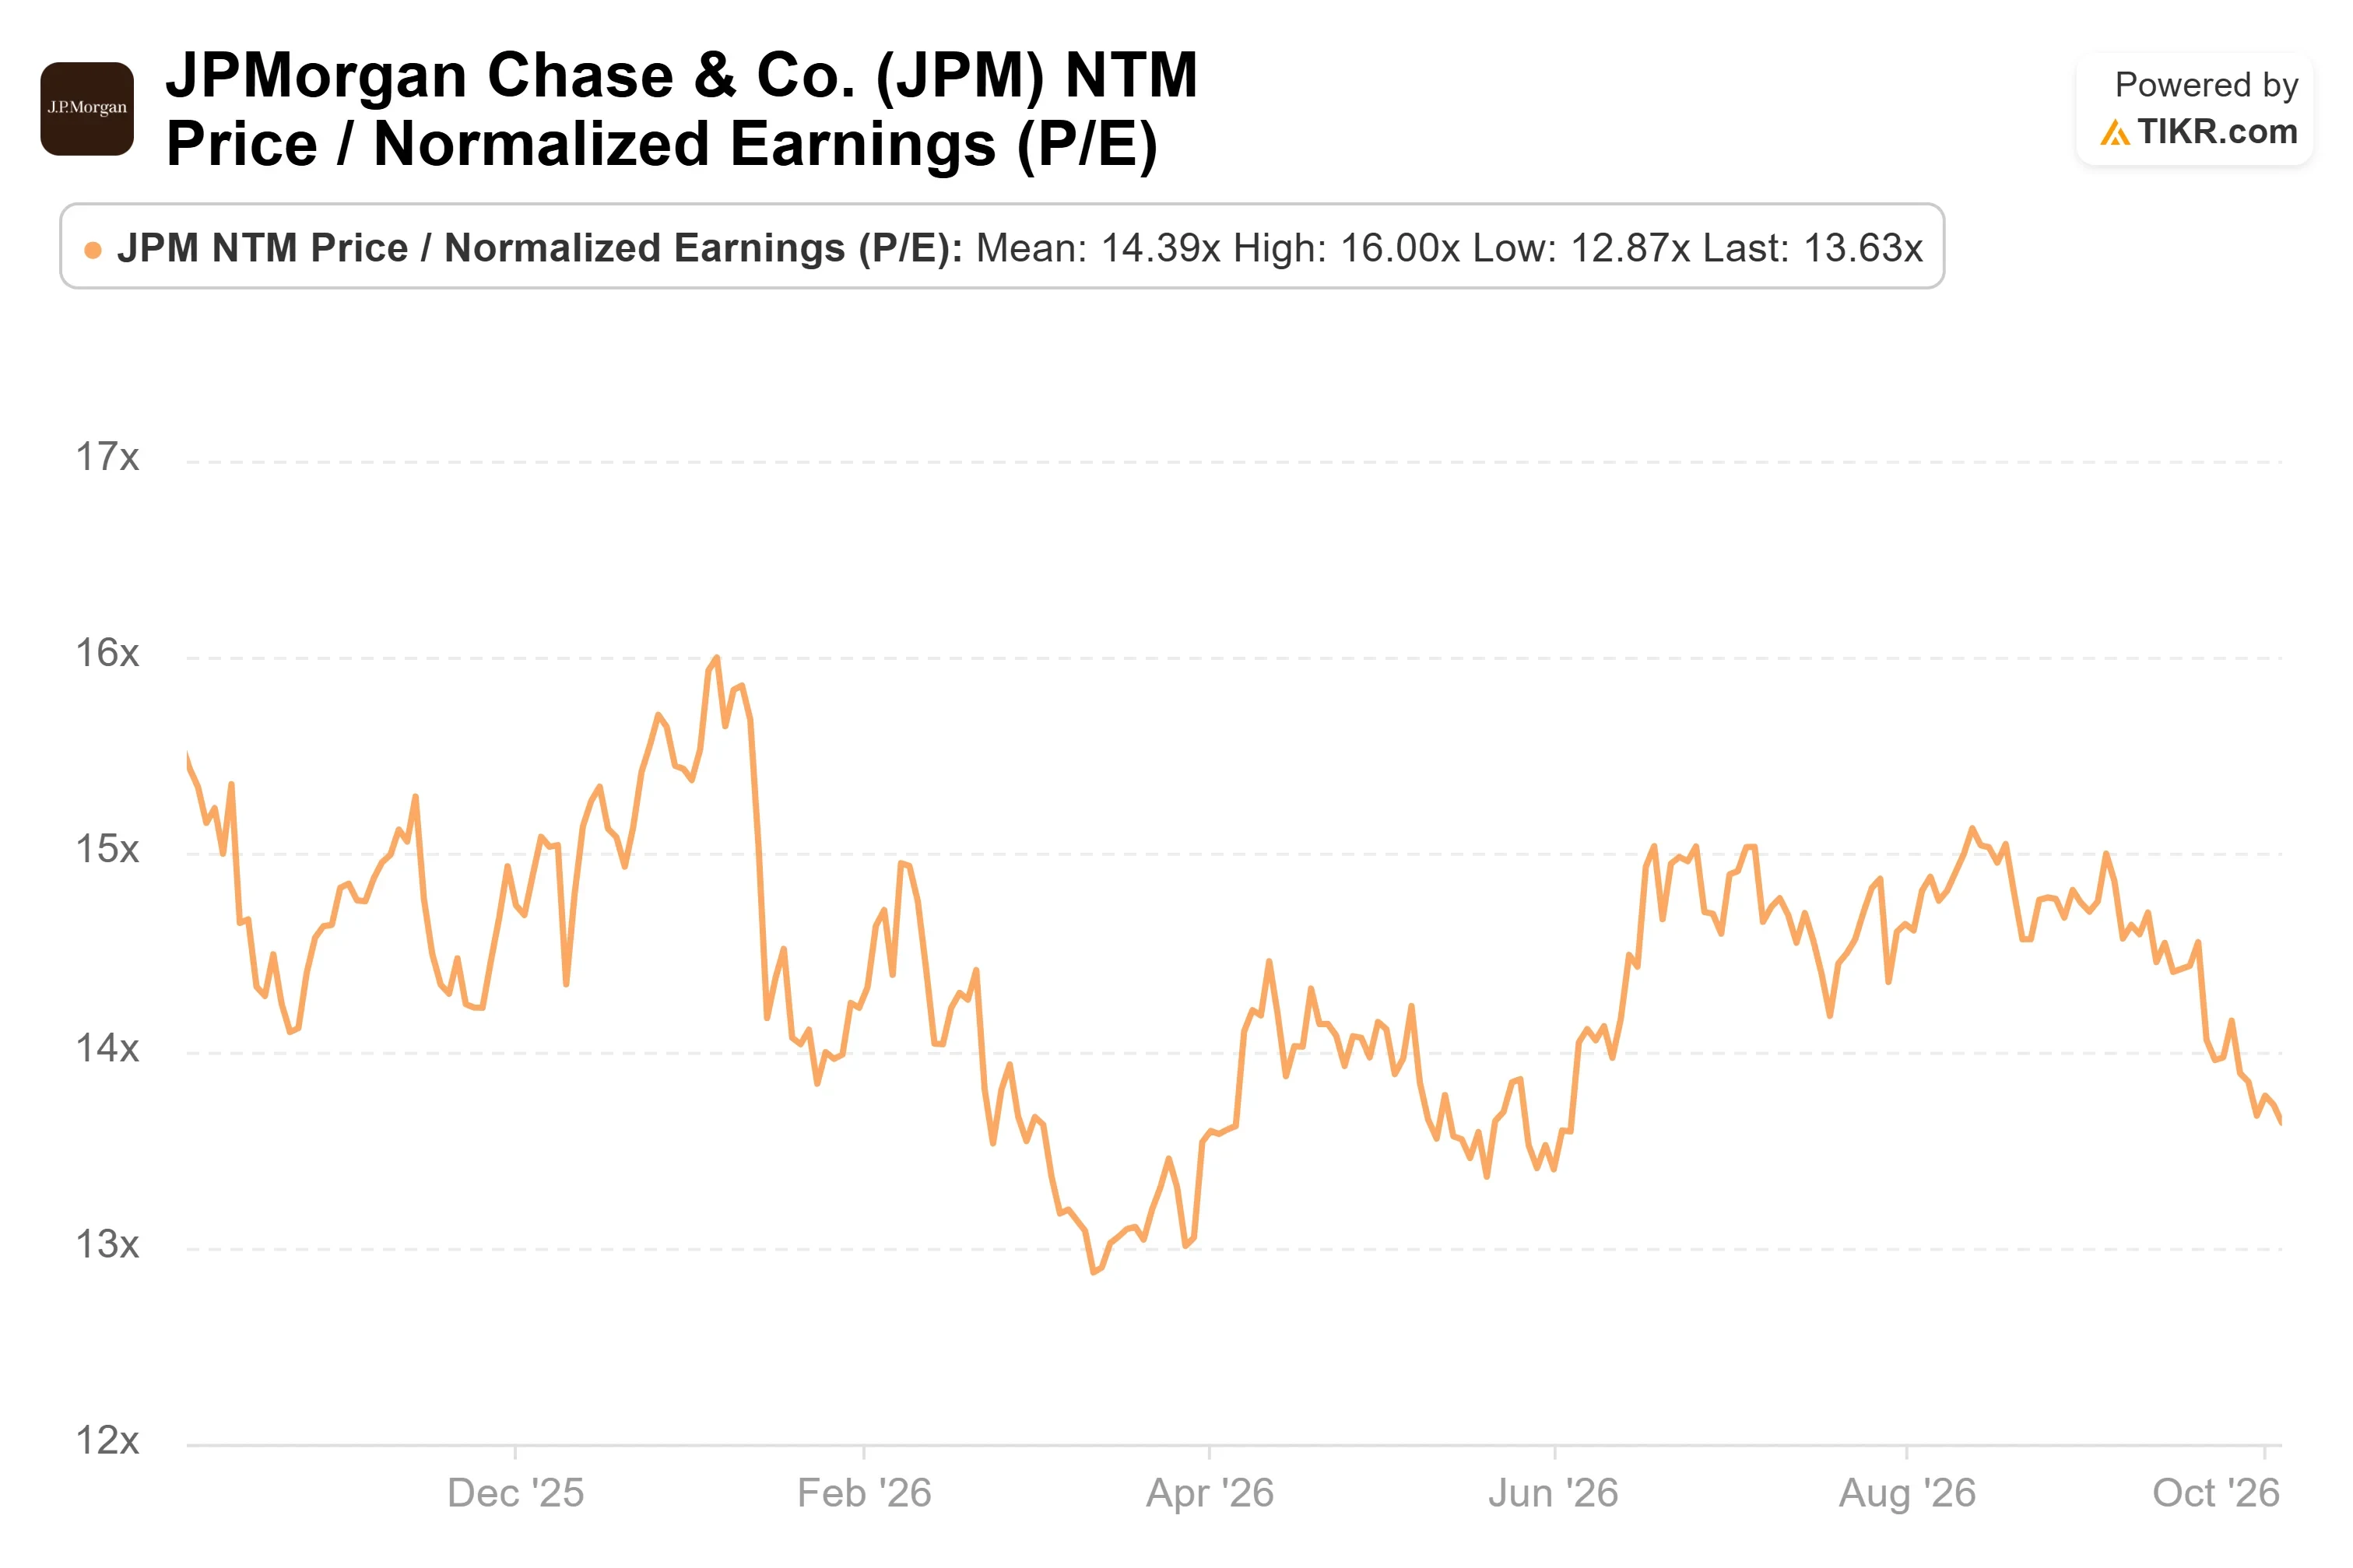
JPMorgan Chase (JPM) closed at $332.38 on October 5, up just 3.2% from $322.22 at the end of 2025, even as analysts kept lifting its earnings outlook. TIKR’s next-twelve-months normalized EPS estimate rose from around $21 to around $24 over the same stretch, partly because the 12-month window now reaches into 2027. As a result, the forward P/E shrank about 11%, to around 14x.
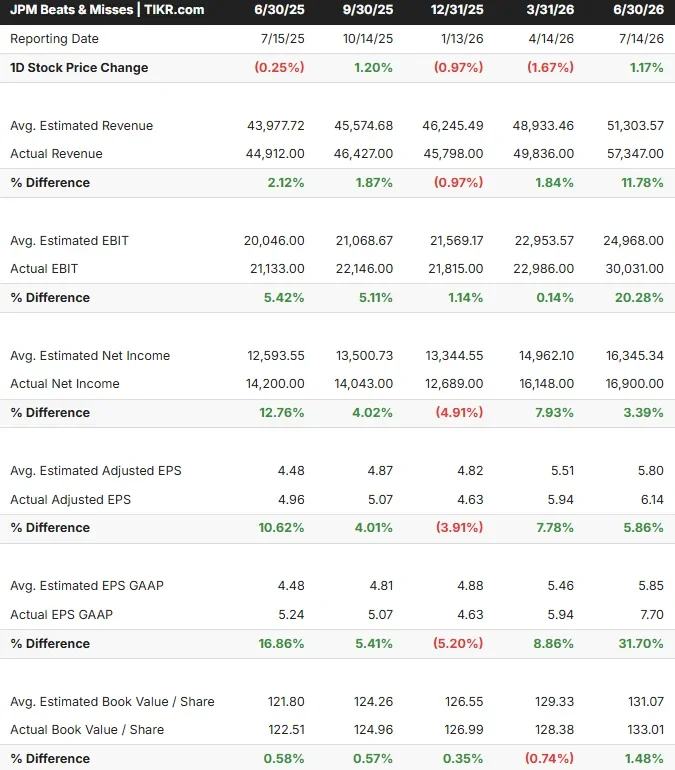
On October 5, BofA cut its target to $400 from $420, and UBS cut to $395 from $400. Both kept Buy ratings, and both targets remain above the ~$374 Street mean, where TIKR shows 13 Buy or Outperform ratings against 11 Holds. JPMorgan’s investor relations materials confirm third-quarter results before the open on October 13.
See historical and forward estimates for JPMorgan stock (It’s free!) >>>
Petno Guided Q3 Up as Bank of America Guided Down
At Barclays’ financial services conference on September 15, Doug Petno, Co-President of JPMorgan and CEO of its Commercial & Investment Bank, guided third-quarter investment banking fees and Markets revenue up mid- to high teens year over year, absent a major market disruption. On September 14, Bank of America (BAC) CEO Brian Moynihan said his firm’s investment banking fees were on pace to fall 10% to 20%.
TIKR’s consensus already expects a strong quarter: adjusted EPS around $5.90, up around 17% from $5.07 a year earlier, on revenue around $51 billion. Petno’s durability case rests on payments, which moves $12 trillion to $13 trillion a day and doubled its revenue over five years. “That is a fintech-like growth rate,” he said. The offset is the cost. He said outperformance would lift compensation in expense guidance, costs he called “good expenses.” That follows JPMorgan raising its 2026 adjusted expense outlook to $107.5 billion in July.
See how JPMorgan performs against its peers in TIKR (It’s free!) >>>
The CIB’s Own Target Assumes Credit Gets Worse
Petno’s own return target explains the discount. He described the Commercial & Investment Bank’s 16% return on equity target as a through-the-cycle figure, citing, among other factors, “the prospect that we’re overearning on credit.” Credit in the unit is clean for now: Petno put nonperforming loans below $5 billion and second-quarter net charge-offs around 12 basis points. His watch list covers clients exposed to a prolonged closure of the Strait of Hormuz, AI disruption, and low-income consumers, where weakness has begun to show.
TIKR’s consensus also has normalized EPS rising around 22% in 2026, then around 4% in 2027. At around 14x forward earnings, JPMorgan trades above Bank of America and Citigroup (C), both around 11x per TIKR’s Competitors data, with a 17.8% LTM return on equity.
TIKR Advanced Model Analysis
- Current Price: $332.38
- Target Price (Mid): ~$447
- Potential Total Return: ~35%
- Annualized IRR: ~7% / year

See analysts’ growth forecasts and price targets for JPMorgan stock (It’s free!) >>>
The mid case, realized December 31, 2030, is the only case the summary card reports at that horizon. It puts JPMorgan at around $447, about 35% above $332.38, or around 7% a year. Across its 2025 to 2035 forecast, the mid case assumes revenue growth of around 4.5% a year and a P/E that shrinks about 1.4% a year, so returns depend on earnings, not a re-rating. The primary risk is a credit turn that hits earnings and the multiple together. Upside: the 12-month Street mean sits about 12.5% above the October 5 close. Downside: if 2026 proves to be the earnings peak, the multiple could compress faster than the model assumes.
Conclusion
Watch year-over-year growth in IB fees and Markets revenue on October 13. Both at or above 15%, with expense guidance rising no faster than revenue, would back the higher estimates and make the current multiple look low. Either line below 10%, or another expense raise without matching revenue, would confirm what the multiple already prices in.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is JPMorgan stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what JPMorgan could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze JPMorgan on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!