

Key Stats for Cameco Stock
- Current Price: $85.18
- Target Price (Mid): ~$179
- Street Target: ~$127
- Potential Total Return: ~110%
- Annualized IRR: ~19% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Cameco (CCJ) sold uranium at an average realized price of US$67.79 per pound in Q2 2026, up 18% from a year earlier, according to its investor relations materials. The average reported long-term uranium price was $95.50 at the end of that quarter and $96.50 at the end of August and September, the highest month-end reading in nominal terms in Cameco’s data going back to 1996.
Yet the uranium segment gross profit fell 27% to C$158 million from C$217 million. Shares closed at $85.18 on October 2, and how quickly the contract book reprices, while costs stay in check, decides how much of that price reaches earnings.
Cameco’s Contract Book Lags a $96.50 Long-Term Price
The lag is built into how Cameco sells. President and COO Grant Isaac said on the July 31 earnings call that market-related contracts “don’t reference the long-term price” and instead carry floors and ceilings, adding that “it’s not unusual to see market-related contracts now where floor prices are in the high 70s escalated and where ceiling prices are 160 escalated.” Those floors sit above the Q2 realized price, and Isaac noted “we’ve never been at this kind of uranium price on the front end of a uranium contracting cycle.”
Repricing reaches the book slowly. Cameco has contracts for average annual deliveries of over 28 million pounds through 2030, with commitments above that average in 2026 through 2028 and below it in 2029 and 2030, leaving more room to sign new volume later in the decade. CEO Tim Gitzel said Cameco is “not prepared to dilute the value of our assets by committing supply into contracts that do not appropriately reflect the durability of market fundamentals.”
The risk is competition for that volume. Isaac said: “There still seems to be some in the market willing to try to discount floors and ceilings in order to win business.”

See historical and forward estimates for Cameco stock (It’s free!) >>>
Higher Prices Have Not Reached Profit or Cash Yet
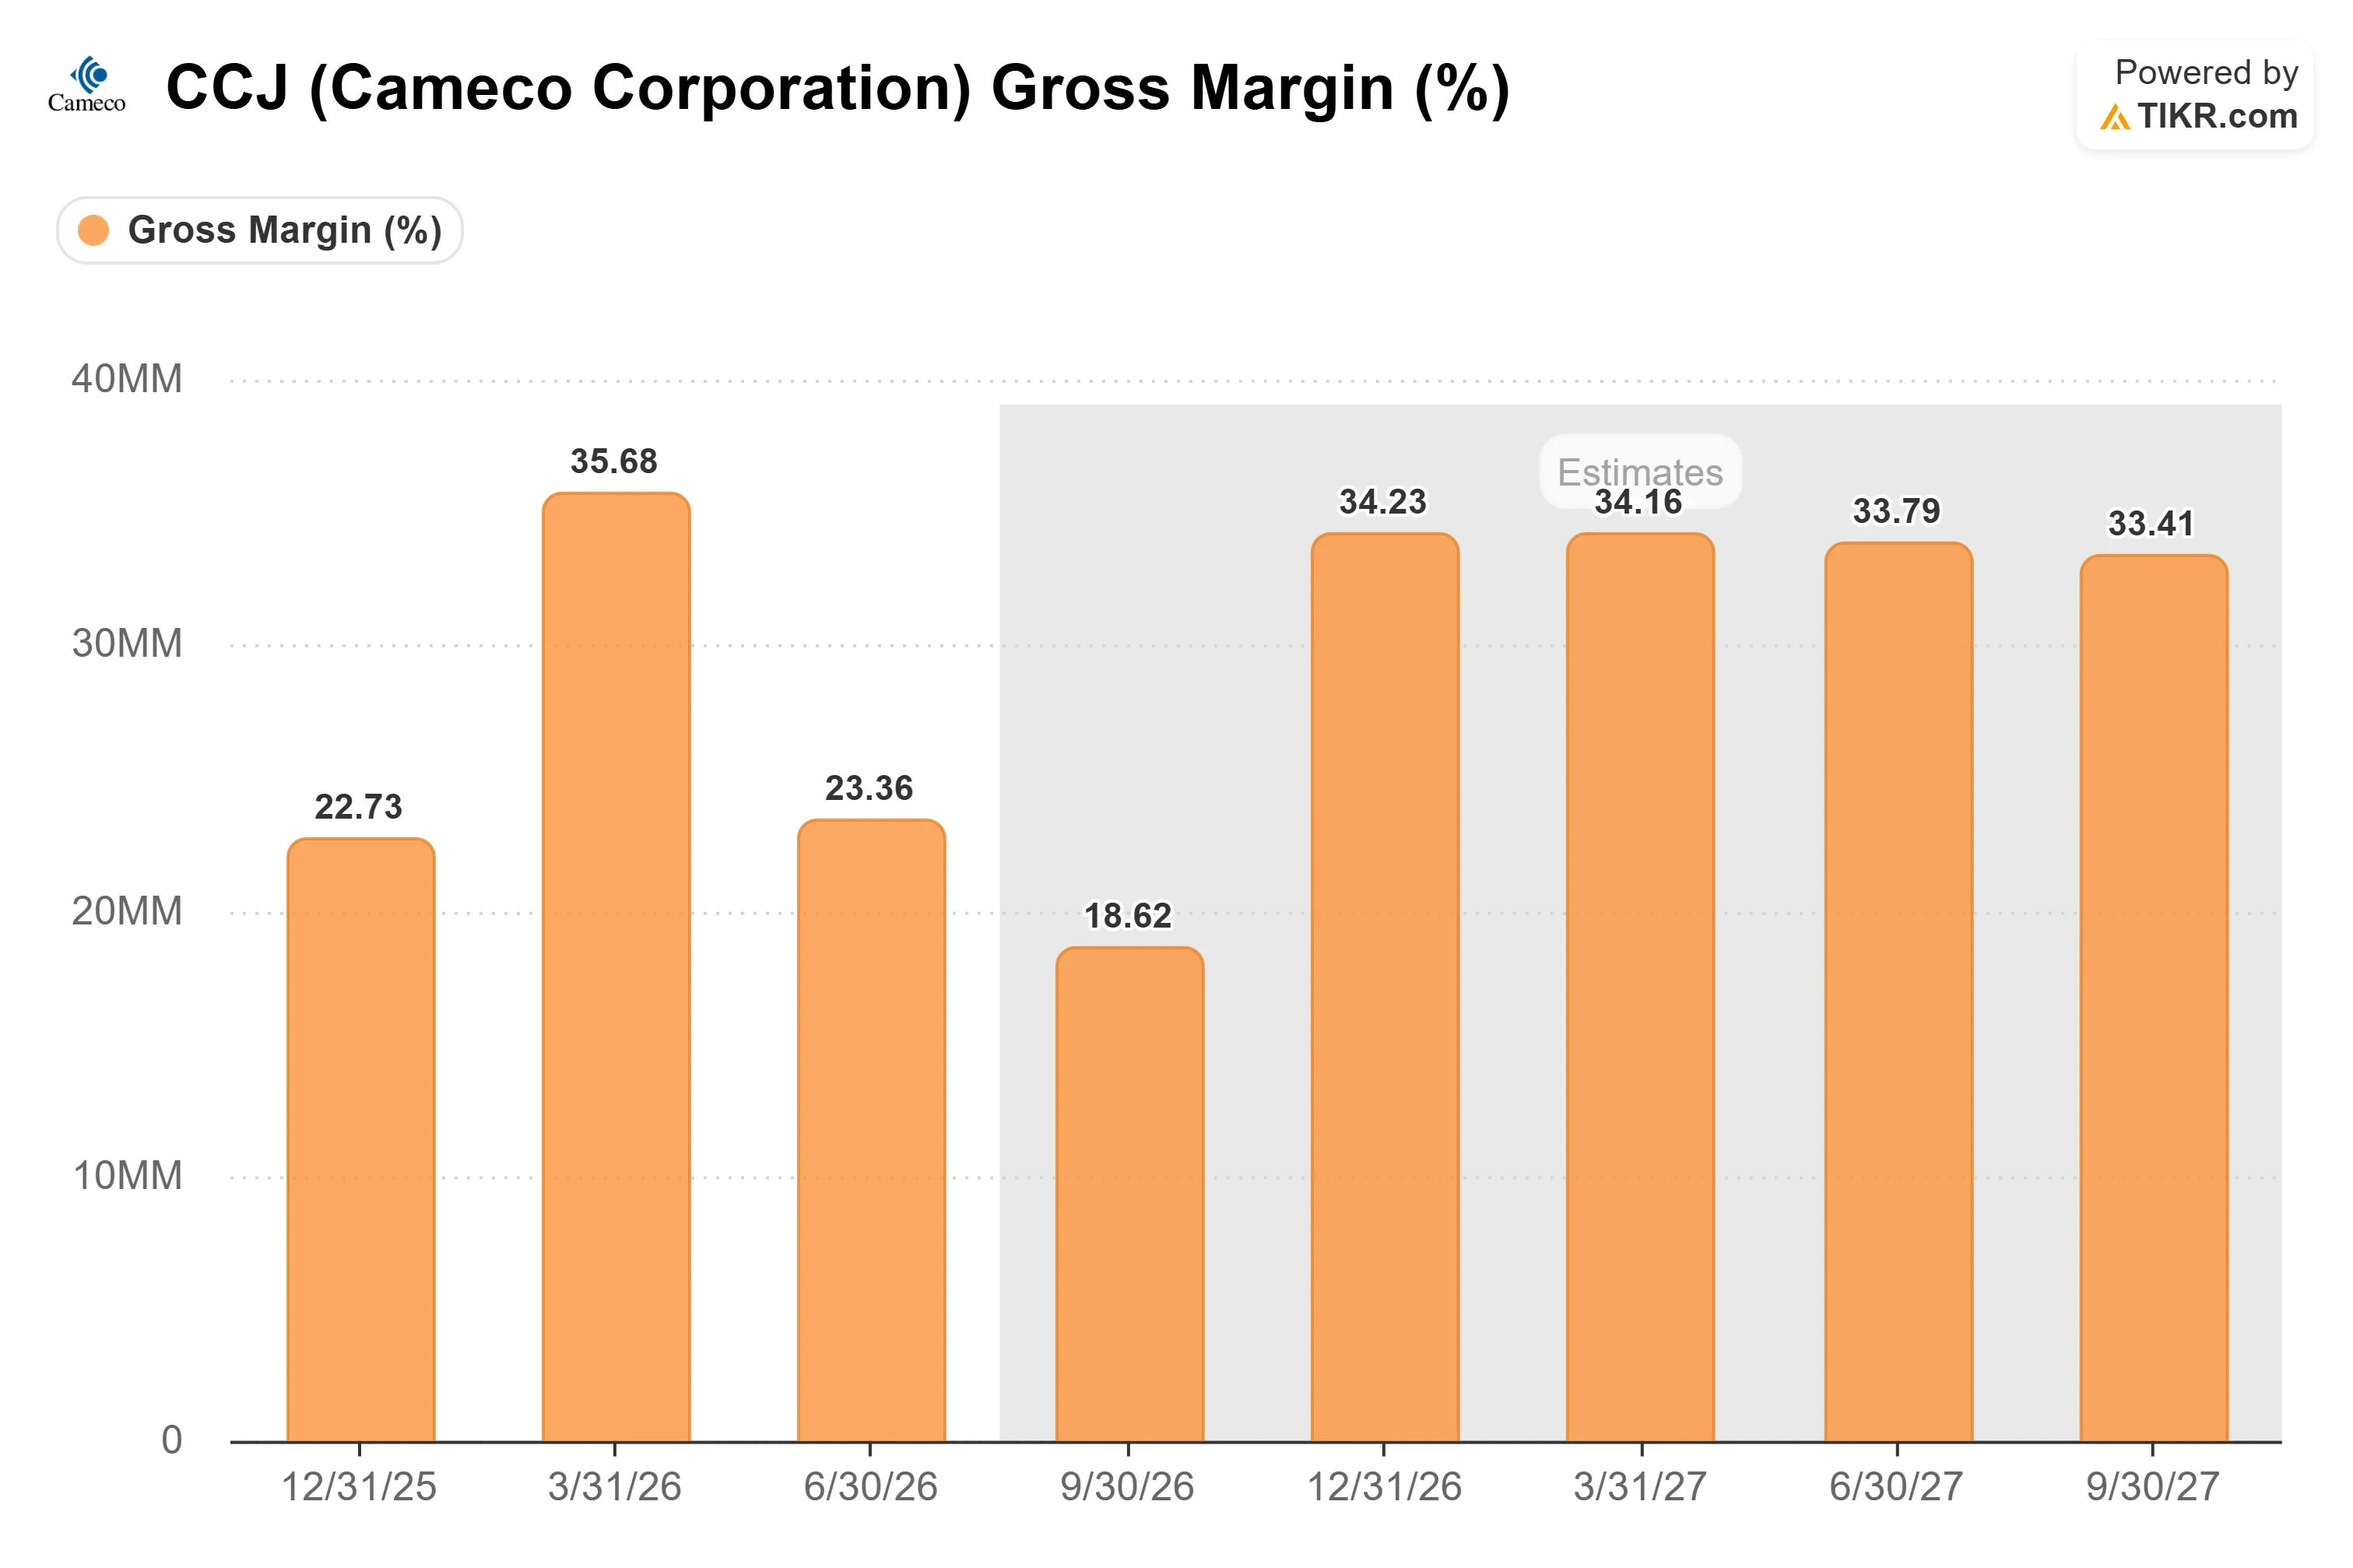
Q2 showed how much of the price gain costs can absorb. Higher US$ realized prices added C$104 million to uranium gross profit versus Q2 2025, but currency took back C$19 million and higher costs C$103 million, as Cameco’s produced and purchased cost rose 36% to C$62.21 per pound, driven by 2.8 million pounds bought at C$91.40, while its own production cost rose 9% to C$41.26.
Isaac pointed downstream for a leading signal, saying “you generally buy nuclear fuel backwards,” starting with fabrication, then enrichment and conversion, then uranium. Cameco’s fuel services realized price rose 13% to C$41.67 per kg U in Q2, though that segment’s earnings before taxes fell 32% to C$30 million, mainly on lower sales volumes.
Street consensus has free cash flow falling to around C$1,075.41 million in 2025 as capital spending rises to around C$480 million from C$333.03 million. Westinghouse, owned 49% by Cameco and 51% by Brookfield Renewable Partners, remains the wildcard after a non-binding U.S. and South Korea framework for up to eight of its reactors, which Cameco acknowledged on September 30, and a September 18 Bloomberg report, citing unnamed sources, that its planned IPO targets a valuation above $50 billion.
See how Cameco performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $85.18
- Target Price (Mid): ~$179
- Potential Total Return: ~110%
- Annualized IRR: ~19% / year

See analysts’ growth forecasts and price targets for Cameco stock (It’s free!) >>>
TIKR’s mid case is a scenario, not a promise: around $179 by 12/31/30, or around 19% a year from the $85.18 entry price. The same mid-case path fades to around $131 by 12/31/34, so the modeled gain depends on the next few years rather than the long tail.
Upside comes if Cameco signs 2029 and 2030 volume near today’s higher floors. The downside is another stretch where costs and competitor discounting absorb the price gains, as costs did in Q2.
Conclusion
Cameco reports Q3 before the open on October 30. It has guided to a 2026 uranium realized price of C$91 to C$96 per pound, against C$93.13 in Q2, an outlook built on a US 84.75 UxC spot assumption that the September 30 industry-average spot price of $89.63 now exceeds. A raised outlook with costs held in check would show price gains reaching profit; another quarter of offsets would mean the gap is closing slower than the stock can wait.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Cameco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cameco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


