Key Stats for Joby Aviation Stock
- Current Price: $5.14
- Target Price (Mid): ~$4.84
- Street Target: ~$10
- Potential Total Return: ~-6%
- Annualized IRR: ~-1% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Barclays assumed coverage of Joby Aviation (JOBY) on Oct. 9 and cut the stock to Underweight from Equal Weight, lowering its target to $4 from $6. The bank argues the eVTOL market will not be winner-take-all, and that Joby lacks the manufacturing capacity to take massive share even if it certifies first. Shares fell about 9% in early trading and closed that session at $5.44. Barclays assumed coverage of Archer Aviation (ACHR) at Overweight with an $8 target.
Joby fell another 5.51% on Oct. 12 to $5.14, near TIKR’s 52-week low of $5.13 and down 61% this year. Joby’s own Q2 call, available with its investor relations materials, makes Barclays’ capacity question harder to wave away.

See historical and forward estimates for Joby Aviation stock (It’s free!) >>>
Joby’s Q2 Call Puts the Limit on Aircraft
On the Aug. 5 call, CFO Rodrigo Brumana said the eIPP markets of Texas, Florida, and New York “could absorb the whole production for quite some time.” He pitched that as proof Joby can monetize every aircraft it builds. Executive Chairman Paul Sciarra said aircraft availability is the main barrier to growing Blade, the premium passenger flight business Joby bought about a year earlier. He called it something “we hope to solve with a better, quieter aircraft in relatively short order.” Both framed demand as the strength, and both put the ceiling on how many Joby aircraft exist, which is the variable Barclays doubts.
The line is growing from a small base:
- Four aircraft added to the production queue during Q2
- At least two targeted to come off the line in the second half
- Nonconformance rate (a measure of build defects) down nearly 40% in the first half, per CEO JoeBen Bevirt
Until those aircraft arrive, Blade carries the revenue. It produced $36.2 million of Joby’s $38.64 million in Q2 sales, which beat consensus of around $30 million by 27%.
A Verdict and a Defense Deal Now Sit on Joby’s Cash
Two new commitments landed after the Q2 report:
- $450 million in cash for Resonant Sciences, a defense deal announced Aug. 11 and expected to close in the first half of 2027
- A $116.9 million jury verdict won by Aerosonic on Oct. 2, which Joby has asked the court to overturn
With the $385 million to $415 million of guided second-half cash use, the three total around $980 million. That compares with about $2.3 billion in cash and short-term investments at June 30, or roughly $1.5 billion net of debt. Brumana said Joby expects Toyota’s (TM) $250 million direct investment around year-end or early 2027, as it finalizes remaining supply agreements.
Barclays also says Joby’s premium valuation is not justified. With a market cap of $5.08 billion as of Oct. 12, the stock trades at nearly 30 times NTM revenue on an enterprise value basis, still pricing in a ramp that has not happened. Ratings split 2 Buy, 1 Outperform, 4 Hold, 2 Underperform, and 2 Sell. Targets run from $4 to $18, with a mean around $10.

See how Joby Aviation performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
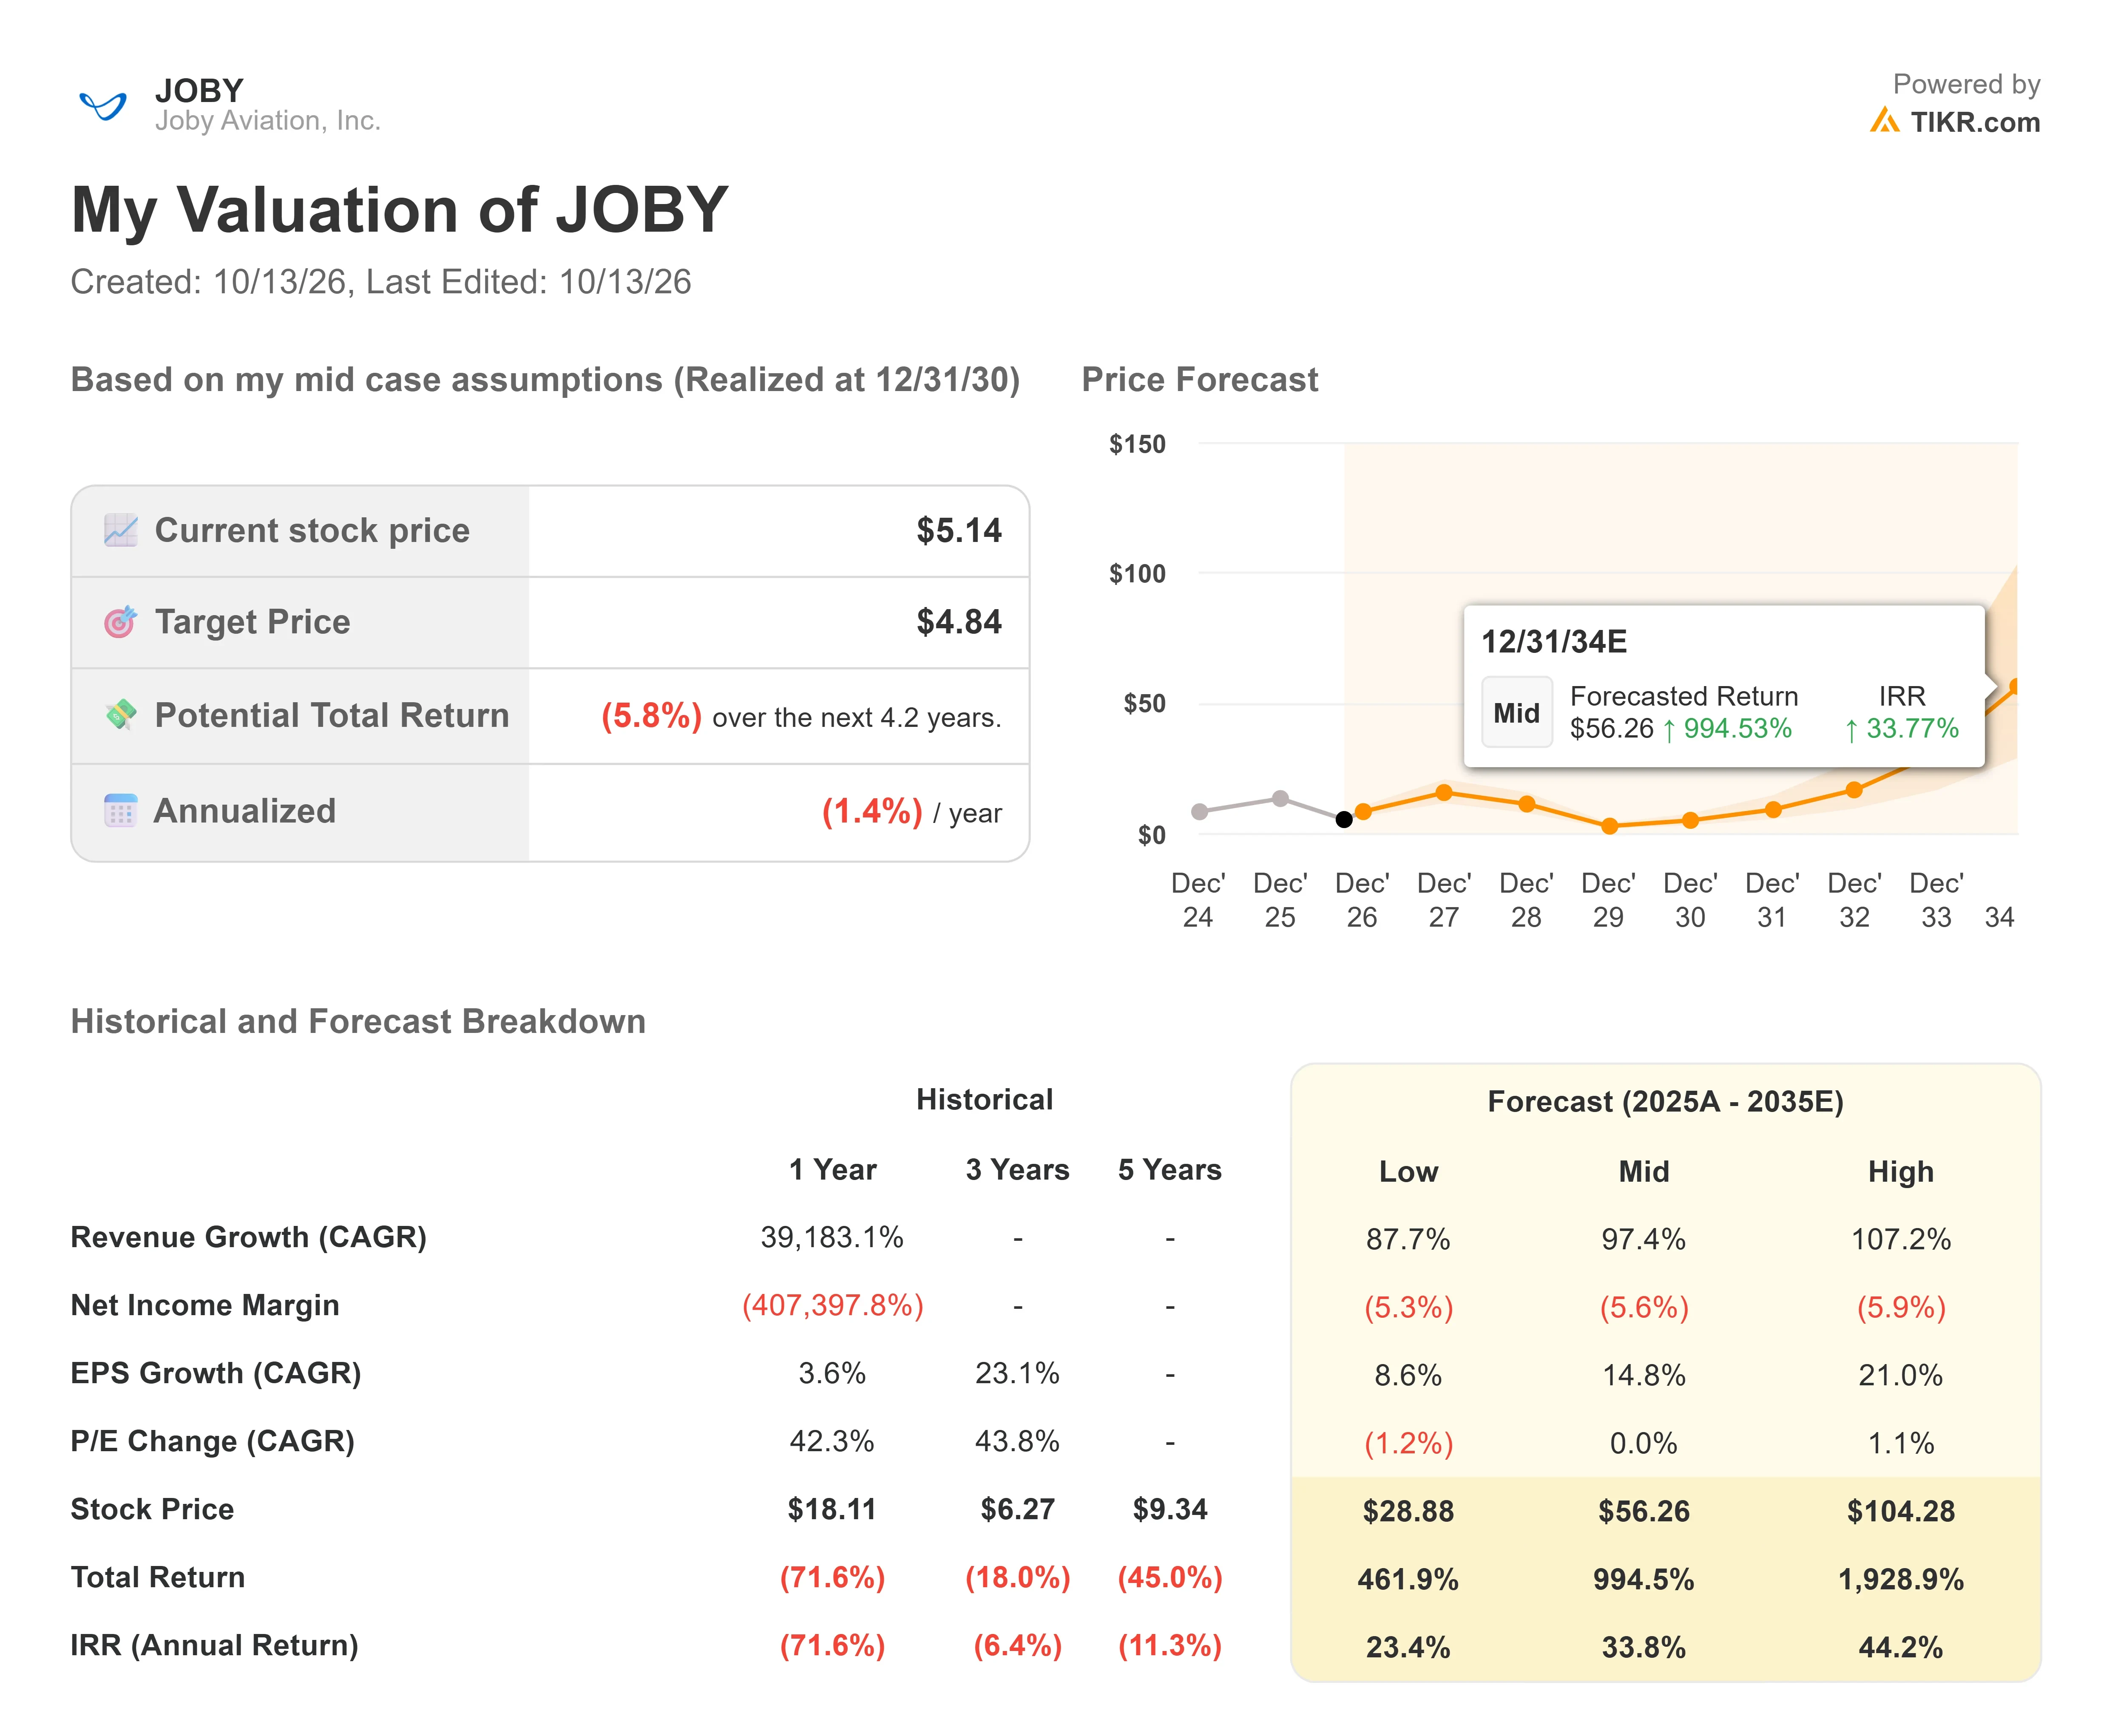
- Current Price: $5.14
- Target Price (Mid): ~$4.84
- Potential Total Return: ~-6%
- Annualized IRR: ~-1% / year
See analysts’ growth forecasts and price targets for Joby Aviation stock (It’s free!) >>>
The TIKR mid case, realized at Dec. 31, 2030, lands closer to Barclays’ $4 than to the Street mean. It assumes revenue compounds around 97% a year across its 2025 to 2035 forecast. That is slightly below the roughly 105% annual pace Street estimates imply from $53.43 million in 2025 to around $1.95 billion in 2030. Even with that growth, the case sits below today’s price at the end of 2030. The payoff comes later: the same mid case reaches around $56 by the end of 2035.
The primary risk is slow output forcing more equity raises. Upside comes if the Toyota venture lifts production enough to put Joby aircraft on Blade’s routes. On the downside, the 2030 mid case already shows a loss from $5.14, and a slower ramp would widen it.
Conclusion
Q3 results are expected in early November (date not yet confirmed). As of the Aug. 5 call, Joby still targeted its first eIPP passengers in 2026. If it confirms both second-half deliveries and those first passengers by Dec. 31, the capacity argument weakens. If deliveries slip into 2027, the $4 target stops looking like an outlier.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Joby Aviation stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Joby Aviation could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Joby Aviation on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!