Key Takeaways
- Intel shares jumped 8% after CEO Lip-Bu Tan said it signed its first outside 18A customer, with yields at 70%.
- It’s the best evidence yet that Intel’s foundry can win outside business.
- Tan says Intel can’t supply enough for AI demand, and Microsoft and ASML gain if it adds capacity.
- The stock trades far above its pre-2023 multiples, so a named customer for 14A is the real test.
Intel (INTC) finally has an outside customer for 18A, the chipmaking process its turnaround rests on. Shares jumped 8% today.
“We just signed the first customer,” CEO Lip-Bu Tan said Wednesday at the TomorrowX Summit, without naming it. He also named Microsoft (MSFT) as the first public customer for EMIB, its most advanced packaging technology. And the 18A win is good news for ASML (ASML).
Yields at 70%, and fabs to fill
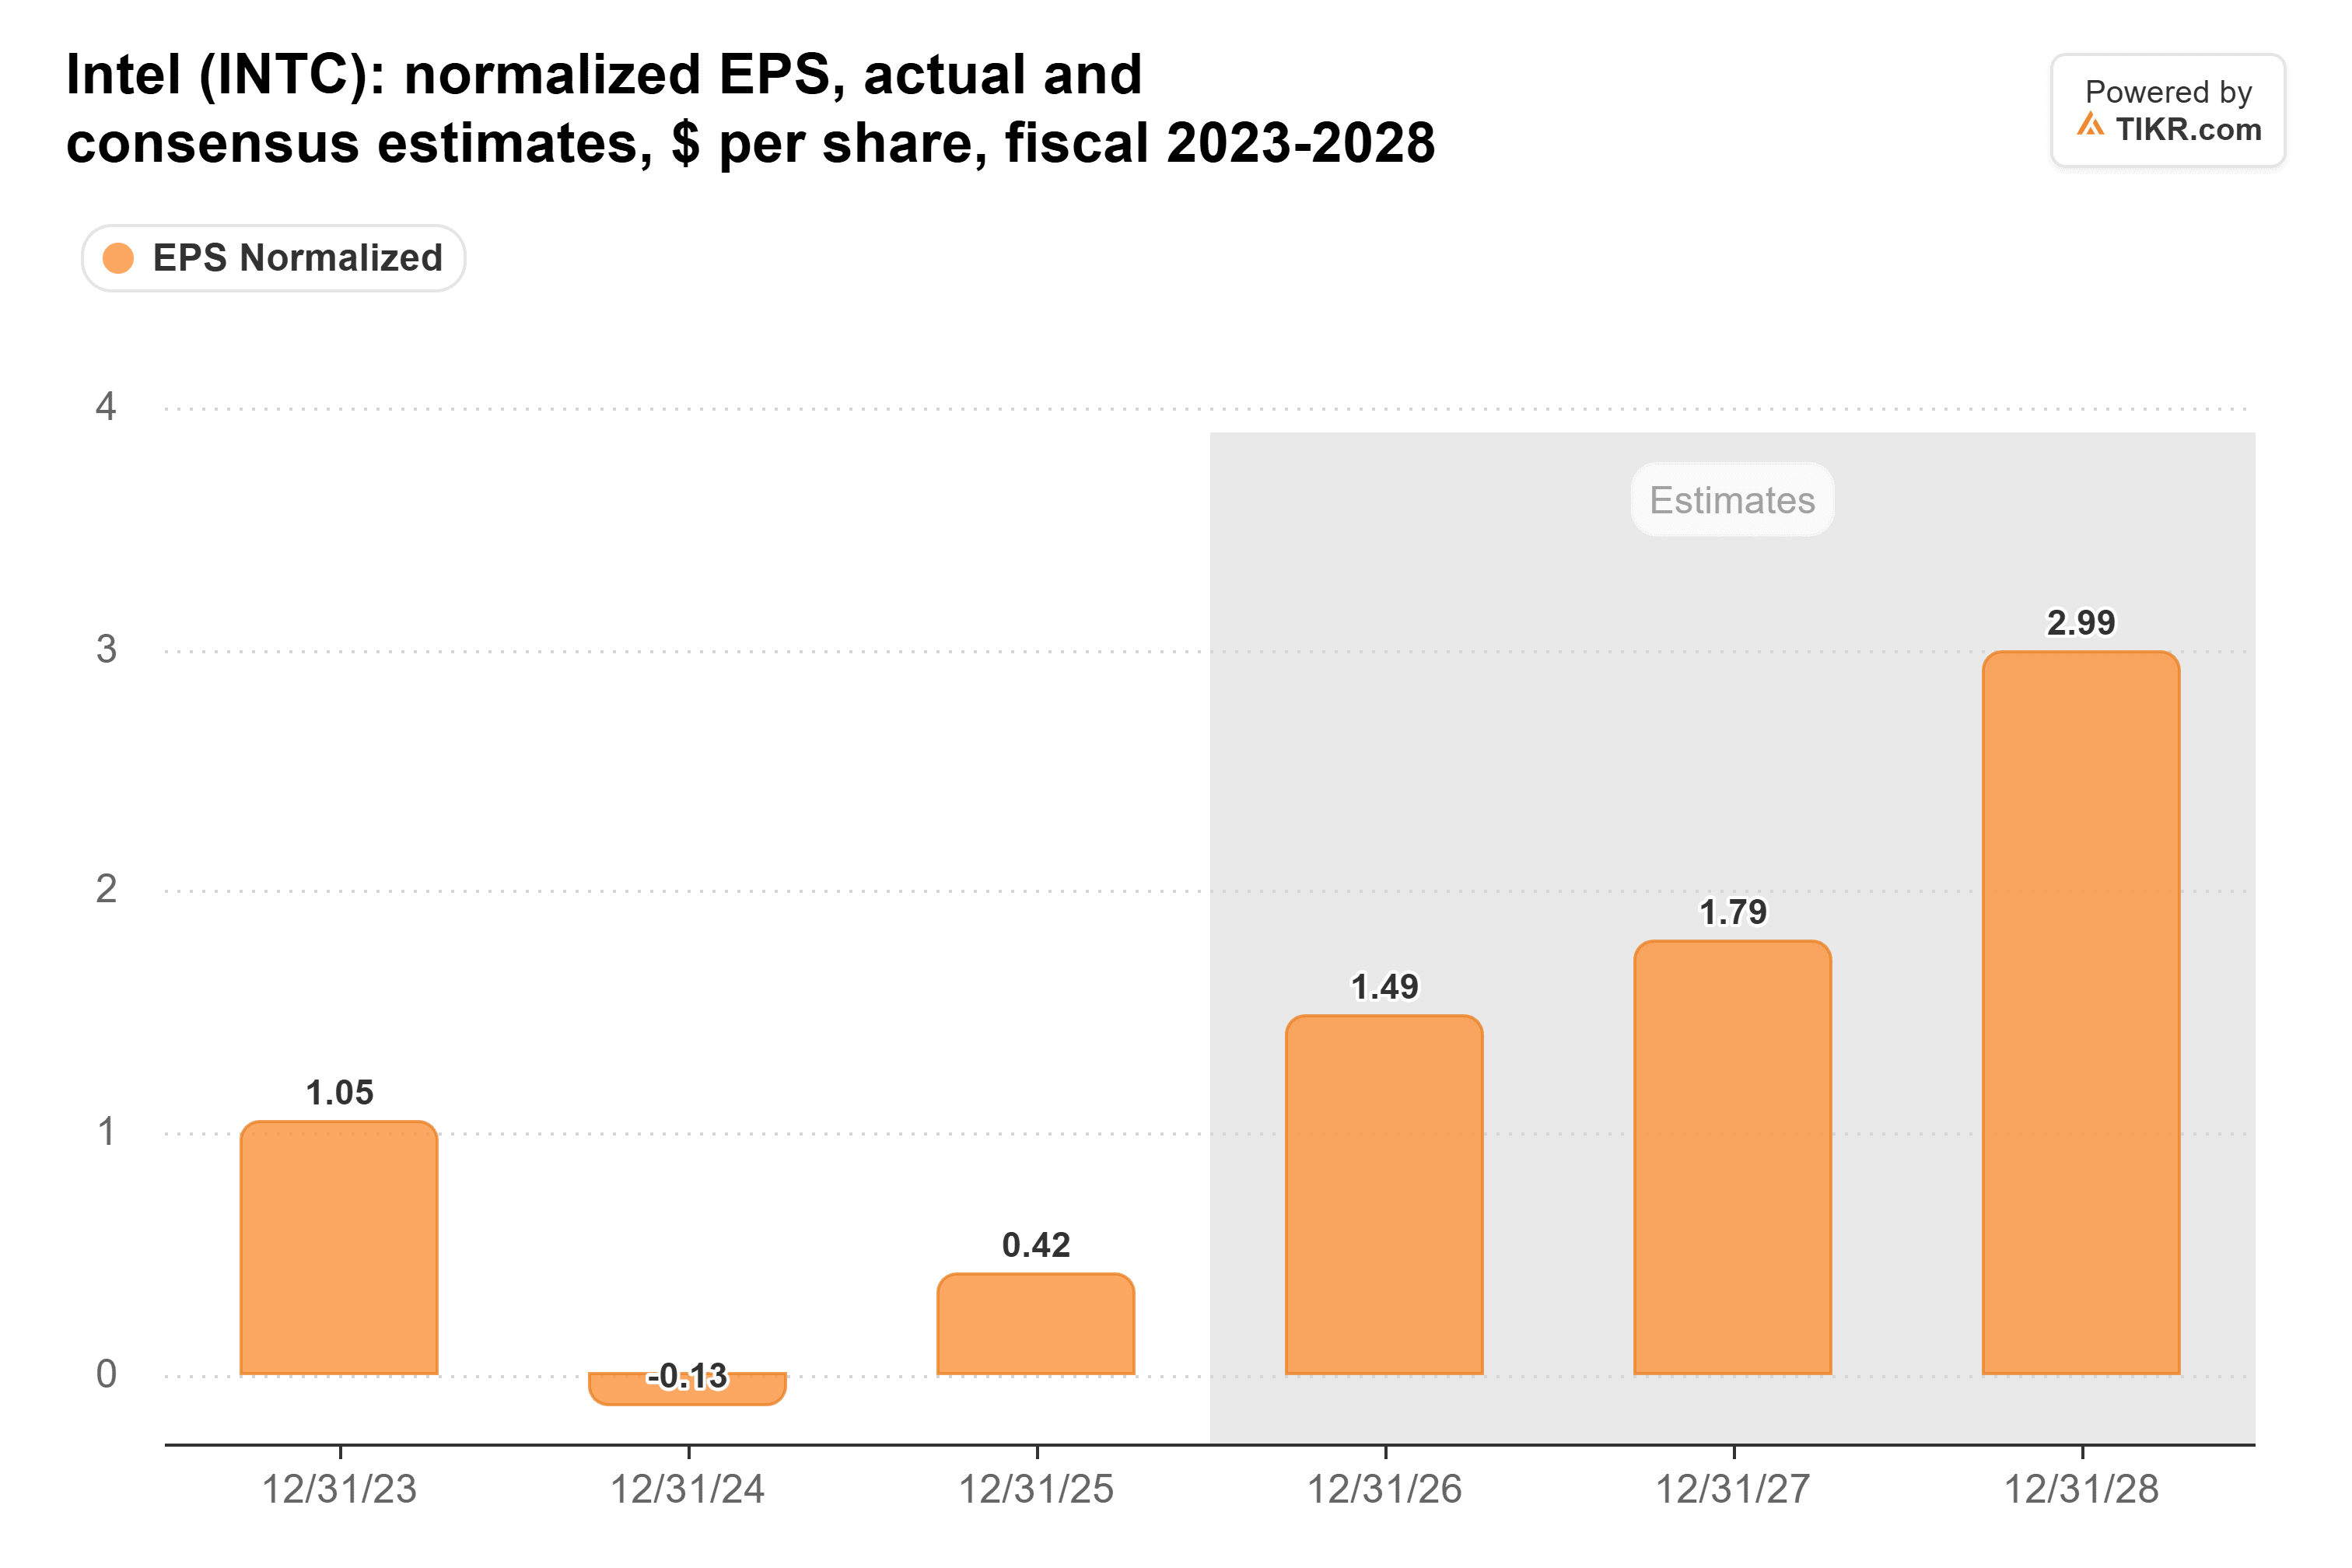
Tan put 18A yields at 70%, and Intel needs the business: its capex has topped its operating cash flow every year from 2022 to 2025, and outside foundry revenue was just $293 million in the second quarter. Analysts expect normalized EPS to roughly double from this year to 2028.
Intel can’t make enough
On AI demand, Tan said: “I just cannot supply enough.” That fits October’s guide, which put fourth-quarter revenue at least $1 billion below estimates, partly on a fab shutdown in Israel and a substrate shortage.
Microsoft wants capacity too. Guessing at the 18A customer, Creative Strategies analyst Ben Bajarin told CNBC that “Amazon, Microsoft and Google are struggling to get capacity for their CPU ambitions at TSMC.” With Azure revenue up 48% in the September quarter, Microsoft has every reason to want a second chip supplier.
ASML, up 3% today, said in October that its planned supply for 2027 and 2028 won’t fully meet demand. Intel already runs its High NA machines on part of 18A, while TSMC doesn’t plan volume use until 2030, so a busier Intel foundry makes those orders more likely to hold.
TIKR tracks 49 analysts on Intel. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intel, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intel’s Analyst Ratings
Priced for a turnaround
Intel’s forward P/E is below its five-year average.
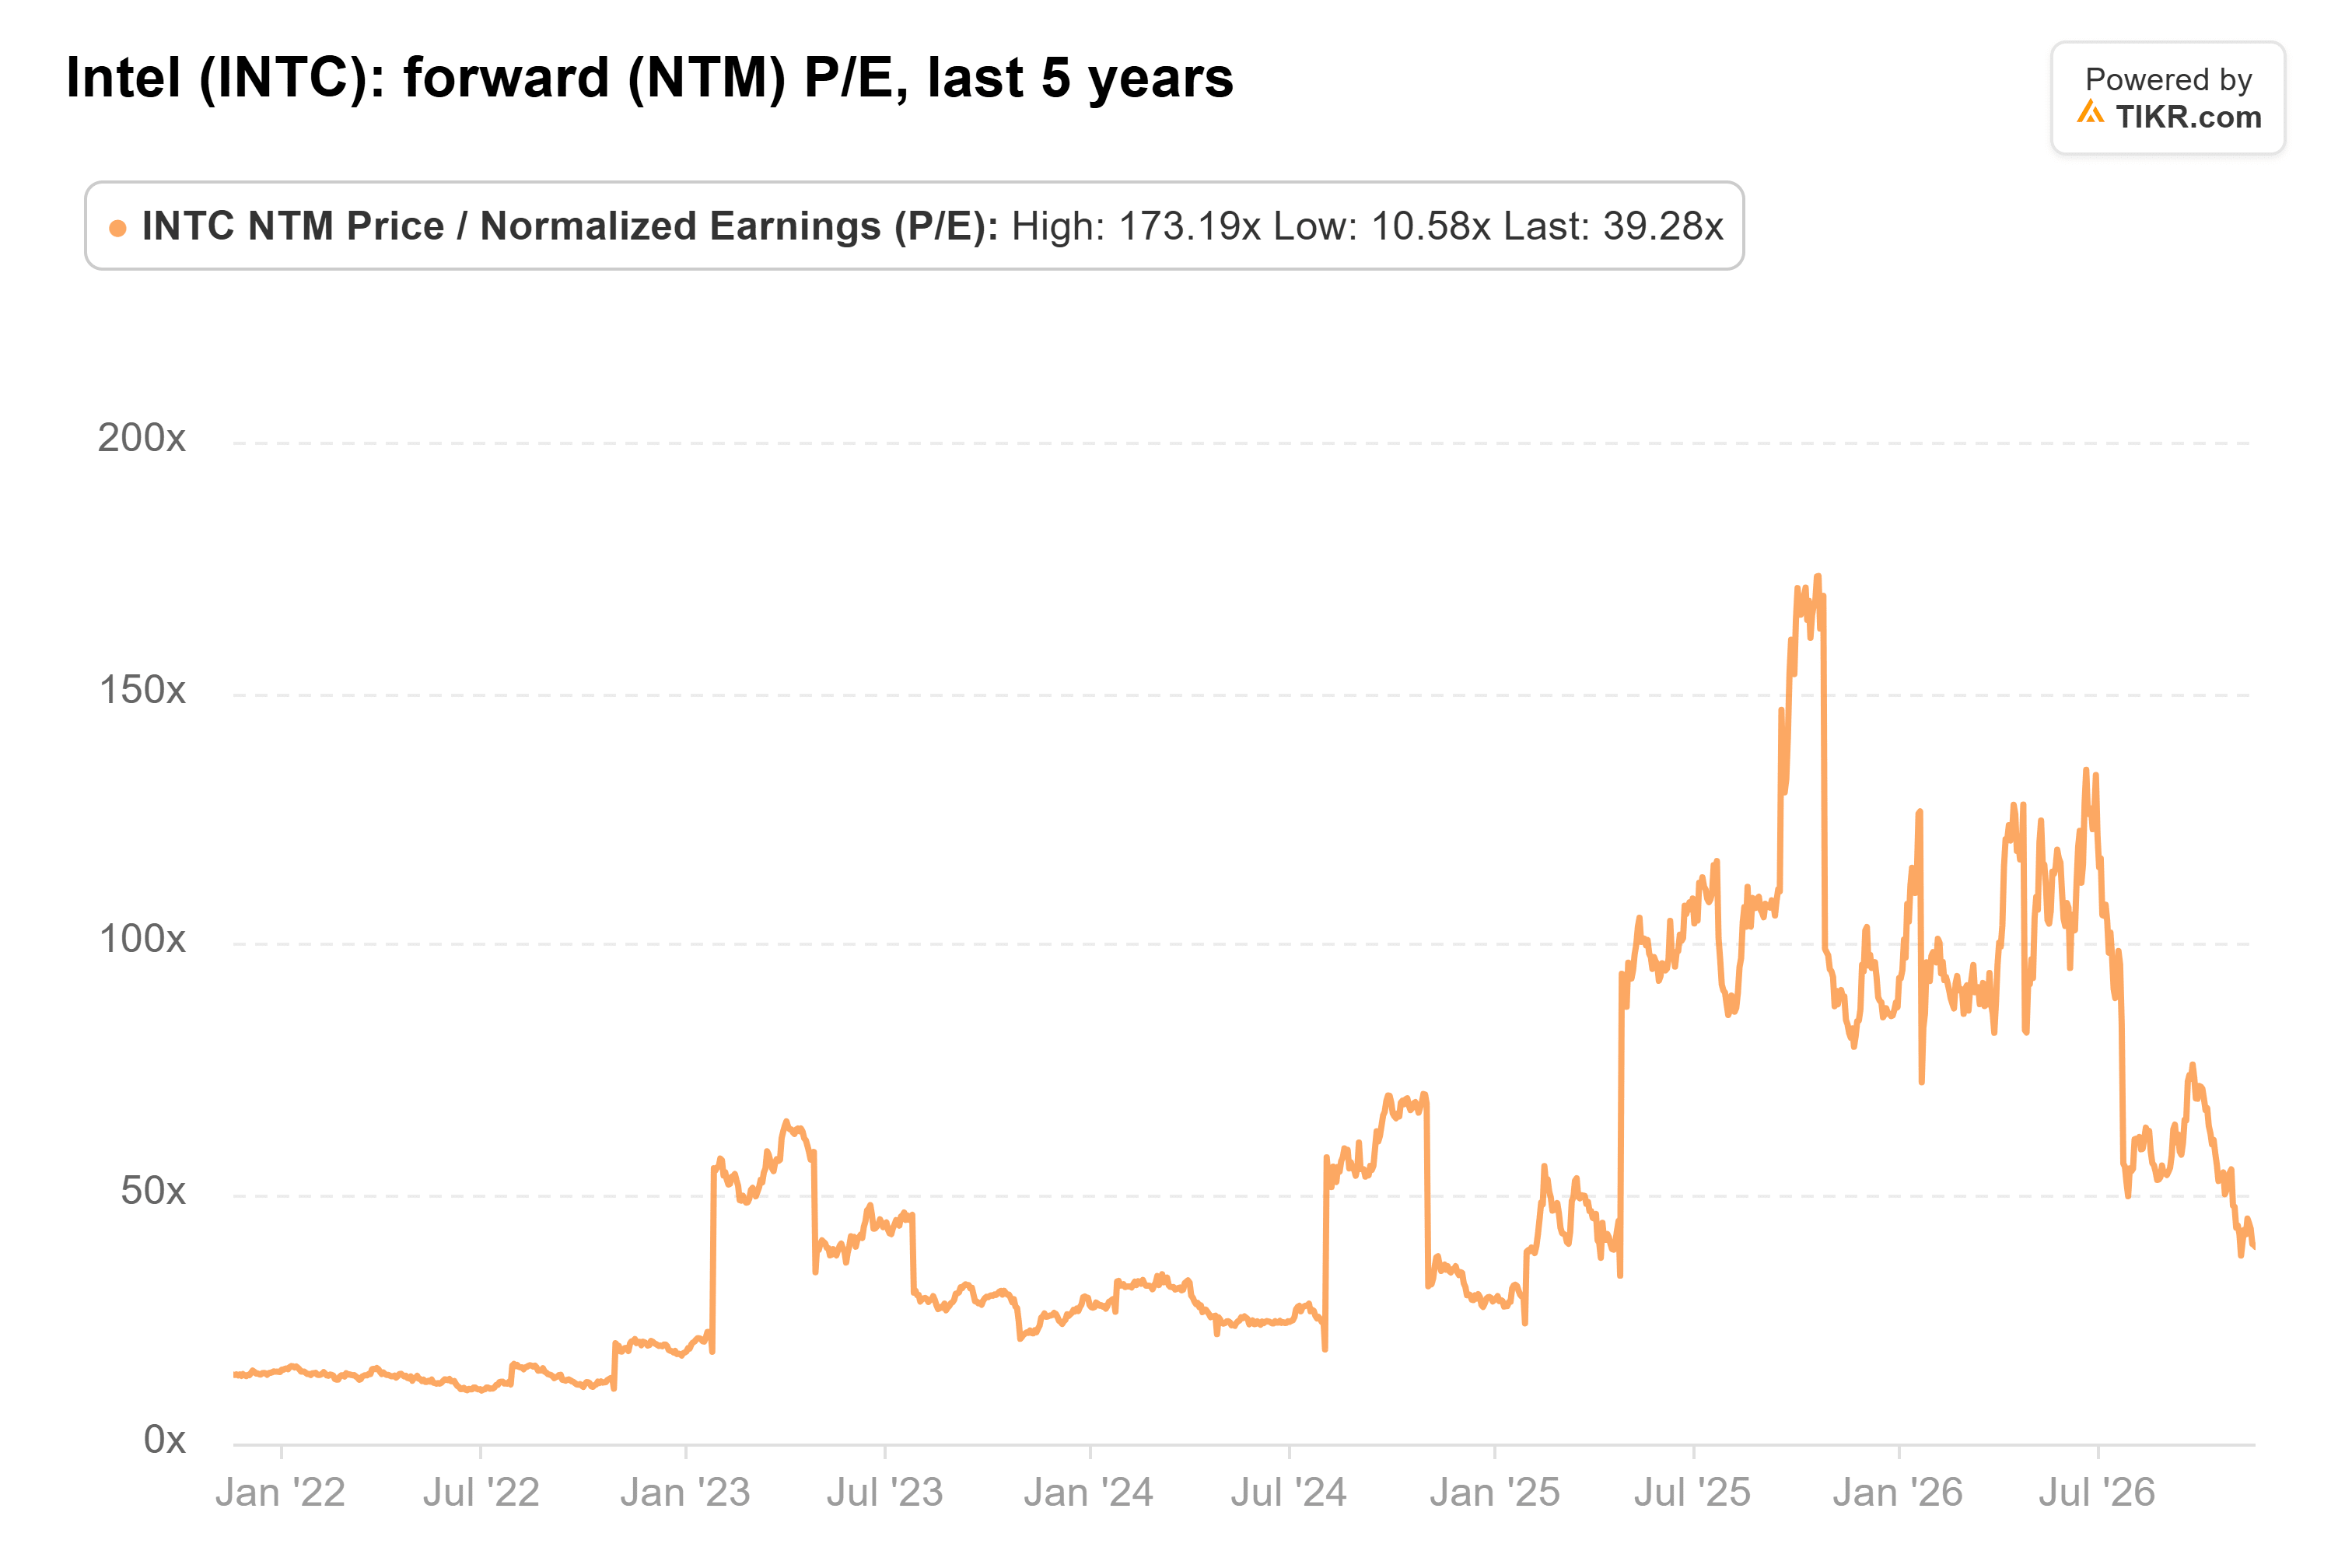
It was 39x at the last close, and about 42x after today’s jump. But that 51x average is inflated by years when Intel barely earned anything; from 2014 to 2022, it traded between about 10x and 18x.
I’d rather own a chipmaker that can’t make enough than one that can’t sell. But at about 42x, the stock is priced for a turnaround that one unnamed customer doesn’t prove. Management expects outside customers to commit to 14A designs by mid-2027, and a named one with volume attached would.
So what is Intel stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intel could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!