Key Takeaways
- Coca-Cola beat third-quarter estimates with comparable EPS of $0.91 and raised its 2026 currency-neutral EPS growth outlook to at least 9%.
- Volume rose 5% on India, China, Mexico and Brazil, while North America was flat and price/mix added just 1 point.
- KFC will start replacing Pepsi with Coke at roughly 3,700 U.S. restaurants in January, a win where Coca-Cola’s U.S. volume has stalled.
- CEO Henrique Braun warned “cost pressures have accelerated,” and February’s fourth-quarter report brings the first 2027 guidance.
Coca-Cola (KO) keeps doing the one thing its rivals are struggling with: selling more drinks. Third-quarter unit case volume rose 5%, and the company raised its full-year profit outlook for the third quarter in a row.
The contrast with PepsiCo (PEP) is hard to miss. PepsiCo grew organic revenue 3.1% in its own third quarter, yet it still cut its 2026 core EPS growth outlook to 2.5% to 3.5%.
Then Yum! Brands (YUM) handed Coca-Cola another win. Its KFC chain will begin swapping Pepsi for Coke at roughly 3,700 U.S. restaurants in January, ending a beverage partnership that dates back to 1986.
So the business looks healthy. The harder question is how much of this the stock already reflects.
Another quarter, another raise
Coca-Cola reported on October 27, and the numbers were clean:
- Net revenue grew 7% to $13.4 billion, ahead of the $12.92 billion analysts expected, per LSEG.
- Comparable EPS rose 11% to $0.91, topping the $0.88 consensus.
- Operating margin widened to 33.4% from 32.0%.
Management now expects comparable currency-neutral EPS to grow at least 9% this year, up from 7% to 8%. Year-to-date free cash flow reached $11.4 billion.
Here’s how revenue has trended quarter by quarter…
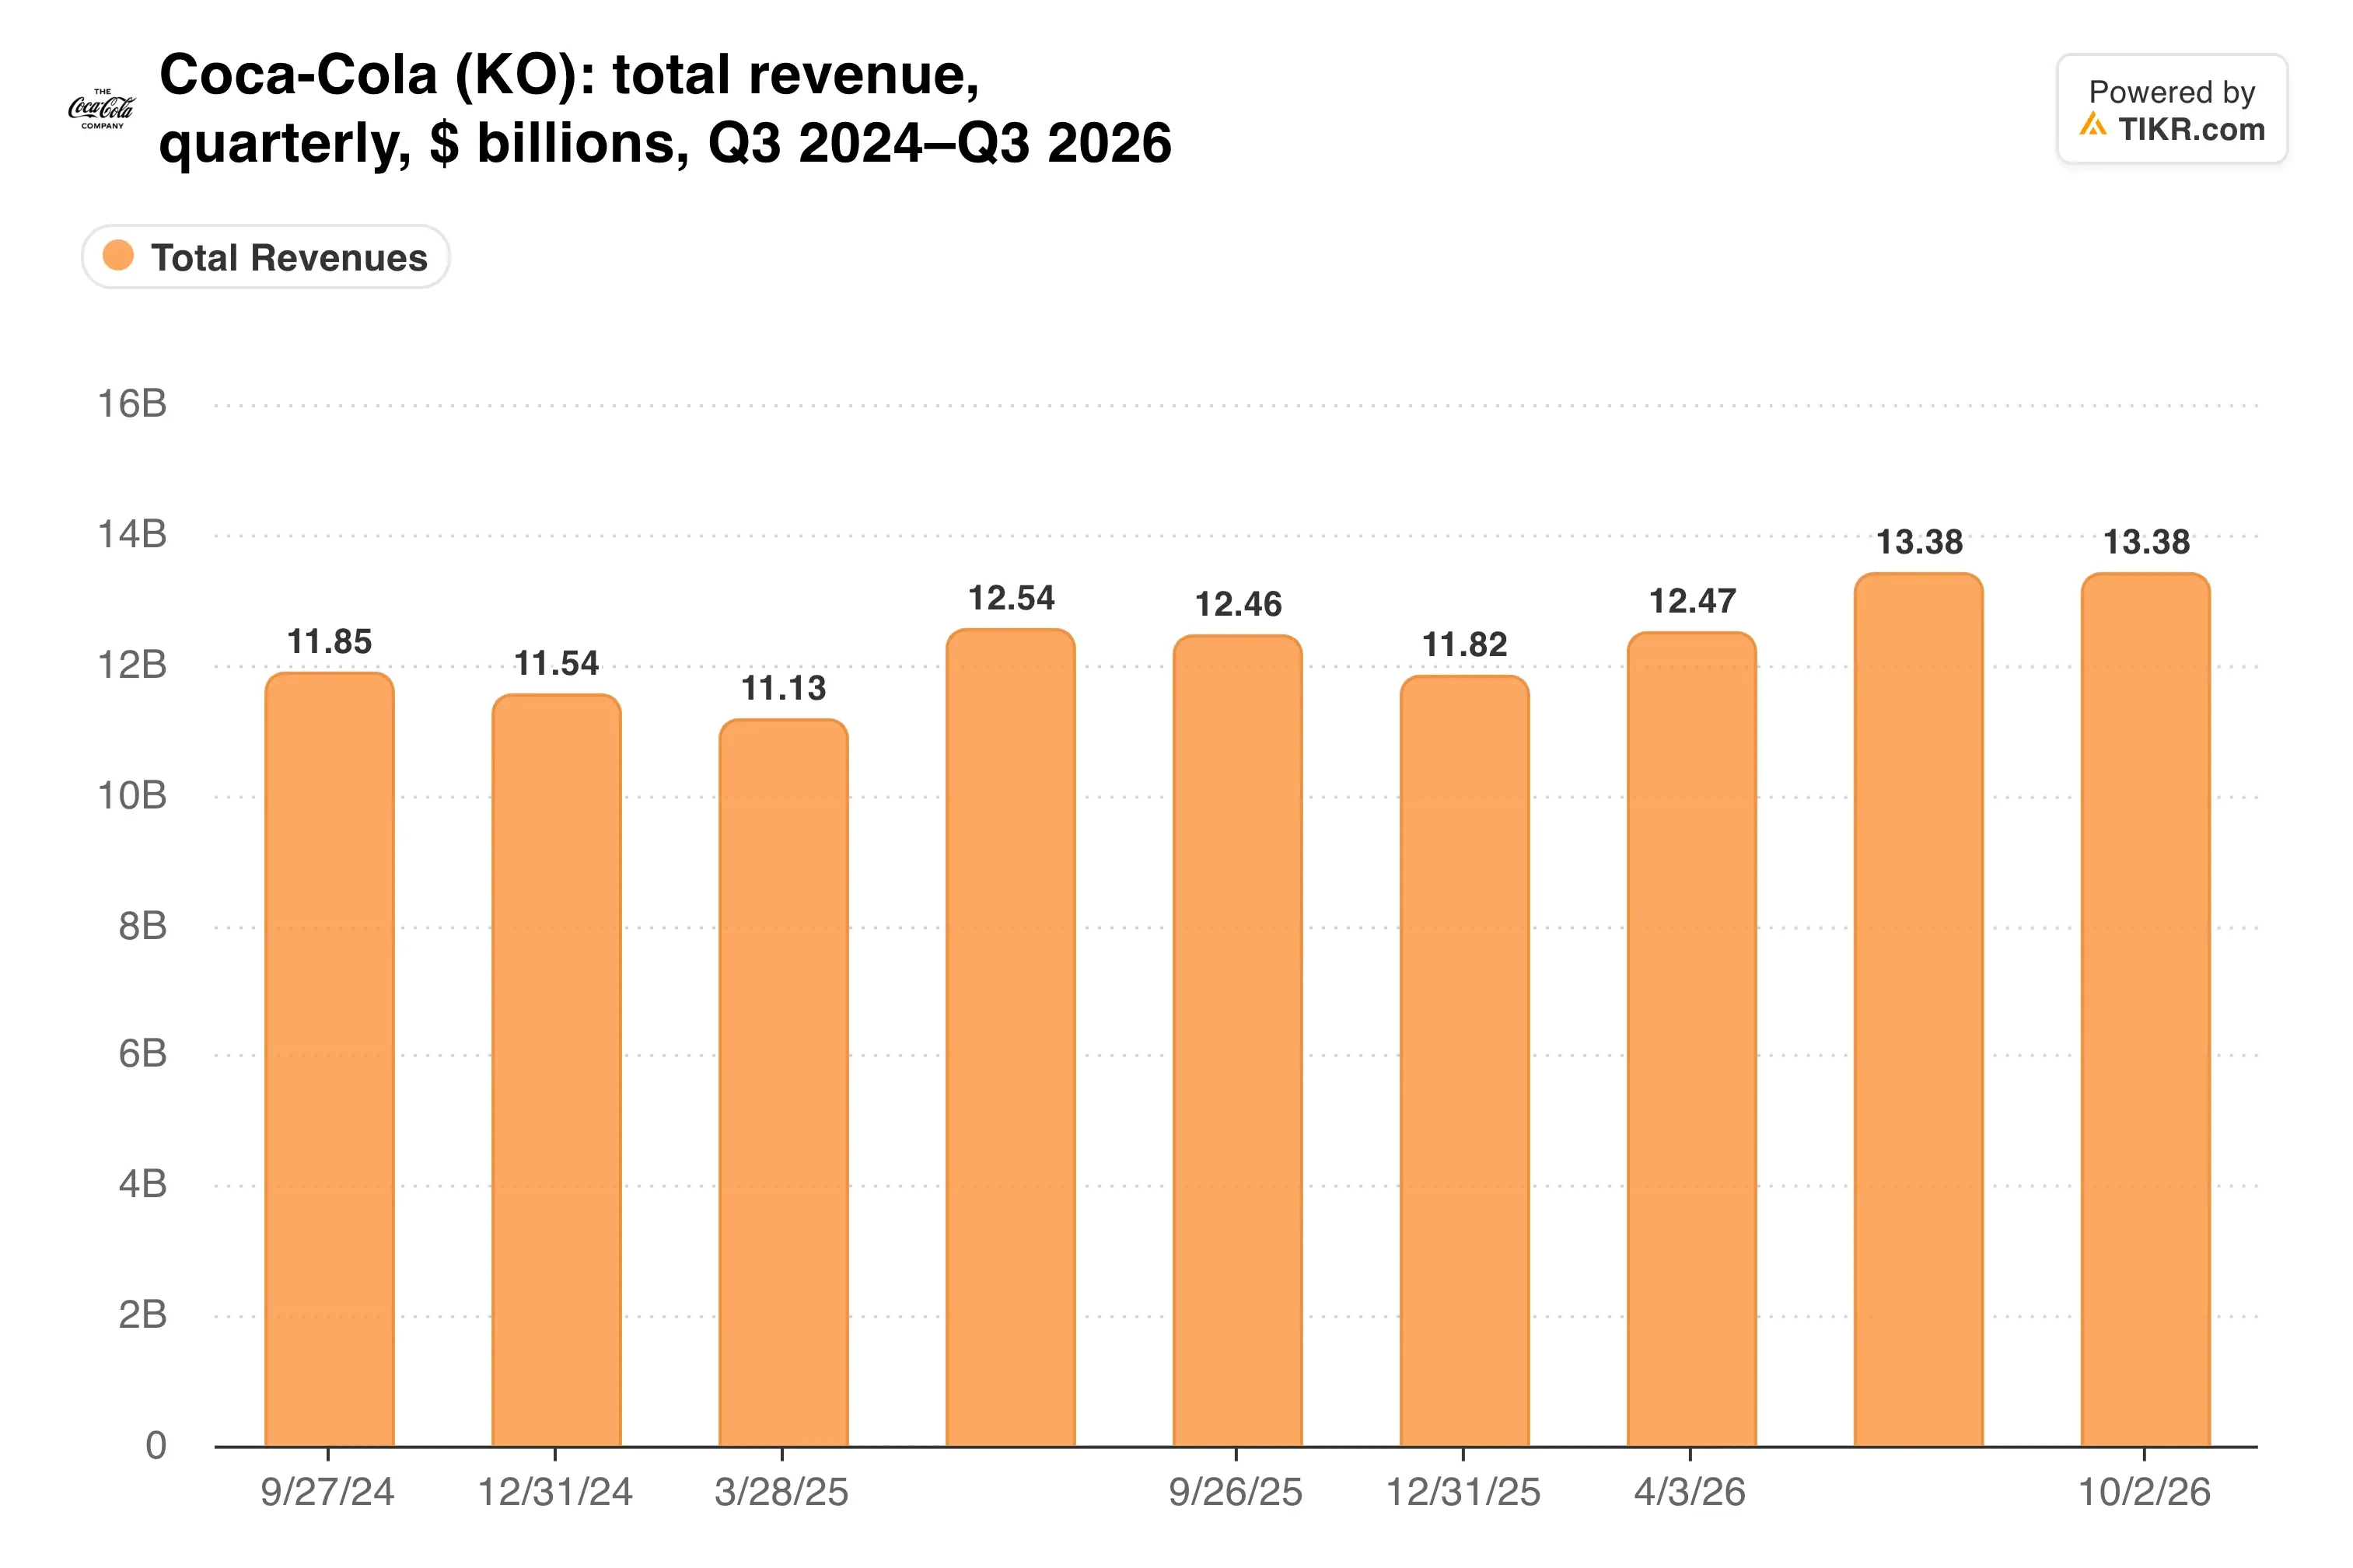
Organic revenue also grew 7%, but price/mix added just 1 point. Volume did most of the work this time.
Growth is coming from abroad
India, China, Mexico and Brazil led the volume gains. Coca-Cola Zero Sugar grew 16%, while Latin America’s operating income jumped 29%.
North America is the soft spot. Volume there was flat, although operating income still rose 5%. CFO John Murphy pointed to weak restaurant traffic as a slight drag, and the July 4 holiday also fell in the second quarter this year.
That is why the KFC deal matters. Restaurants are exactly where Coke’s U.S. volume has stalled, and KFC brings thousands of fountains between January and spring 2027.
How does that profitability stack up against its oldest rival?
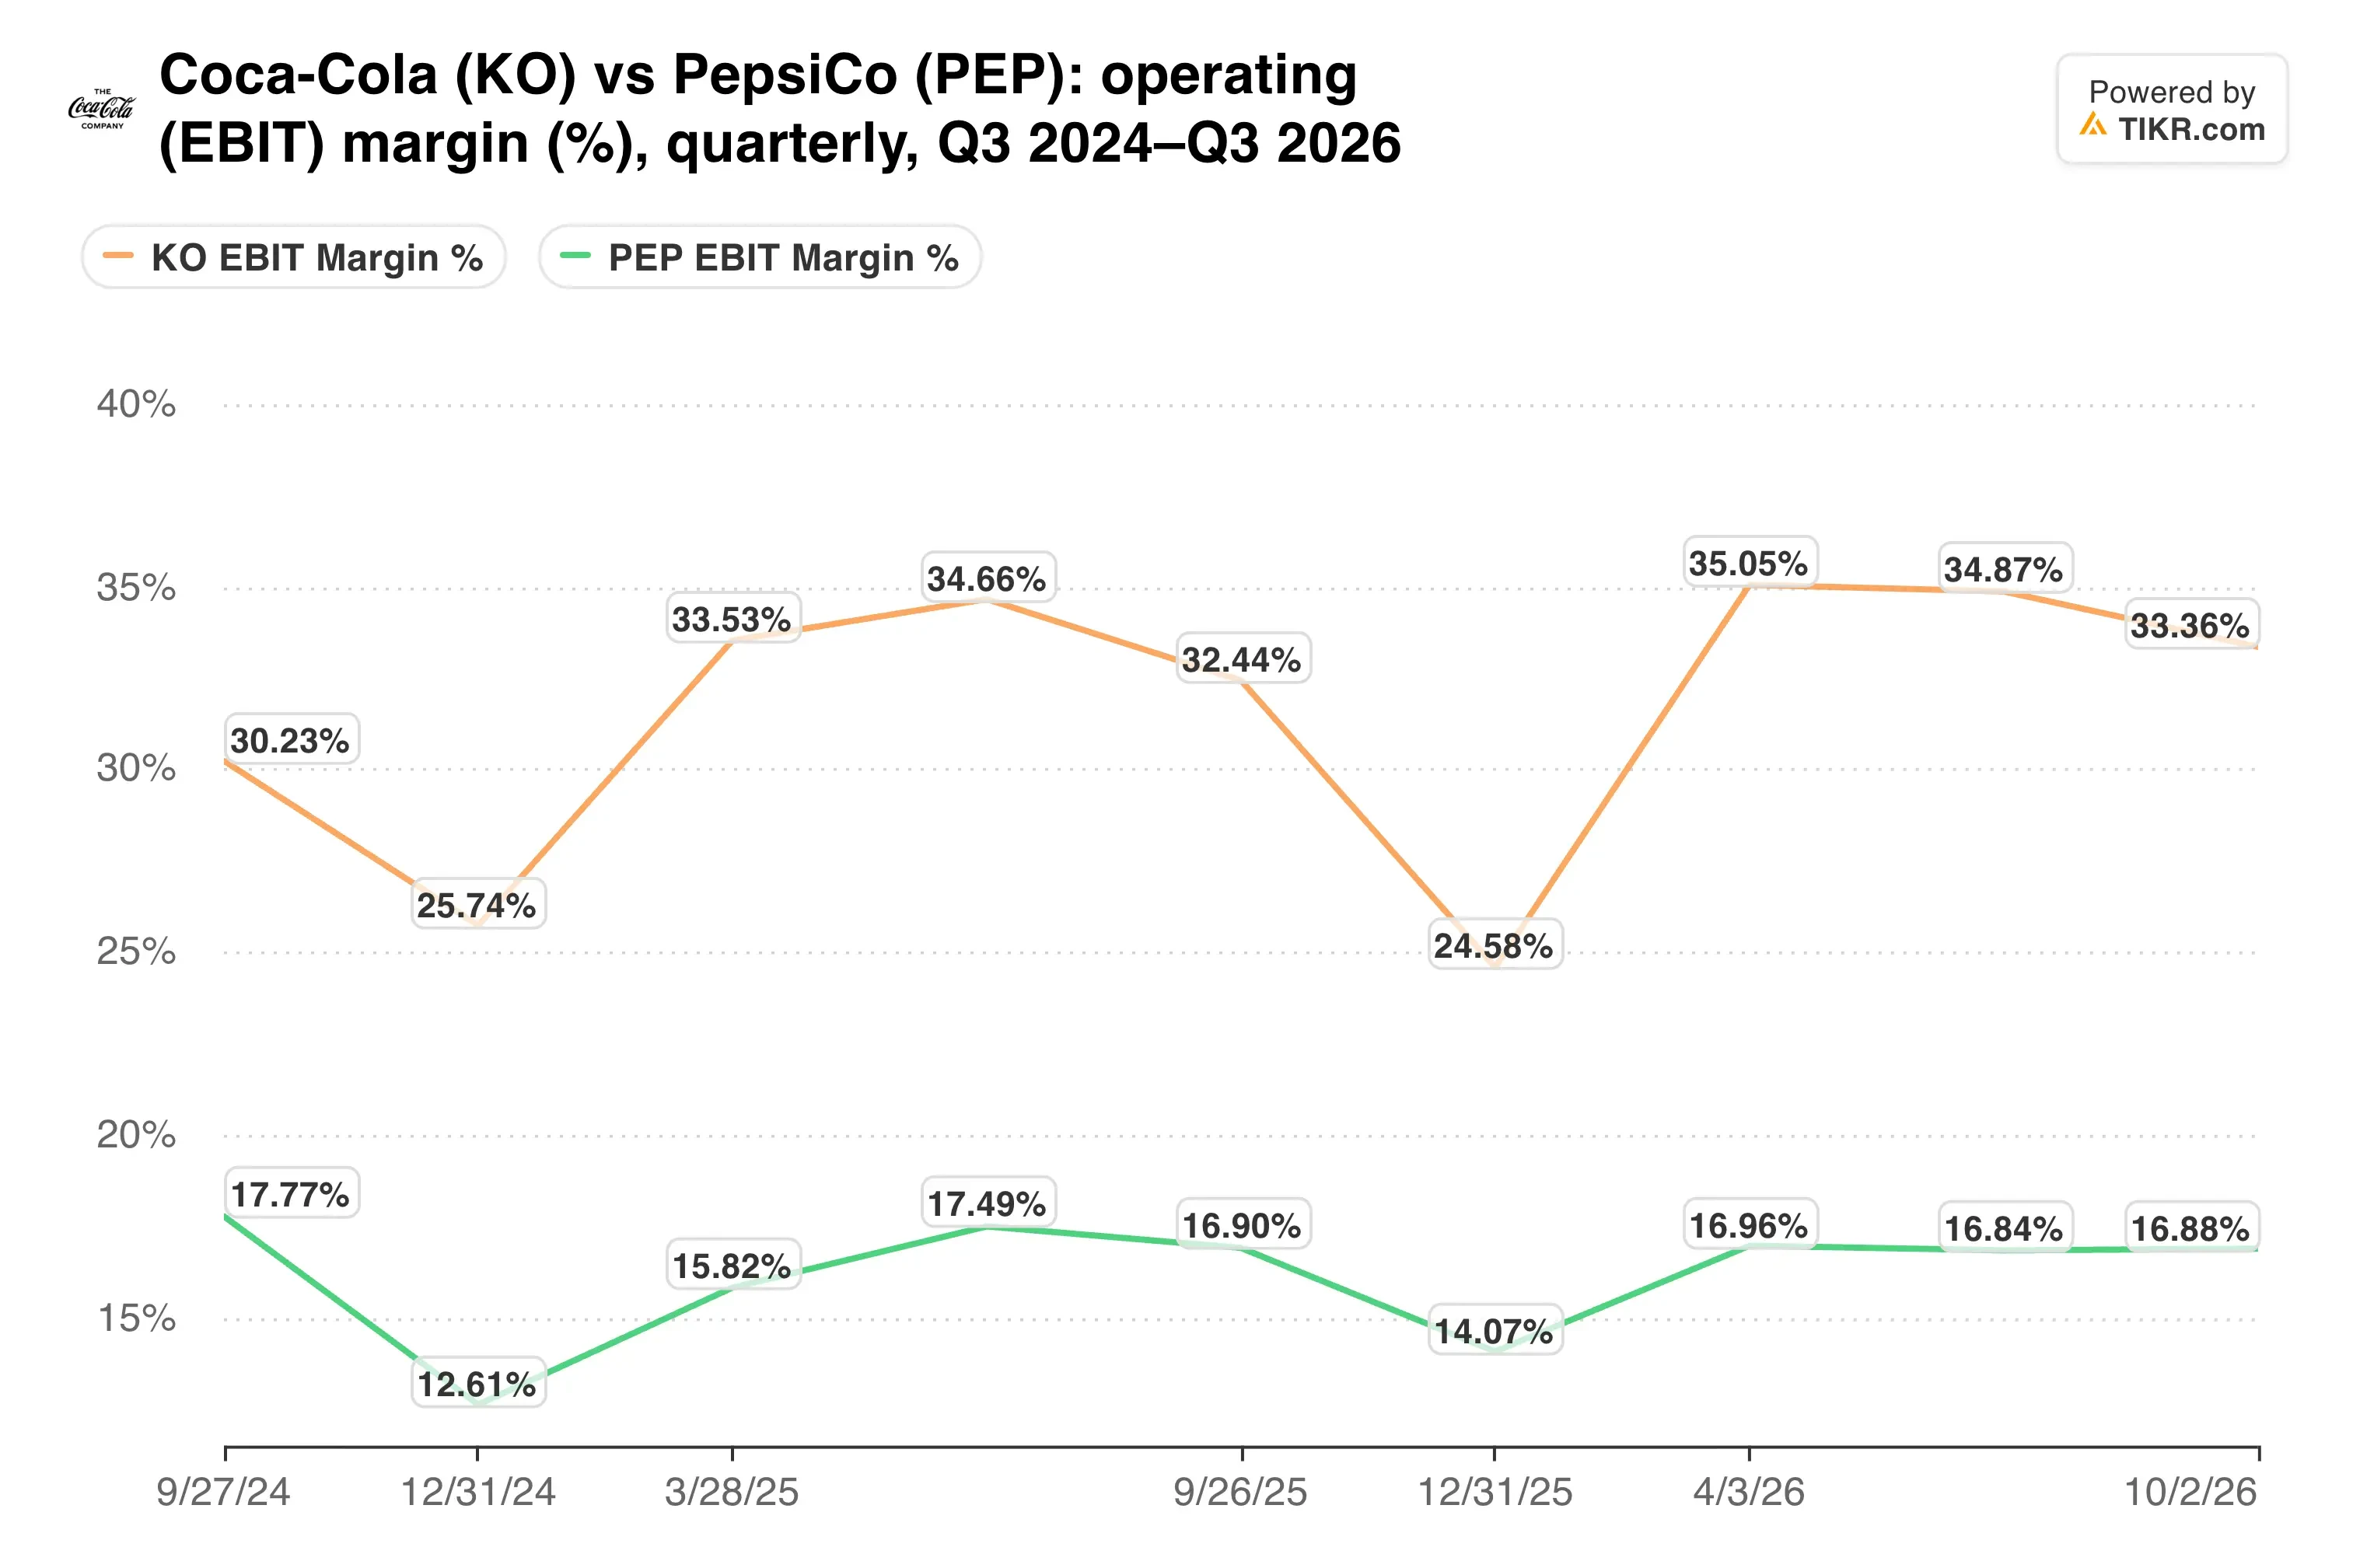
Coca-Cola’s 33.4% operating margin this quarter is roughly double PepsiCo’s 16.9%. Selling concentrate to bottlers keeps that gap wide, even when volume softens.
TIKR tracks 26 analysts on Coca-Cola. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coca-Cola, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coca-Cola’s Analyst Ratings
The premium leaves little room
Chief executive Henrique Braun did not sound triumphant. “Geopolitical disruptions affect several parts of the world, cost pressures have accelerated, and all of these have an impact on many consumers,” he said on the earnings call.
Executives also warned that consumer pressure could last into 2027. Meanwhile, the fourth quarter has six fewer days than last year, which will weigh on reported results.
Investors have paid up for that steadiness anyway.
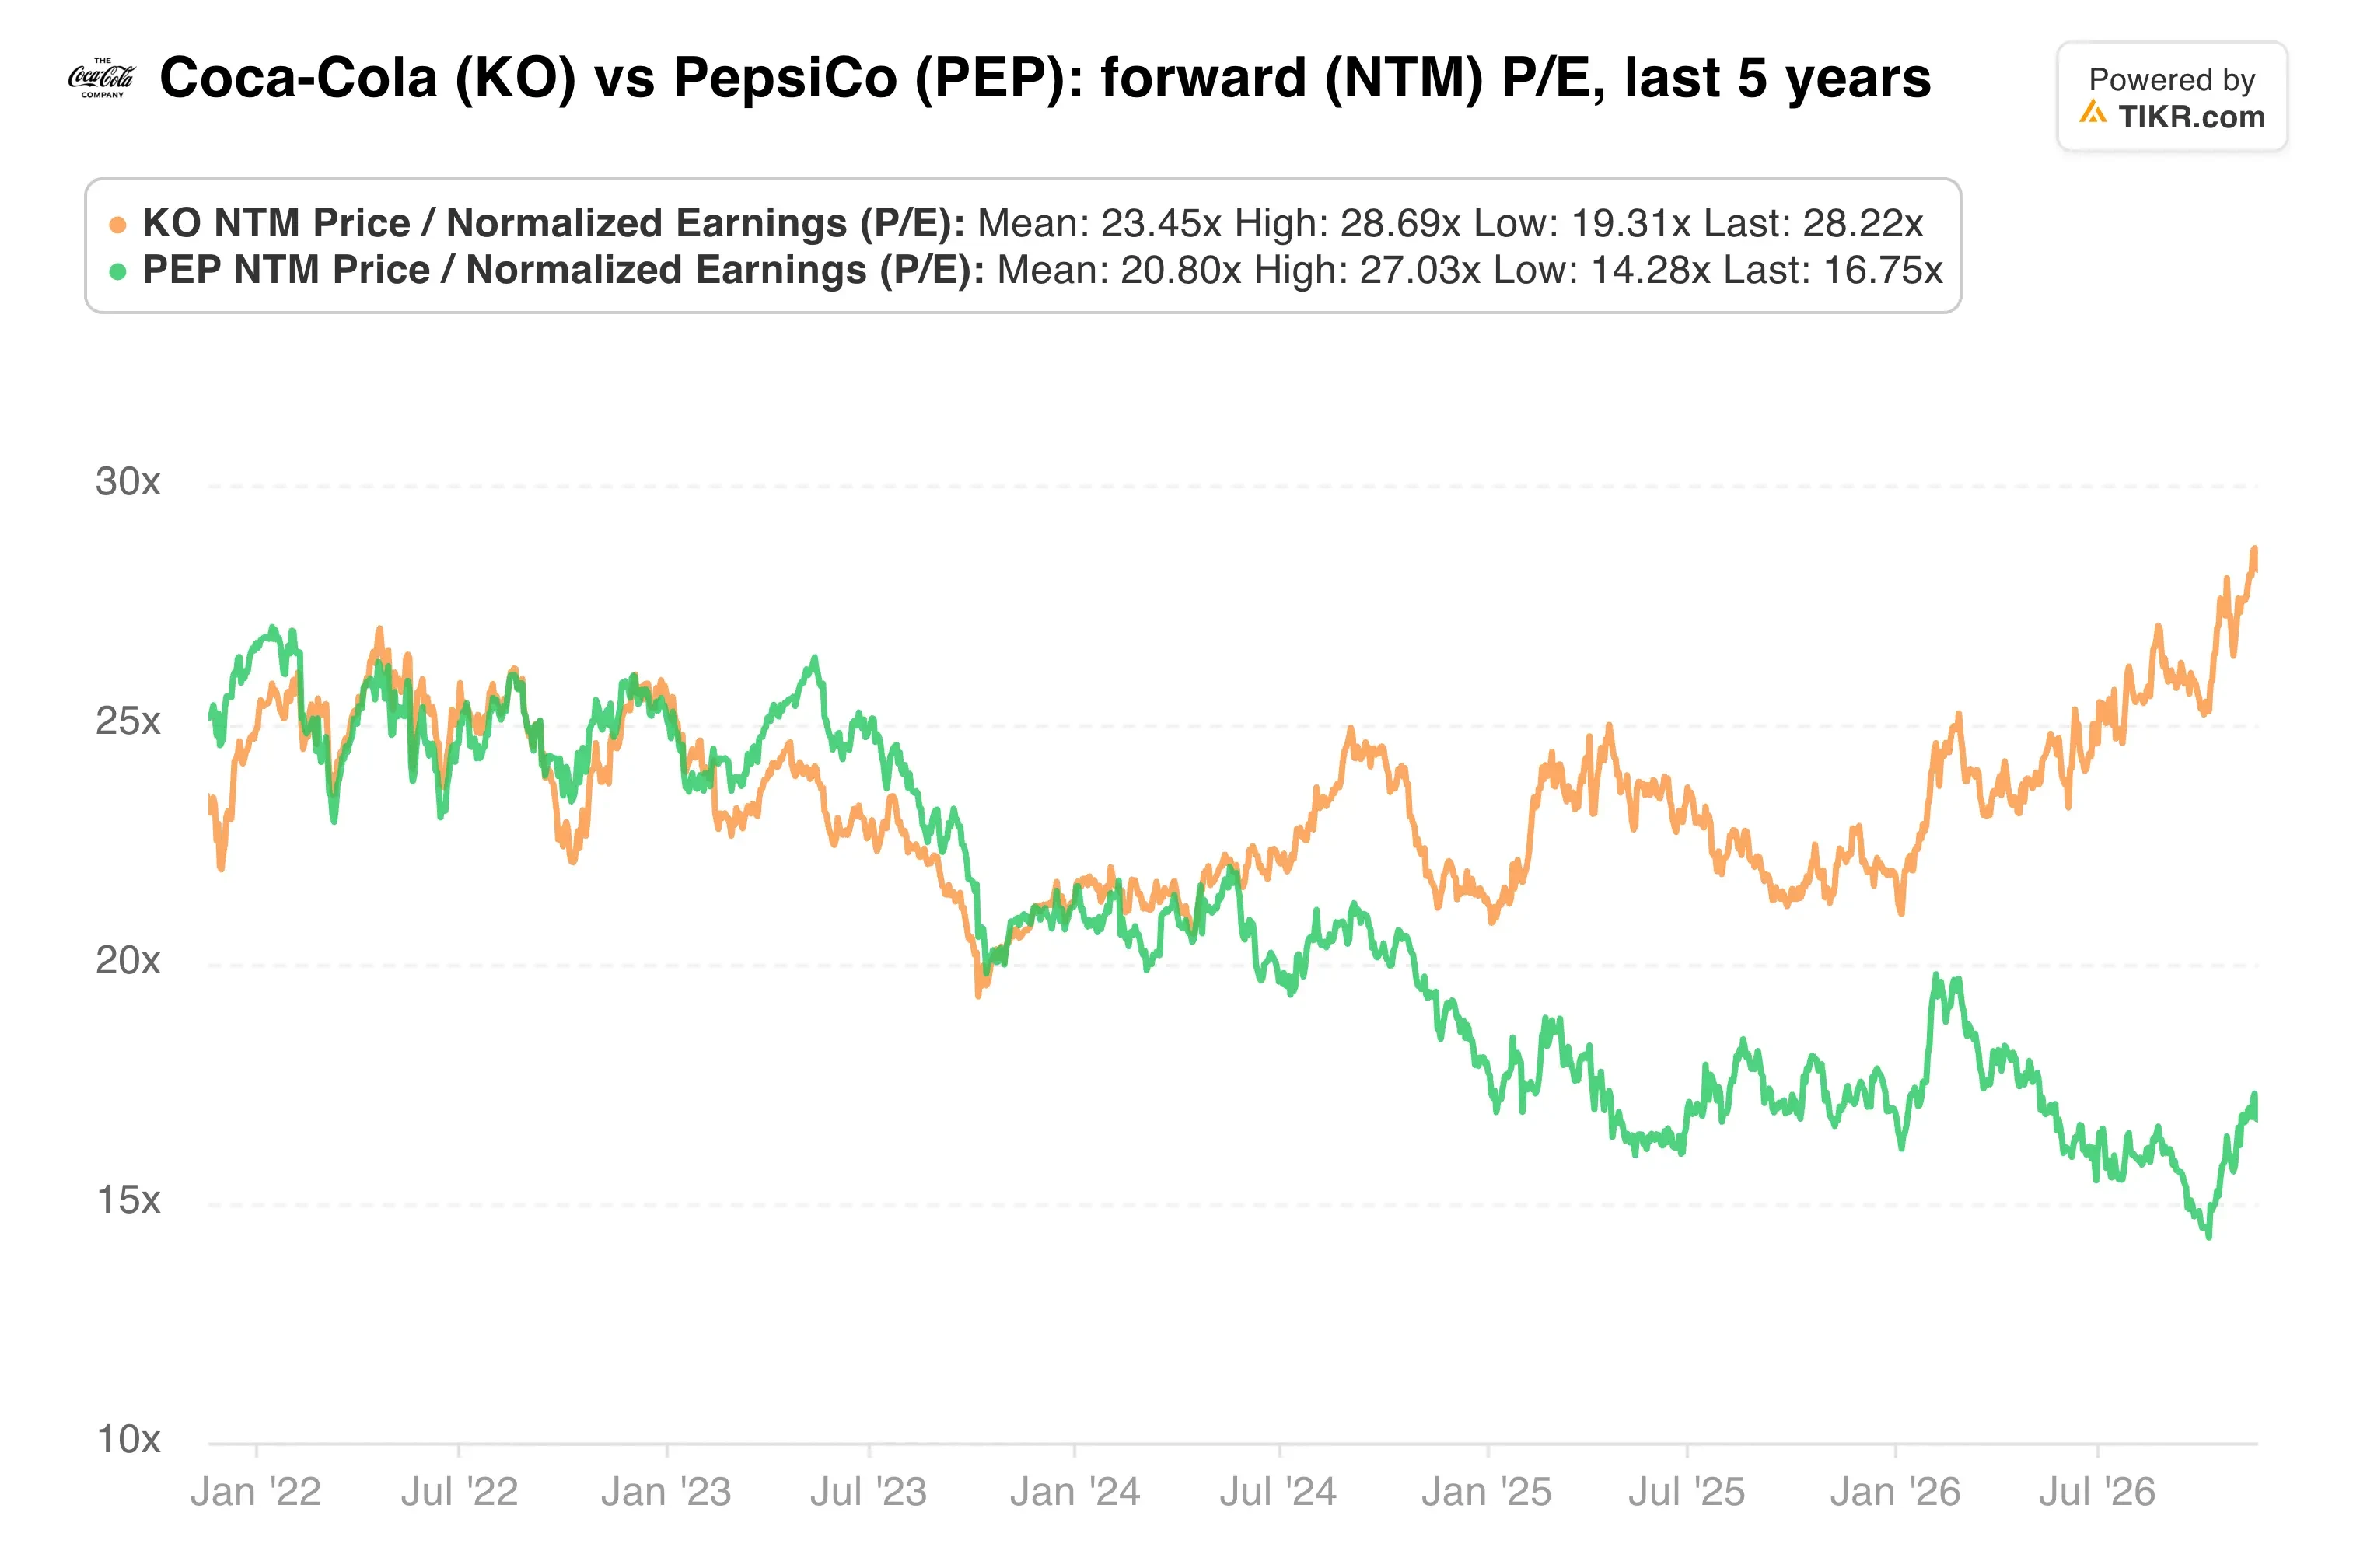
Coca-Cola’s forward multiple has expanded over the past year and now sits well above PepsiCo’s. That premium assumes the volume streak keeps going, so the stock is leaning heavily on its reputation.
My take: This was a genuinely strong quarter, and the KFC win patches a real weak spot in U.S. restaurants. Still, 1% price/mix tells me pricing power is fading just as costs climb. At this valuation, I’d hold rather than add.
The next checkpoint is fourth-quarter results, expected in February, when Coca-Cola gives its first 2027 guidance. That outlook will show whether volume can keep carrying earnings while costs rise.
So what is Coca-Cola stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coca-Cola could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!