


Key Takeaways
- DraftKings shares have lost 42% in the year to Oct. 7. That day, Guggenheim cut its price target to $30 from $33 and kept its Buy rating.
- The $30 target implies 51% upside, but it’s below the Street’s average target of $34.
- Over the last 90 days, analysts cut their 2026 earnings estimate to $0.88 a share from $1.07, while their 2027 estimate held near $1.68.
- The call looks plausible but stretched: it needs 25.2x forward earnings, against 16.1x on Oct. 7, so it depends on 2027’s earnings showing up.
DraftKings (DKNG) shares have lost 42% in the year to their Oct. 7 close, and even analysts who like the stock are cutting their targets.
On Oct. 7, Guggenheim’s Curry Baker reiterated his Buy rating and cut his price target to $30 from $33. That’s still 51% above the $19.89 the stock traded at on Oct. 8.
Blame prediction markets (and the Knicks)
Shares closed 2025 at $34.46 and ended March 2026 at $21.62. As CEO Jason Robins put it on the Aug. 7 earnings call, “everyone was worried about Predictions cannibalization.”
On Aug. 6, DraftKings reported that second-quarter revenue fell 5% from a year earlier to $1.44 billion. CFO Alan Ellingson blamed June’s bad betting outcomes mainly on the Knicks’ championship.
DraftKings kept its 2026 adjusted EBITDA guidance of $700 million to $900 million, which already includes an extra $200 million to $300 million of spending on Predictions.
The stock closed at $19 on Sept. 30, after an 8% drop on prediction-market fears that TIKR covered.
Guggenheim trims, but stays a buyer
Guggenheim lowered its target after updating its model for the third quarter.
The bull case rests on the core business. In the Aug. 6 release, Ellingson said it “remains on track to generate approximately $1 billion of Adjusted EBITDA this year.”
Does $30 add up?
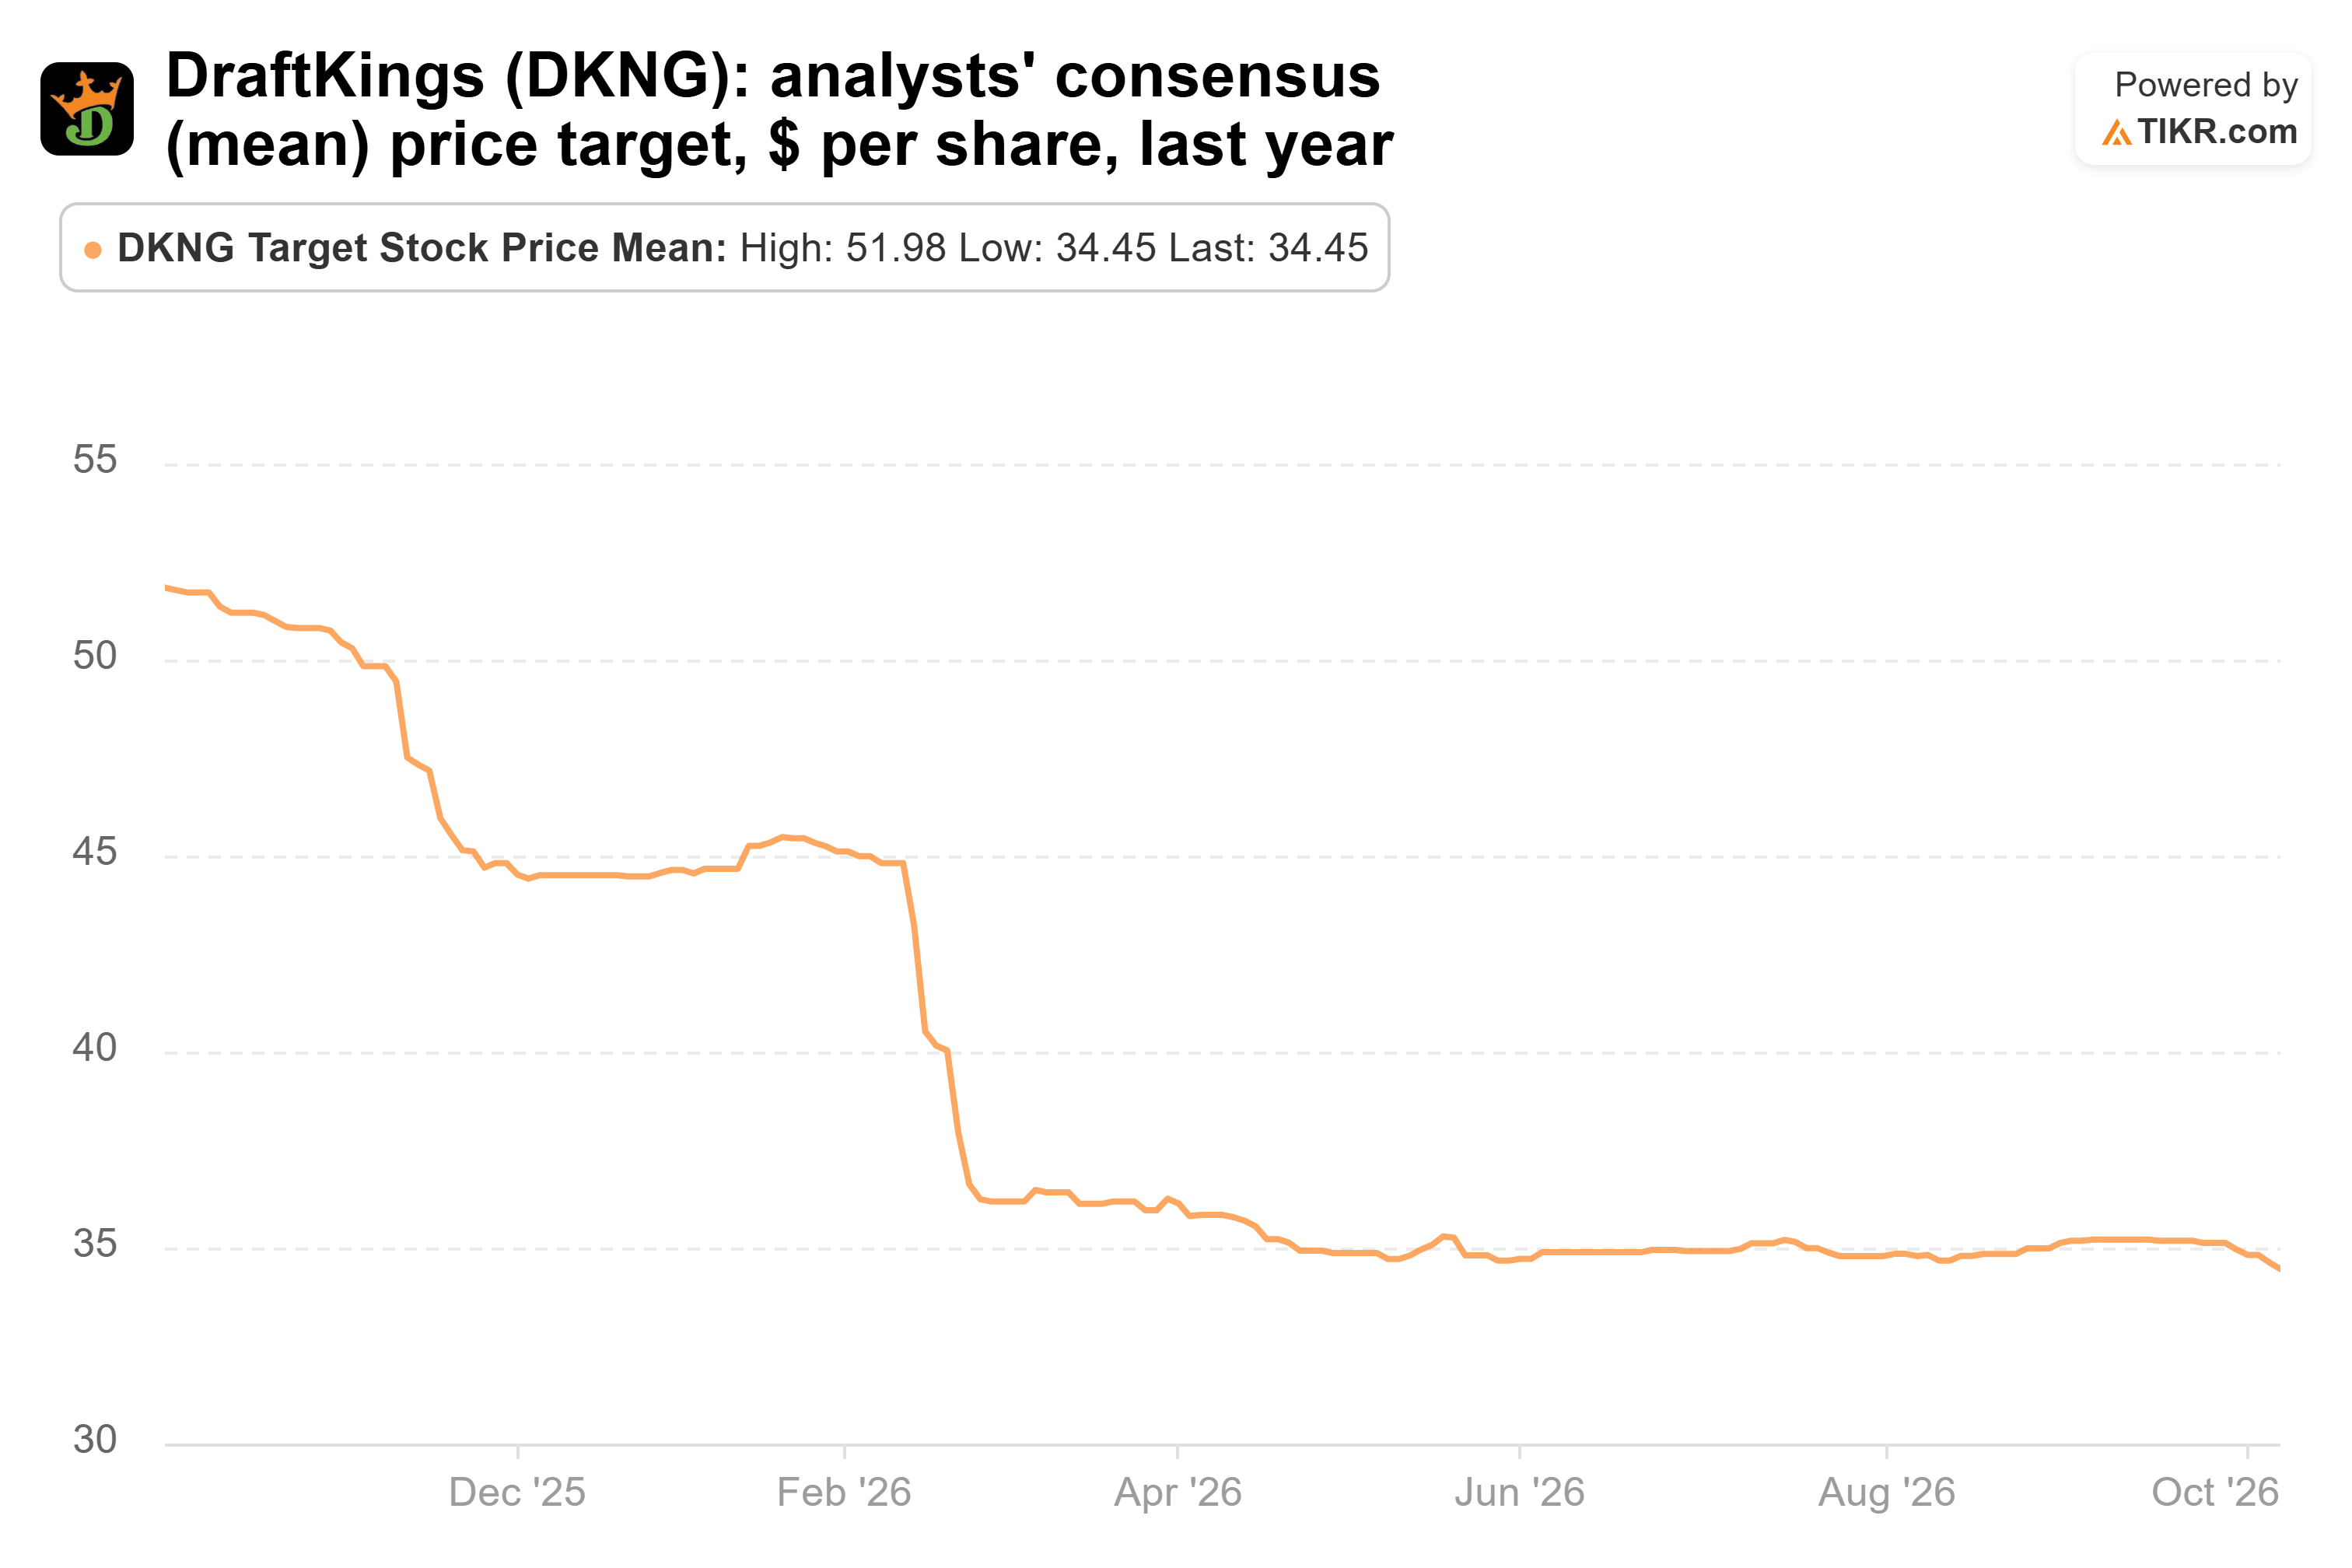
The average analyst target has fallen from $52 on Oct. 8, 2025, to $34 a year later, so Guggenheim’s $30 is below the consensus.
Analysts still see normalized EPS climbing from $0.66 in 2025 to $0.88 in 2026 and $1.68 in 2027.
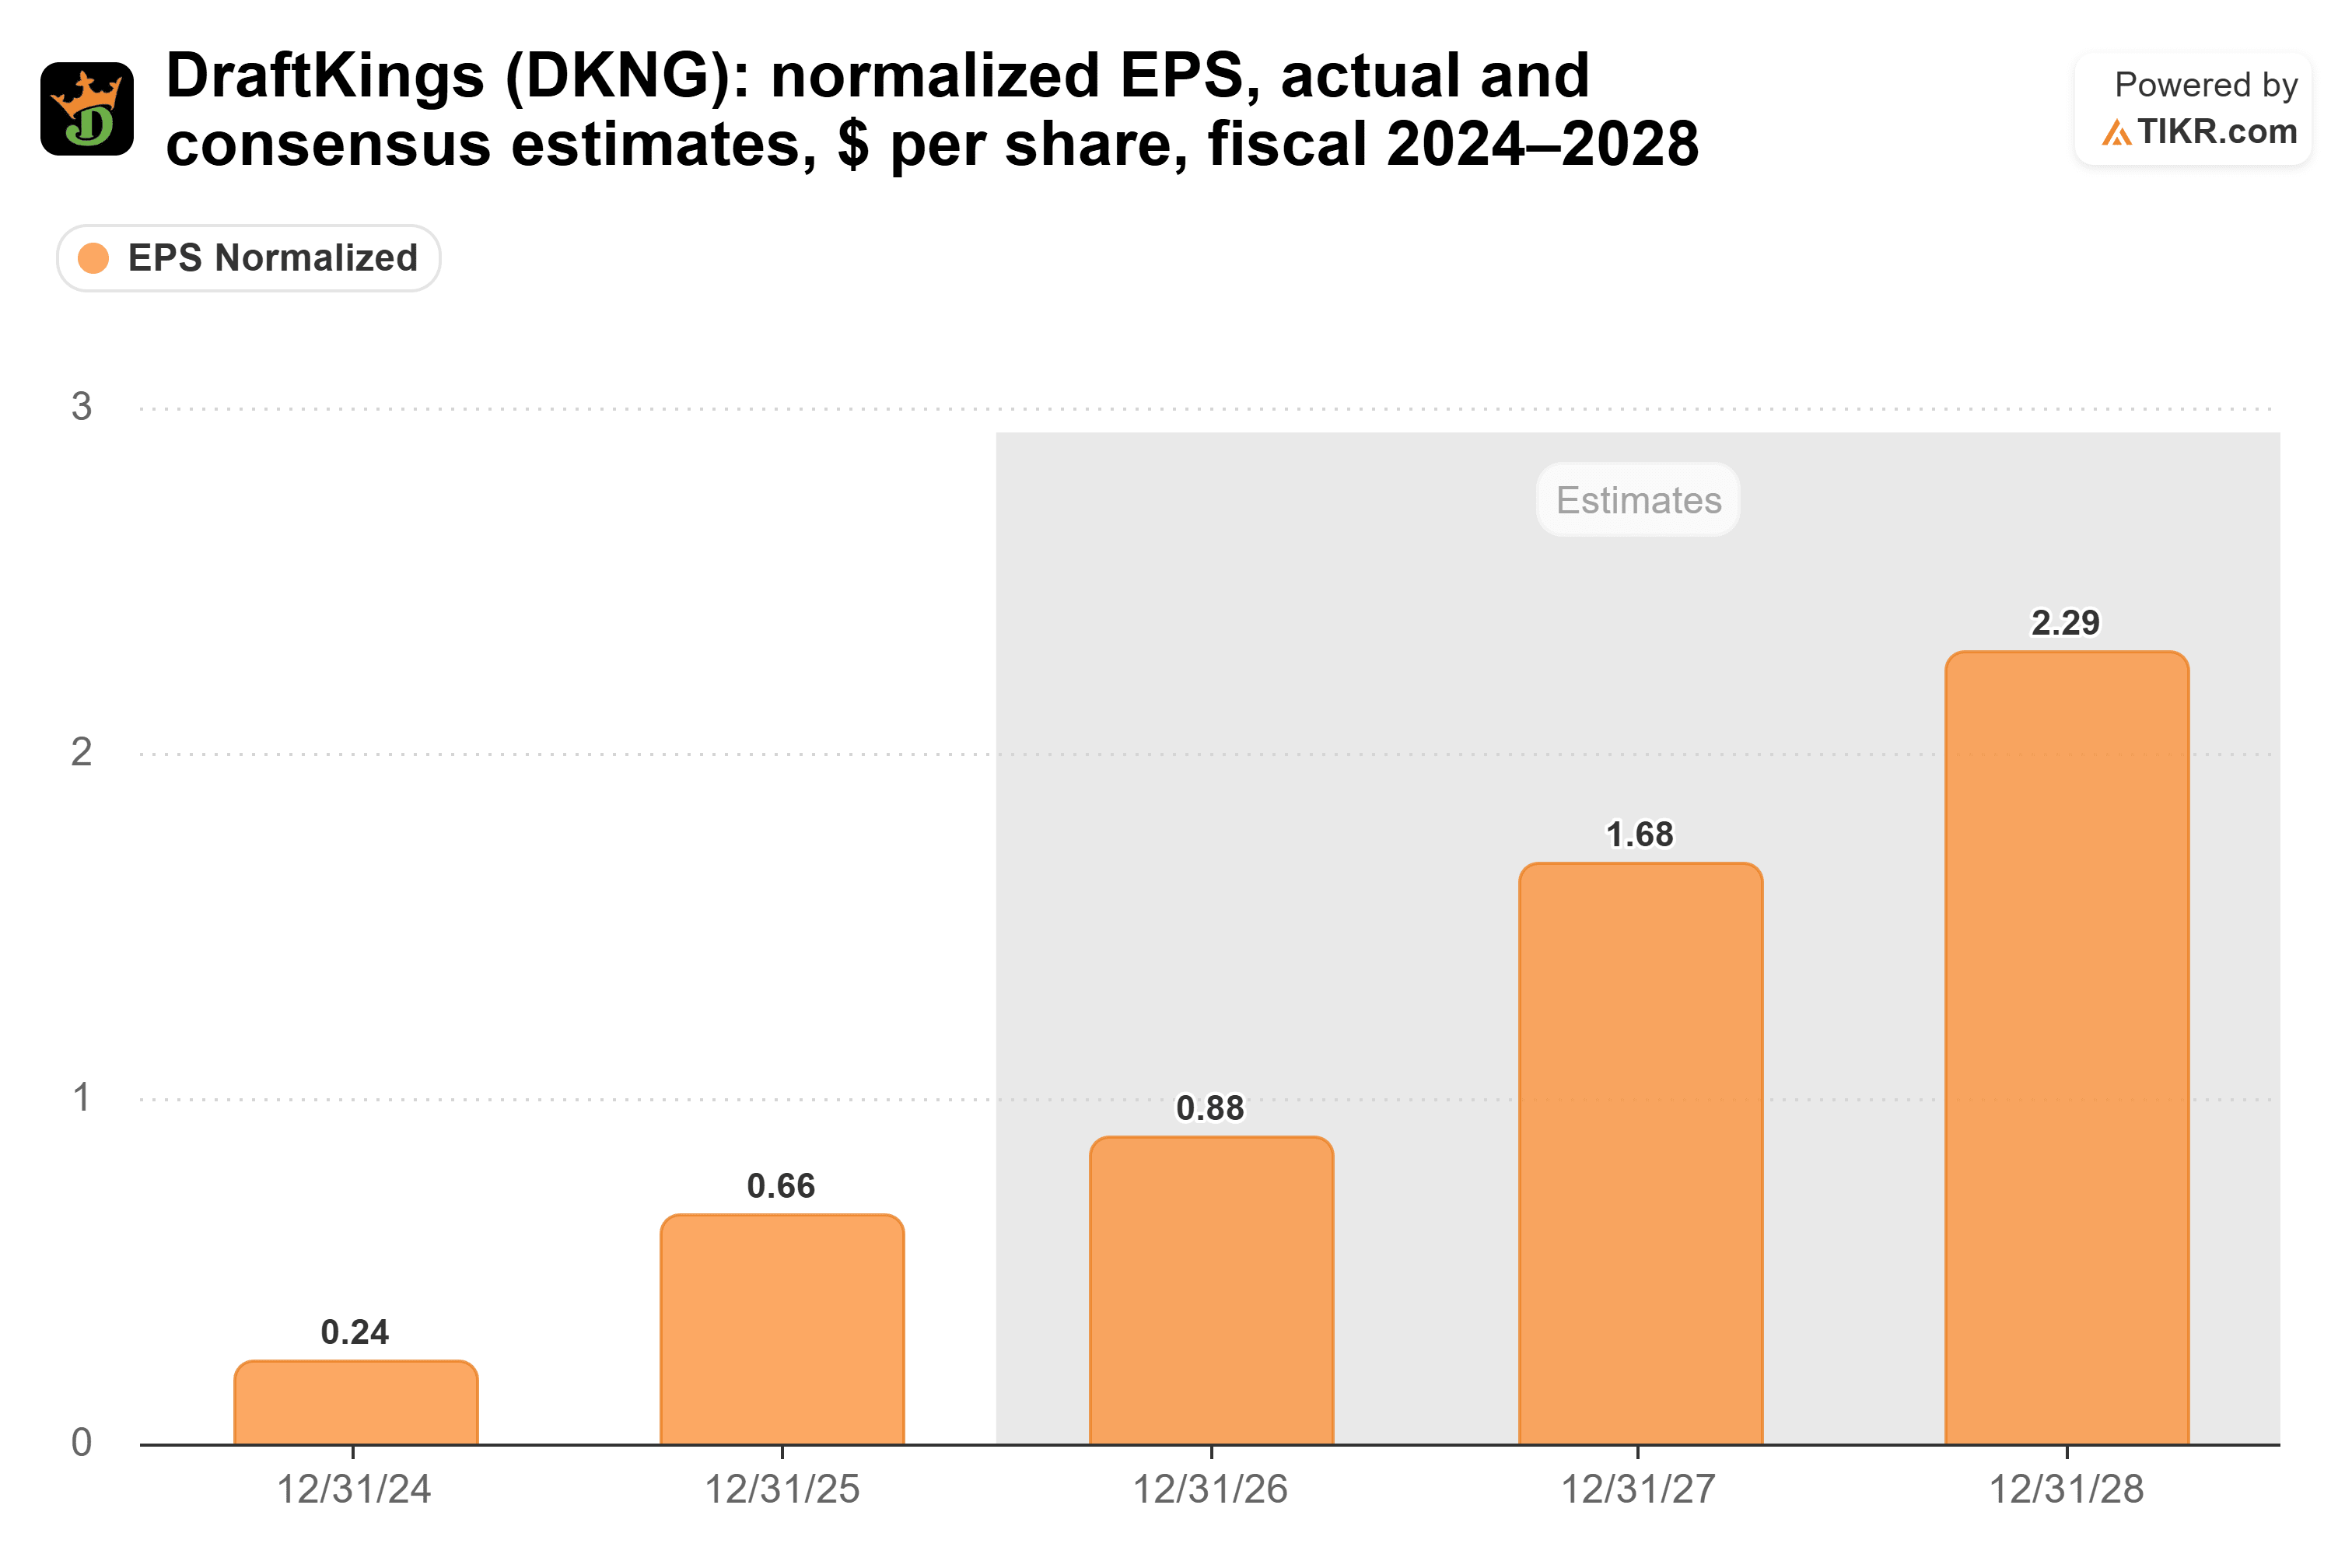
But 90 days ago, the 2026 estimate was $1.07 and the 2027 estimate was $1.71. So analysts cut this year’s number and barely touched next year’s.
The stock traded at 16.1x forward earnings at its Oct. 7 close, above its 5-year average of 12.9x.

(That average includes years when analysts expected losses, so it’s only a rough guide.)
Guggenheim’s $30 target, divided by the $1.19 of earnings analysts expect over the next twelve months, works out to 25.2x.
Plausible, if 2027 shows up
The risk is spending. On the call, Robins said that if customer acquisition stayed this strong into the fall, spending more “would be the wise move.”
I think Guggenheim’s call is plausible but stretched. A year from now, the stock will be priced on 2027’s earnings, so $30 depends on that $1.68 estimate, the one that has held up.
DraftKings’ third-quarter report is the test. If guidance holds and Predictions spending stays inside its range, $30 starts to look a lot more reasonable.
So what is DraftKings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DraftKings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


