Key Takeaways
- AppLovin shares have lost 56% over the past year, but Needham kept its Buy rating and $475 price target on Oct. 6, implying 70% upside.
- A second-quarter revenue miss sent shares down 19% in a day in August, after management said its gaming ad models had improved less than usual.
- Needham’s target works out to 25.4x next-twelve-months earnings, close to the stock’s five-year average of 25.9x and well above today’s 15x.
- The call looks plausible but stretched for now, since analysts are trimming estimates and a securities class action is pending.
AppLovin (APP) shares have lost 56% over the past year. Needham still rates the stock a Buy, and its $475 price target implies 70% upside from today’s $280.12.
A rare miss, then a pile-on
The slide picked up after second-quarter results on Aug. 5. Revenue rose 53% from a year earlier to $1.92 billion, just short of the $1.94 billion Wall Street expected, and shares fell 19% the next day.
On the call, CEO Adam Foroughi pointed to slower gains in AppLovin’s gaming ad models: “In this case, in Q2, we didn’t have the same amount of uplift that we normally have in any other prior quarter.”
Analysts have grown warier since. Wells Fargo called a recent pickup in AppLovin Pixel adoption a “false start” on Sept. 30. On Oct. 8, Jefferies kept its Buy but cut its target to $375 from $550 after a mobile gaming survey.
Needham is betting on better brands
Needham analyst Bernie McTernan kept his Buy and $475 target on Oct. 6. He pointed to three higher-quality advertisers AppLovin has added: Steve Madden (SHOO), Quince and Thorne. Needham said they’re unlikely to move near-term results, but could spend more over time.
Does $475 add up?
Needham is hardly out on a limb. Its $475 matches the Street’s median target as of Oct. 7, and the mean has fallen from a peak of $744 in January to $490 on Oct. 8.
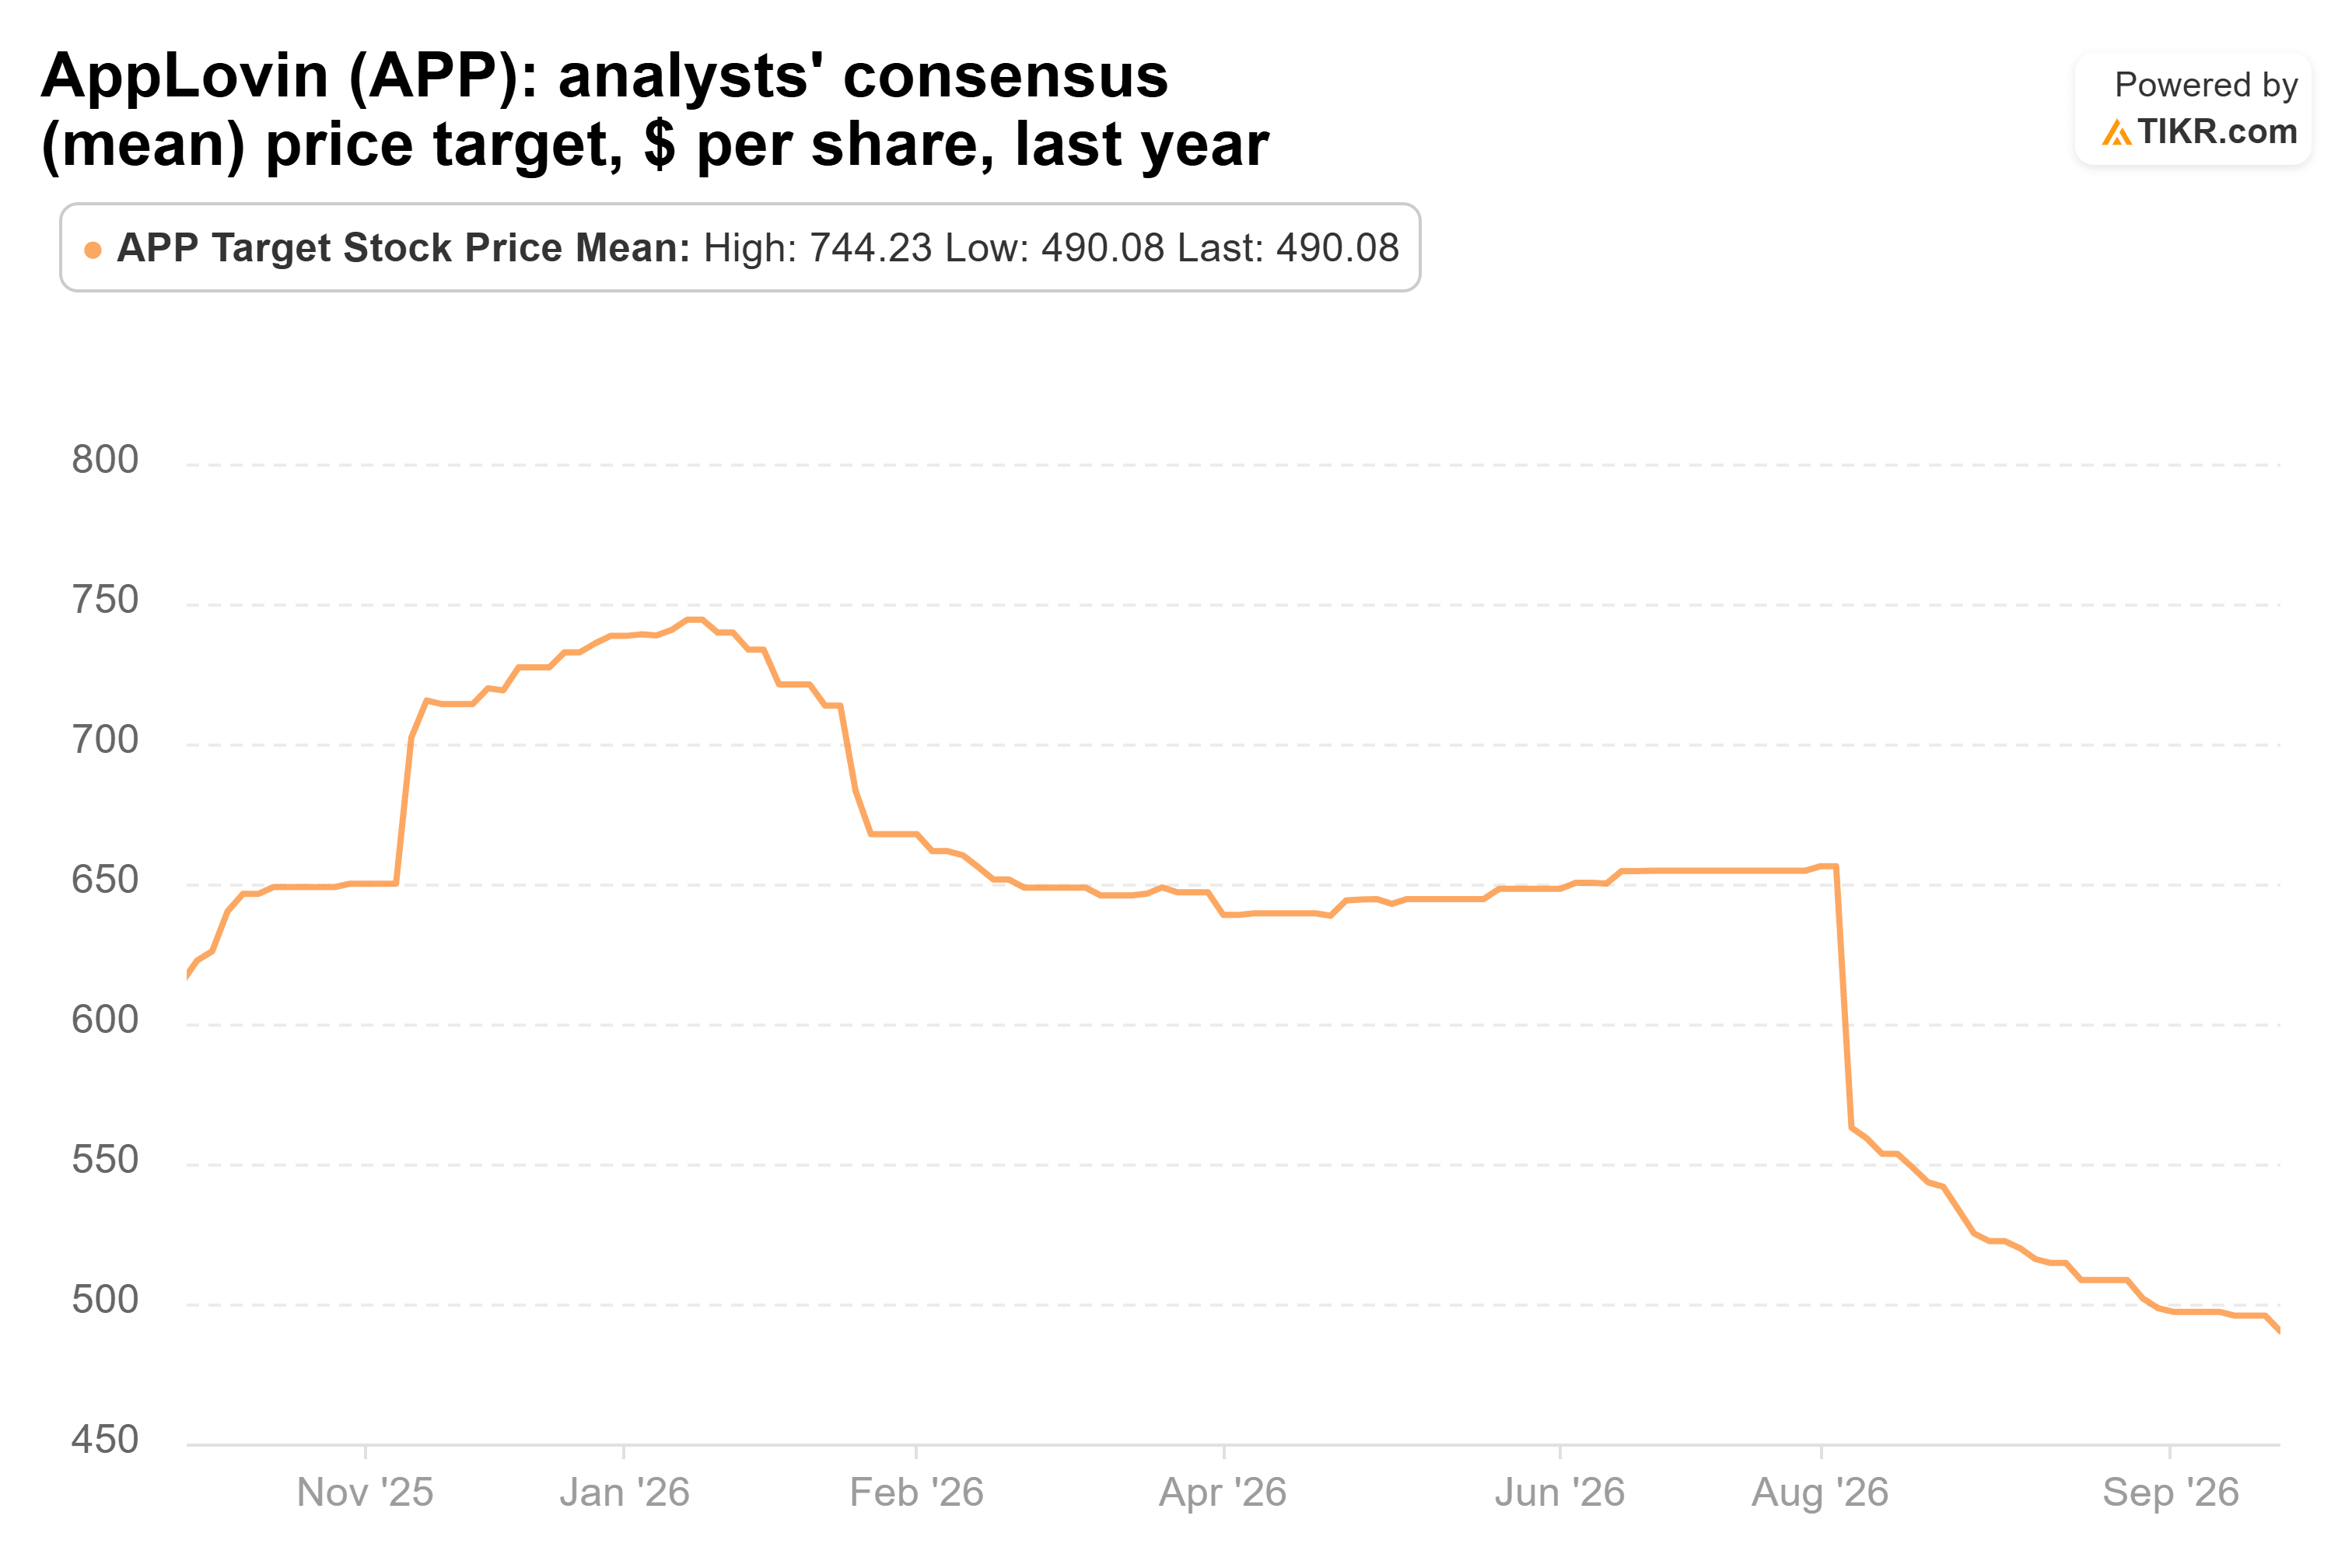
Most ratings are still Buys, but Holds have doubled from three at the end of June to six, and the lowest target is $325.
Analysts still see normalized EPS rising from $10.64 in 2025 to $16.67 this year and $25.87 by 2028.
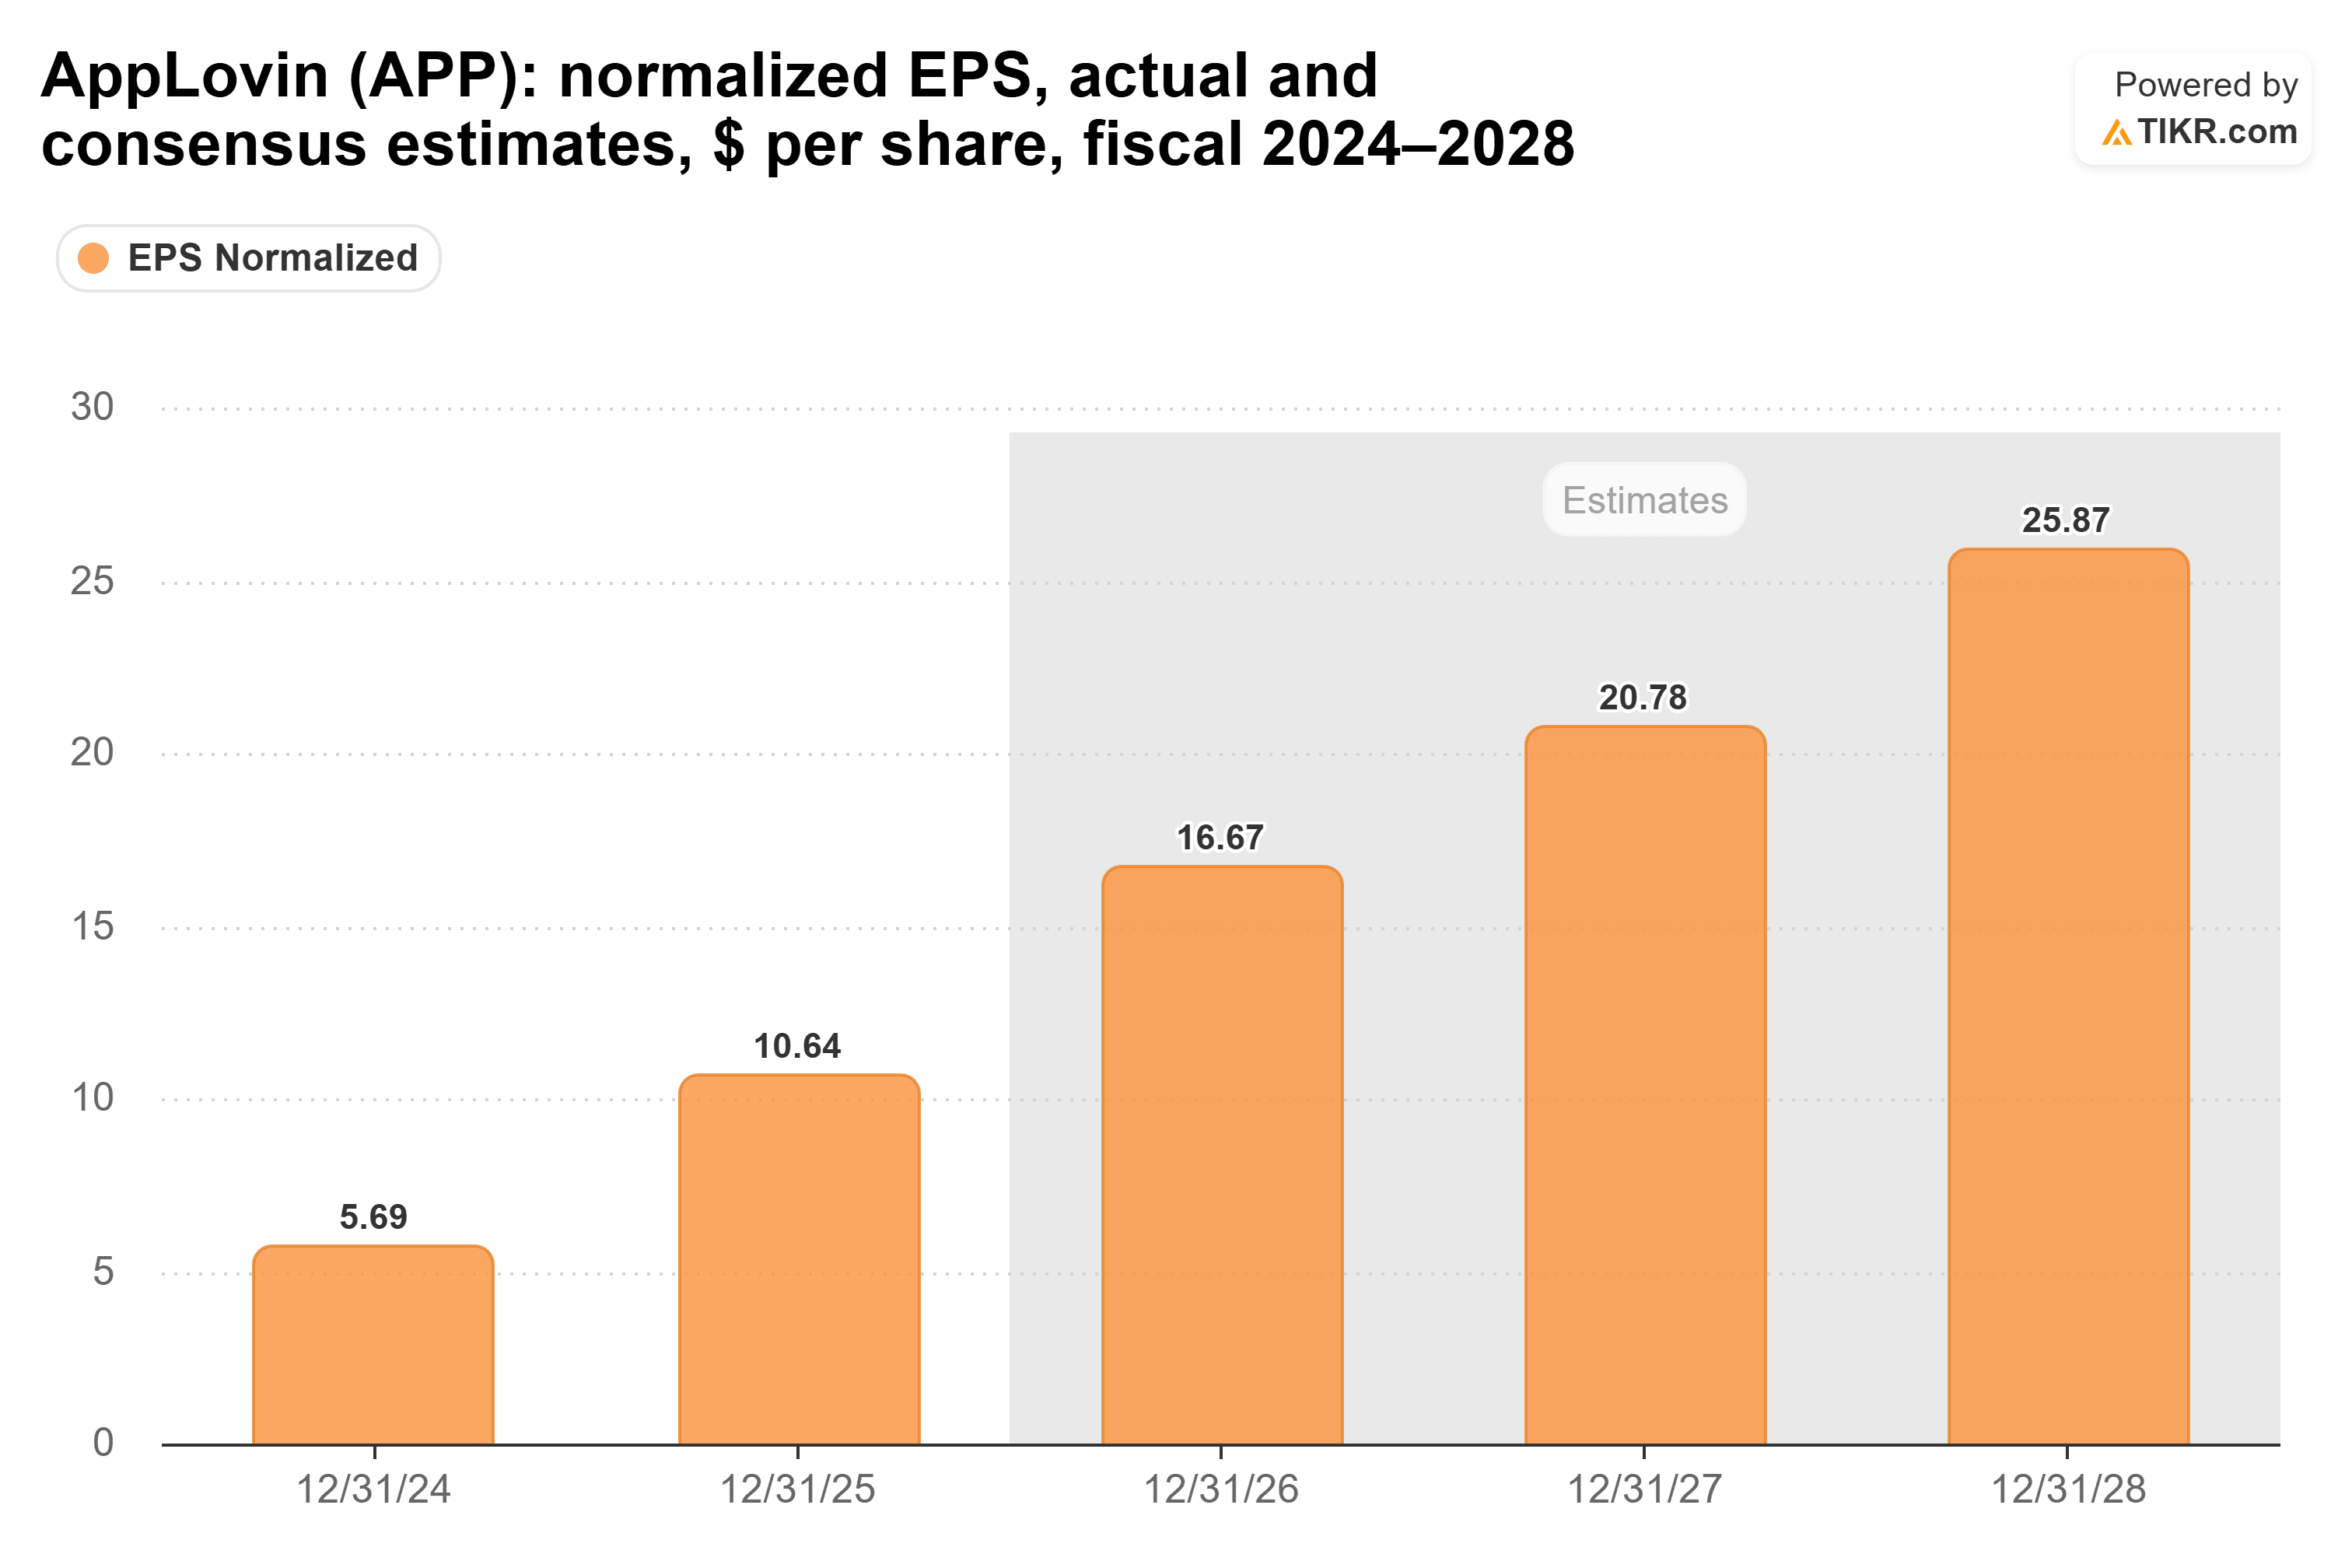
But those estimates are slipping. The 26 analysts Yahoo Finance tracks have cut their 2027 figure from $21.09 a share to $19.95 over the last 90 days. Needham’s note won’t reverse that, since by its own account the new brands won’t show up in near-term results.
What’s changed most is the multiple. At 15x forward earnings at the Oct. 7 close, AppLovin trades well below its five-year average of 25.9x.

Divide Needham’s $475 by the $18.73 a share analysts expect over the next twelve months, and you get 25.4x. So the target only needs the average multiple back on today’s estimates.
The multiple is the whole bet
The risk is that the discount sticks. AppLovin faces a securities class action alleging it misled investors about the strength of its AI models and the feasibility of its AI video creative tool.
I think Needham’s call is plausible, but stretched for now. Getting back to 25x means investors trusting the growth again, which is a hard sell while estimates drift lower and the lawsuit plays out.
The next test is the third-quarter report. AppLovin guided to $2.06 billion to $2.09 billion of revenue, and Foroughi said a model uplift “came right after the quarter,” so “Q3 has started really well.” If the results show it, the multiple has room to recover.
So what is AppLovin stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AppLovin could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!