Key Takeaways
- Goldman Sachs cut its Broadcom price target to $460 from $540 on Nov. 18 and kept its Buy rating, so the target was still 30% above that day’s close.
- Goldman cut the multiple it uses because peer valuations fell. Earnings had nothing to do with it.
- The main risk is Broadcom’s reliance on Anthropic and OpenAI, with Marvell competing for Google’s chip business, though Anthropic’s IPO and TSMC’s planned stakes in both labs ease the worry.
- On fiscal 2028 estimates, $460 is about 15x earnings, which makes Goldman’s target look conservative ahead of Broadcom’s Dec. 9 report.
Broadcom (AVGO) closed at $354.05 on Nov. 18, 27% below its June high, as Goldman Sachs trimmed its price target to $460 from $540. It kept its Buy rating, and the new target sat 30% above the stock. Broadcom then fell with the rest of the chip sector on Nov. 19 and 20.
The worries behind the slide reach past Broadcom. Marvell Technology (MRVL) has its own custom-chip deal with Google, Broadcom’s longest-running XPU customer. And Broadcom’s chipmaker, Taiwan Semiconductor Manufacturing (TSM), just approved investing in Anthropic and OpenAI, the two AI labs Broadcom expects to become its largest XPU customers.
Two Labs and a Backstop
On Broadcom’s Sept. 2 call, CEO Hock Tan said Anthropic “is on track to become our largest XPU customer in 2027,” with OpenAI second in 2028. Broadcom’s quarterly report puts one AI-rack lease backstop at up to about $29 billion, more than its $24.0 billion of cash on Aug. 2. In October, it disclosed a second backstop of up to about $43 billion, tied to Anthropic’s racks.
On Nov. 13, Rothschild & Co Redburn downgraded Broadcom and cut its target to $398 from $595. It said the labs “need to establish sustained primacy over open models and become self-financing in short order.”
Goldman’s Cut Is About the Multiple
Goldman analyst James Schneider now puts a 25x multiple on Broadcom’s earnings, down from 30x, because peer multiples have fallen, according to TheFly. The cut came from the multiple, not from his earnings view.
TIKR Tracks 51 Analysts on Broadcom. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Does $460 Add Up?
Wall Street’s average target has climbed from $396 to $528 over the past year.
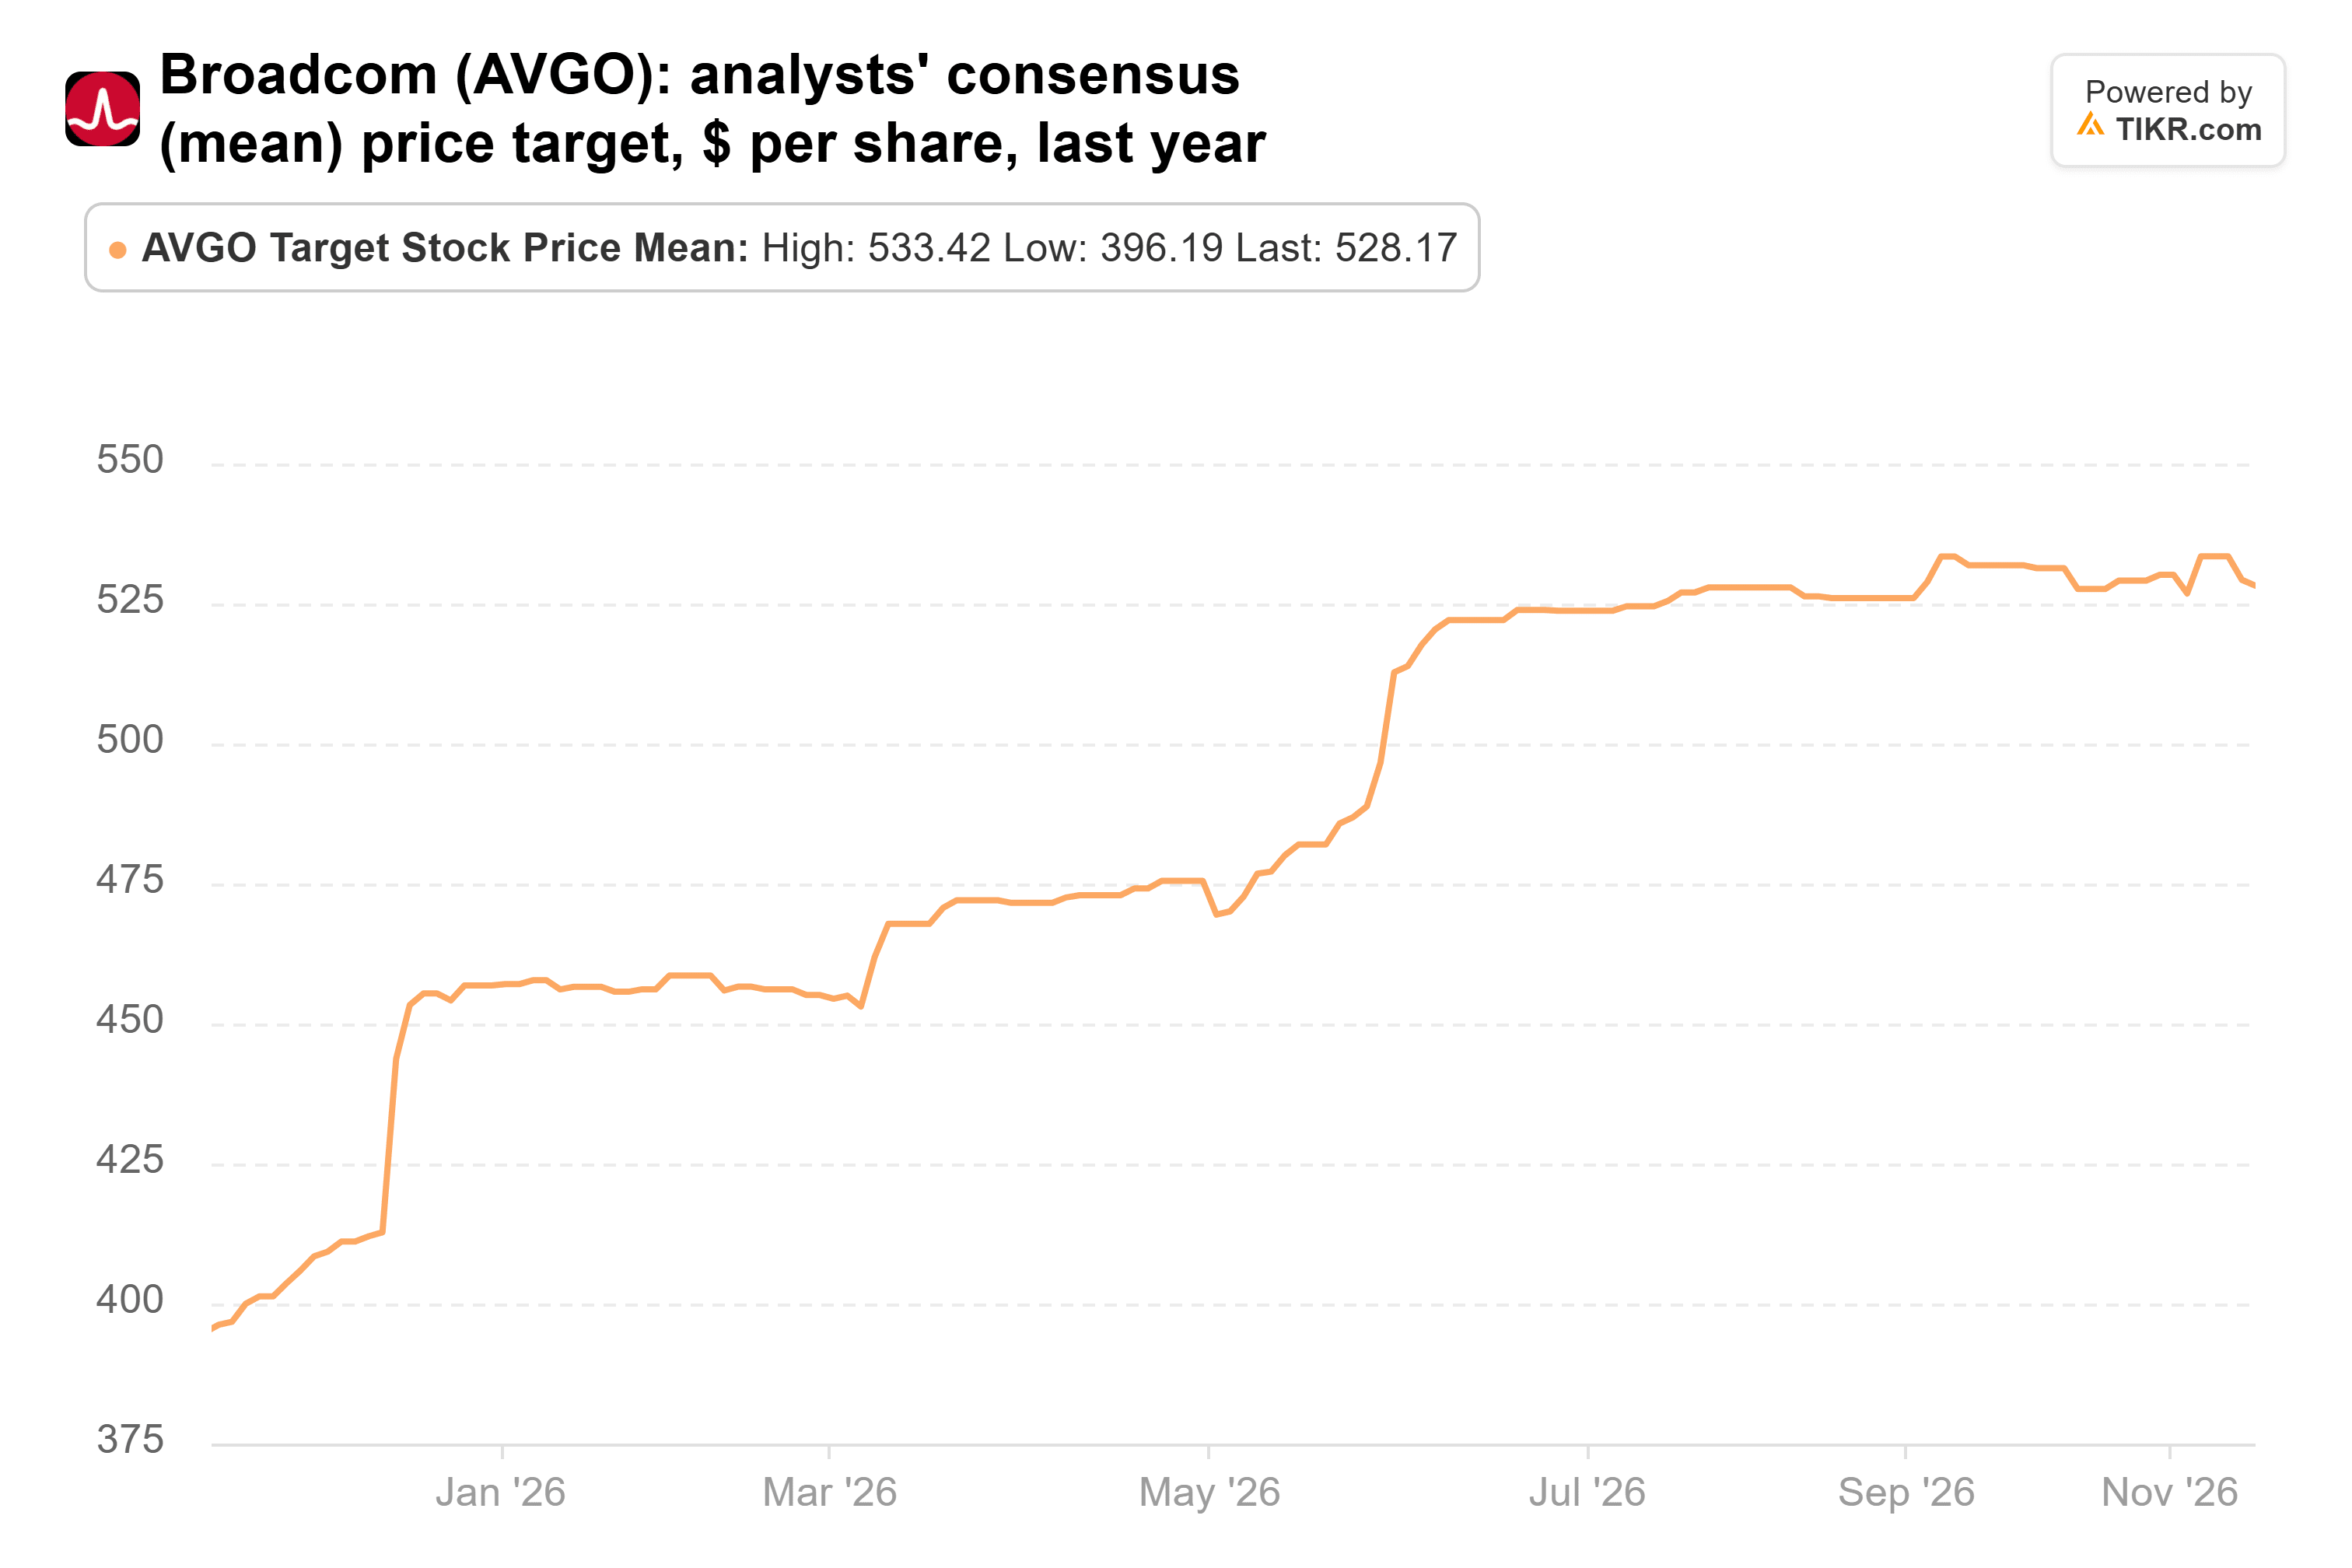
Goldman’s $460 is 13% below that average.
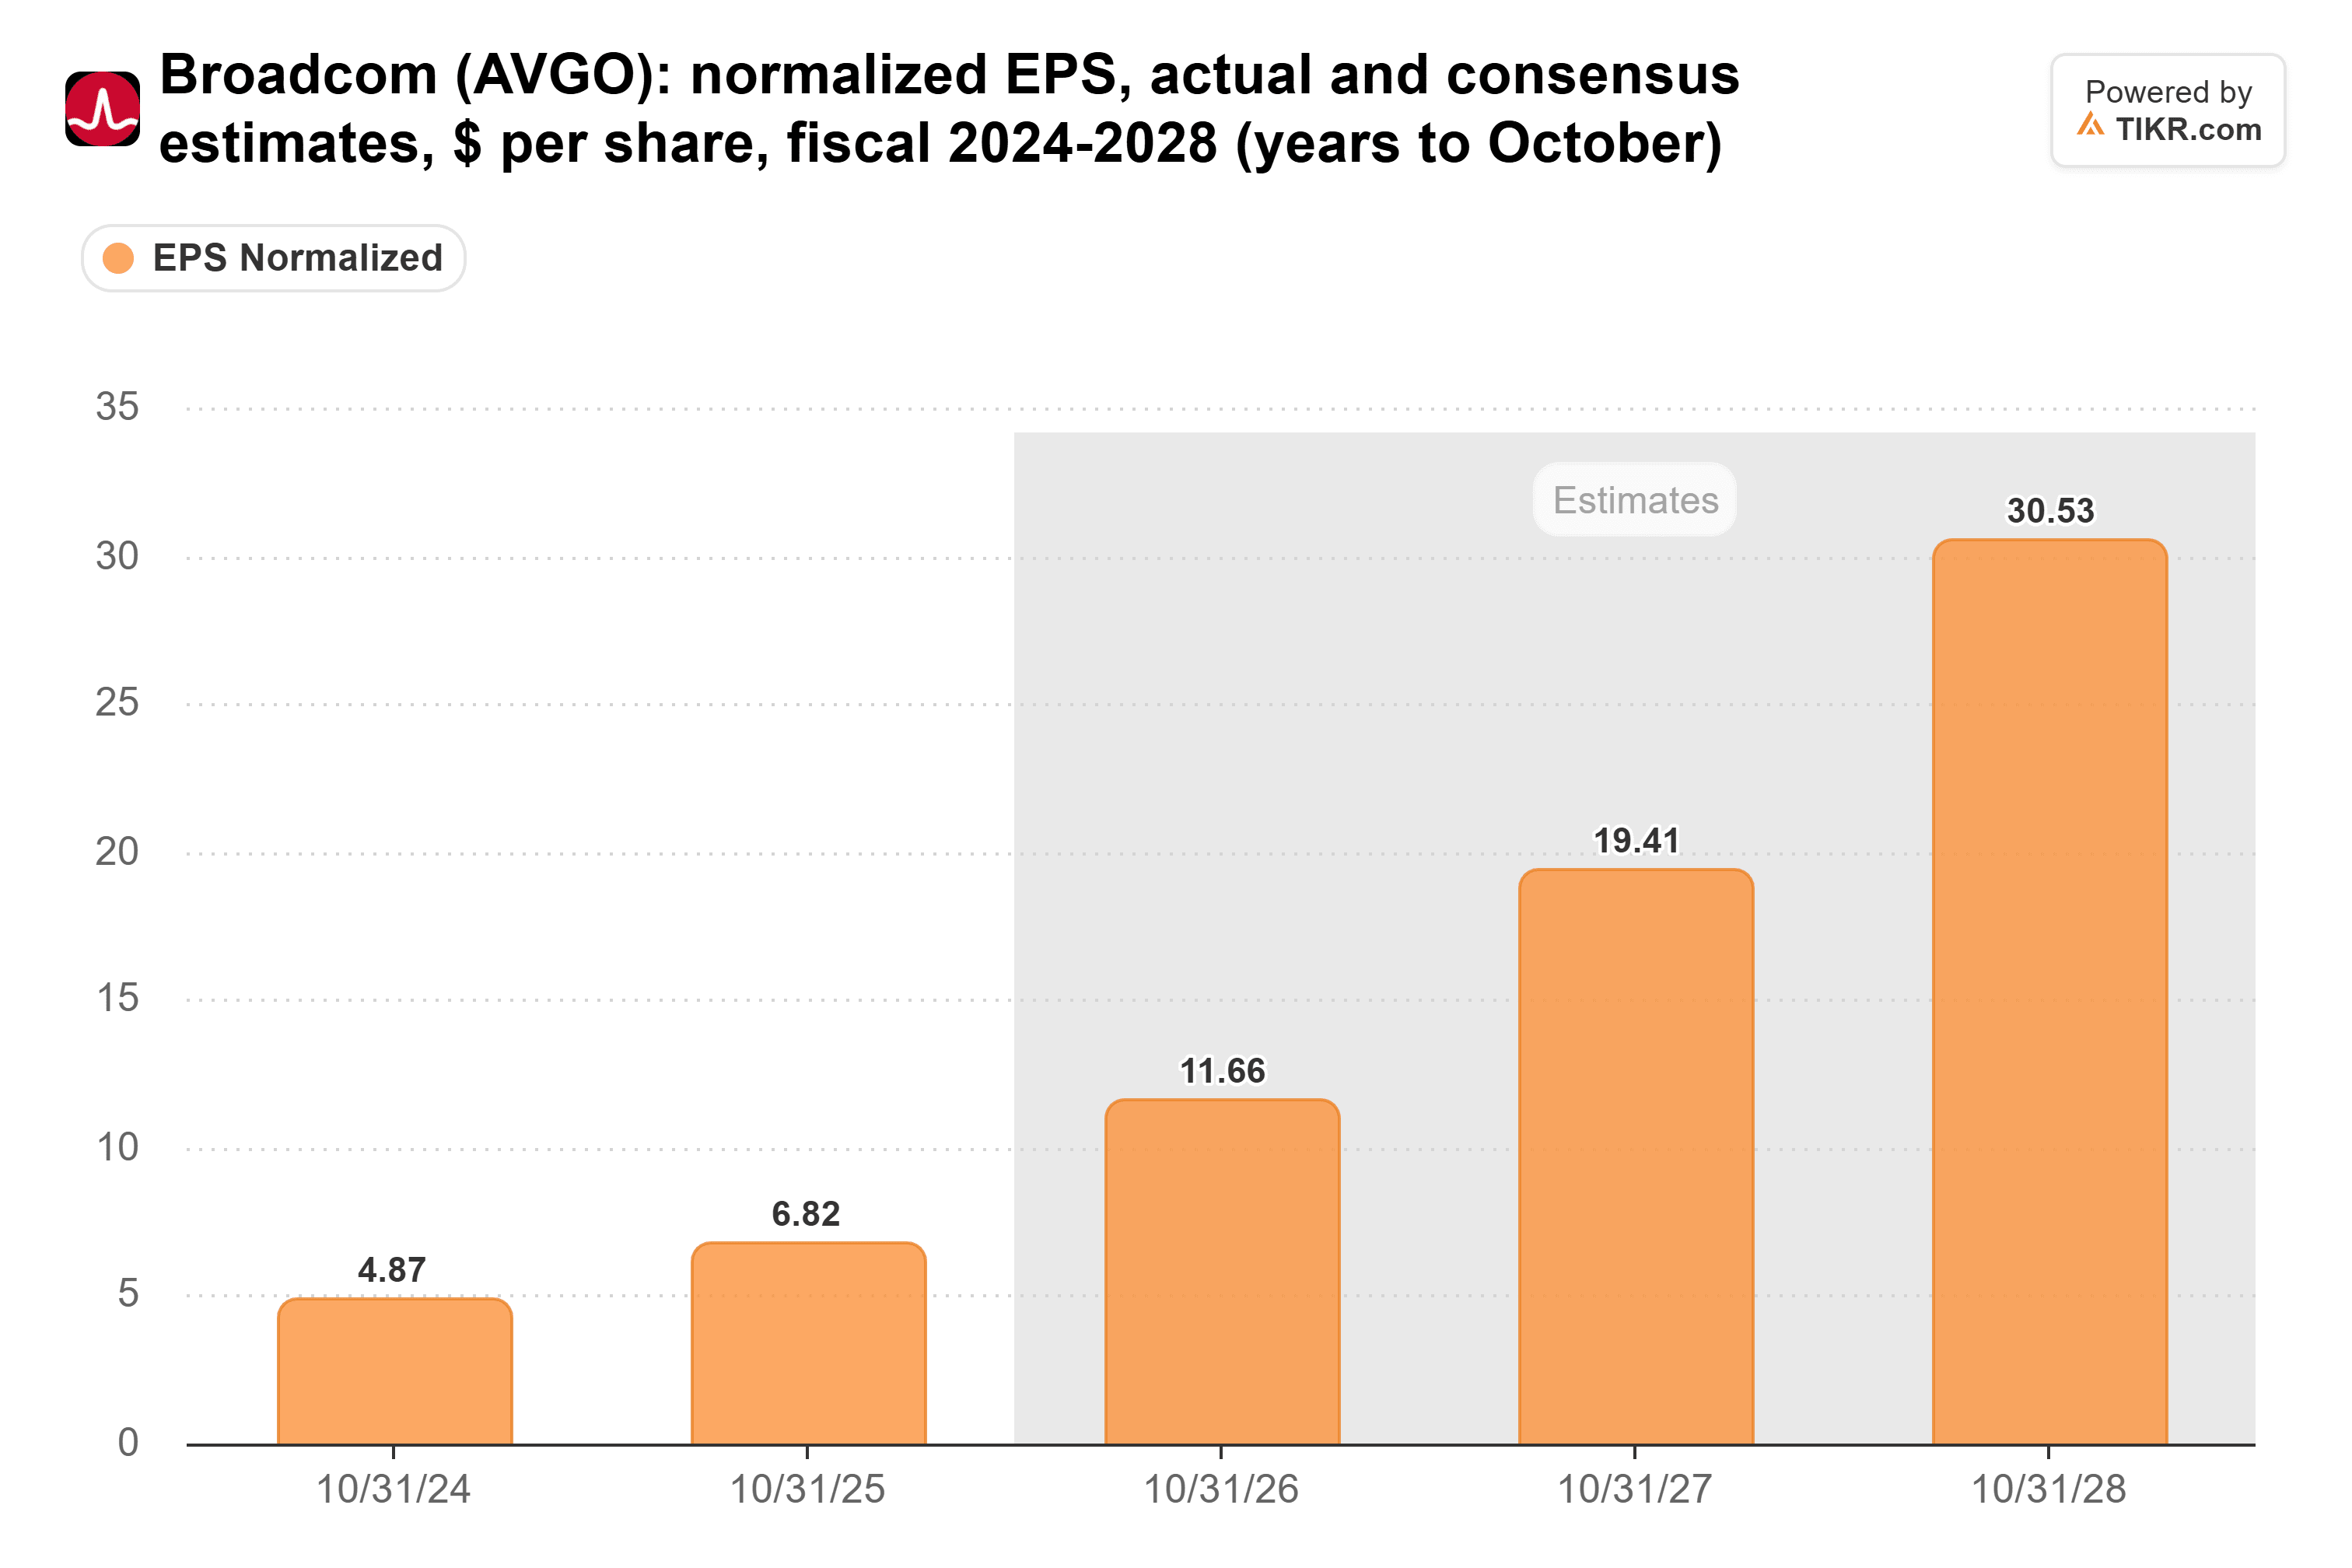
Analysts expect normalized EPS to climb from $6.82 in fiscal 2025 to $30.53 in fiscal 2028.
The stock traded at 20x forward earnings on Nov. 18, below its five-year average of 24x.
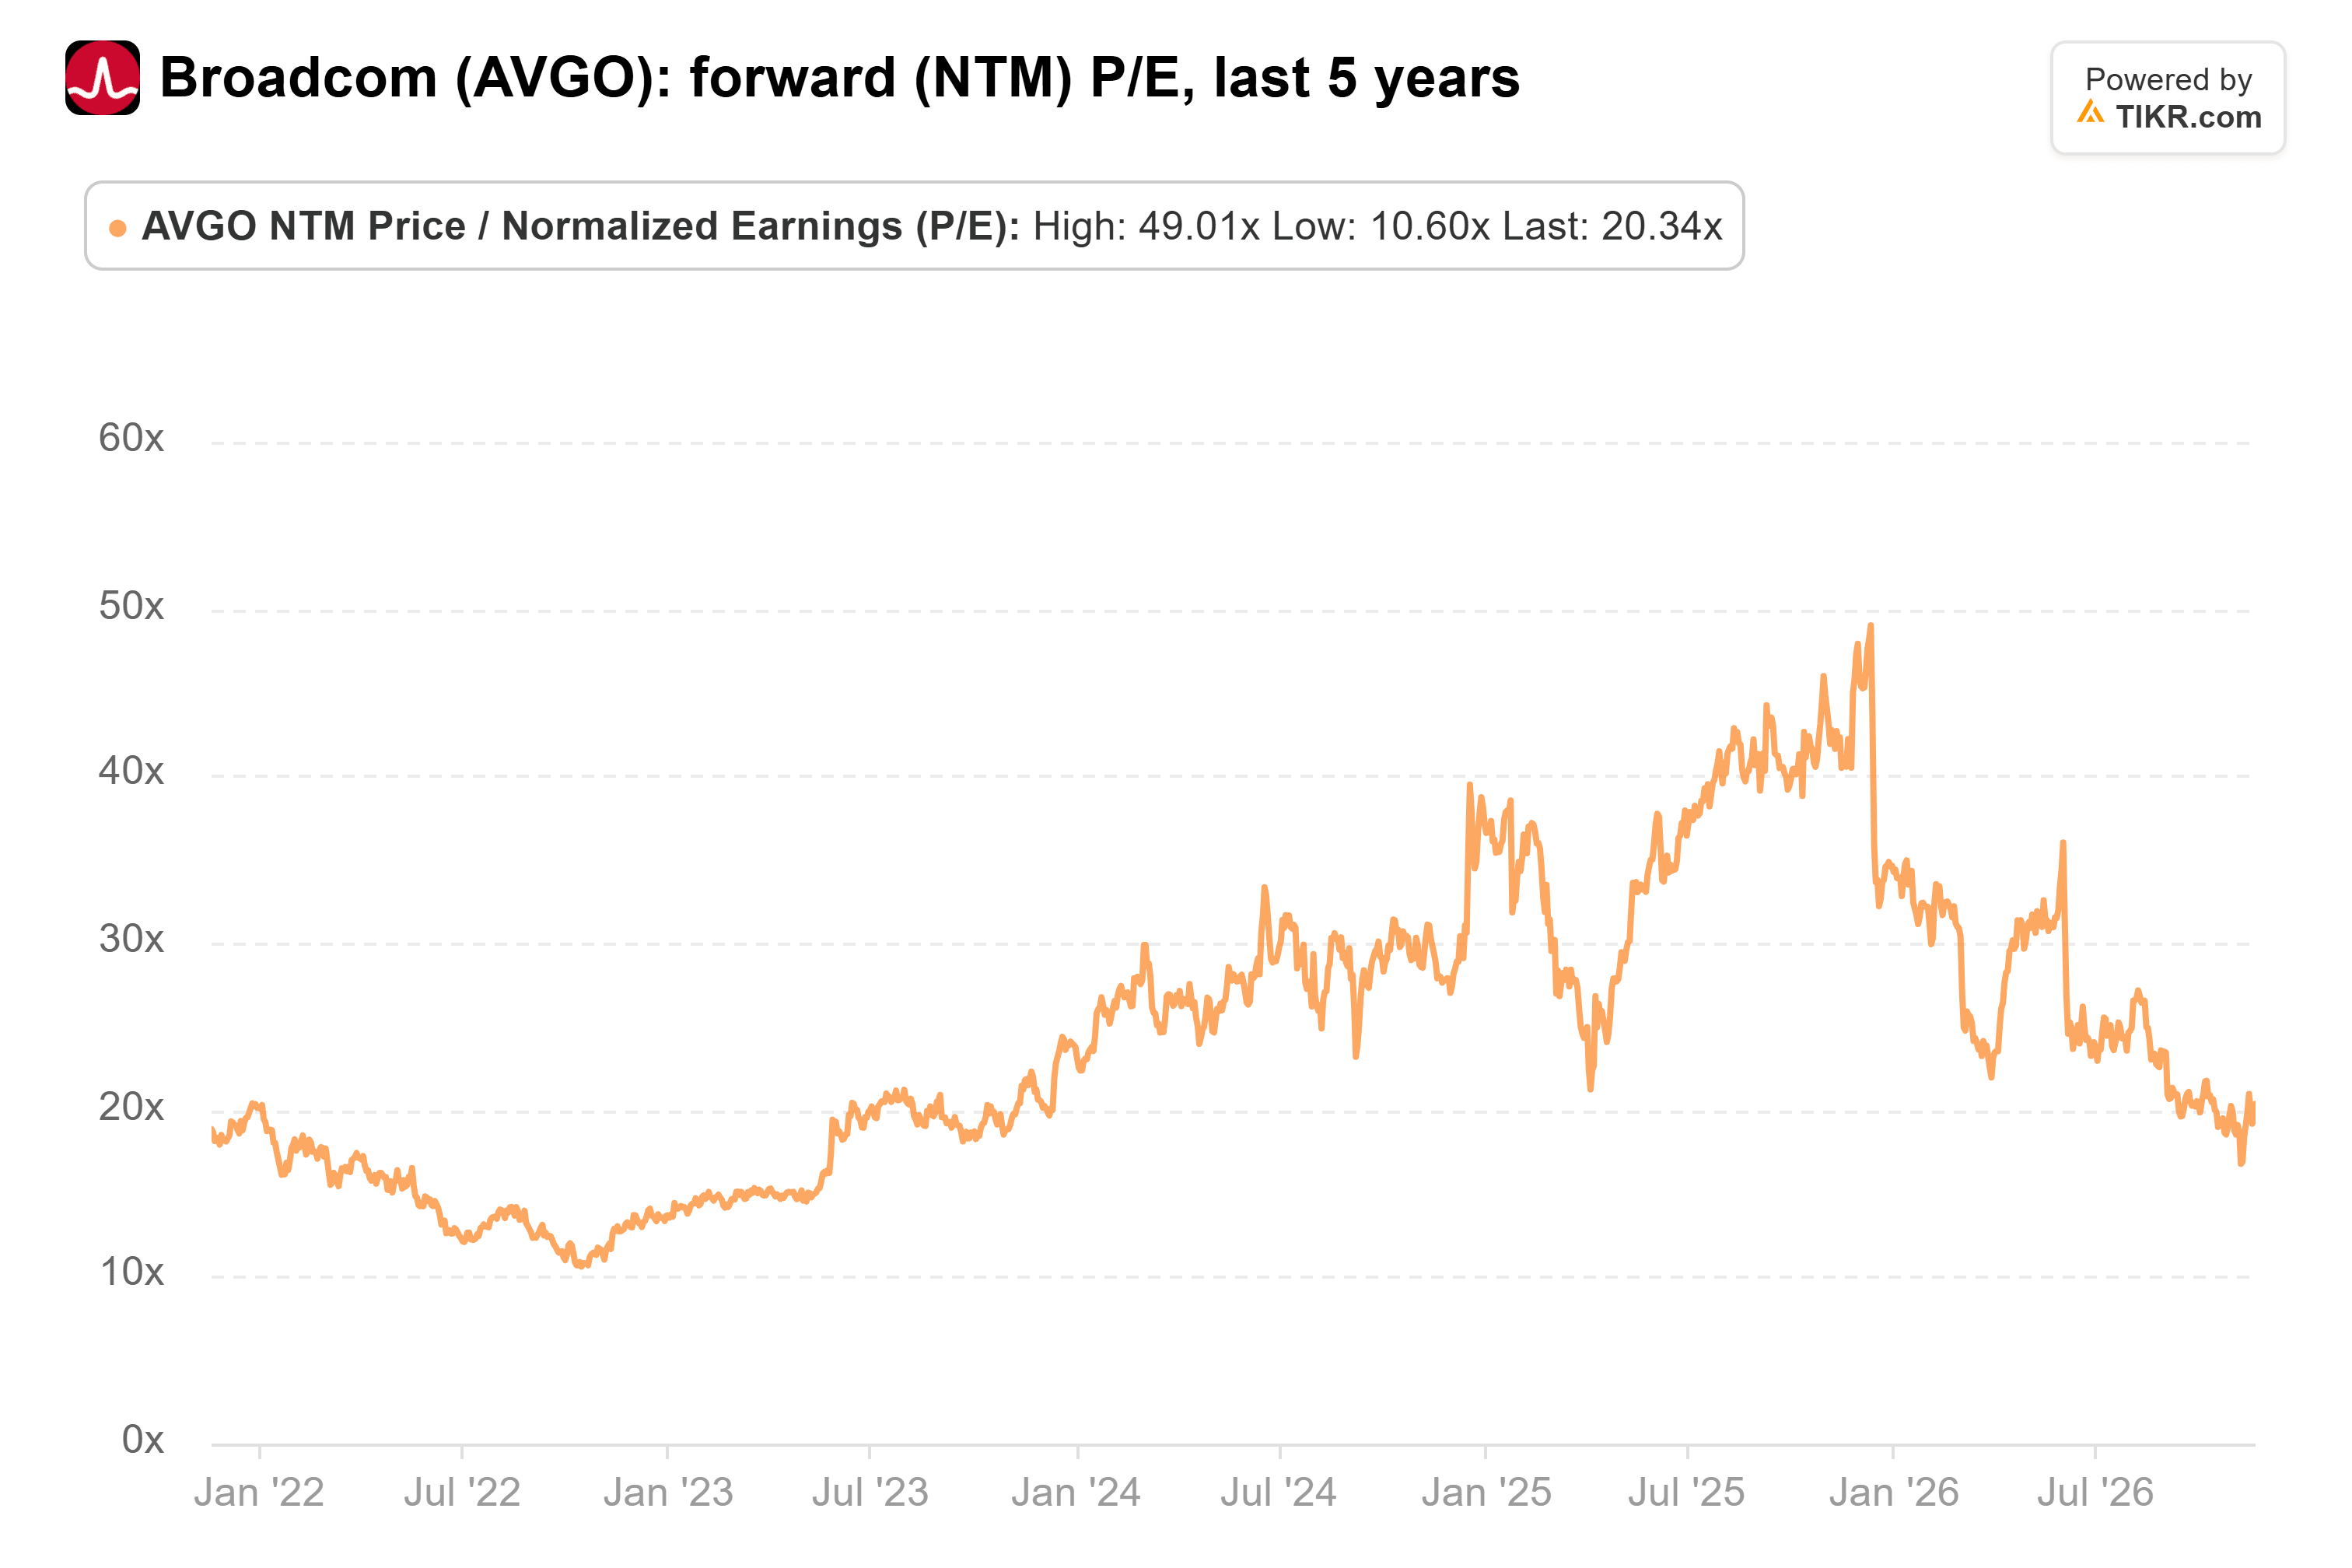
On fiscal 2028 estimates, $460 is about 15x, so the target needs no help from the multiple. If earnings grow 75% from the next 12 months’ estimate to fiscal 2028’s, the multiple could fall 26% and the stock would still reach $460.
Goldman Is Being Cautious on Broadcom
If either lab cuts orders, Broadcom’s growth slows, and an Anthropic lease default could leave it owing on its backstops. But Anthropic’s IPO, priced at $83, closed on Nov. 20 with about $91.6 billion in gross proceeds for the company, plus a $26 billion private placement. And TSMC’s board approved up to $500 million for each lab on Nov. 10.
Tan says Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.” Goldman’s $460 asks only for those earnings, at a below-average multiple, so I think it’s conservative. Marvell reports Dec. 1, an early read on Google’s custom-chip spending. Broadcom’s own Dec. 9 report needs AI revenue of at least $21.7 billion and a repeat of the roughly $115 billion AI outlook for fiscal 2027.
So What Is Broadcom Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!