


Key Takeaways
- Fiserv shares are up 17% in the past month, off their 52-week low, as payments stocks like Mastercard and Visa rallied while the Nasdaq fell.
- Analysts cut their price targets through October, and Fiserv’s own news didn’t explain the rally.
- Fiserv’s third-quarter results, out today, kept its 2026 guidance in place, and the company plans to buy back $500 million of stock this quarter.
- The stock trades at about 7x forward earnings, cheap enough to hold and add to, though its merchant business is still shrinking.
Fiserv (FISV) stock is up 17% in the past month, off the 52-week low it hit on Oct. 2. It’s still down 22% in 2026, and the company itself gave investors very little reason for the run.
Most of the lift came from money moving into payments. While the Nasdaq 100 fell 9% over the month, Mastercard rose 19% and Visa 18%.
Payments had the month tech didn’t
You could see it on Oct. 22. The Nasdaq slid 3% that day, and Fiserv rose with bank-tech names Jack Henry and FIS without any news of its own.
Fiserv did have some business news. Clover passed 5 million devices shipped worldwide on Oct. 14. Five days later, Klarna said it’s live at 100,000 US Clover locations and is coming to Commerce Hub, Fiserv’s platform for large merchants. And on Oct. 20, Fiserv signed a multi-year deal with VikingCloud to offer cybersecurity protection to its merchants.
All good to see. But none of it explains a month like this for a $30.7 billion company.
Wall Street cut its targets the whole way up
Analysts got more cautious through October. Barclays, TD Cowen, Citi, Cantor Fitzgerald, Truist and BMO Capital all lowered their price targets, to between $48 and $53. BofA reinstated coverage with an Underperform rating and a $48 target.
Goldman Sachs was the only firm to raise its target, to $56 from $54.
So the stock rallied while most of the analysts covering it got gloomier.
TIKR tracks 37 analysts on Fiserv. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Fiserv, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Fiserv’s Analyst Ratings
Guidance held, and buybacks are back
Fiserv reported third-quarter results before the open today, and they were mixed:
- Organic revenue was flat, with Merchant Solutions down 2% and Financial Solutions up 2%.
- Adjusted EPS came in at $1.75, down from $2.04 a year earlier but slightly ahead of analysts’ estimates.
- Adjusted operating margin fell to 31.2%, from 37.0%.
- A $6.45 billion non-cash goodwill impairment pushed it to a GAAP loss of $11.17 per share.
More important, Fiserv stood by its 2026 outlook: adjusted EPS of $7.20-$7.40 and organic revenue flat to down 1%. That’s well below the $8.00-$8.30 it guided to in February, but it held.
And CFO Paul Todd said in the release that the buyback is coming back early: “Our growing confidence also allows us to resume share repurchases earlier than anticipated, with $500 million planned in the fourth quarter.” That’s roughly 1.6% of the company at Monday’s market value.
Going into the report, analysts expected normalized EPS to fall to $7.24 this year, from $8.64 in 2025, then grow about 10% in 2027.
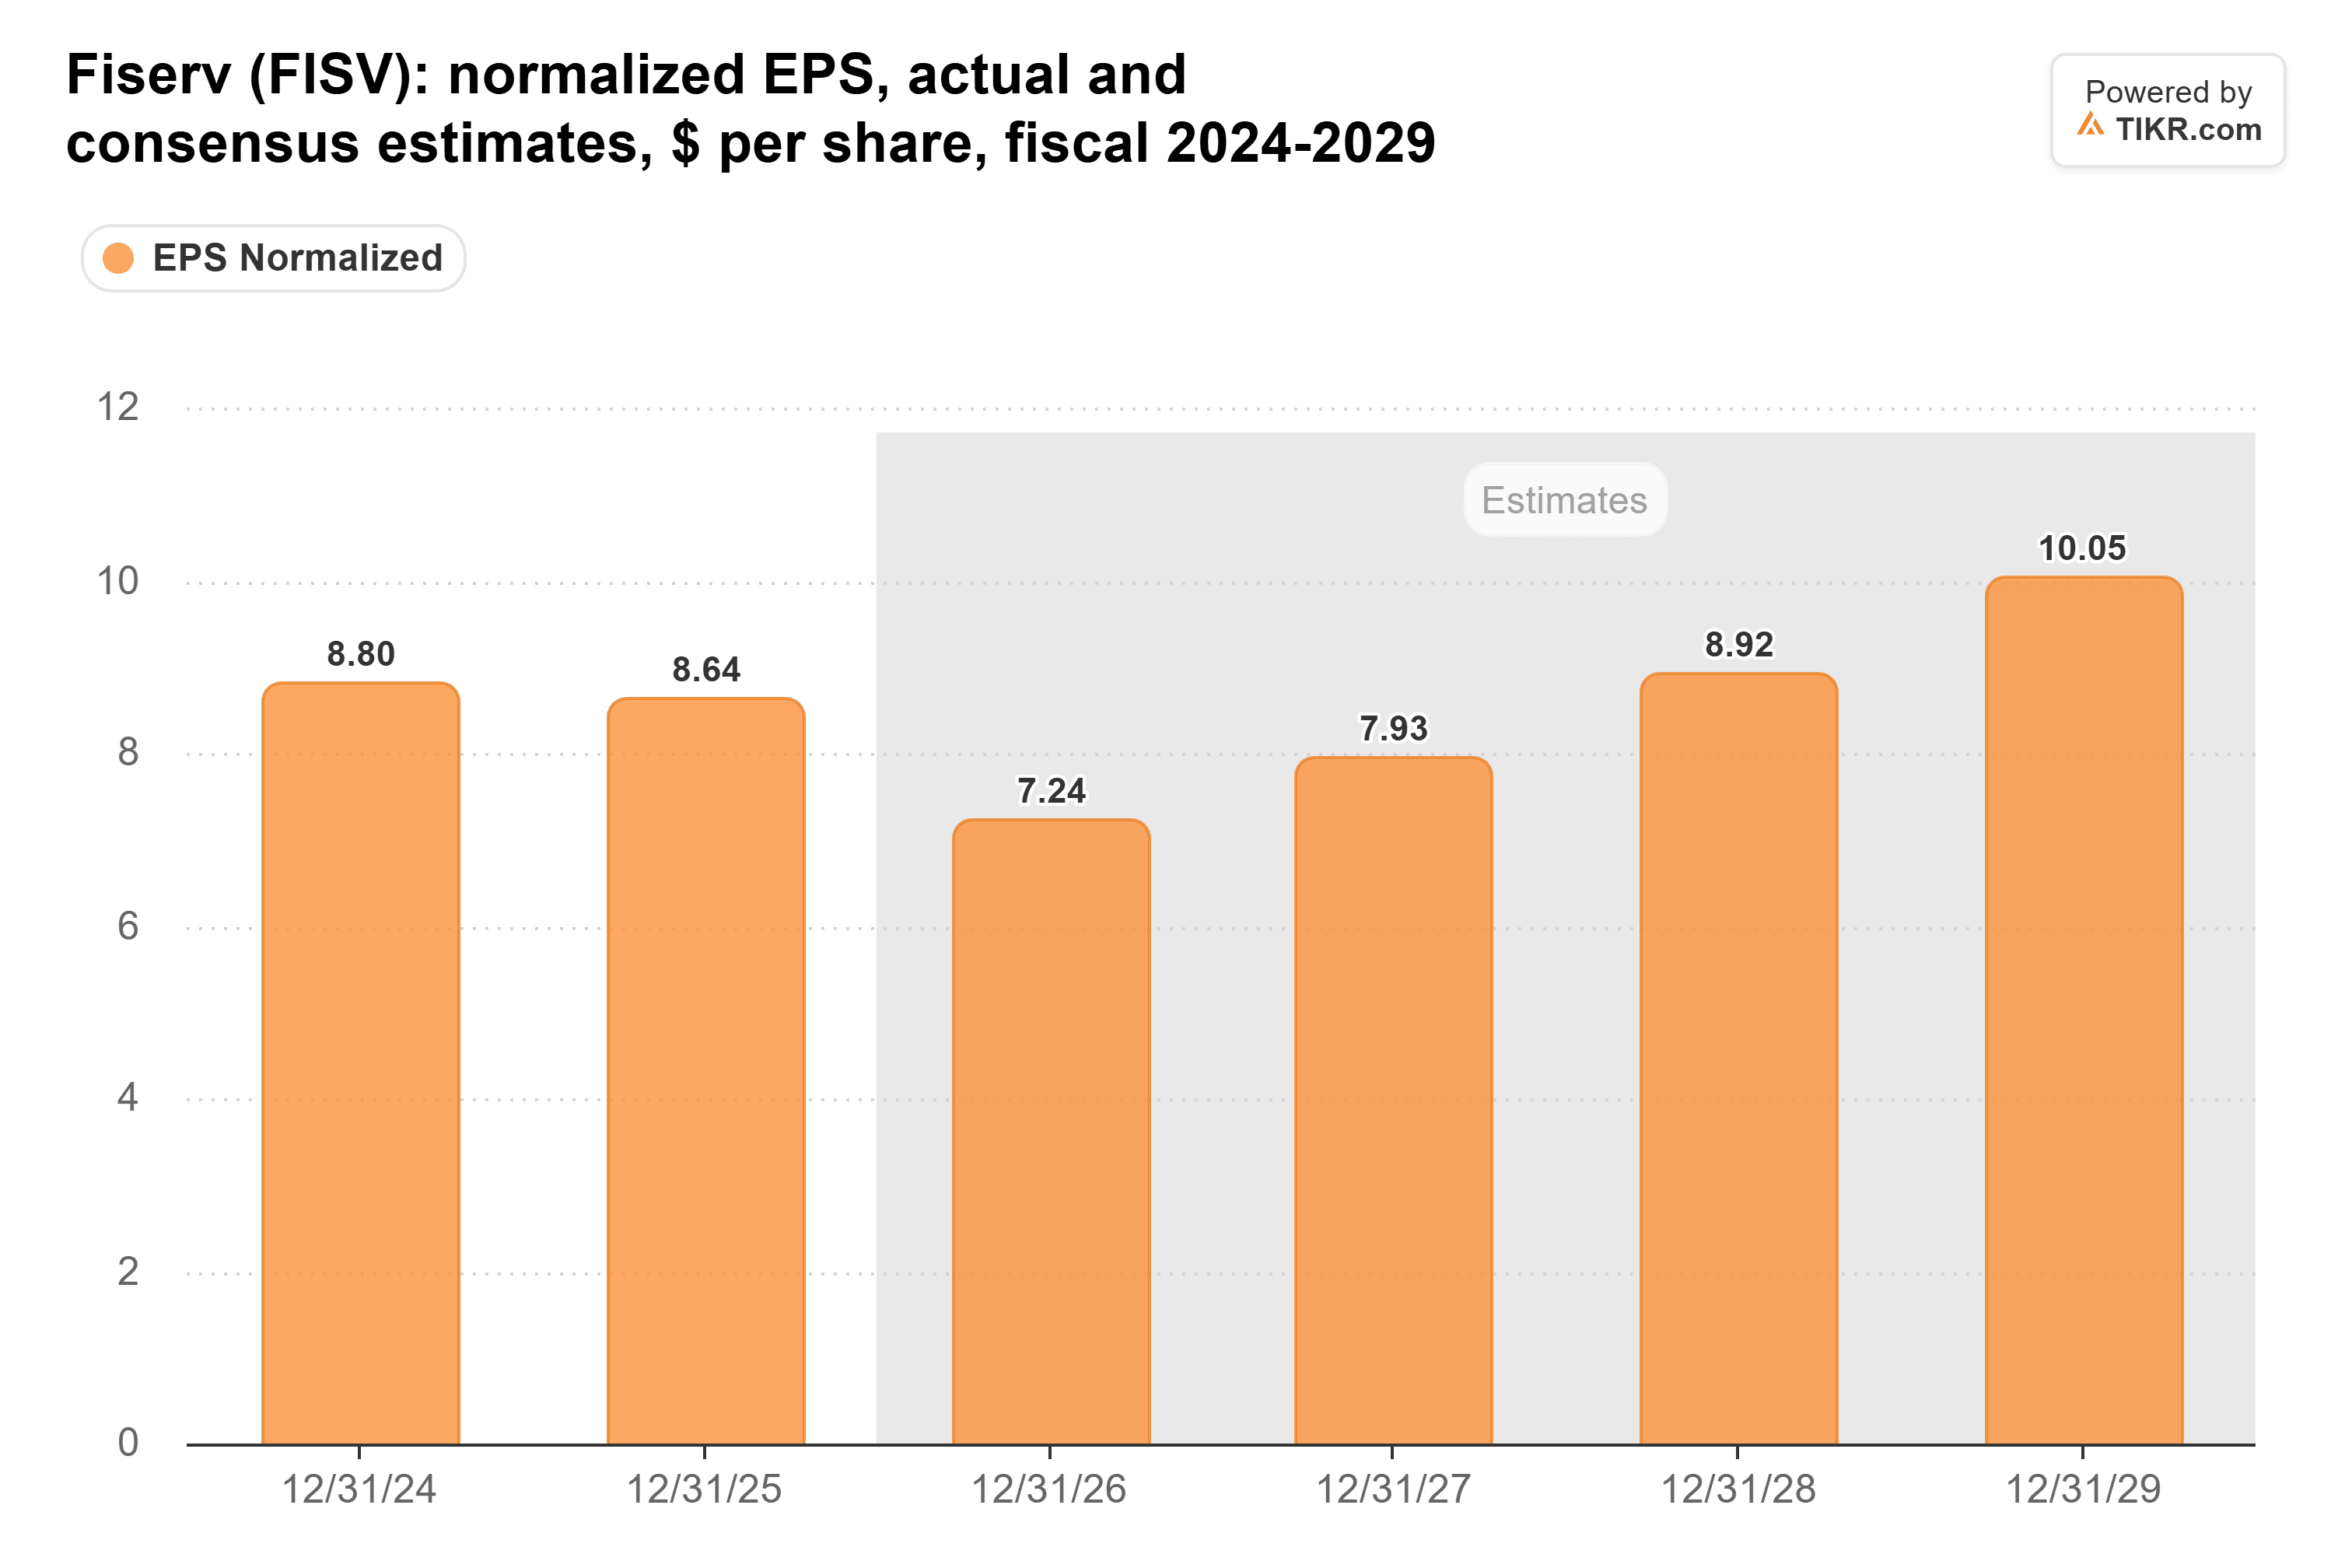
Their $7.24 sits at the low end of the range Fiserv just reaffirmed, and nothing in today’s release makes me expect a cut.
At 7x earnings, I’m holding on
Even after the run, Fiserv traded at 7.1x forward earnings at Monday’s close, less than half its five-year average of 15x.

Analysts’ average price target has come down hard over the past year, from $169 to $58.

Even so, that’s about 11% above Monday’s close.
So, take profits or buy more? I wouldn’t take profits here. Fiserv just reaffirmed its guidance and restarted buybacks, and at 7x earnings the stock doesn’t need much to go right from here. I’d be comfortable adding to a position.
The risk is Merchant Solutions, Clover’s segment, which is still shrinking, with margins six points below last year’s.
Todd said Fiserv’s second-half initiatives “are on track to support the revenue acceleration we expect in the fourth quarter.” If that acceleration doesn’t show up in the fourth-quarter report, likely in February, I’d rethink it.
So what is Fiserv stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Fiserv could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


