Key Takeaways
- FIGS reports third-quarter results after the close on Thursday, Nov. 5, with its stock up 93% in 2026 and trading at more than 60x forward earnings.
- At that price, beating the quarter’s EPS estimate isn’t enough: the report needs a wider operating margin and higher full-year earnings estimates.
- Nike (NKE) and Cintas (CTAS) both lifted margins in their latest quarters, but FIGS has guided its own gross margin lower, so its gain has to come from costs growing slower than sales.
- Analysts expect FIGS’s EPS to grow only about 6% in 2027, which leaves little room at more than 60x if estimates don’t rise after the call.
FIGS (FIGS) reports third-quarter results after the close on Thursday, Nov. 5, and the bar is about as high as it’s been all year.
The stock is up 93% in 2026 through the Nov. 4 close, extending a run TIKR covered on Oct. 28. Oppenheimer raised its price target to $25 on Oct. 29, and Simply Wall St wrote on Oct. 18 that the stock looks “priced for perfection” after a 204% gain over three years.
Two companies that already reported give a read on the test FIGS faces. Nike lifted its gross margin in the quarter to Aug. 31, and Cintas widened its operating margin and raised its full-year guidance.
Analysts are already counting on growth
Analysts expect FIGS’s normalized EPS to nearly double in 2026 and keep rising through 2028:
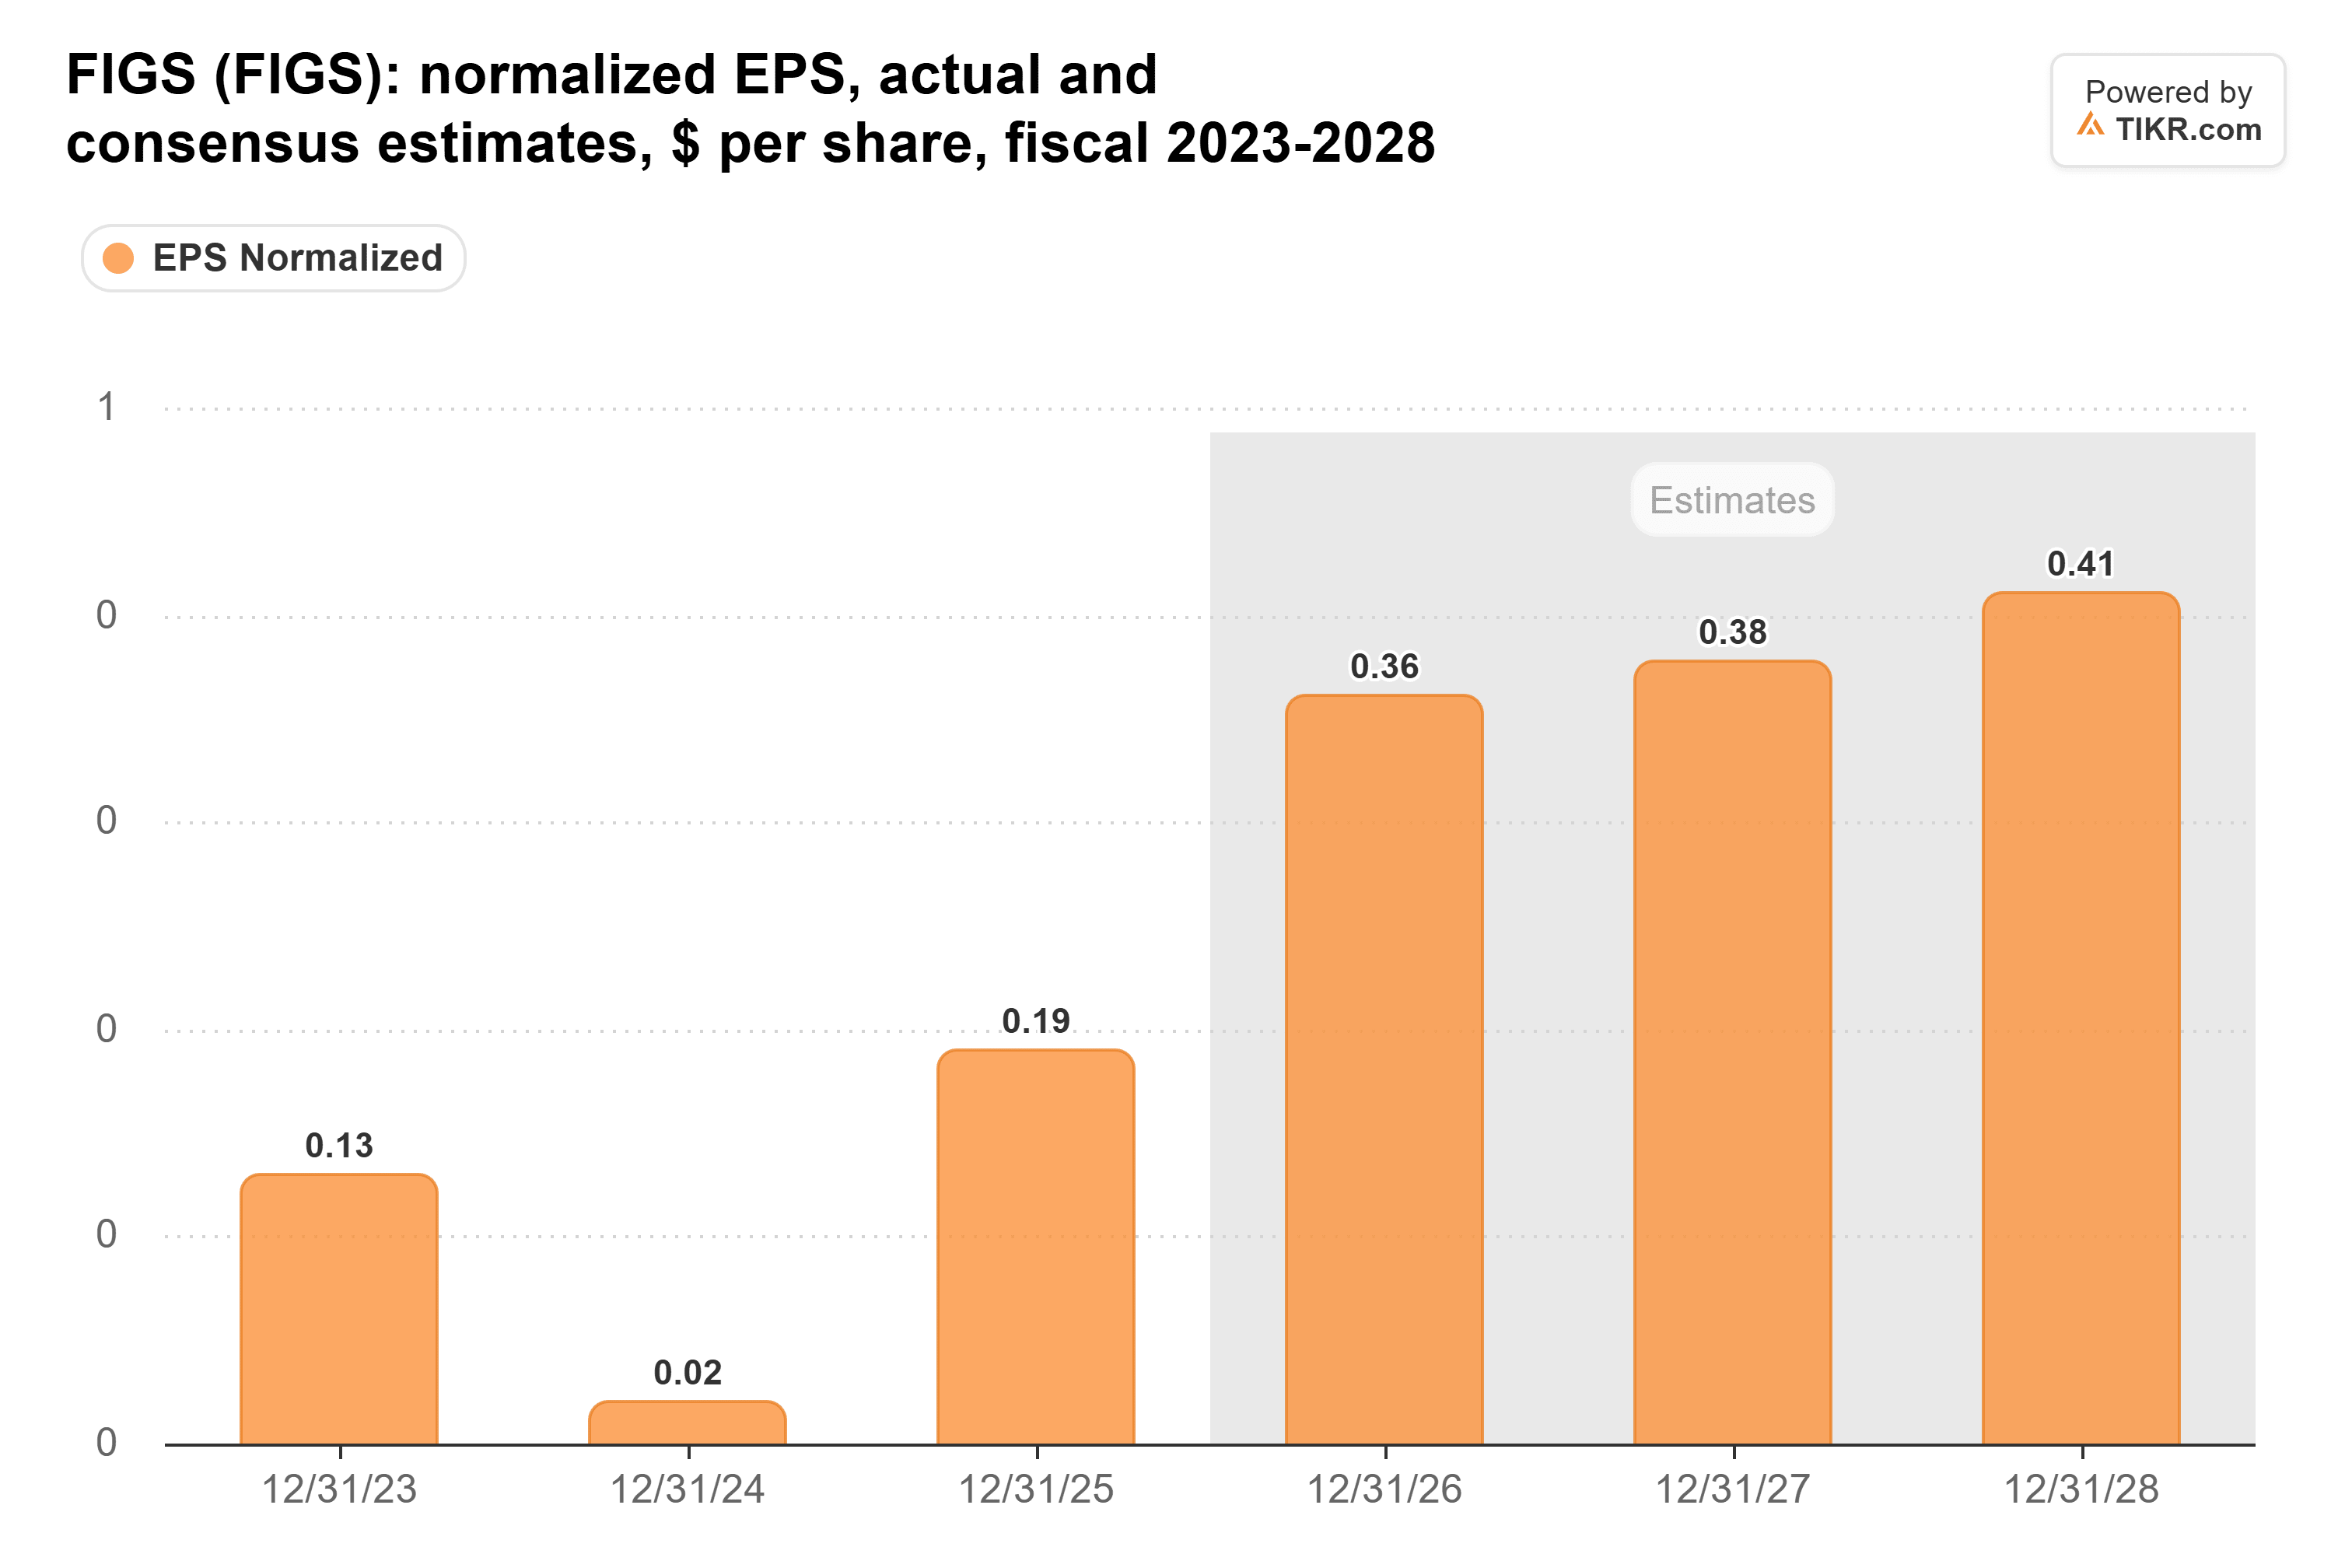
Those estimates have climbed all year. The 2026 figure was $0.11 at the end of 2025 and $0.27 at the end of June, and it’s $0.36 now, as FIGS topped Wall Street’s EPS estimate in each of its last four quarters.
But the climb flattens from here: 2027’s $0.38 is only about 6% above 2026’s. Management has guided revenue growth down to about 10% in the fourth quarter, against about 20% for 2026 as a whole, and analysts see 9.4% in 2027.
A strong active-customer count on Thursday would help, after a 13.2% jump to 3.1 million at June 30. But with sales growth slowing, more of FIGS’s earnings growth has to come from a wider margin.
TIKR tracks 9 analysts on FIGS. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on FIGS, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See FIGS’s Analyst Ratings
Investors are paying up for the same estimates
FIGS’s forward P/E was 62x at the Nov. 2 close, below its five-year average of 78x:
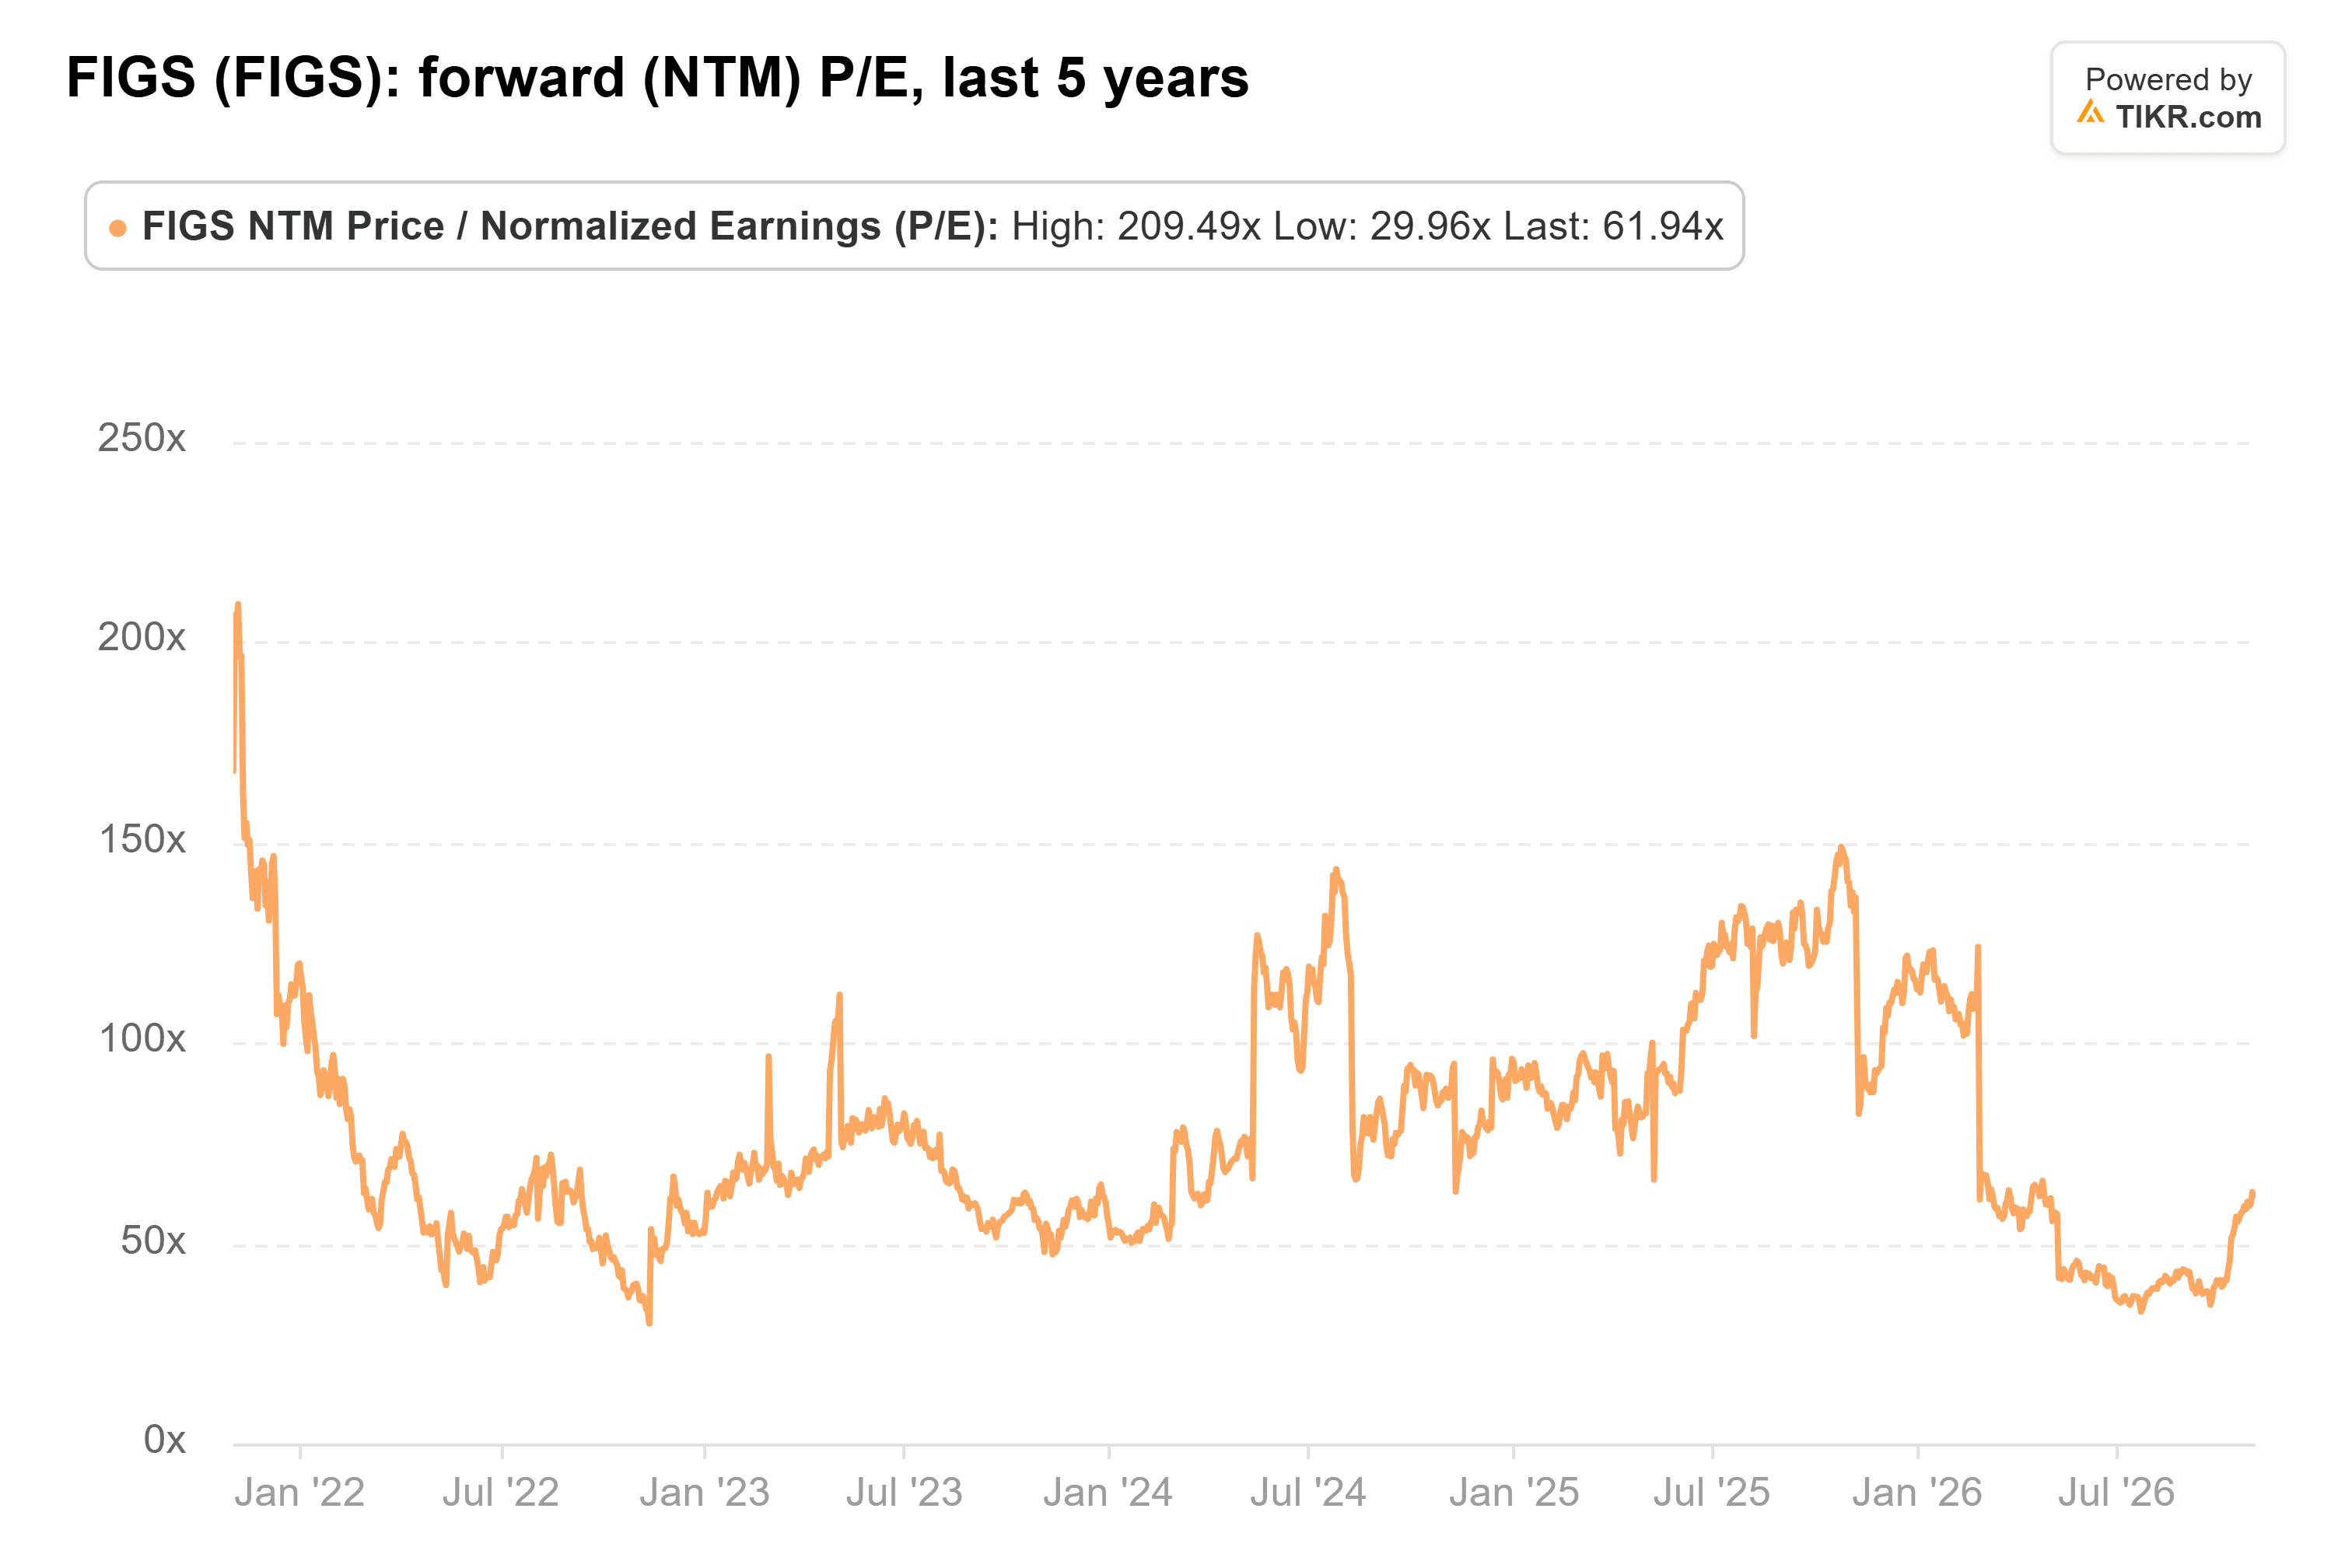
That average was set when analysts expected FIGS to earn far less. Over the past three years, its expected earnings for the next 12 months averaged $0.13 a share, against $0.35 in late October.
This year is the better yardstick. The multiple was 36x at the end of June and 40x at the end of September. The stock’s October jump came without a matching jump in estimates, so investors are now paying more than 60x for roughly the same earnings outlook they paid 40x for five weeks ago.
Q3 needs a wider margin, without the refund help
FIGS’s operating margin has widened over the last three years, with big swings from quarter to quarter:

The second quarter’s 17.9% was the highest in at least three years, but it had help: refunds of tariffs the Supreme Court struck down added 7.8 points to gross margin. Take them out, and the margin was still about 10%, up from 6.5% a year earlier.
Thursday’s comparison is last year’s third quarter, at 6.4%. On its second-quarter call, management guided to revenue growth of about 20% and an adjusted EBITDA margin of about 14%, up from 12.4%. It also guided gross margin below last year’s 69.9%, so the gain has to come from shipping, marketing and overhead growing slower than sales.
Nike’s latest quarter is a good sign on shipping costs. Its gross margin rose 60 basis points to 42.8% in the three months to Aug. 31, mostly on lower warehousing and logistics costs, even as revenue fell 4%. FIGS saw something similar in its second quarter, when better shipping rates helped cut its selling expense to 22.2% of revenue from 22.6%. Thursday’s report will show whether that held up through the summer.
Cintas shows what passing this kind of test looks like. Its organic revenue grew 8.9% in the three months to Aug. 31, its operating margin rose to a record 23.6% from 22.7%, and it raised its full-year revenue and adjusted EPS guidance. FIGS needs the same pattern: a wider margin first, then estimates that move up behind it.
What Thursday has to show
On Thursday, FIGS needs an operating margin above last year’s 6.4% that doesn’t lean on tariff refunds, and an outlook that pushes analysts’ 2026 and 2027 EPS estimates above $0.36 and $0.38.
Watch the share count, too. Diluted shares were 195.14 million in the second quarter, up 13% from a year earlier. Consensus has 2027 net income rising 8.7% but EPS only 6%, which assumes the count keeps climbing.
A U.S. Customs order blocking imports from a Jordanian partner that made about a third of FIGS’s second-quarter finished goods could also dent the quarter. The company expects the order to hurt second-half revenue, gross margin and inventory.
FIGS beat its own revenue and margin guidance in both quarters it has reported this year, so clearing the margin bar looks likely. Lifting 2027 is harder with growth slowing and the tariff refunds gone next year, and at more than 60x, the share price already assumes an upgrade that hasn’t arrived.
Of course, one quarter won’t settle it. The fourth-quarter report and FIGS’s first 2027 outlook, likely in late February, will say far more.
So what is FIGS stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what FIGS could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!