Key Takeaways
- Campbell’s stock rose 13% in the week through Nov. 4, with the biggest jump coming after Kraft Heinz’s third-quarter report lifted packaged-food stocks that day.
- Campbell’s had no news of its own, and its guidance still calls for lower sales and earnings in fiscal 2027.
- The stock trades above analysts’ roughly $21 average target, so the case for taking profits looks stronger than the case for buying more.
Campbell’s (CPB) is up 13% in the week through Nov. 4, while the S&P 500 slipped 0.7%.
The soup maker had no news of its own. Nearly half the gain came on Nov. 4, when the stock rose 5.9%, far ahead of the S&P 500’s 1.6%, after Kraft Heinz (KHC) reported third-quarter results that lifted the whole packaged-food aisle.
Kraft Heinz did the heavy lifting
Kraft Heinz raised the low end of its 2026 organic sales outlook, and CEO Steve Cahillane said on the call that price increases are likely in 2027. That’s what the group needed to hear, and Conagra, General Mills and Smucker all rose with it.
Campbell’s is already raising prices
Campbell’s set its own plan on Sept. 3. It guided for fiscal 2027 organic sales to fall 2% to 4% and adjusted EPS of $1.65 to $1.80. It also cut its quarterly dividend 36% to $0.25 to pay down debt from the Rao’s deal faster.
In prepared remarks for the Sept. 3 call, CEO Mick Beekhuizen said he expects “another year of elevated inflation that will continue to pressure margins, particularly in the first half.” Management’s answer is selective, commodity-driven price increases plus cost savings. It expects first-quarter sales and profit to fall more than the full-year range implies, with pricing, productivity, and savings building through the year to support margins.
Analysts expect normalized EPS to fall to $1.70 this fiscal year, from $2.17, then recover to $1.84 in fiscal 2028:
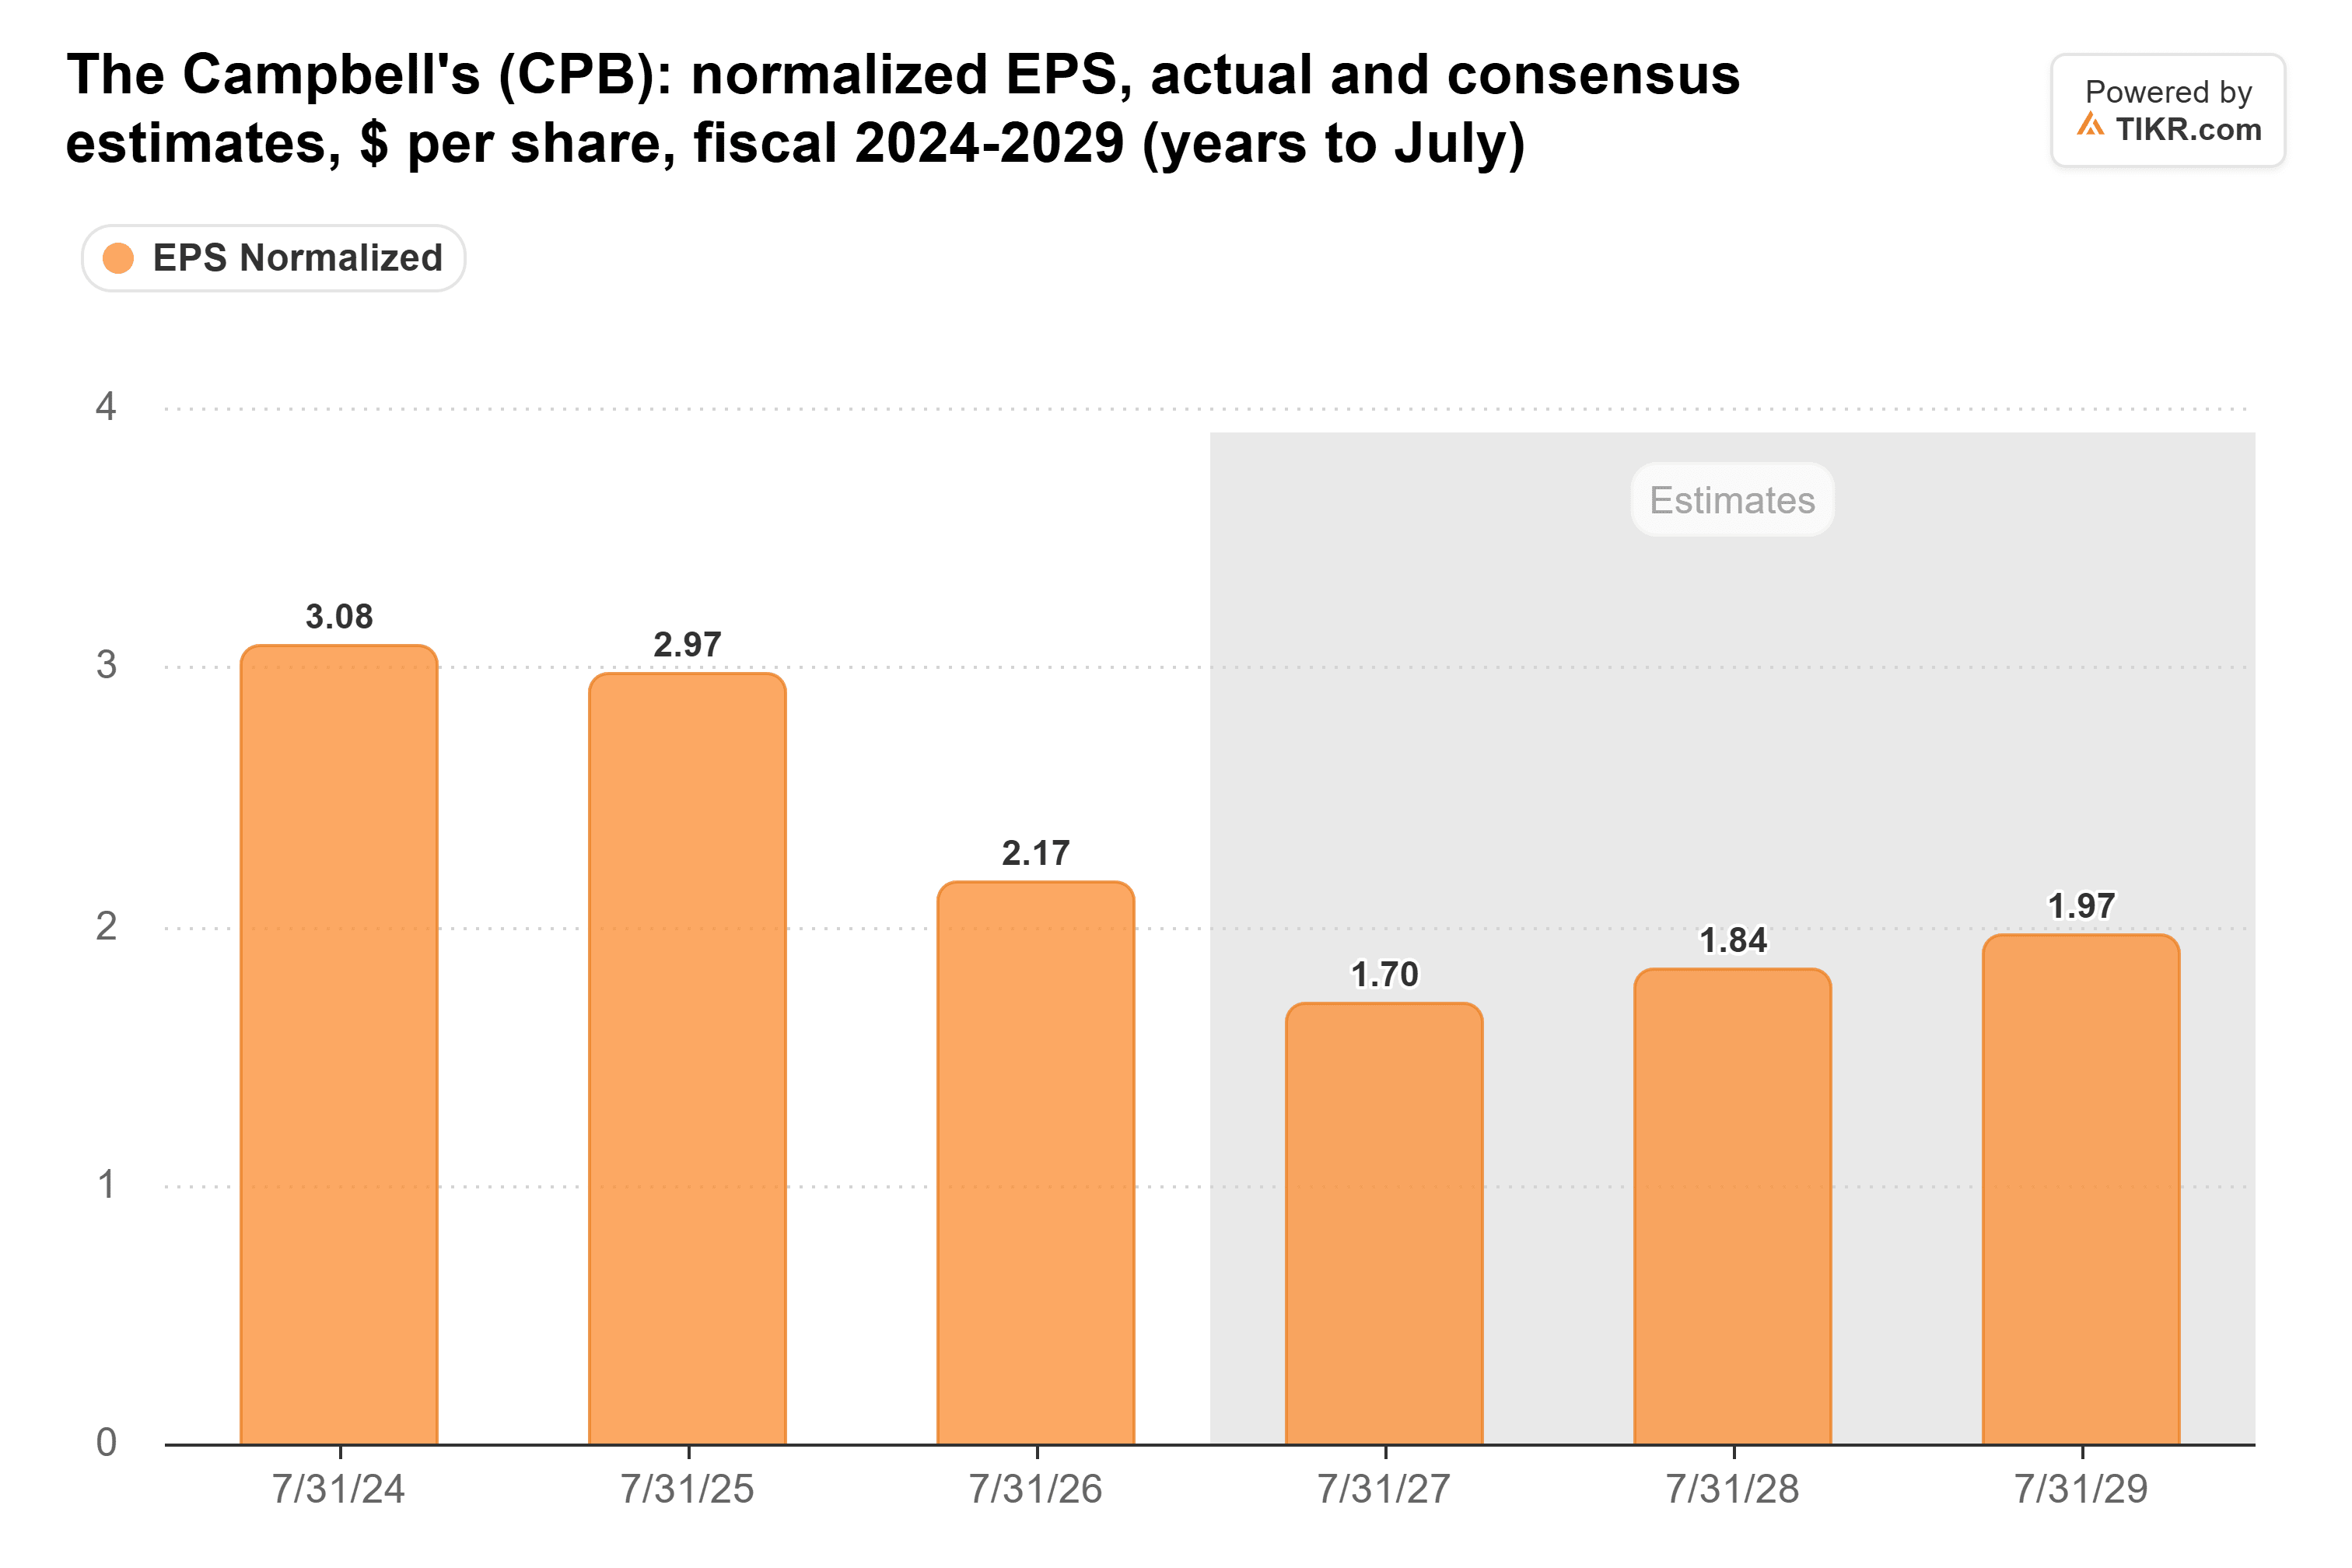
That’s in the lower half of Campbell’s range. Kraft Heinz’s pricing talk doesn’t change Campbell’s own outlook, so estimates may not move much before Campbell’s reports again.
TIKR tracks 20 analysts on Campbell’s. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Campbell’s, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Campbell’s’ Analyst Ratings
Wall Street isn’t buying the bounce
Twenty analysts cover Campbell’s, and their average target of around $21 now sits below the stock’s $23.26 close on Nov. 4. Bernstein’s Alexia Burland Howard kept her Sell rating and $18 target on Oct. 21.
Campbell’s traded at 13x forward earnings on Nov. 2, a bit under its five-year average of 14x:

After Nov. 4’s jump, it sits close to that average. That’s a full price for earnings that are still shrinking.
The case for taking profits looks stronger than the case for buying more. The rally came from a rival’s report, and Campbell’s own guidance still points to lower earnings this year. If its pricing sticks, fiscal 2028 could bring the earnings recovery analysts expect, and today’s multiple would look cheap.
The first-quarter report, expected in early December, will show whether that pricing is landing. If sales hold up and the outlook stays intact, the stock would earn another look.
So what is Campbell’s stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Campbell’s could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!