Key Stats for Dell Stock
- Current Price: $424.30
- Target Price (Mid): ~$733
- Street Target: ~$595
- Potential Total Return: ~73%
- Annualized IRR: ~14% / year
What Happened?
Dell Technologies (DELL) fell 10.77% to $424.30 on October 30 after Intel (INTC) said memory prices are shrinking the PC market. Intel expects PC units to fall about 12% in 2026 and is planning for a roughly 10% drop in 2027. Its own shares sank 28.58%. HP Inc. (HPQ), whose PC shipments fell 30.9% in the July-to-September quarter according to preliminary IDC data, slid alongside Dell. The Nasdaq Composite lost 2.86% in a broad selloff that CNN tied to doubts about AI spending.
The selling treated Dell like a PC maker. Its Client Solutions Group, which sells PCs, earned 19% of Dell’s segment operating income in the quarter ended July 31, down from 35% a year earlier. At the October 30 close, Dell sat 27.89% below its record close of $588.40 on September 17.
Dell Already Expected a Double-Digit PC Drop This Year
Intel’s 2026 forecast matched what Dell had already told investors. Chief Financial Officer David Kennedy told Citi’s technology conference on September 10 that the PC market “is compressed for the rest of this year, like I said, minus double digit.” Dell had raised its fiscal 2027 revenue guide to $192 billion nine days earlier. What Intel added is a second down year in 2027.
PCs also carry less of Dell’s revenue than the selloff implied. Client Solutions revenue rose 20% to $15.0 billion in the July quarter, mostly from commercial customers at $13.2 billion. Consumer sales, the weakest part of the market, were $1.8 billion, under 4% of Dell’s $47.0 billion total.
Units are the soft spot. Preliminary IDC data shows Dell’s PC shipments fell 25% in the July-to-September quarter. Kennedy said most enterprises are “sweating those assets out a little bit more” and putting budgets into infrastructure, but noted “there are still 400 million-plus PCs over 4 years old.” Intel does not expect a sustained recovery until memory supply and prices improve, so that refresh may wait.

TIKR tracks 29 analysts on Dell Technologies. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Dell Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Dell Technologies’ Analyst Ratings
Intel’s Server Chip Shortage Is the Bigger Test
Intel also said industry server CPU units should grow more than 30% in both 2026 and 2027, with supply capping the pace. That demand feeds Dell’s traditional servers, but the shortage reaches Dell too. Kennedy said DRAM and NAND are “by far the big brother” among scarce parts, then added: “Given the growth in CPUs, obviously, that now comes into the equation also.” In his words, “any part associated within an AI box is short to some degree.” Intel Chief Financial Officer Dave Zinsner said Intel will “likely not fully meet” what customers require.
So far, Dell has managed the squeeze. Its Infrastructure Solutions Group earned a 15.0% operating margin in the July quarter, up from 8.8% a year earlier. At the October 30 close, Dell traded at 15.08x next-twelve-month normalized earnings.

TIKR Advanced Model Analysis
- Current Price: $424.30
- Target Price (Mid): ~$733
- Potential Total Return: ~73%
- Annualized IRR: ~14% / year
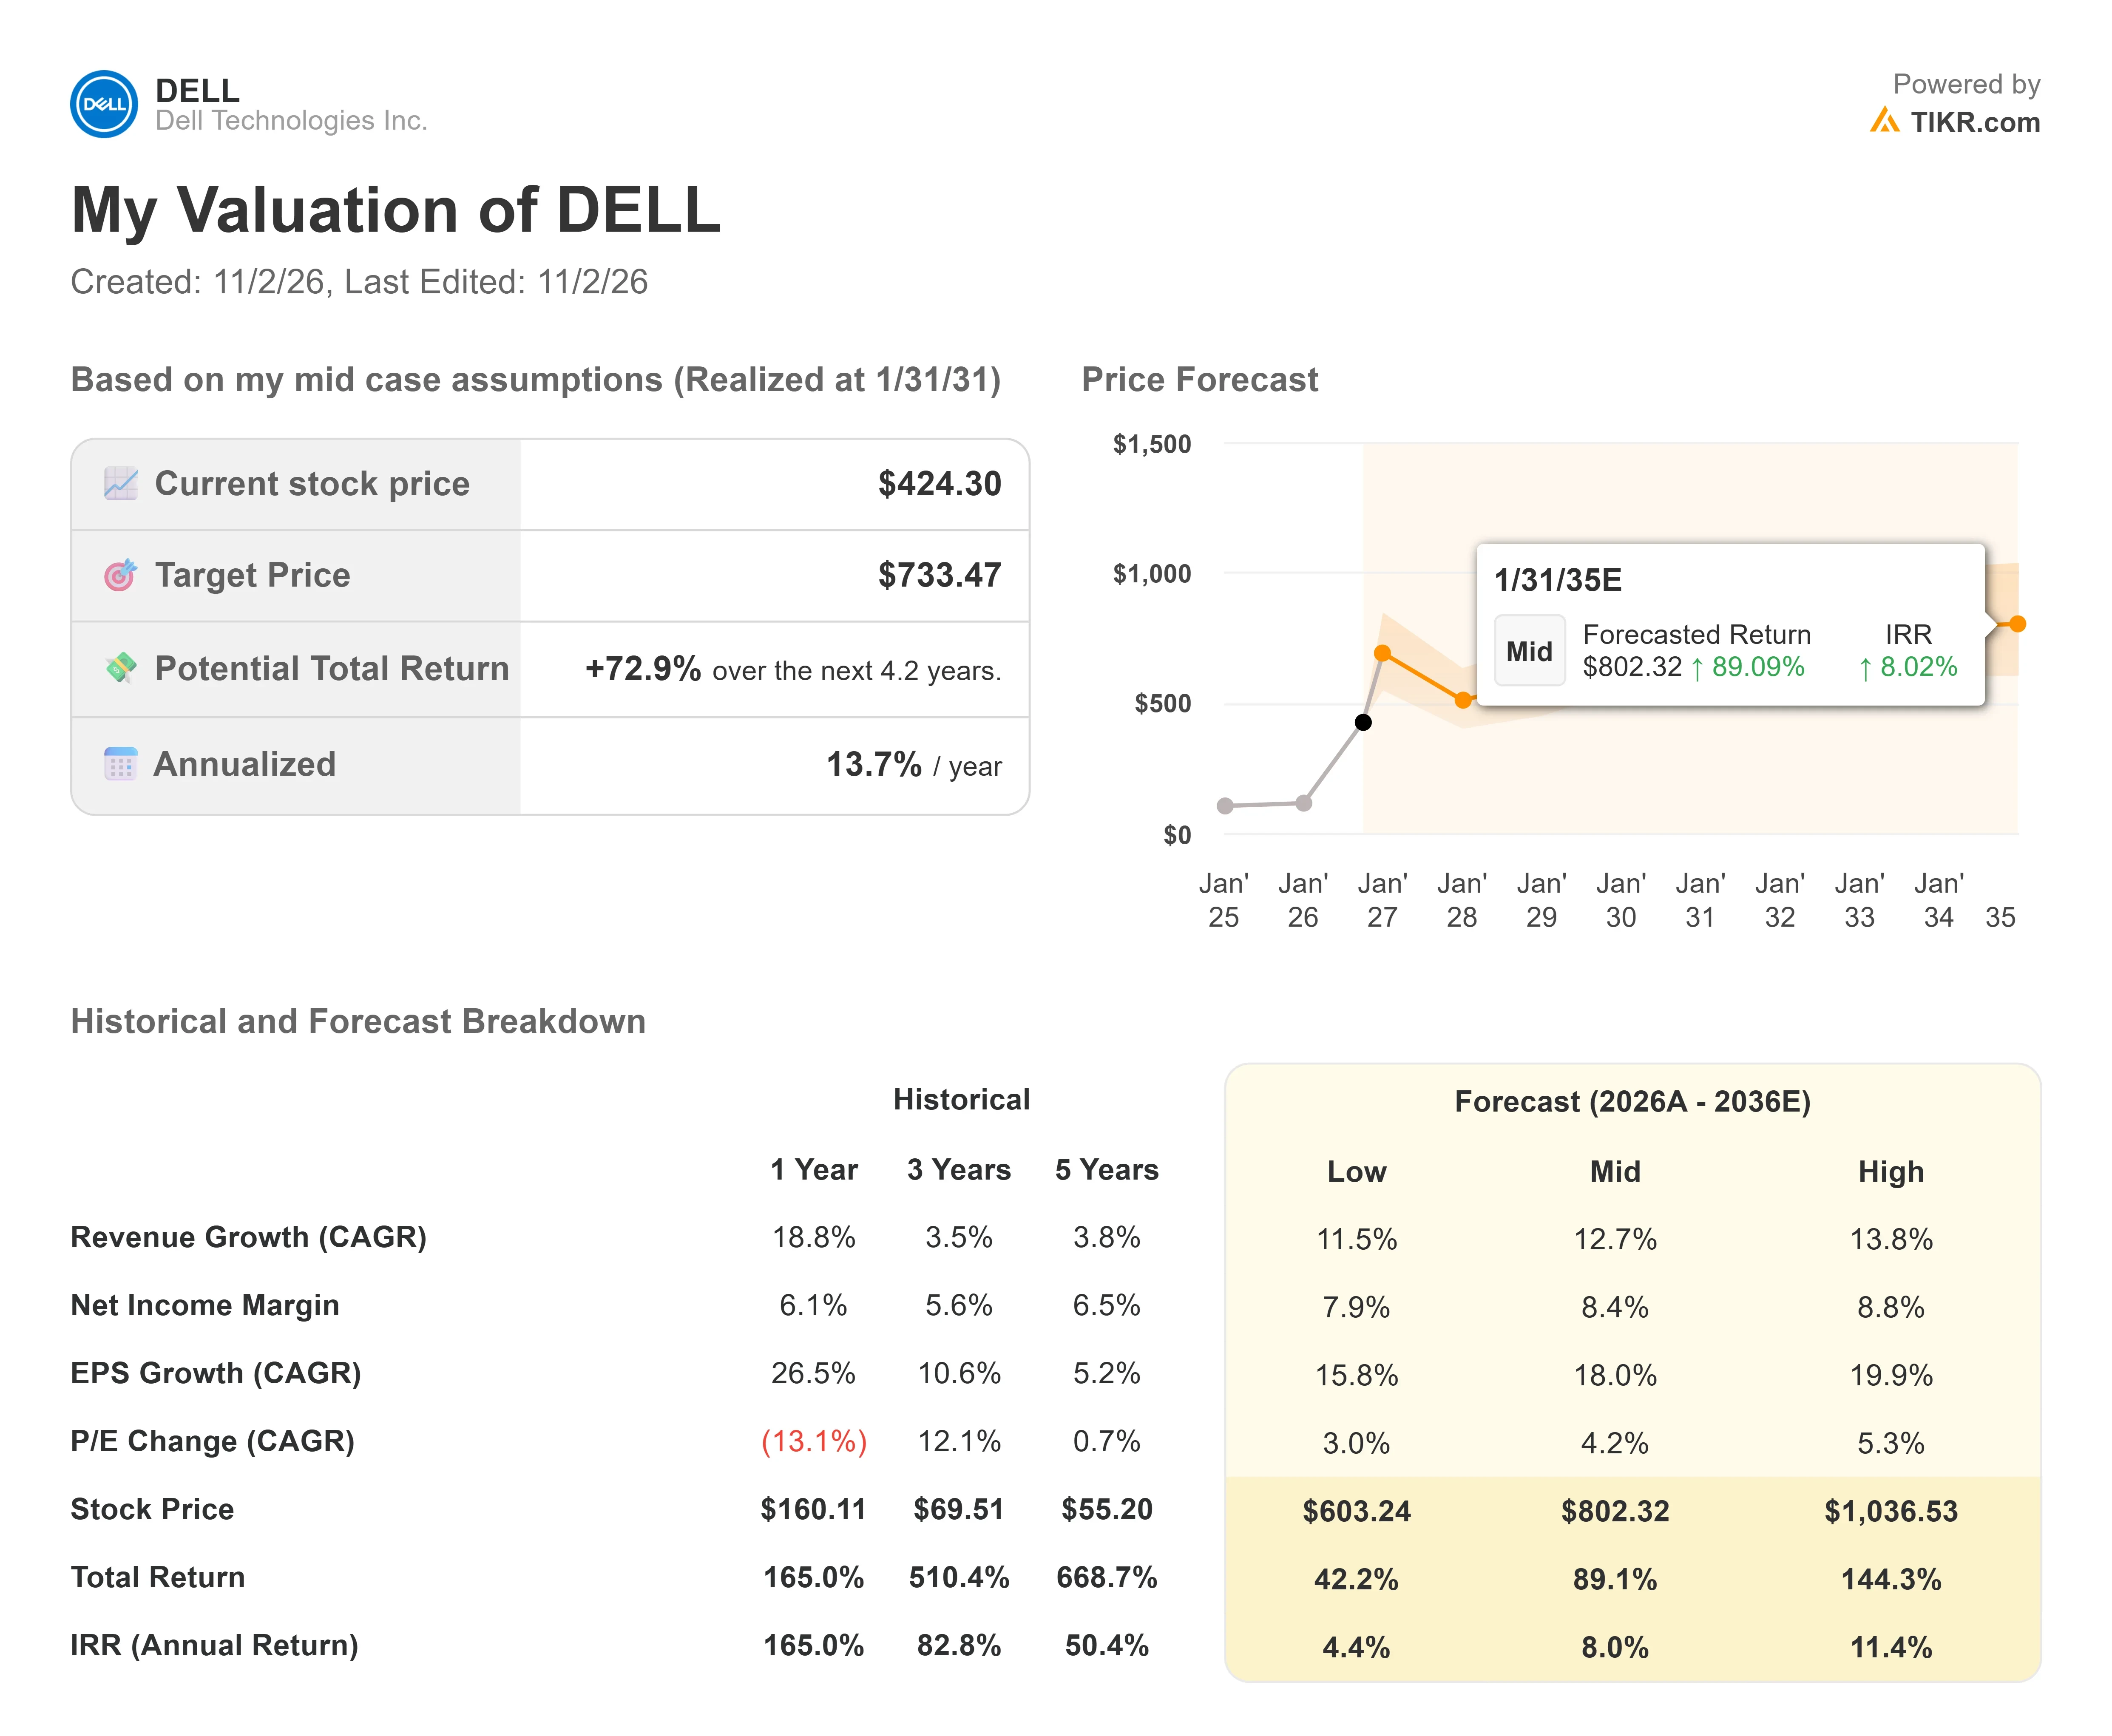
The mid case is the model’s base scenario. Its inputs run through fiscal 2036. They assume revenue grows about 13% a year and net income margin settles near 8%, below the roughly 9% normalized margin analysts expect for fiscal 2027.
- Upside: CPU and memory supply loosen enough for Dell to meet the server demand Intel describes.
- Downside: shortages cap server shipments while PC orders shrink. Intel expects its own client chip revenue to fall more than 20% from the third quarter to the fourth as PC makers cut inventory.
Conclusion
Dell reports fiscal third-quarter results after the close on November 24. Client Solutions revenue above last year’s $12.5 billion would show Dell’s PC sales held up through the unit decline Intel described. A figure below that would mean Intel’s warning has reached Dell’s income statement.
So what is Dell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Dell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!