Key Takeaways
- Datadog stock has gained 98% year to date through October 23, closing at $269.65 after another volatile week.
- Bernstein upgraded Datadog to Outperform with a $350 price target, while BofA raised its target to $335 ahead of earnings.
- Q2 revenue increased 36% to $1.12 billion, significantly outpacing rival Dynatrace’s 16% quarterly revenue growth.
- With shares trading at a premium valuation and Q3 earnings approaching on November 4, taking some profits looks more attractive than aggressively buying more.
Datadog (DDOG) has been one of the strongest-performing software stocks in 2026, with shares rising 98% year to date through October 23.
The stock closed at $269.65 on Friday, rebounding 4.6% after falling 5.6% the previous session amid reports of a potential multibillion-dollar acquisition.
Despite the volatility, Wall Street remains optimistic that accelerating cloud demand and rising AI workloads could support further growth.
The question is whether Datadog’s improving fundamentals can justify its premium valuation after such a massive rally.
Wall Street Keeps Getting More Bullish on Datadog
Analyst optimism has helped drive Datadog’s recent performance.
On October 9, shares jumped 7.1% to a record closing price of $293.26 as technology stocks rebounded and CIBC raised its price target to $315 from $280.
Shares subsequently reached an intraday 52-week high of $300.68 on October 12 before retreating.
On October 19, Bernstein upgraded Datadog to Outperform from Market Perform and increased its price target to $350 from $237.
Analyst Peter Weed cited stronger-than-expected AI-native customer demand, with enterprise token consumption growing faster than previously modeled.
BofA followed on October 23, raising its price target to $335 from $305 while maintaining its Buy rating.
These upgrades suggest analysts increasingly expect Datadog to benefit from continued AI infrastructure spending.
Datadog’s Growth Is Accelerating Beyond AI Customers
Datadog reported second-quarter revenue of $1.12 billion, up 36% year over year, marking its fifth consecutive quarter of accelerating revenue growth.
For comparison, rival Dynatrace (DT) reported $555 million in revenue for its quarter ended June 30, representing 16% year-over-year growth.
Datadog’s faster expansion helps explain its premium valuation, although both companies are benefiting from enterprise cloud monitoring demand.
Importantly, Datadog’s momentum extends beyond its largest AI customers.
Revenue from non-AI customers grew in the high 20% range, compared with 18% a year earlier.
Datadog also generated $316 million in operating cash flow and $279 million in free cash flow during Q2.
However, shares dropped 16.6% following the August earnings report as investors worried about reduced consumption from its largest AI customer.
Management’s Q3 revenue guidance of $1.135 billion to $1.145 billion assumed that customer would contribute only at its contractual minimum.
If AI consumption improves while the broader customer base maintains its momentum, Datadog could exceed those expectations.
Datadog’s Valuation Leaves Little Room for Error
The biggest concern is how much investors are already paying for that growth.
Datadog’s forward P/E increased from 47.4 times on February 23 to 93.2 times on October 16.
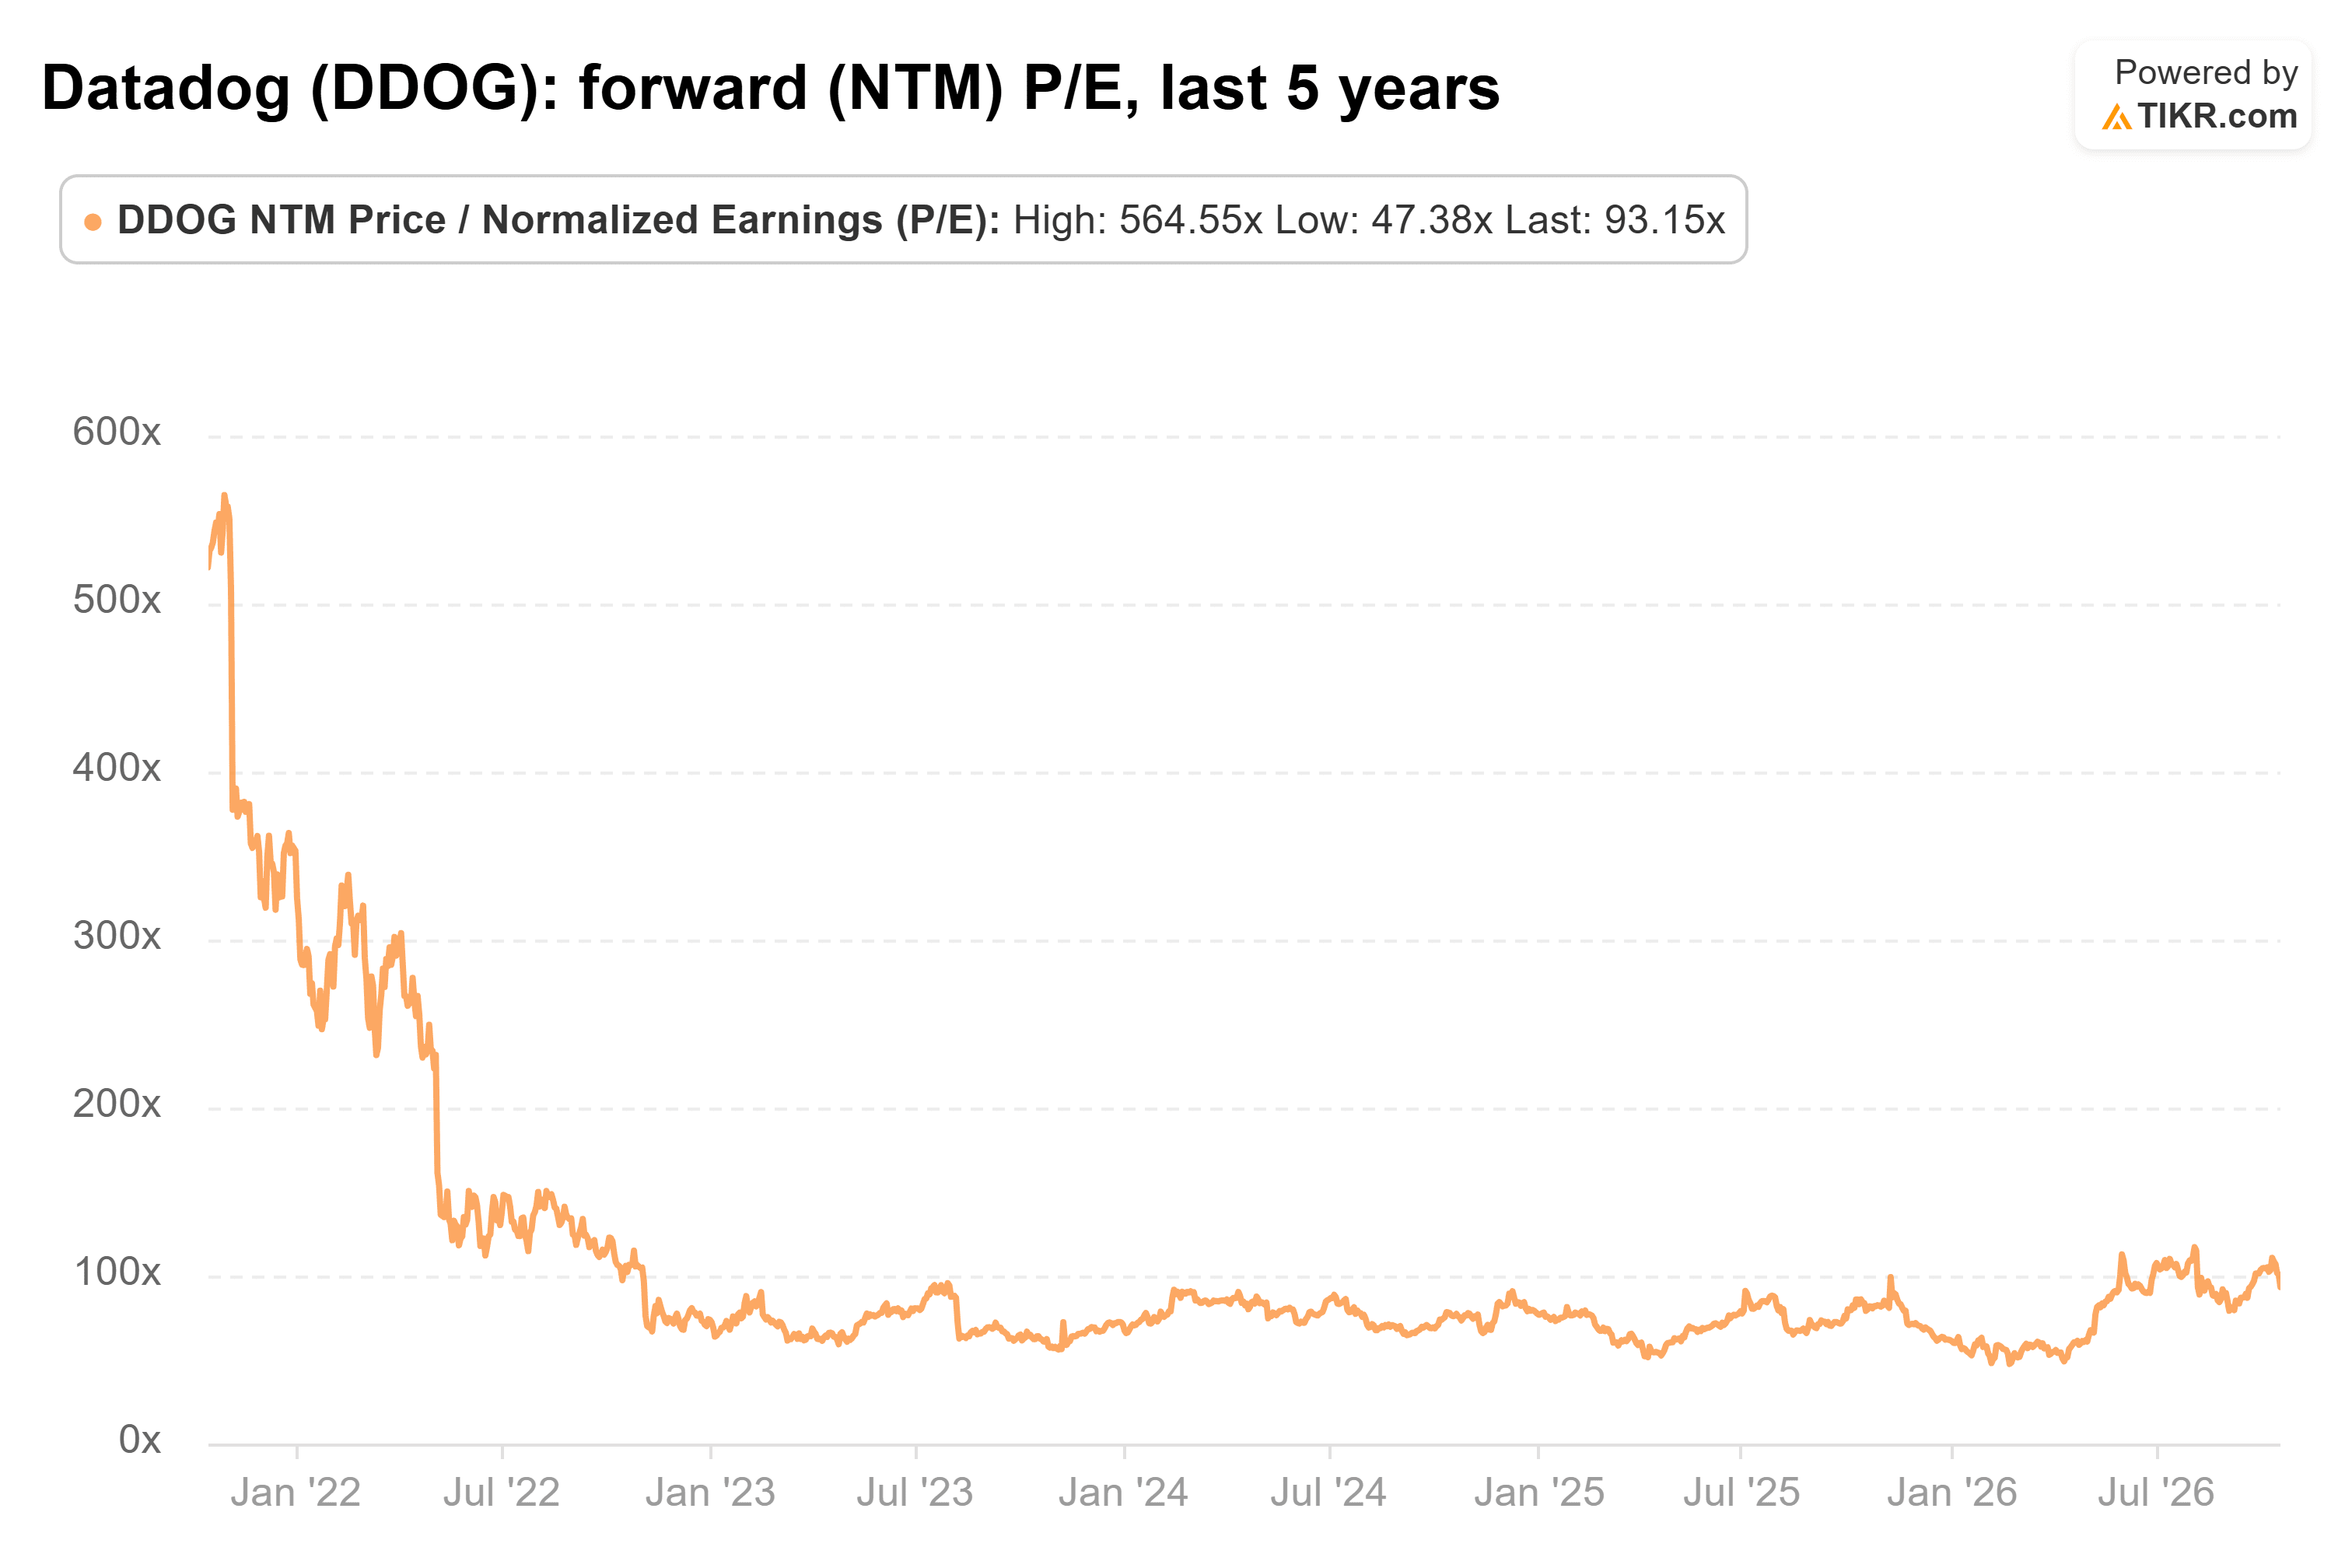
That valuation expansion significantly outpaced the approximately 23% increase in forecast next-12-month earnings between late March and early October.
Datadog’s five-year average forward P/E is approximately 108 times, although unusually high valuations during 2021 significantly inflate that figure.
Analysts still expect substantial growth.
Consensus forecasts call for revenue to increase from $3.43 billion in fiscal 2025 to $4.47 billion in 2026 and $6.78 billion by 2028.
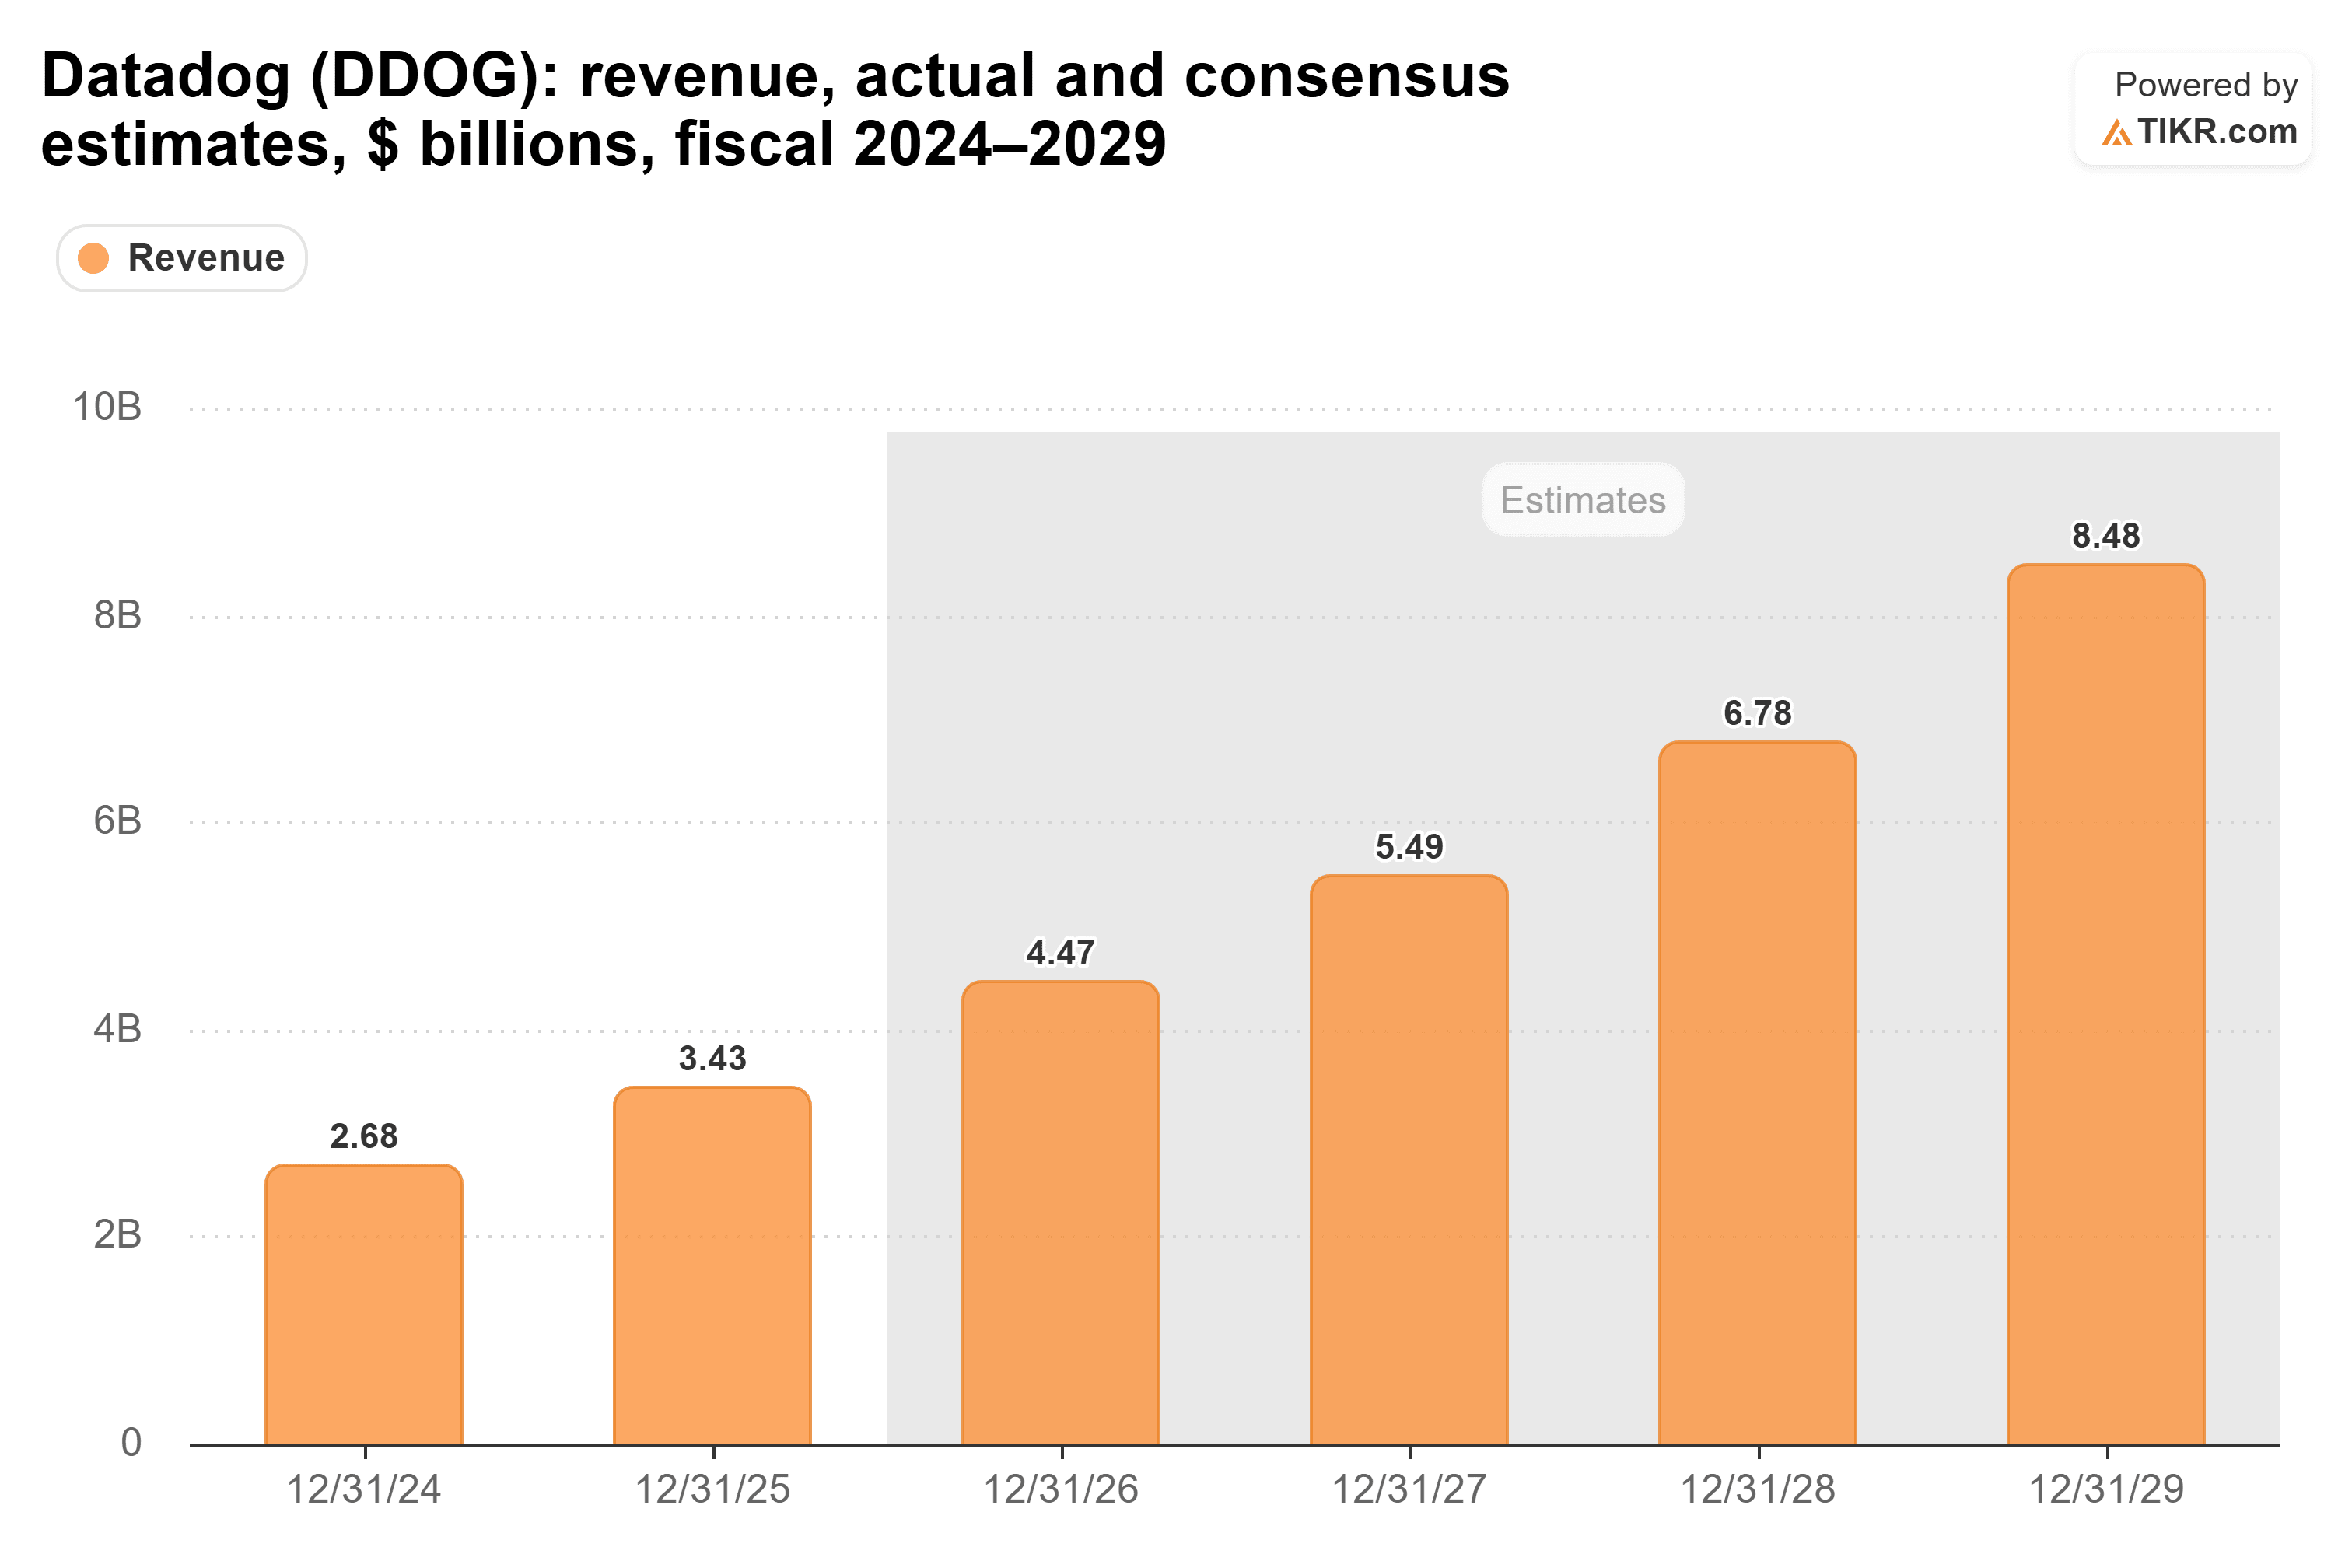
Those projections support Datadog’s long-term growth opportunity, but investors are already paying for much of that optimism.
Wall Street Sees Around 9% Upside
Analysts have steadily increased their Datadog price targets over the past year.
The average target has climbed from approximately $168 a year ago to around $293.
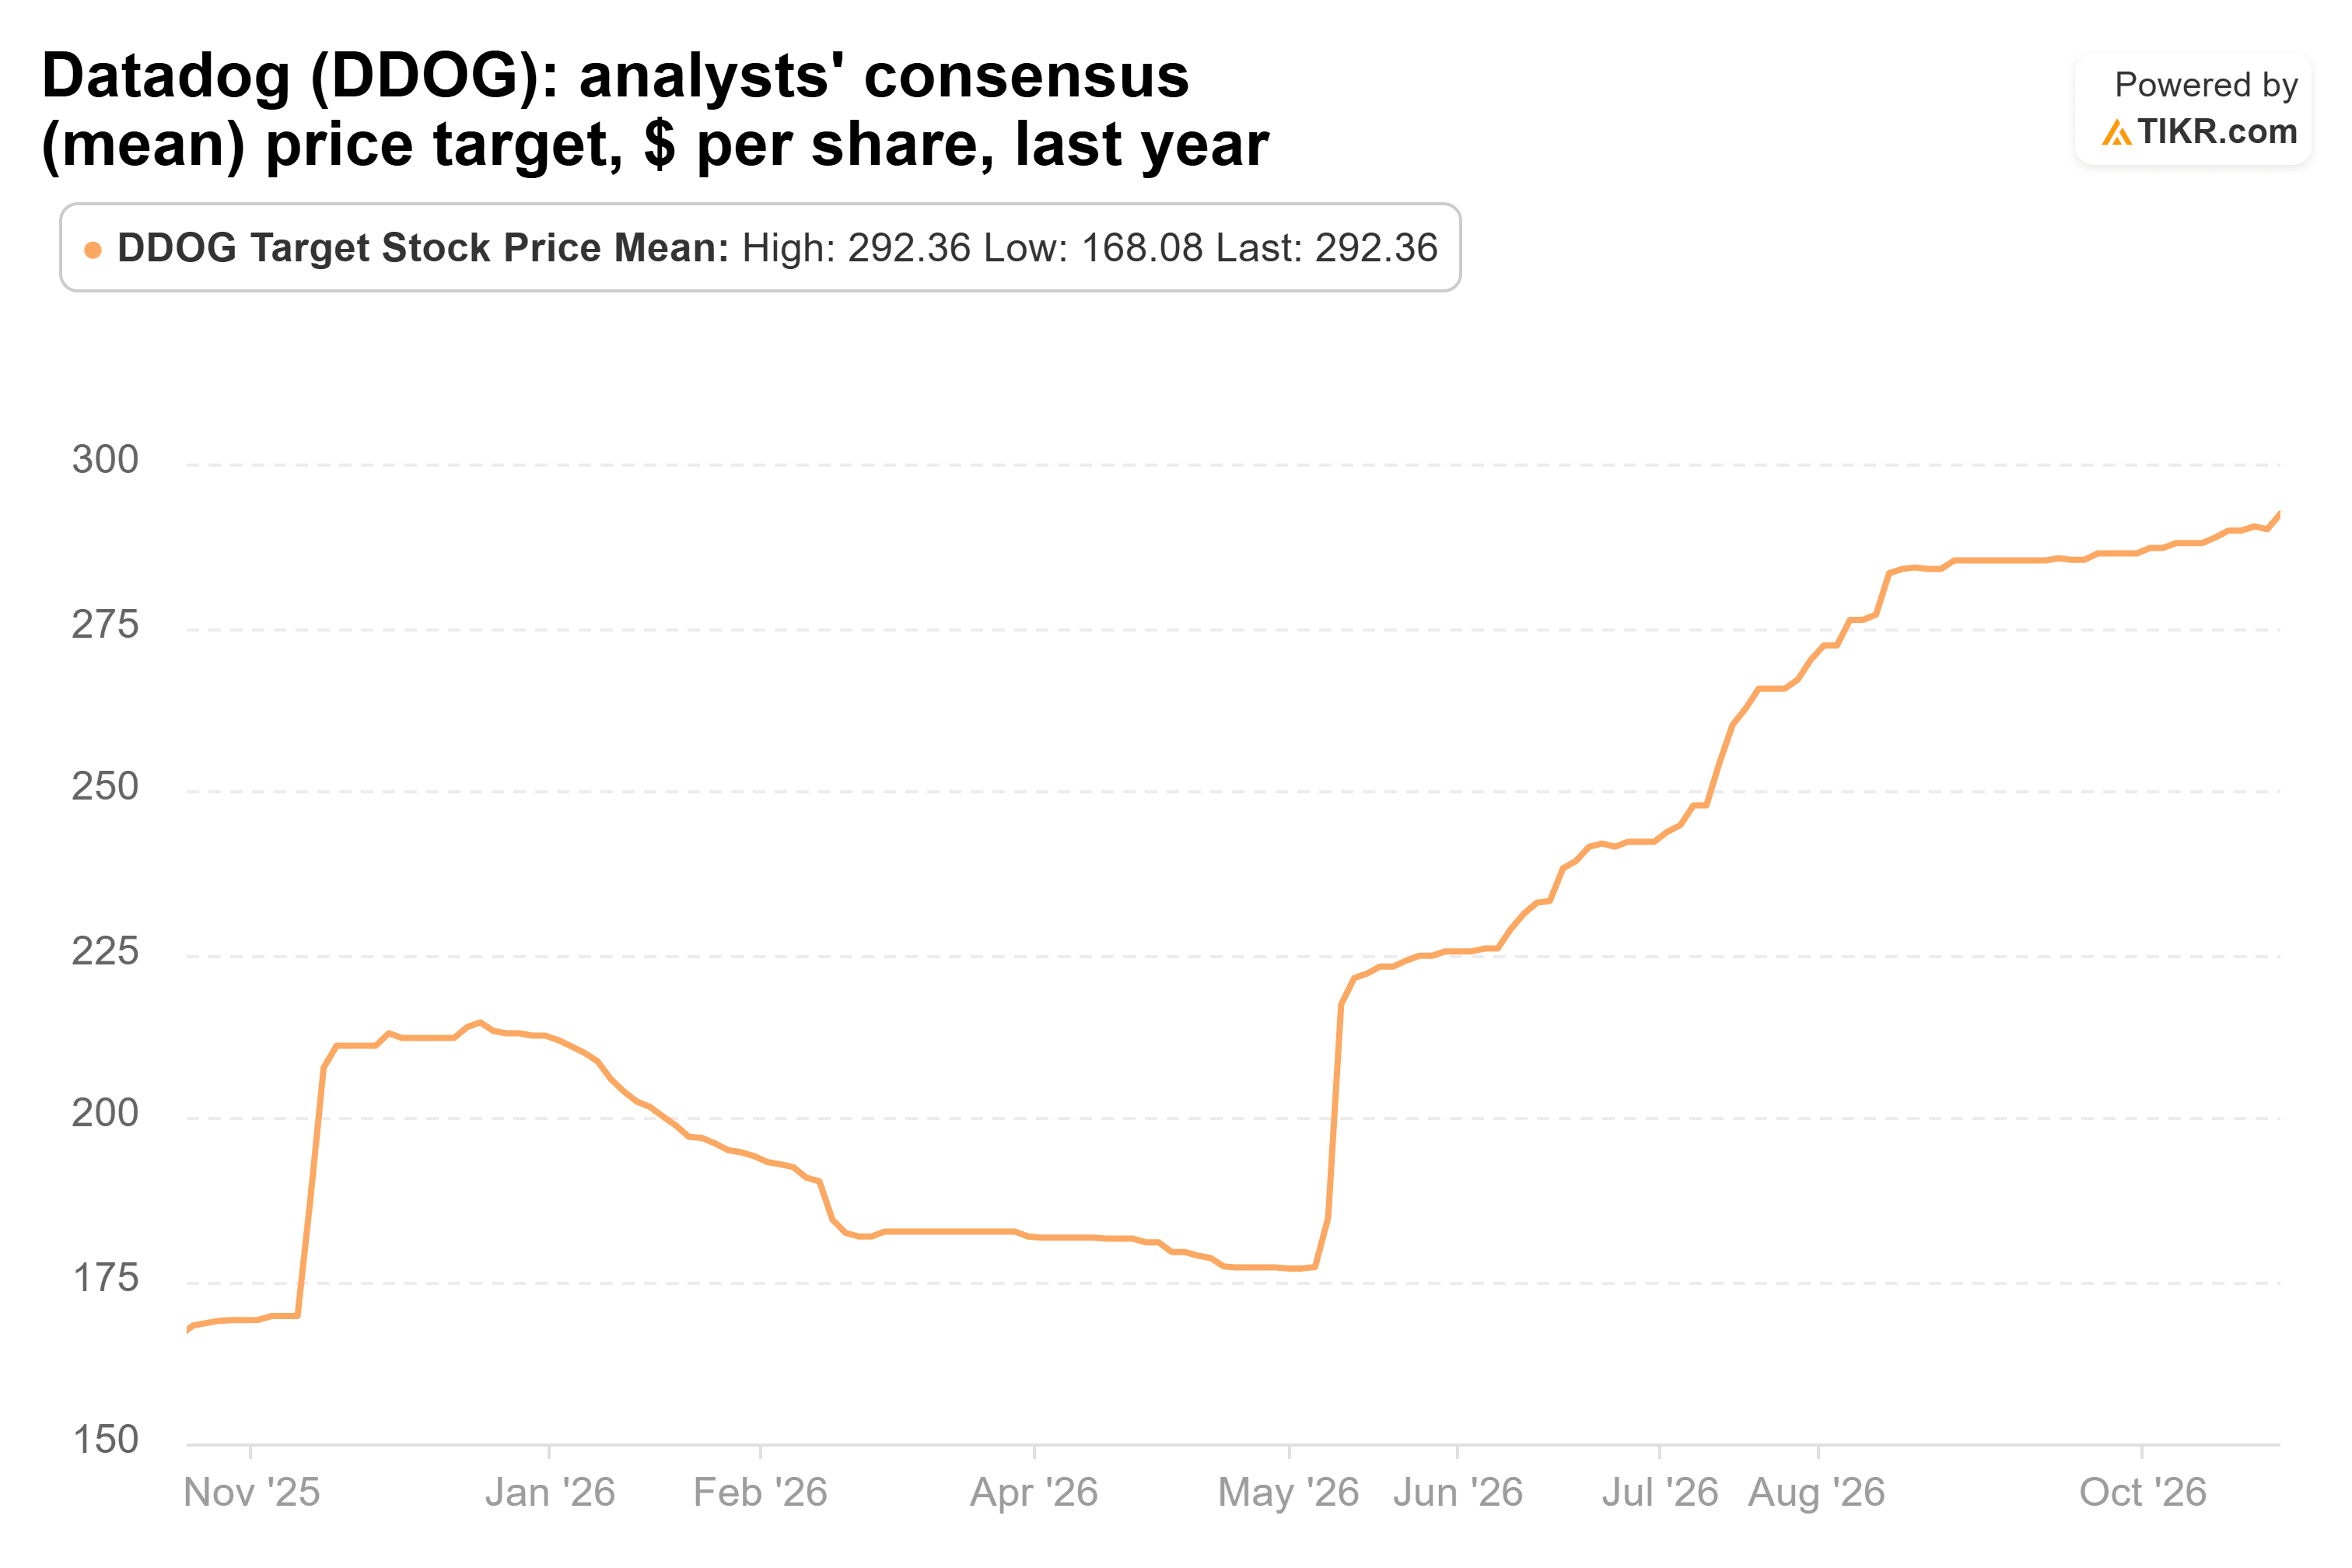
Against the October 23 closing price of $269.65, the $293 consensus target implies approximately 9% upside.
Bernstein’s $350 target represents a more optimistic outlook, while the lowest analyst target remains $158.
The wide range highlights uncertainty surrounding Datadog’s ability to sustain rapid growth while maintaining its premium valuation.
November 4 Earnings Could Be the Next Major Catalyst
Datadog is scheduled to report third-quarter results before the market opens on November 4.
Analysts expect adjusted EPS of around $0.64, within management’s guidance range of $0.63 to $0.65.
Revenue performance will be especially important.
Investors should watch whether Datadog exceeds the $1.145 billion upper end of its revenue guidance and whether AI-related customer consumption is improving.
Another development is Datadog’s reported offer of nearly $4 billion to acquire cloud security startup Upwind Security.
No completed transaction has been confirmed.
A potential acquisition could strengthen Datadog’s cloud security offering, although it would also require substantial capital.
Datadog had approximately $5 billion in cash, cash equivalents, and marketable securities at the end of June.
Is Datadog Stock Still Worth Buying After Its Rally?
Datadog’s long-term growth story remains attractive, but after the stock nearly doubled in 2026, taking some profits looks more appealing than aggressively buying more shares at current prices.
Revenue growth is accelerating, non-AI customers are spending more, and improving AI demand could support another strong earnings report.
However, with Datadog trading at a premium valuation and Wall Street’s consensus price target implying only around 9% upside, investors are already paying a substantial premium for future growth.
That doesn’t mean investors need to sell their entire positions. Long-term shareholders could still benefit if Datadog continues exceeding expectations.
But for investors sitting on significant gains, trimming a portion of their holdings could reduce exposure ahead of November 4 earnings while preserving participation in the company’s long-term growth.
Between taking profits and buying more, taking some profits appears to be the better choice at Datadog’s current valuation.
So what is Datadog stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Datadog could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!