Key Takeaways
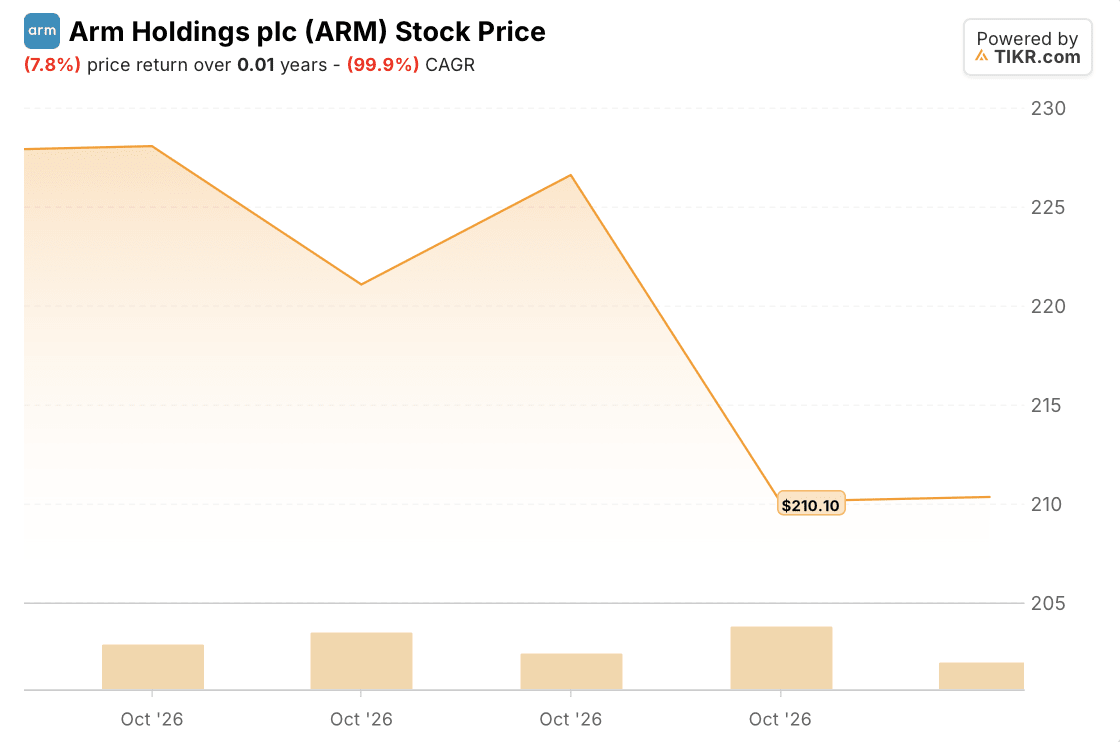
- Arm stock is down 7.8% over the past week to $210.33 on October 23, with a 7.28% drop on October 22 accounting for nearly all of it.
- Lam Research’s warning that supply constraints held back its $8.6 billion December-quarter guide came before a 6.72% one-day drop in the Philadelphia Semiconductor Index.
- Street EPS estimates climb from $2.23 in fiscal 2027 to $6.13 by fiscal 2030.
- November 4 brings Arm’s fiscal second-quarter report, guided at $1.38 billion in revenue and $0.47 in EPS.
Arm Holdings (ARM) stock is down 7.8% over the past week, closing at $210.33 on October 23. Nearly all of that came in one session: on October 22, Arm stock fell 7.28% to $210.10 after a supply warning from chip-equipment maker Lam Research (LRCX) pulled the whole semiconductor group lower.
Nothing in Lam’s warning was about Arm. But the problem Lam described, not enough supply to meet chip demand, is the same one Arm’s own management named in July as the limit on its newest business.
Arm Stock’s Week Came Down to One Thursday
The first three sessions went sideways. Arm stock held in the high $220s on Monday, slipped into the low $220s on Tuesday, then bounced back to $226.59 on Wednesday, October 21, as chip stocks rallied with the Nasdaq.
Then Lam spoke. On its October 21 earnings call, CFO Doug Bettinger said Lam’s December-quarter revenue guide of $8.6 billion would have been a bit higher without near-term supply chain constraints. By the next close, the Philadelphia Semiconductor Index had fallen 6.72%, and Arm’s 7.28% drop ran slightly deeper than the index. Friday added just $0.23.
Why a Supplier’s Warning Lands on Arm Stock
Arm’s last report gave the stock plenty to stand on. Revenue reached $1.29 billion in the fiscal first quarter, up 22%, and data center royalties more than doubled from a year earlier. Non-GAAP EPS rose 29% to $0.45, above the top of Arm’s own guidance.
The newer story is the Arm AGI CPU, a chip Arm sells itself instead of only licensing the designs. Arm said it has secured manufacturing capacity for a $1 billion opportunity across fiscal 2027 and fiscal 2028, while customer demand now exceeds $2 billion. Supply is what stands between those two numbers.
“It is a very, very, very tight market across everything,” CEO Rene Haas said on the Q1 fiscal 2027 earnings call, pointing to memory, test equipment, substrates and TSMC wafers. He said Arm’s confidence in securing more supply had improved over the prior 90 days, and CFO Jason Child said a fuller revenue and margin update on the chip will come with third-quarter results.
TIKR Tracks 44 Analysts on Arm Holdings. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arm Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arm Holdings’ Analyst Ratings
The Growth Analysts Have Built Into Arm Stock

The Street’s numbers barely leave room for a supply hiccup. Analysts expect normalized EPS of $2.23 for the fiscal year ending March 2027, rising to $3.07, $4.05 and then $6.13 by fiscal 2030. Revenue estimates climb from $6.06 billion to $16.27 billion over the same span.
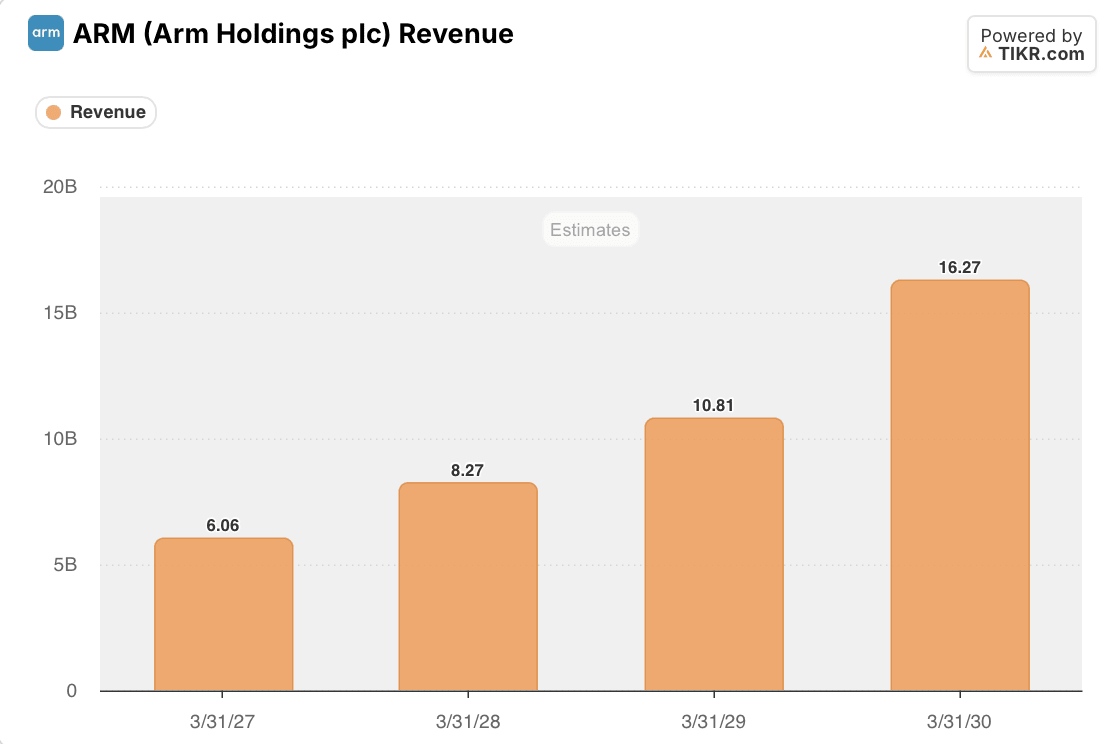
By my math, the fiscal 2027 revenue estimate implies 23.2% growth over last year’s $4.92 billion. It also means $210.33 still equals 94.3 times fiscal 2027 EPS and 68.5 times fiscal 2028 EPS. At those multiples, a delayed chip ramp costs the stock far more than a slow quarter would cost a cheaper name.
The November 4 Report That Tests Arm Stock
Arm reports fiscal second-quarter results on November 4. The company guided for revenue of $1.38 billion, plus or minus $50 million, and non-GAAP diluted EPS of $0.47, plus or minus $0.04, with royalty revenue growing in the low teens year over year.
The headline figures matter less than one sentence. If Arm still says supply is locked for the first $1 billion of AGI CPU revenue and holds the more-than-$2 billion demand line, last week reads as a sector selloff that Arm got caught in. If Arm lowers its supply expectations, that would raise the risk of delays to its AGI CPU revenue ramp.
The Qualcomm case sits in the background too. Qualcomm (QCOM) accounted for roughly $443 million of Arm’s revenue last fiscal year, and Judge Maryellen Noreika still has to decide whether an October 13 jury’s breach finding lets Qualcomm stop paying royalties for five years.
So What Is Arm Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ARM stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Arm Holdings plc for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!