Key Takeaways
- Robinhood stock rose about 3.8% Wednesday after Rosenblatt started coverage at Buy with a $135 price target.
- Rosenblatt argues that Robinhood has grown into a full financial platform whose growth deserves a premium valuation.
- Analysts expect normalized EPS to rise from $2.34 in 2025 to $4.39 in 2028, but only five to seven analysts make those estimates.
- If those earnings arrive, $135 is about 31x 2028 EPS, and third-quarter results on Oct. 27 are the next test.
Robinhood Markets (HOOD) stock rose about 3.8% in Wednesday trading after Rosenblatt started coverage at Buy with a $135 price target. The note landed after Tuesday’s close.
Rosenblatt admits the stock isn’t cheap, even after a pullback of about 20%. But analyst Chris Brendler calls Robinhood a “generational growth story” that deserves a premium valuation.
His case is that a commission-free trading app has become a full financial platform. He adds that its core brokerage is still taking share at its size. And Pattern Day Trading reform lifts a key limit on its most valuable customers.
That’s a sharp turn from a week earlier. Back then, Wolfe Research downgraded Robinhood to Peer Perform. Analyst Steven Chubak said the drivers of the bull case had “largely played out.”
Meanwhile, the platform keeps widening. On Oct. 22, Robinhood received authorization from the Dubai Financial Services Authority to launch retail investing in the Middle East. It also picked Dubai’s DIFC for its regional headquarters.
Pricey, but well off its peak
Rosenblatt is right that Robinhood isn’t cheap. It traded at about 33x forward earnings at Tuesday’s close…
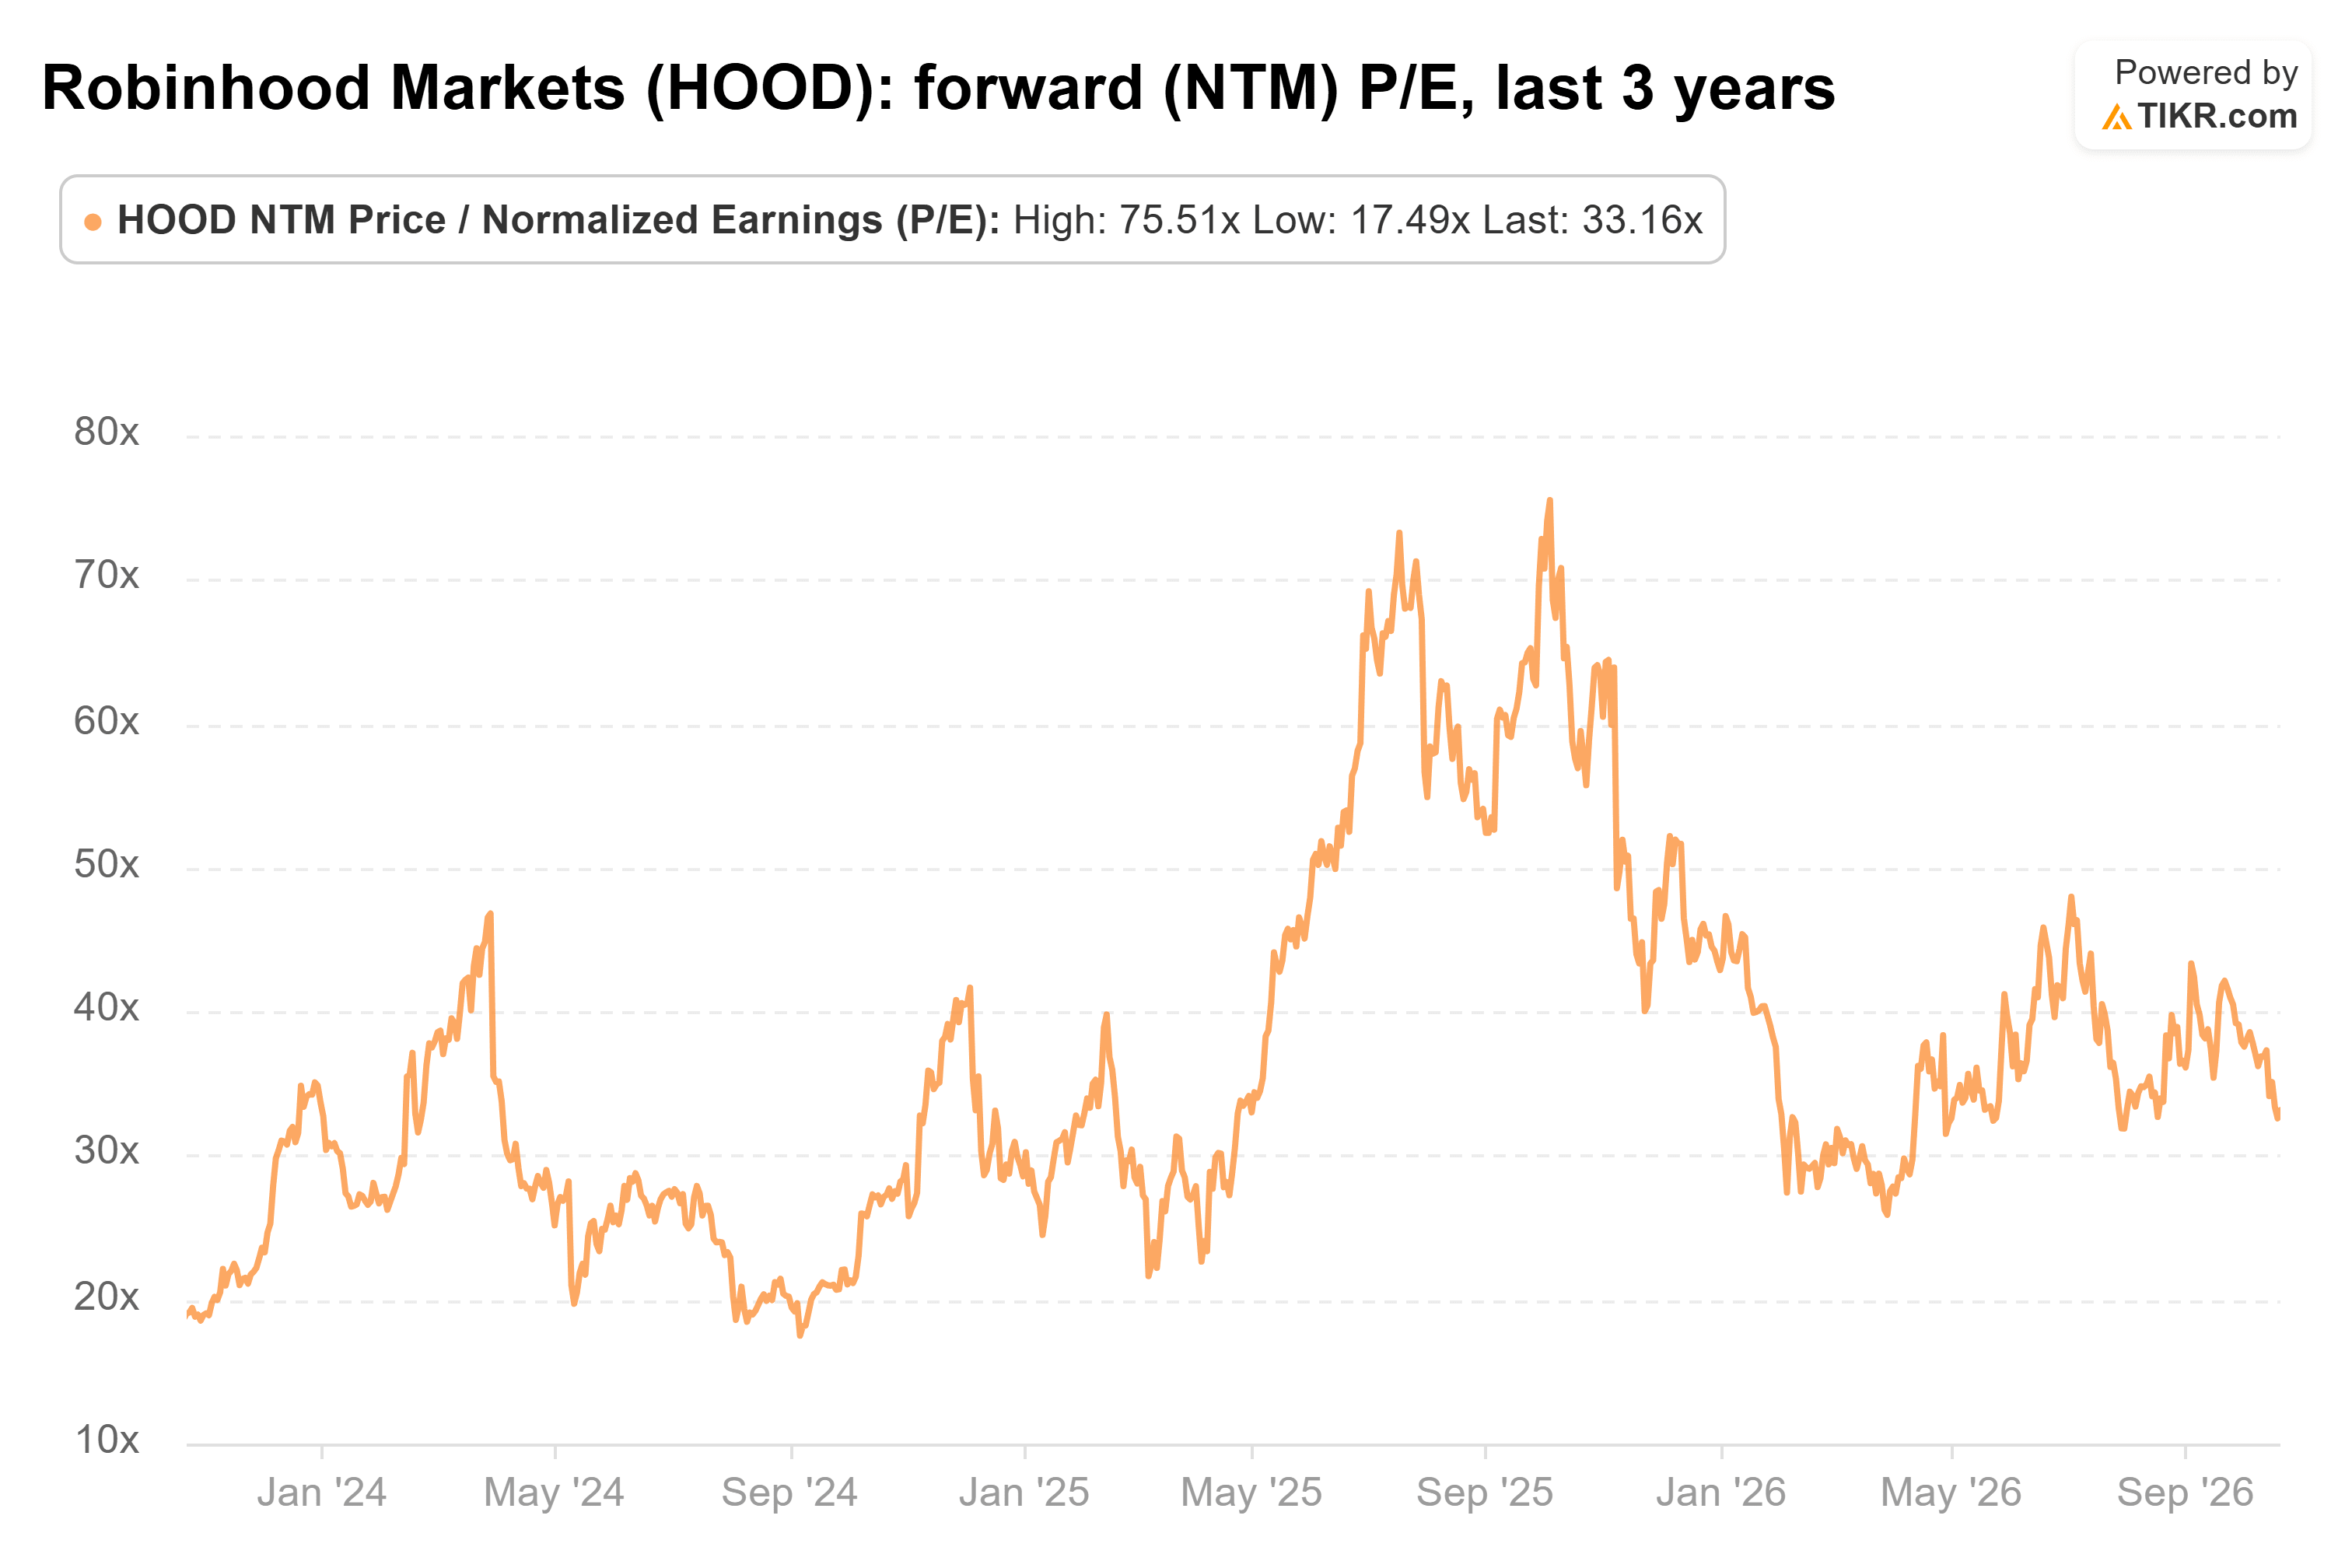
…which is below its three-year average of 36.4x and less than half its 75.5x peak in October 2025. (The multiple had been shrinking well before Wolfe’s downgrade.)
TIKR tracks 32 analysts on Robinhood. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Robinhood, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Robinhood’s Analyst Ratings
The earnings have to show up
So the premium is already smaller than it was. What the $135 target really needs is growth, and Wall Street expects plenty. Robinhood’s revenue rose from $1.87 billion in 2023 to $4.47 billion in 2025, and analysts expect $7.99 billion by 2028…
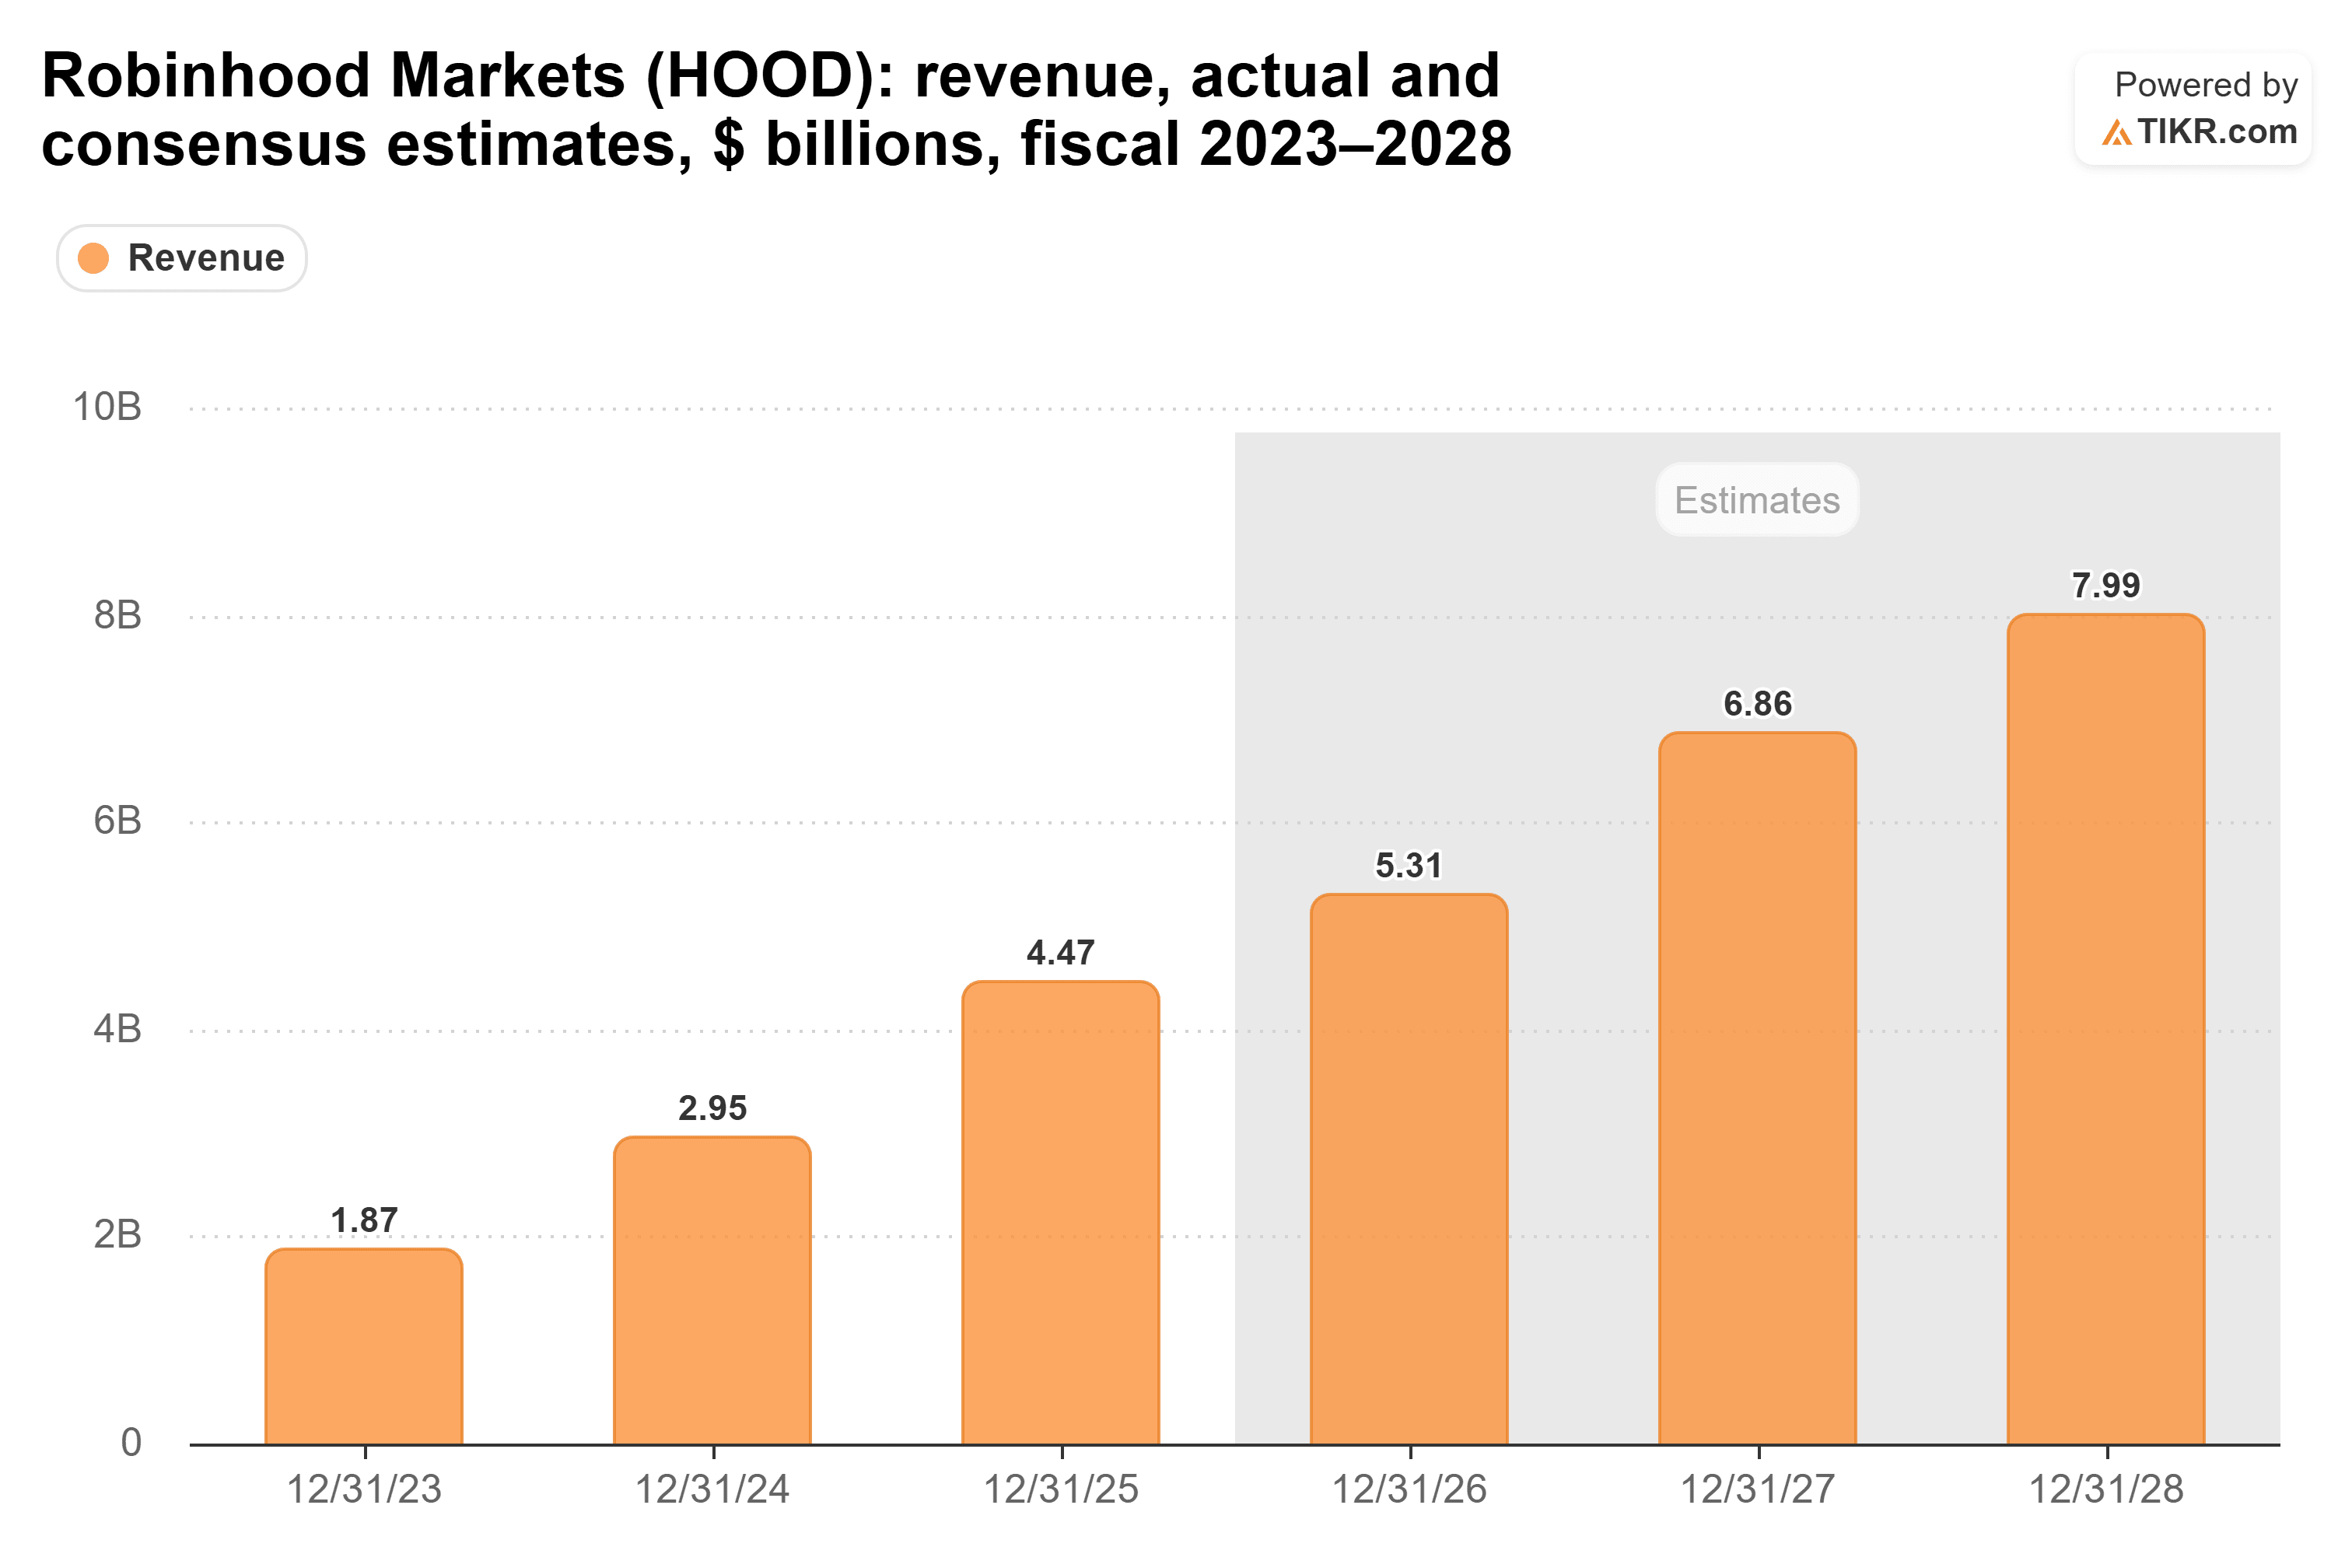
…and normalized EPS to climb from $2.34 in 2025 to $4.39 in 2028.
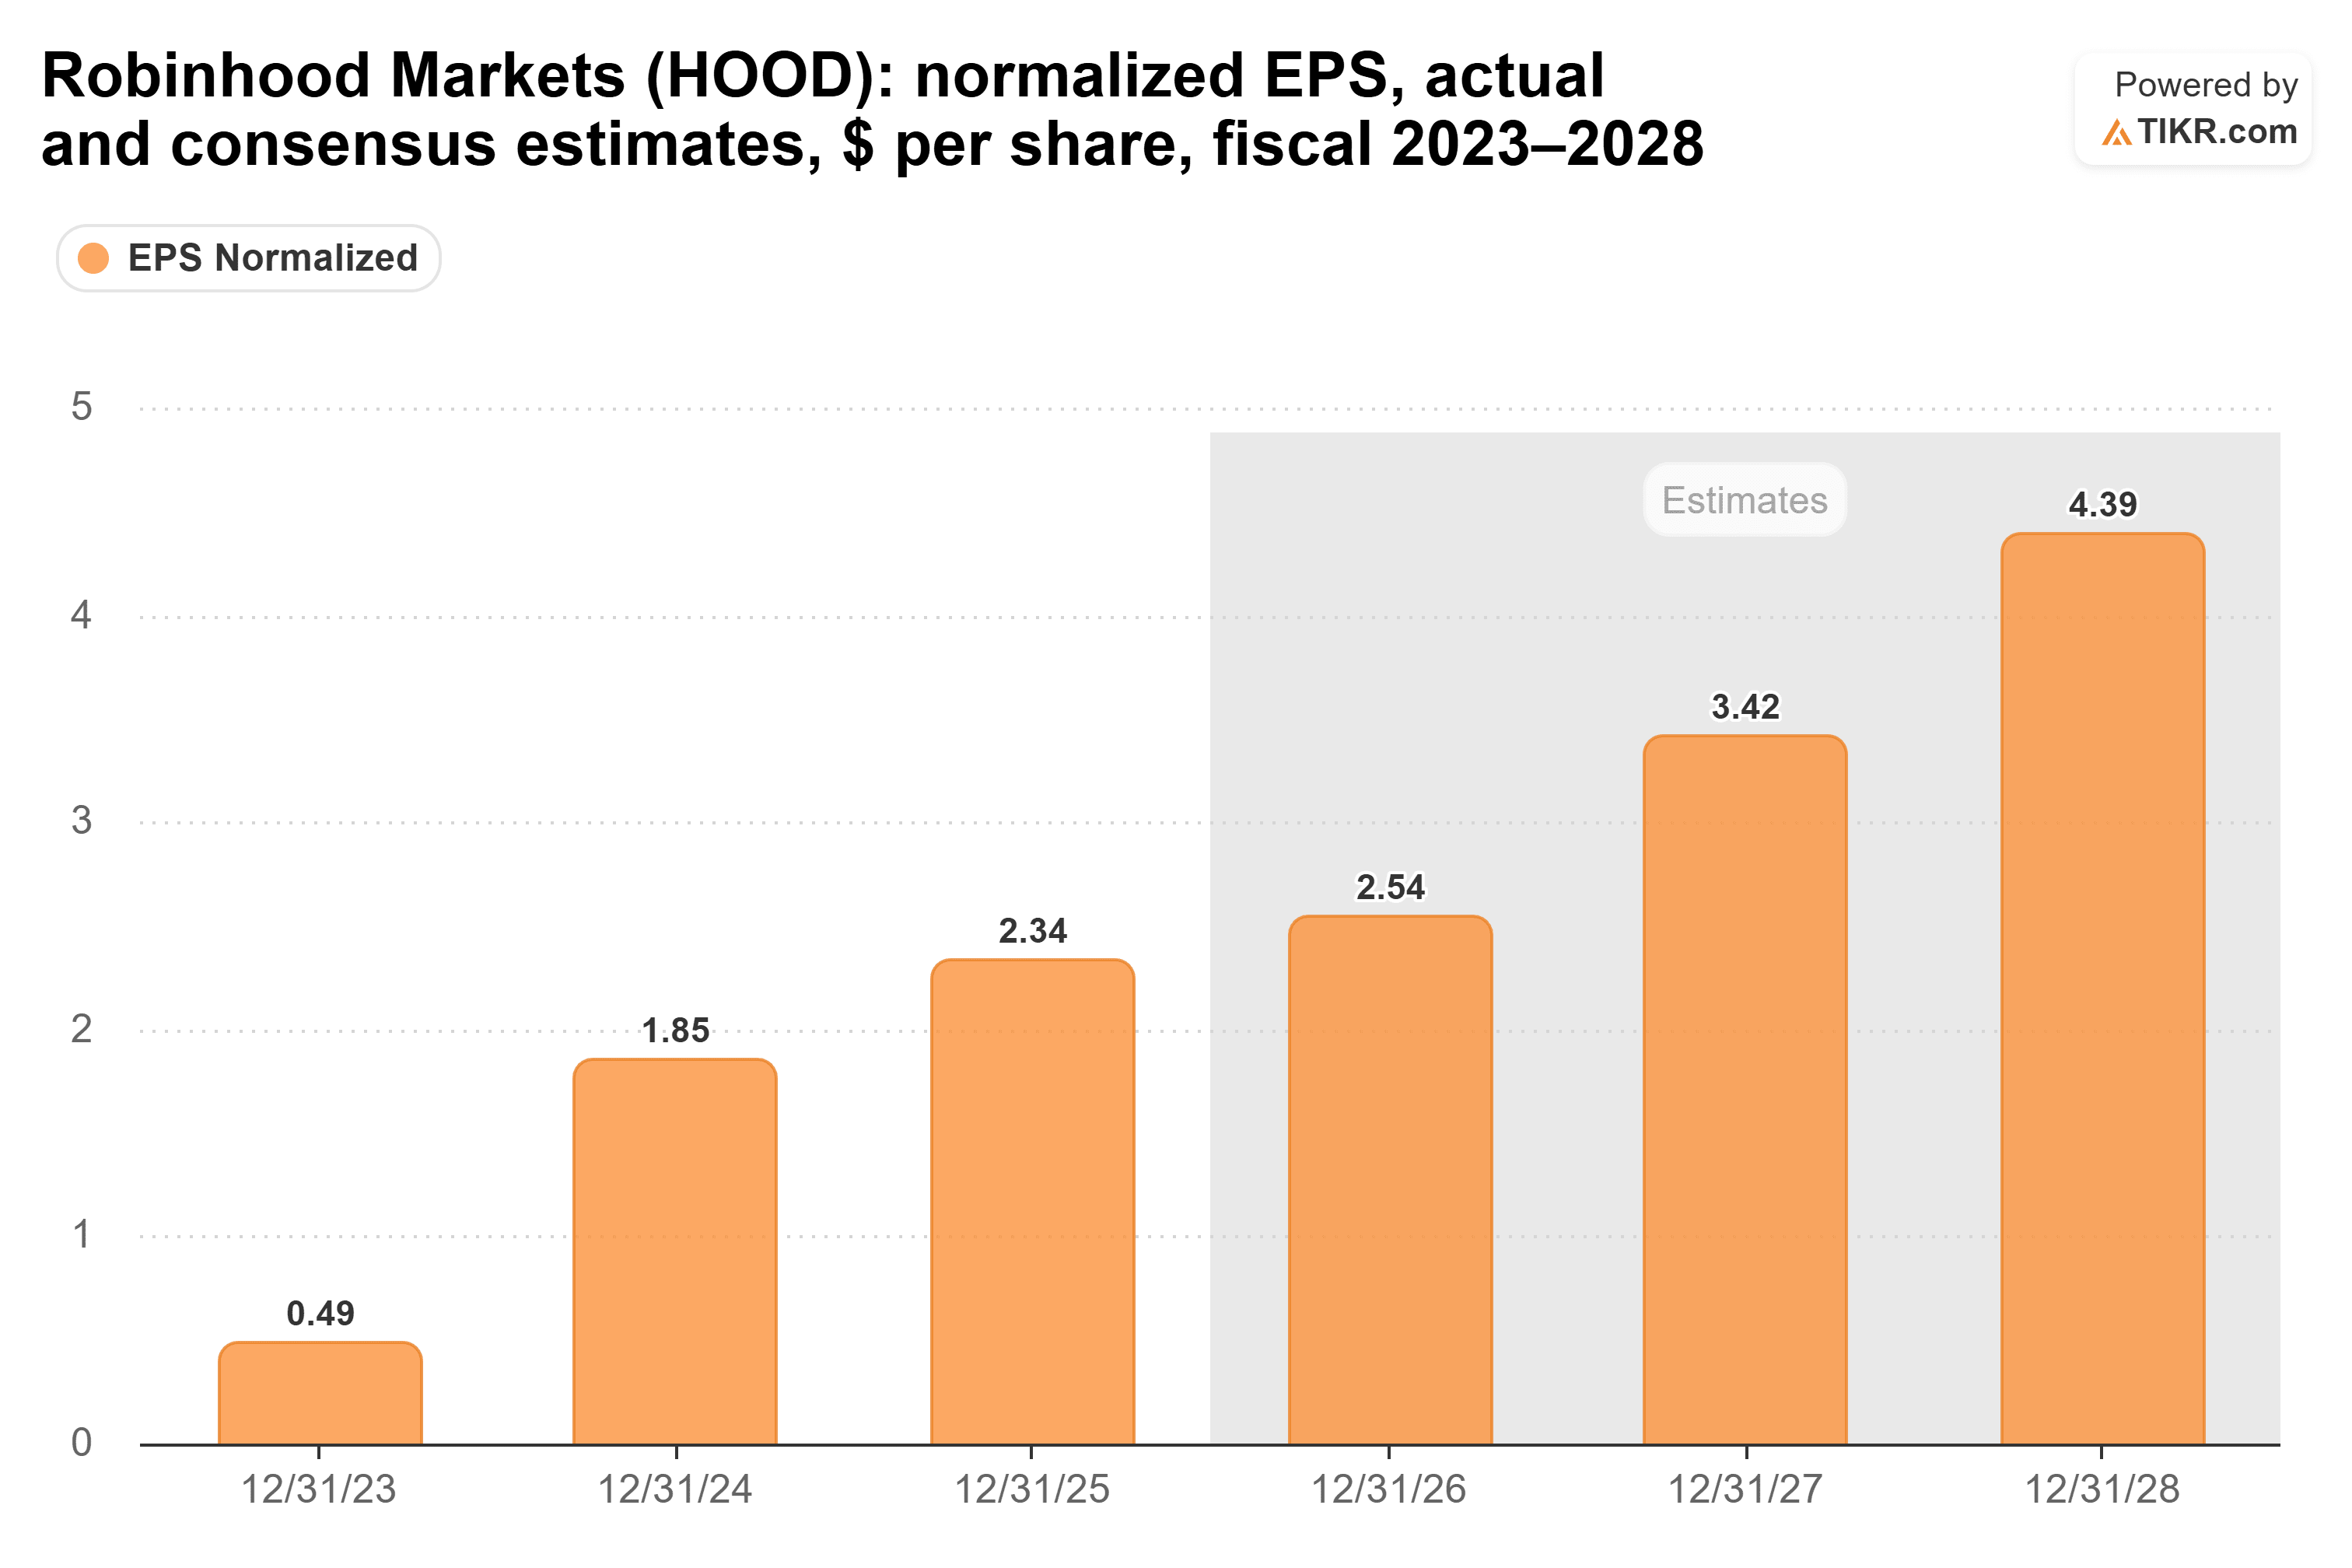
If Robinhood gets there, $135 is about 31x its 2028 earnings, a bit below the current multiple. (A year from now, when the target comes due, 2028 is mostly what the market will be pricing.)
Of course, most of that growth comes later. Analysts expect only $2.54 of EPS this year. And the EPS estimates come from just five to seven analysts, against 27 on revenue.
The recent track record is mixed, too. Robinhood missed revenue estimates in the fourth quarter of 2025 and again in the first quarter of 2026. The first quarter miss was steep, at $1.07 billion against about $1.18 billion expected. Then it beat in the second quarter, with $1.31 billion against $1.28 billion.
Insiders have been selling, as well. Director Baiju Bhatt just reported a $5.16 million share sale. CEO Vladimir Tenev sold $42.75 million of Class A shares in early October. Founders sell for plenty of reasons, so I’d treat that as a footnote.
Robinhood reports third-quarter results on Oct. 27, and that’s the first real test of whether those estimates hold.
My take: Rosenblatt’s call holds up. If Robinhood delivers the earnings analysts already expect, $135 looks reasonable at the multiple it trades at now.
So what is Robinhood stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Robinhood could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!