


Key Takeaways
- CoreWeave fell 11.3% last week to $54, just above its $53.50 52-week low, as fears over AI-related debt hit neocloud stocks.
- Q2 revenue jumped 112% to $2.58 billion, and the backlog reached about $104 billion before more than $25 billion of new commitments.
- Q3 guidance calls for $860 million to $940 million of interest expense against only $200 million to $260 million of adjusted operating income.
- The November 12 Q3 report must show capacity coming online fast enough to service about $46 billion of net debt.
CoreWeave (CRWV) has a demand problem most companies would love. Customers keep signing, prices are rising, and near-term capacity is sold out.
Yet shares fell 11.3% last week to $54, a hair above the $53.50 52-week low. Short sellers have booked about $6 billion of paper profits as neocloud stocks slid on AI debt fears.
The stock now sits roughly 62% below its 52-week high of $141.79.
The concern is simple arithmetic. CoreWeave’s lenders get paid before its shareholders, and that gap widens next quarter.
Growth showed up with a bill
Q2 was strong on the top line. Here is what CoreWeave reported on August 11:
- Revenue of $2.58 billion, up 112%, ahead of the $2.56 billion consensus
- Adjusted EBITDA of $1.51 billion, a 59% margin
- A GAAP net loss of $626 million, with interest expense of $640 million
Management also raised 2026 revenue guidance to $12.4 billion to $13.2 billion and guided Q3 revenue to $3.45 billion to $3.60 billion.
CEO Michael Intrator said in the release that CoreWeave’s “scale began to translate into expanding operating leverage.” That is true at the EBITDA line. Below it, depreciation and interest still swallow the gains.
Each quarter has stacked meaningfully on the last…
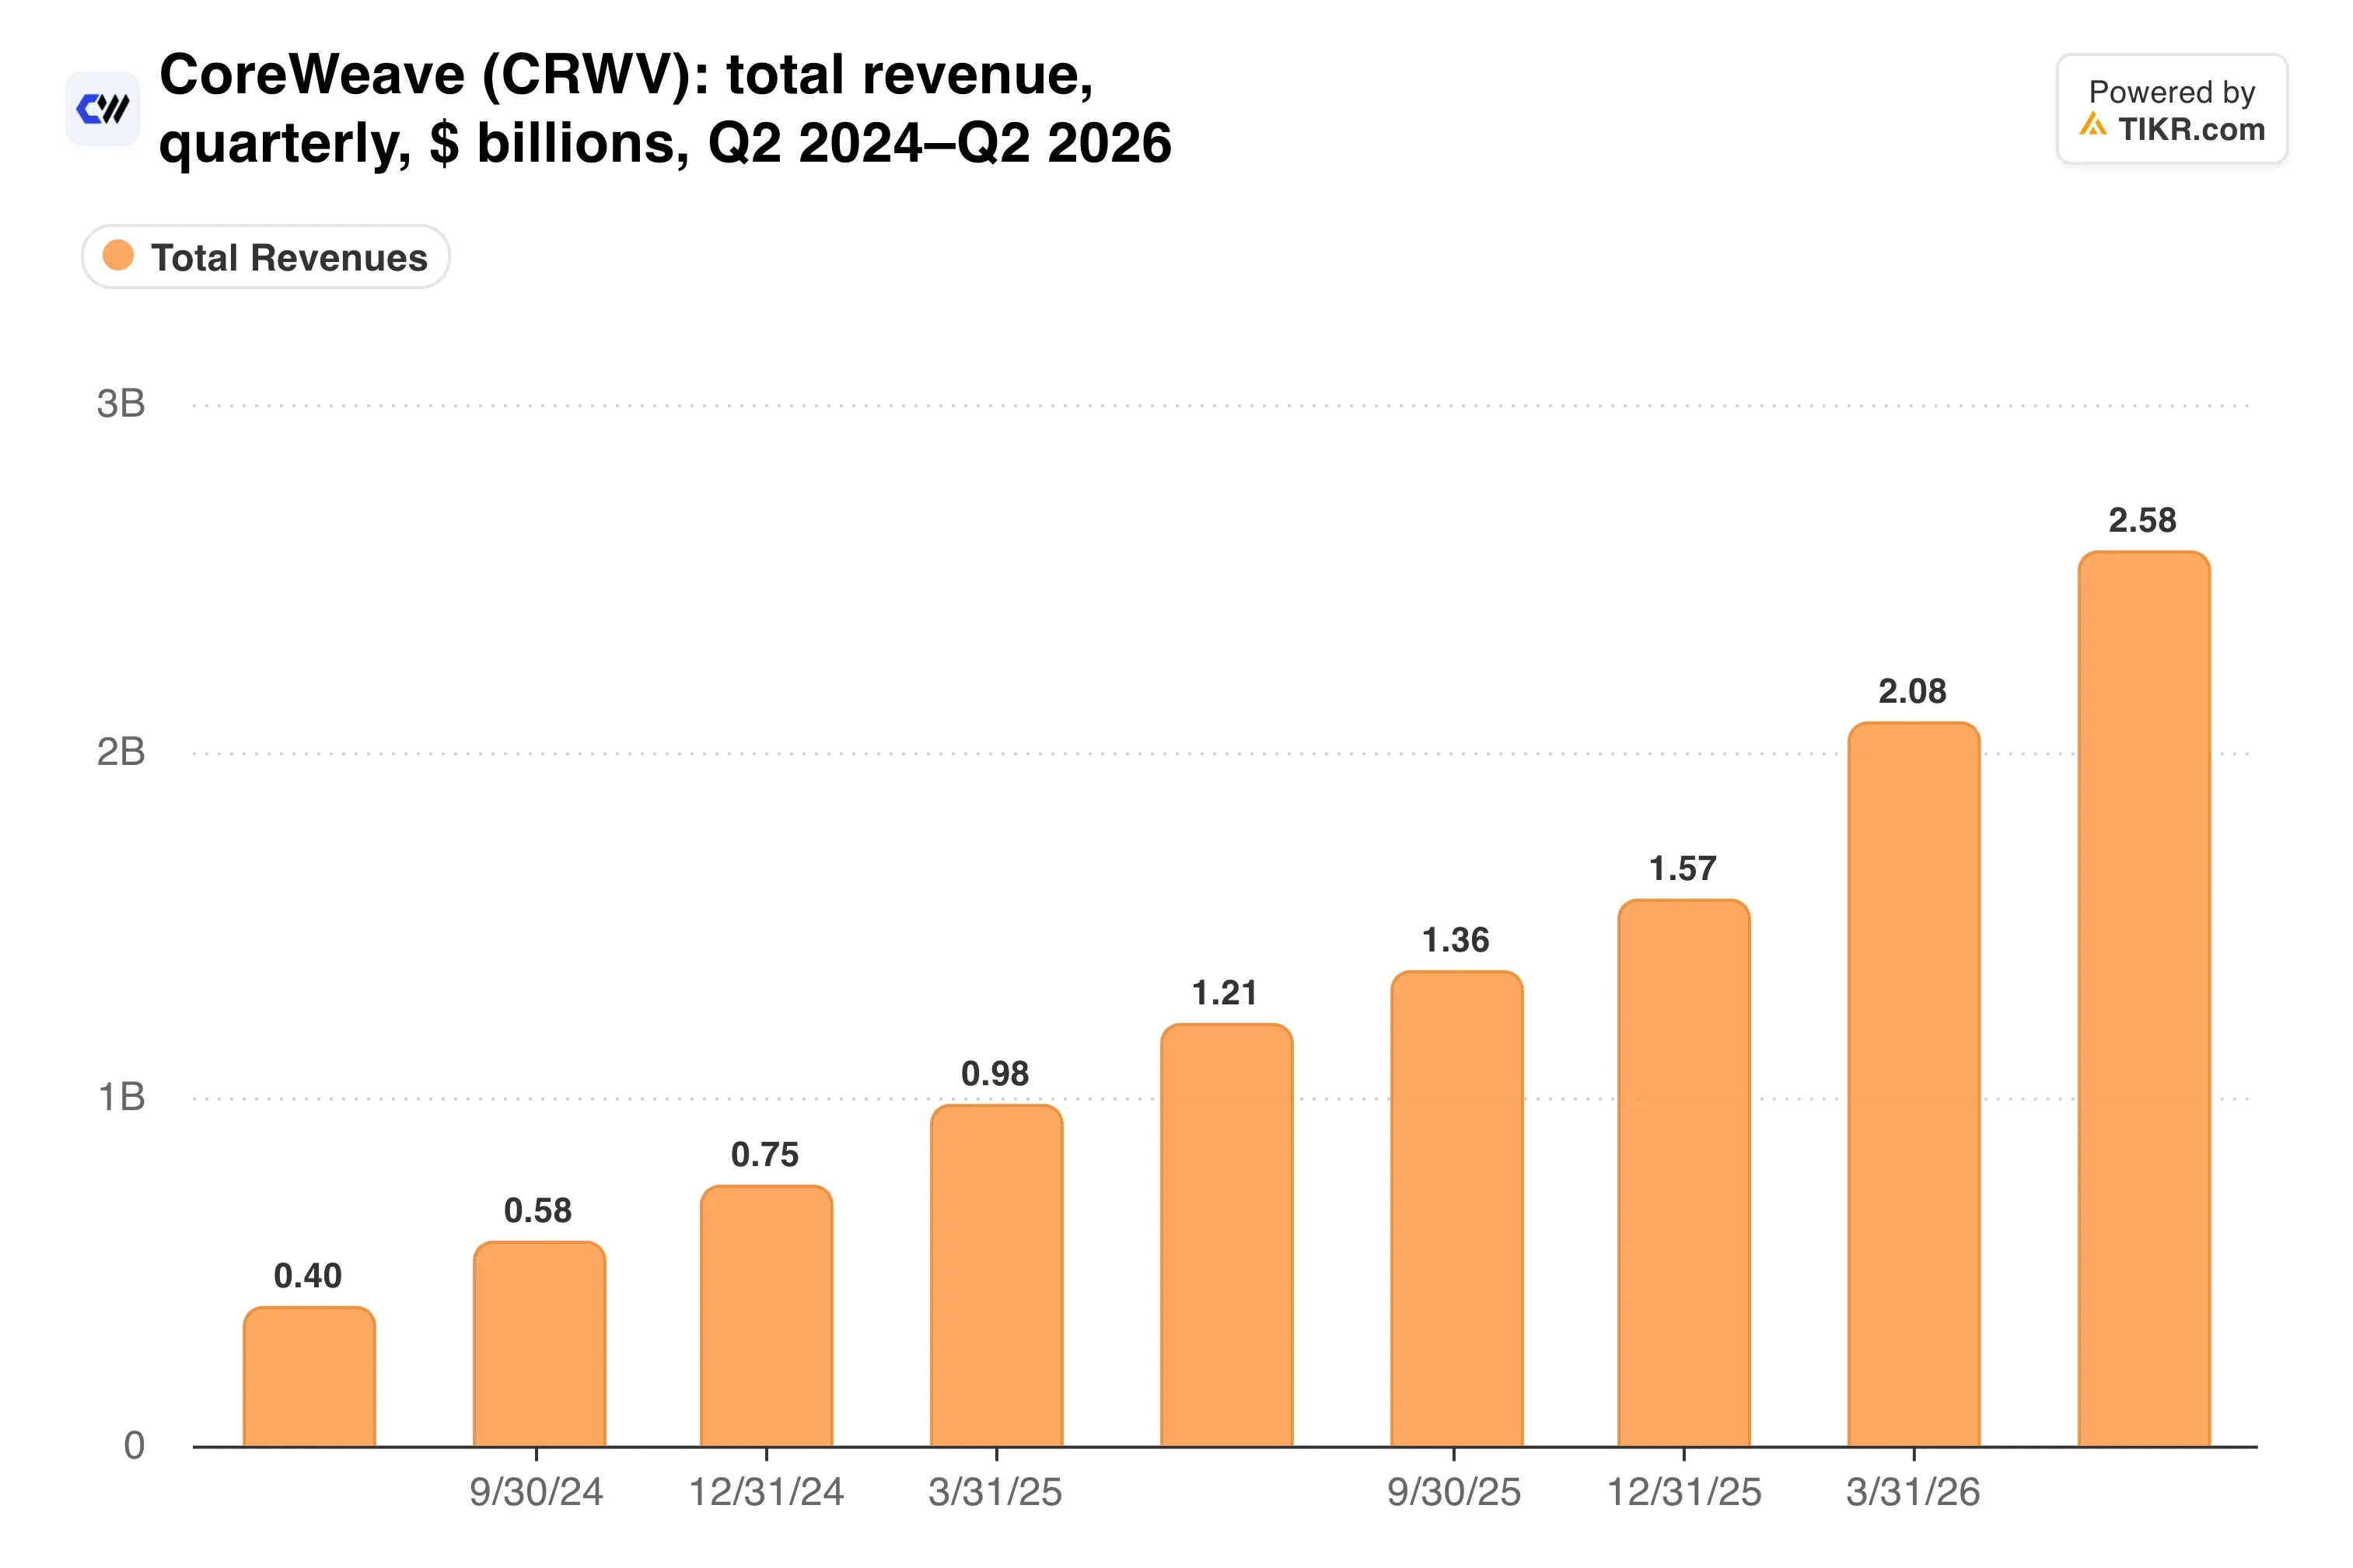
Quarterly revenue more than doubled in a year, which is why the backlog story still commands attention.
Backlog beyond Microsoft
The backlog reached about $104 billion at June 30. That figure excludes more than $25 billion of net new commitments signed in the first weeks of Q3.
Diversification is the real news inside it. Microsoft (MSFT) accounted for about 67% of 2025 revenue. An April deal with Anthropic to support Claude models adds a frontier lab, and Meta Platforms (META) also ranks among the largest customers.
Pricing power showed up too. CoreWeave raised prices about 25% in July with near-term capacity effectively sold out.
About 41% of the $103.7 billion in remaining performance obligations should convert to revenue within 24 months. Delivering that compute takes extraordinary spending, though, with 2026 capex guided to $35 billion to $39 billion.
Capex is where demand turns into cash out the door.

This year’s spending runs near three times expected revenue, so every new contract needs new financing.
TIKR tracks 41 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
Lenders get paid first
The Q3 guide frames the risk neatly. CoreWeave expects $860 million to $940 million of interest expense against adjusted operating income of only $200 million to $260 million.
Total debt reached $35.6 billion at June 30, plus about $16.3 billion of operating lease liabilities. Net debt of about $46 billion now runs 8.2x trailing EBITDA.
Compare that with Nebius (NBIS), which carries roughly $2.2 billion of net debt. Investors pay 6.4x forward EV/Sales for Nebius and just 3.9x for CoreWeave, a discount that reflects the balance sheet.
So where does operating profit stand against the interest bill?

Interest expense has climbed faster than EBIT, which explains the stock’s slide better than any demand data.
My take: The demand is real, and a sub-4x sales multiple on a $104 billion backlog looks cheap on paper. But the equity only works if capital markets stay open at tolerable rates, and bond investors have started demanding more. I would treat this as a high-beta call on credit conditions, and its 3.18 beta says the market already does.
The November 12 Q3 report is the next test. Watch whether interest lands at the low end of guidance, how much capacity came online, and what the 2027 funding plan looks like.
Until then, the backlog is a promise and the debt is a bill.
So what is CoreWeave stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CoreWeave could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


