Key Takeaways
- Dan Loeb’s Third Point, the Windacre Partnership, and YCG all added to their TransDigm Group (TDG) stakes in the quarter ended June 30, and Windacre made it 9.0% of its 13F holdings.
- TransDigm trades at about 26x forward earnings, near its five-year low, against about 36x for GE Aerospace (GE) and 24x for RTX (RTX).
- Analysts expect earnings to keep climbing, but their average price target has fallen from $1,558 to $1,414 over the past year.
- Management has raised its outlook three times this fiscal year, and the funds’ bet looks right going into next week’s report.
Dan Loeb’s Third Point and two other funds all added to TransDigm Group in Q2. That’s according to their latest 13Fs, which cover the quarter ended June 30 and were filed in mid-August.
The stock has slipped since then, and TransDigm reports next week.
Windacre made it a top-five holding
Third Point more than tripled its stake in the quarter, to 79,000 shares worth $105 million at June 30. That’s 2.3% of its 13F holdings and its 18th-largest position, at a firm that manages $29 billion in all.
The bigger bet came from The Windacre Partnership, which manages $11 billion and lists just 11 stocks on its 13F. It raised its stake 34%, to 684,100 shares worth $911 million. That’s 9.0% of its 13F stocks and its fourth-largest position.
YCG, a $1.5 billion firm, raised its stake 54%, to 46,242 shares worth $62 million, 5.4% of its 13F holdings and its fifth-largest.
A 13F only shows what a fund held on the last day of the quarter, so we don’t know what any of them paid or whether they’ve added since.
Anyone buying today pays 10% less than the June 30 price the filings used to value their shares.
TIKR tracks 23 analysts on TransDigm Group. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on TransDigm Group, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See TransDigm Group’s Analyst Ratings
The business keeps beating its own forecasts
In August, TransDigm raised its fiscal 2026 guidance for Q3 in a row. Sales rose 23% to $2.74 billion in the quarter ended June 27, and commercial aftermarket revenue grew 17%.
“Bookings have exceeded expectations, and we see the current momentum continuing,” CEO Mike Lisman said in the Q3 release, as the company lifted its adjusted EPS guide to $41.04 at the midpoint.
Analysts expect that growth to continue. They see normalized EPS climbing from $37.33 in fiscal 2025 to $48.66 in fiscal 2027 (TransDigm’s years end in September):
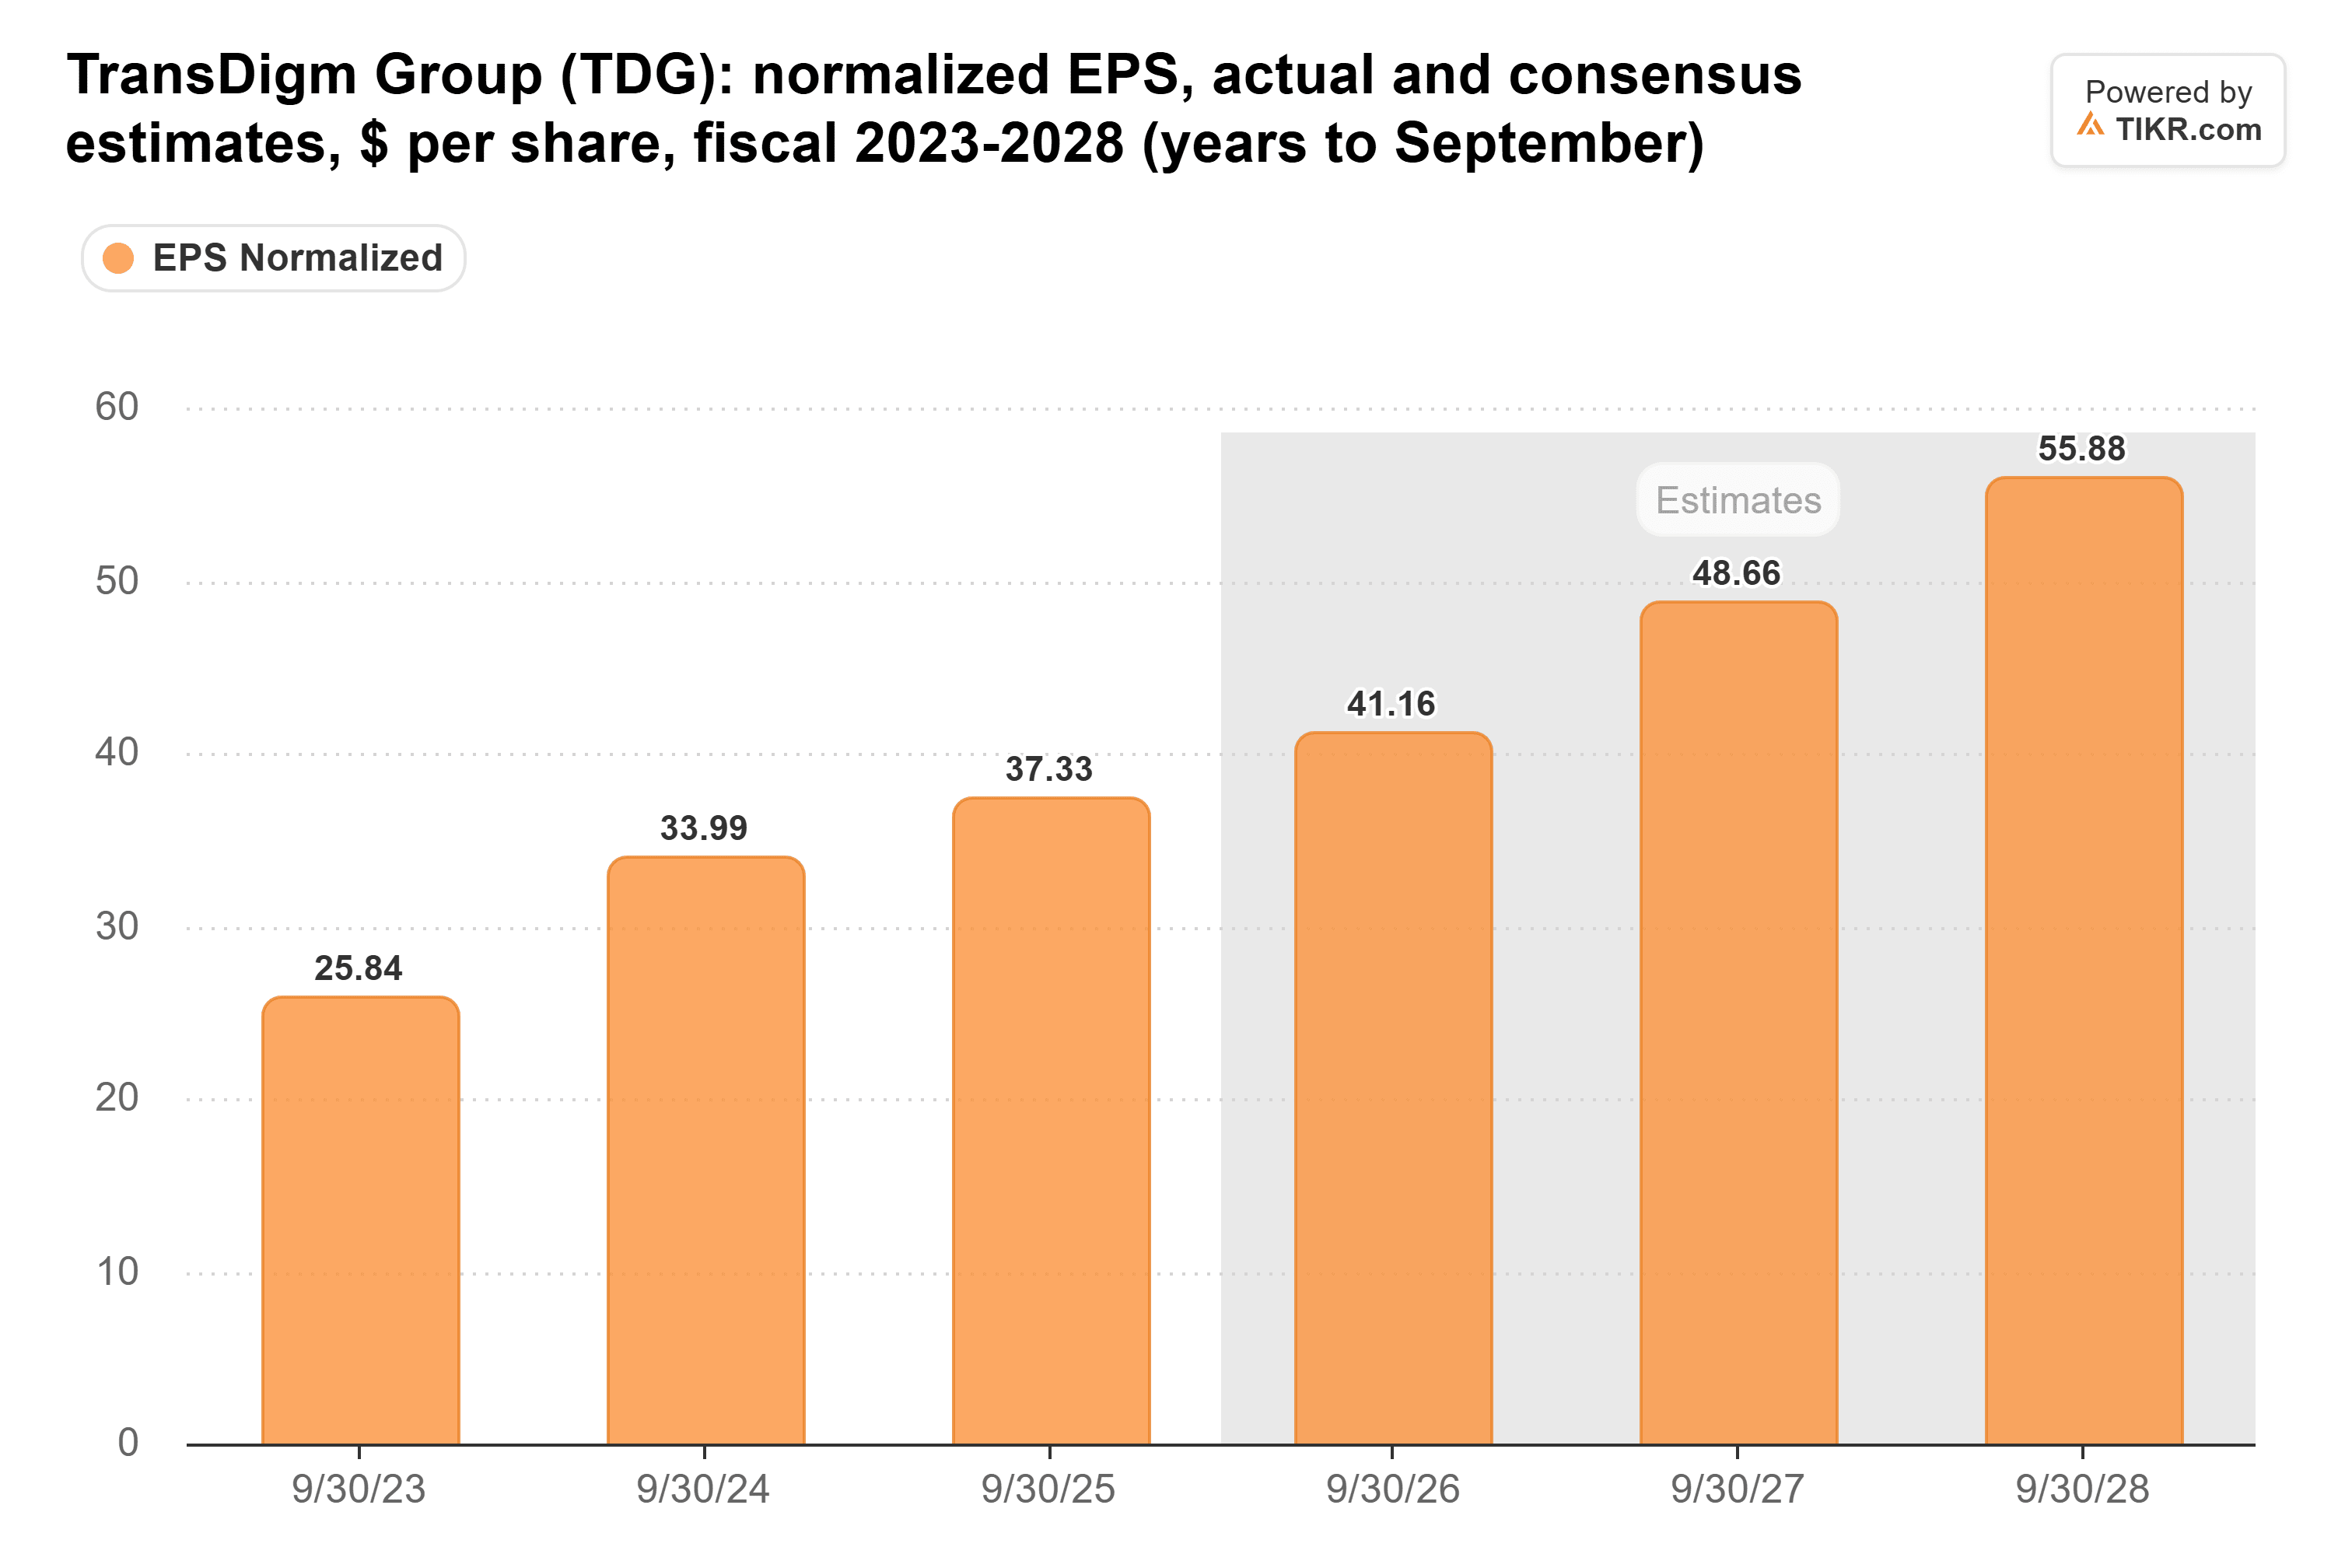
Their $41.16 for fiscal 2026 sits right on management’s midpoint. So when TransDigm reports next week, investors will be looking past the year that just ended to what it sees for fiscal 2027.
Investors are paying less for it
The stock hasn’t kept up pace with the earnings. TransDigm trades at 26x forward earnings, near the bottom of its range over the last five years:
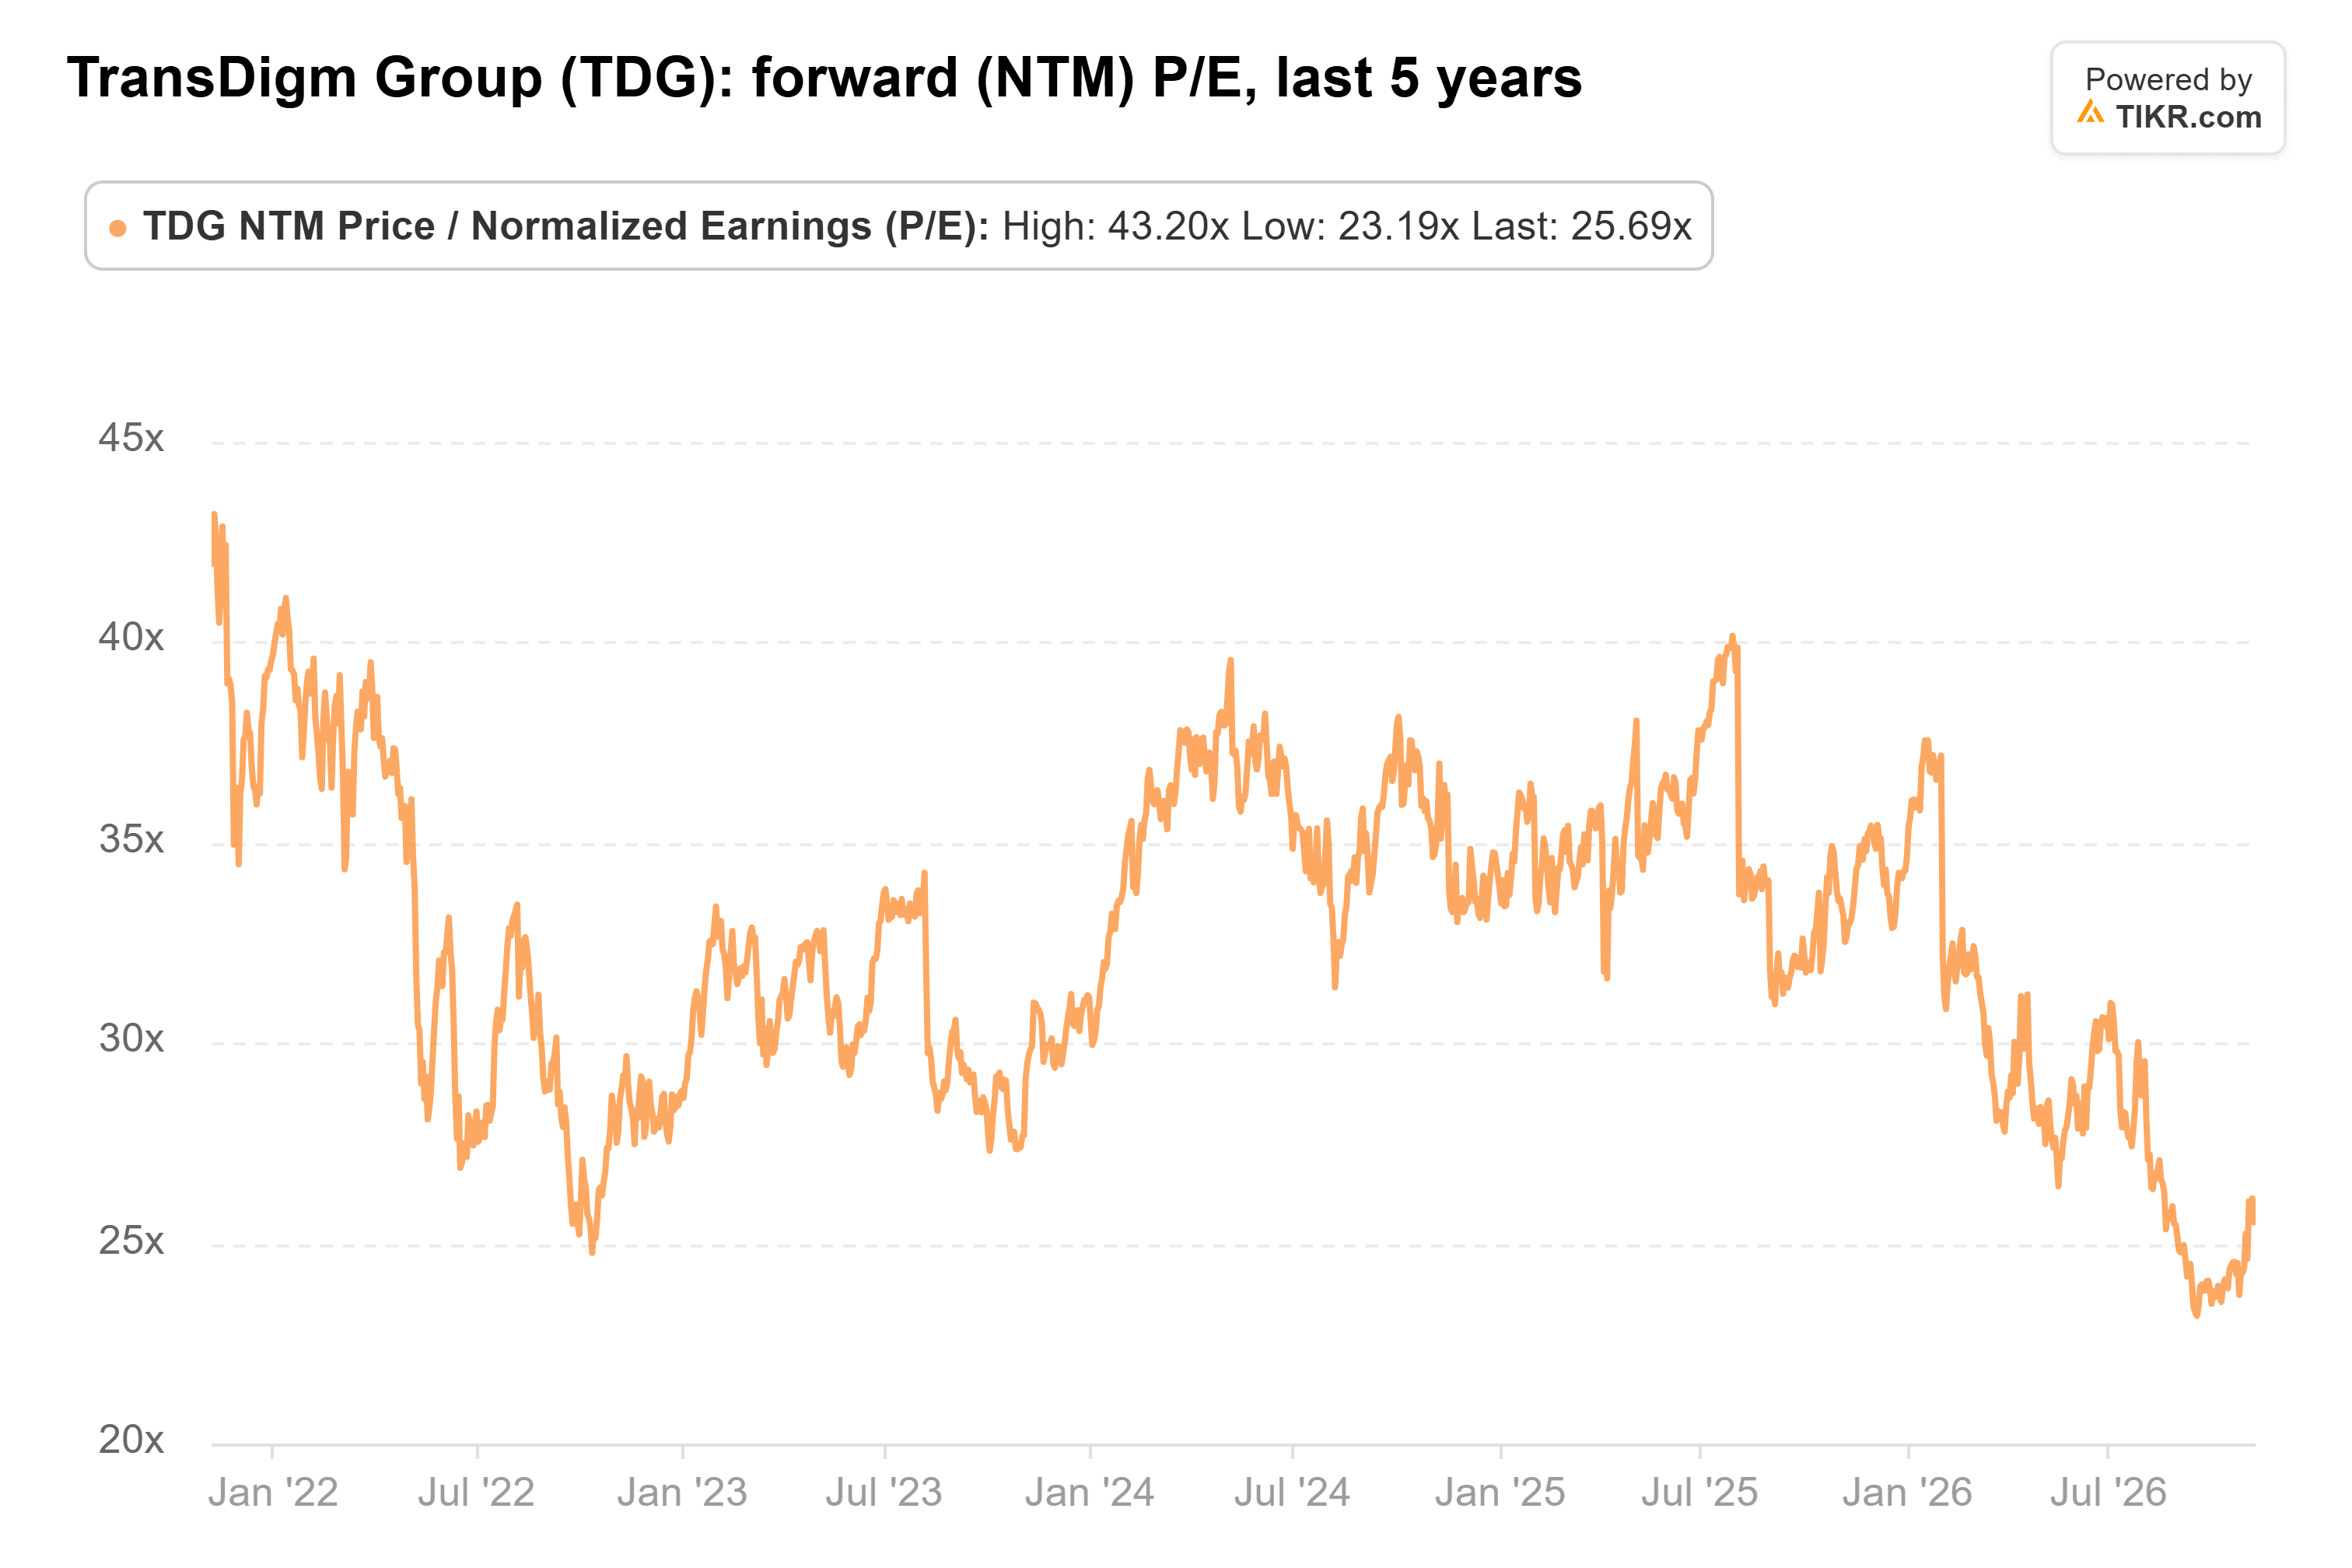
Its five-year average is 33x, and its five-year low of 23x came only on Sept. 17.
TransDigm has company. GE Aerospace and RTX are 15% and 17% below their 52-week highs, close to TransDigm’s 15%.
GE Aerospace’s forward P/E fell from 49x at June 30 to 37x at Sept. 30. It slipped again after the company raised its 2026 guidance across the board in October.
GE now expects commercial services growth to slow to the low double digits in 2027, from the low 20s this year. I suspect investors are pricing that kind of aftermarket slowdown into TransDigm too.
Even so, TransDigm’s multiple sits much closer to RTX’s 24x than to GE Aerospace’s 36x.
Does the $1,414 target add up?
The 23 analysts covering TransDigm have an average price target of $1,414, 18% above the last close.
They’ve been trimming it all year, though. A year ago it was $1,558, and it peaked at $1,622 in January before falling to its lowest point of the past year:
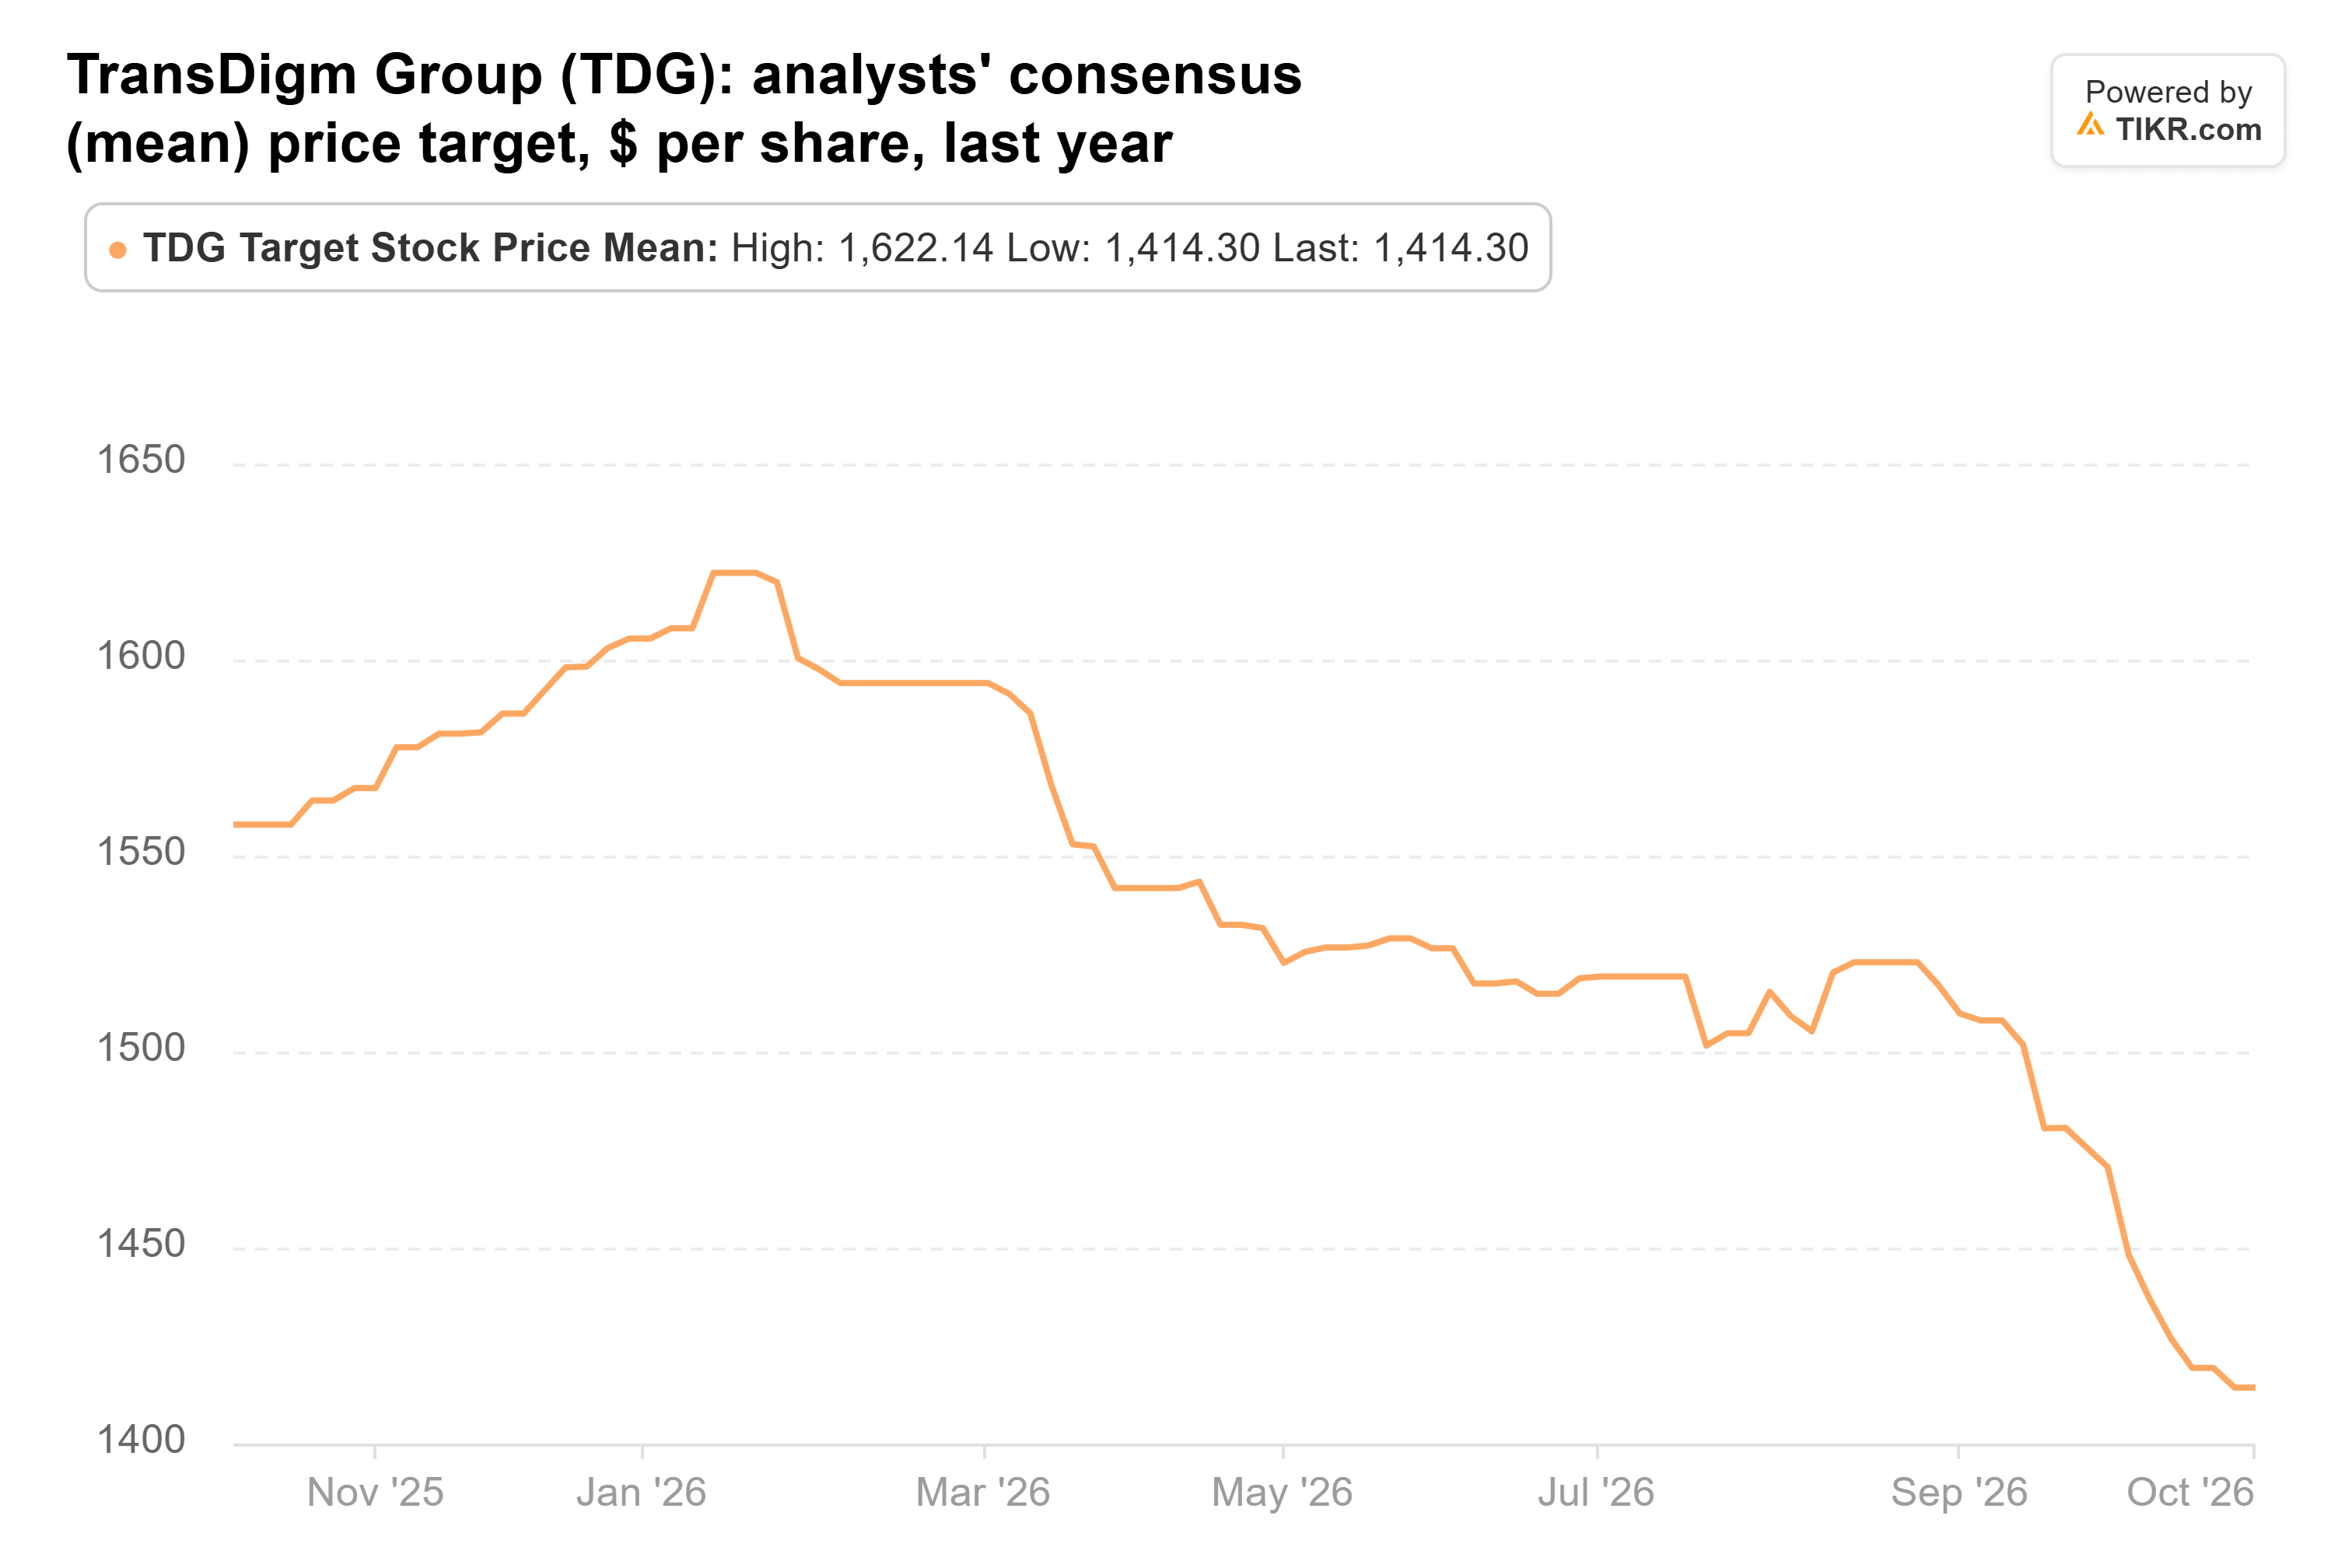
Individual targets run from $1,100 to $1,745. Even after the cuts, $1,414 is about 29x what analysts expect TransDigm to earn in fiscal 2027.
That’s still below the stock’s five-year average multiple. So TransDigm can reach that target if earnings come in as expected, even at a valuation below its usual one.
I’d follow the funds in
The main risk is a slowdown in the aftermarket. If next week’s report shows TransDigm’s aftermarket growth slowing the way GE Aerospace expects its own to, analysts could keep cutting their targets.
But these funds bought into a business that keeps raising its forecast, and I think the market is underpricing it. I’d rather own TransDigm going into the report than wait for it.
Of course, TransDigm could still give a softer view of fiscal 2027 next week. And the funds’ 13Fs for the quarter ended Sept. 30, due by Nov. 16, will show whether they held on as the stock fell.
So what is TransDigm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TransDigm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!