


Key Takeaways
- B. Riley cut its Snap (SNAP) price target to $8 from $10 on Thursday and kept its Buy rating, 60% above the stock’s price.
- Snap’s Q3 adjusted EBITDA beat its own guidance, but ad revenue grew just 4% as brand advertising fell.
- B. Riley’s $8 works out to 10.3x the earnings analysts expect over the next year. That’s below Snap’s 11x average over the past year.
- Those adjusted earnings leave out roughly $1 billion a year of stock pay, so reaching $8 within a year depends on Snap holding its share count flat in 2027.
Snap stock is down 38% over the past year, and it sank again after Wednesday’s Q3 report. On Thursday, B. Riley analyst Naved Khan cut his price target to $8 from $10 but kept his Buy rating. From $4.96, that’s 62% upside.
Plenty has gone wrong
Snap’s North American daily users fell from 99 million in Q2 2025 to 92 million in Q2 2026. And while Snap settled a Los Angeles teen-addiction trial on Nov. 2, more than 3,000 similar suits are moving ahead.
Ie Q3 revenue rose 14% to $1.72 billion in line with Snap’s guidance. But advertising revenue grew just 4% as brand advertising declined.
CEO Evan Spiegel didn’t sugarcoat it on the call: “Certainly, 4% ad growth is below our ambitions.”
Here’s B. Riley’s path to $8
B. Riley credits better ad technology for Snap’s strong direct-response growth. It’s counting on higher-margin formats (Sponsored Snaps, Spotlight and Promoted Places) and subscriptions to keep that growth going.
Here’s what the Q3 showed on each:
- Direct response is now about 77% of revenue, per Chief Commercial Officer Ronan Harris.
- Sponsored Snaps revenue rose 56% from Q2, and Promoted Places revenue more than doubled.
- Other revenue, led by Snapchat+, grew 84%, and paid subscribers passed 30 million.
Plus: total costs grew just 1%, so adjusted EBITDA more than doubled to $383 million, above the top of Snap’s guidance.
B. Riley put the Q4 outlook slightly ahead of Wall Street’s at the midpoint.
TIKR tracks 42 analysts on Snap. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snap, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snap’s Analyst Ratings
Does $8 add up?
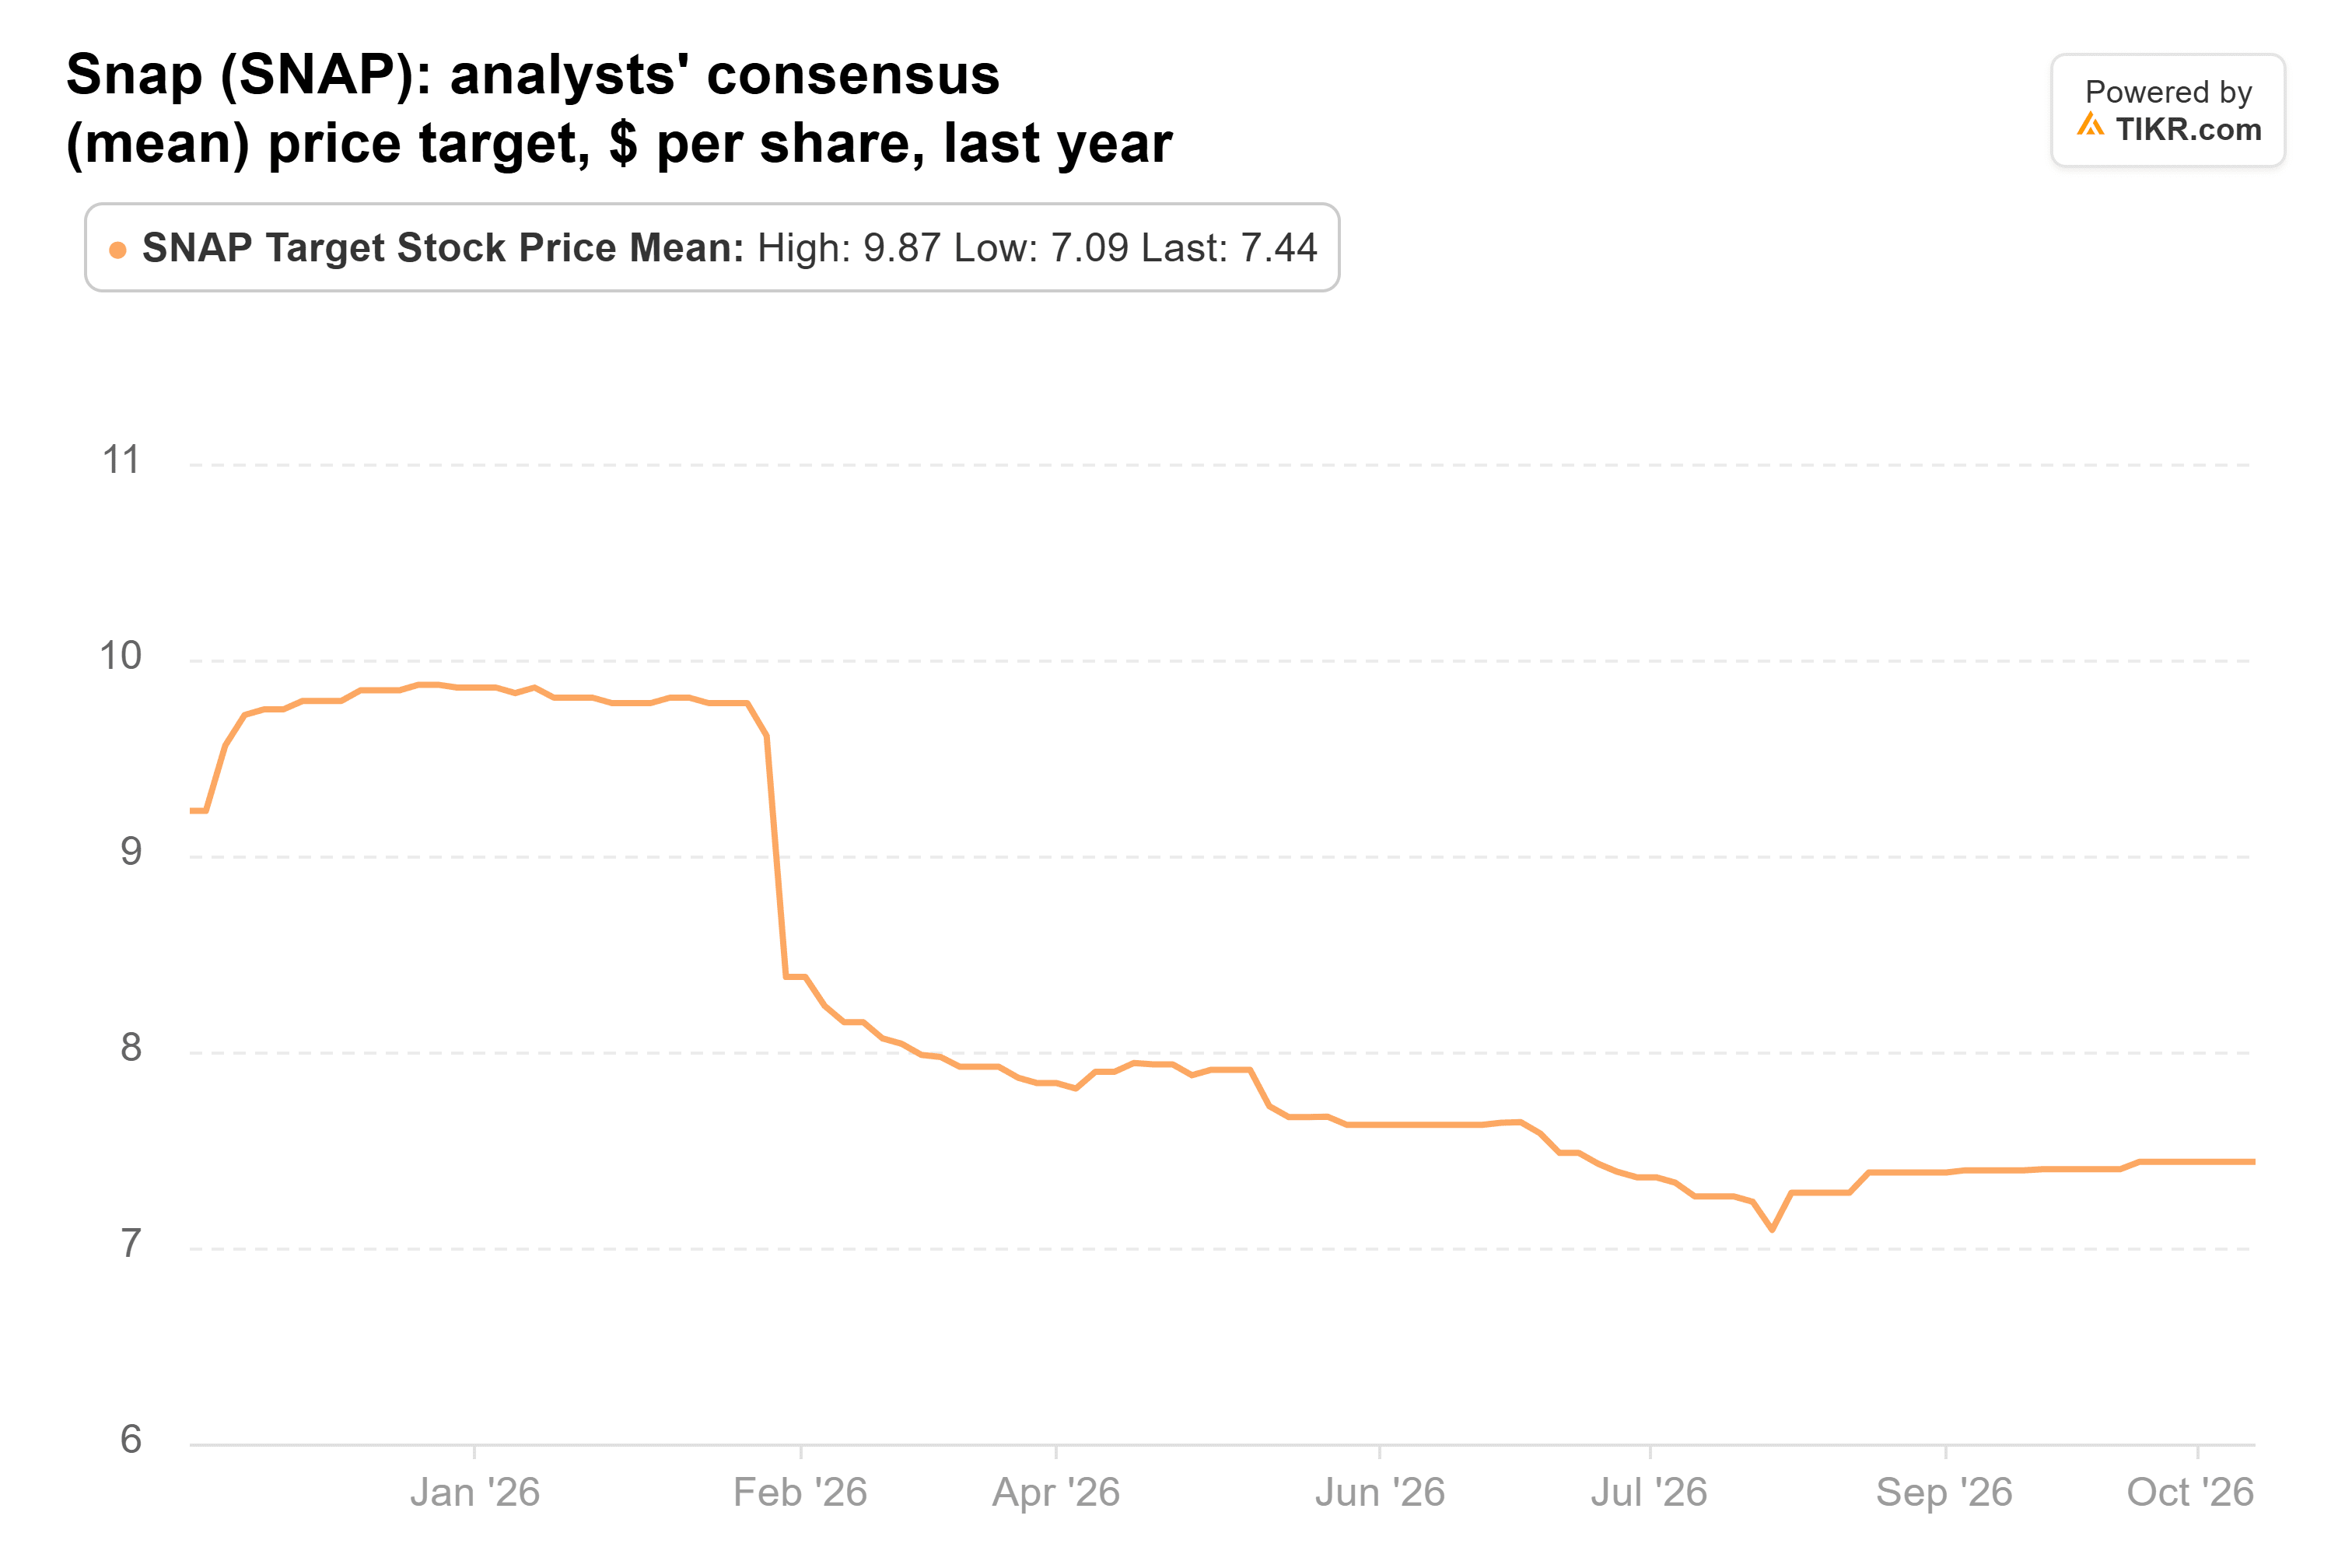
The average target of the 42 analysts who cover Snap has slid from $9 a year ago to $7.
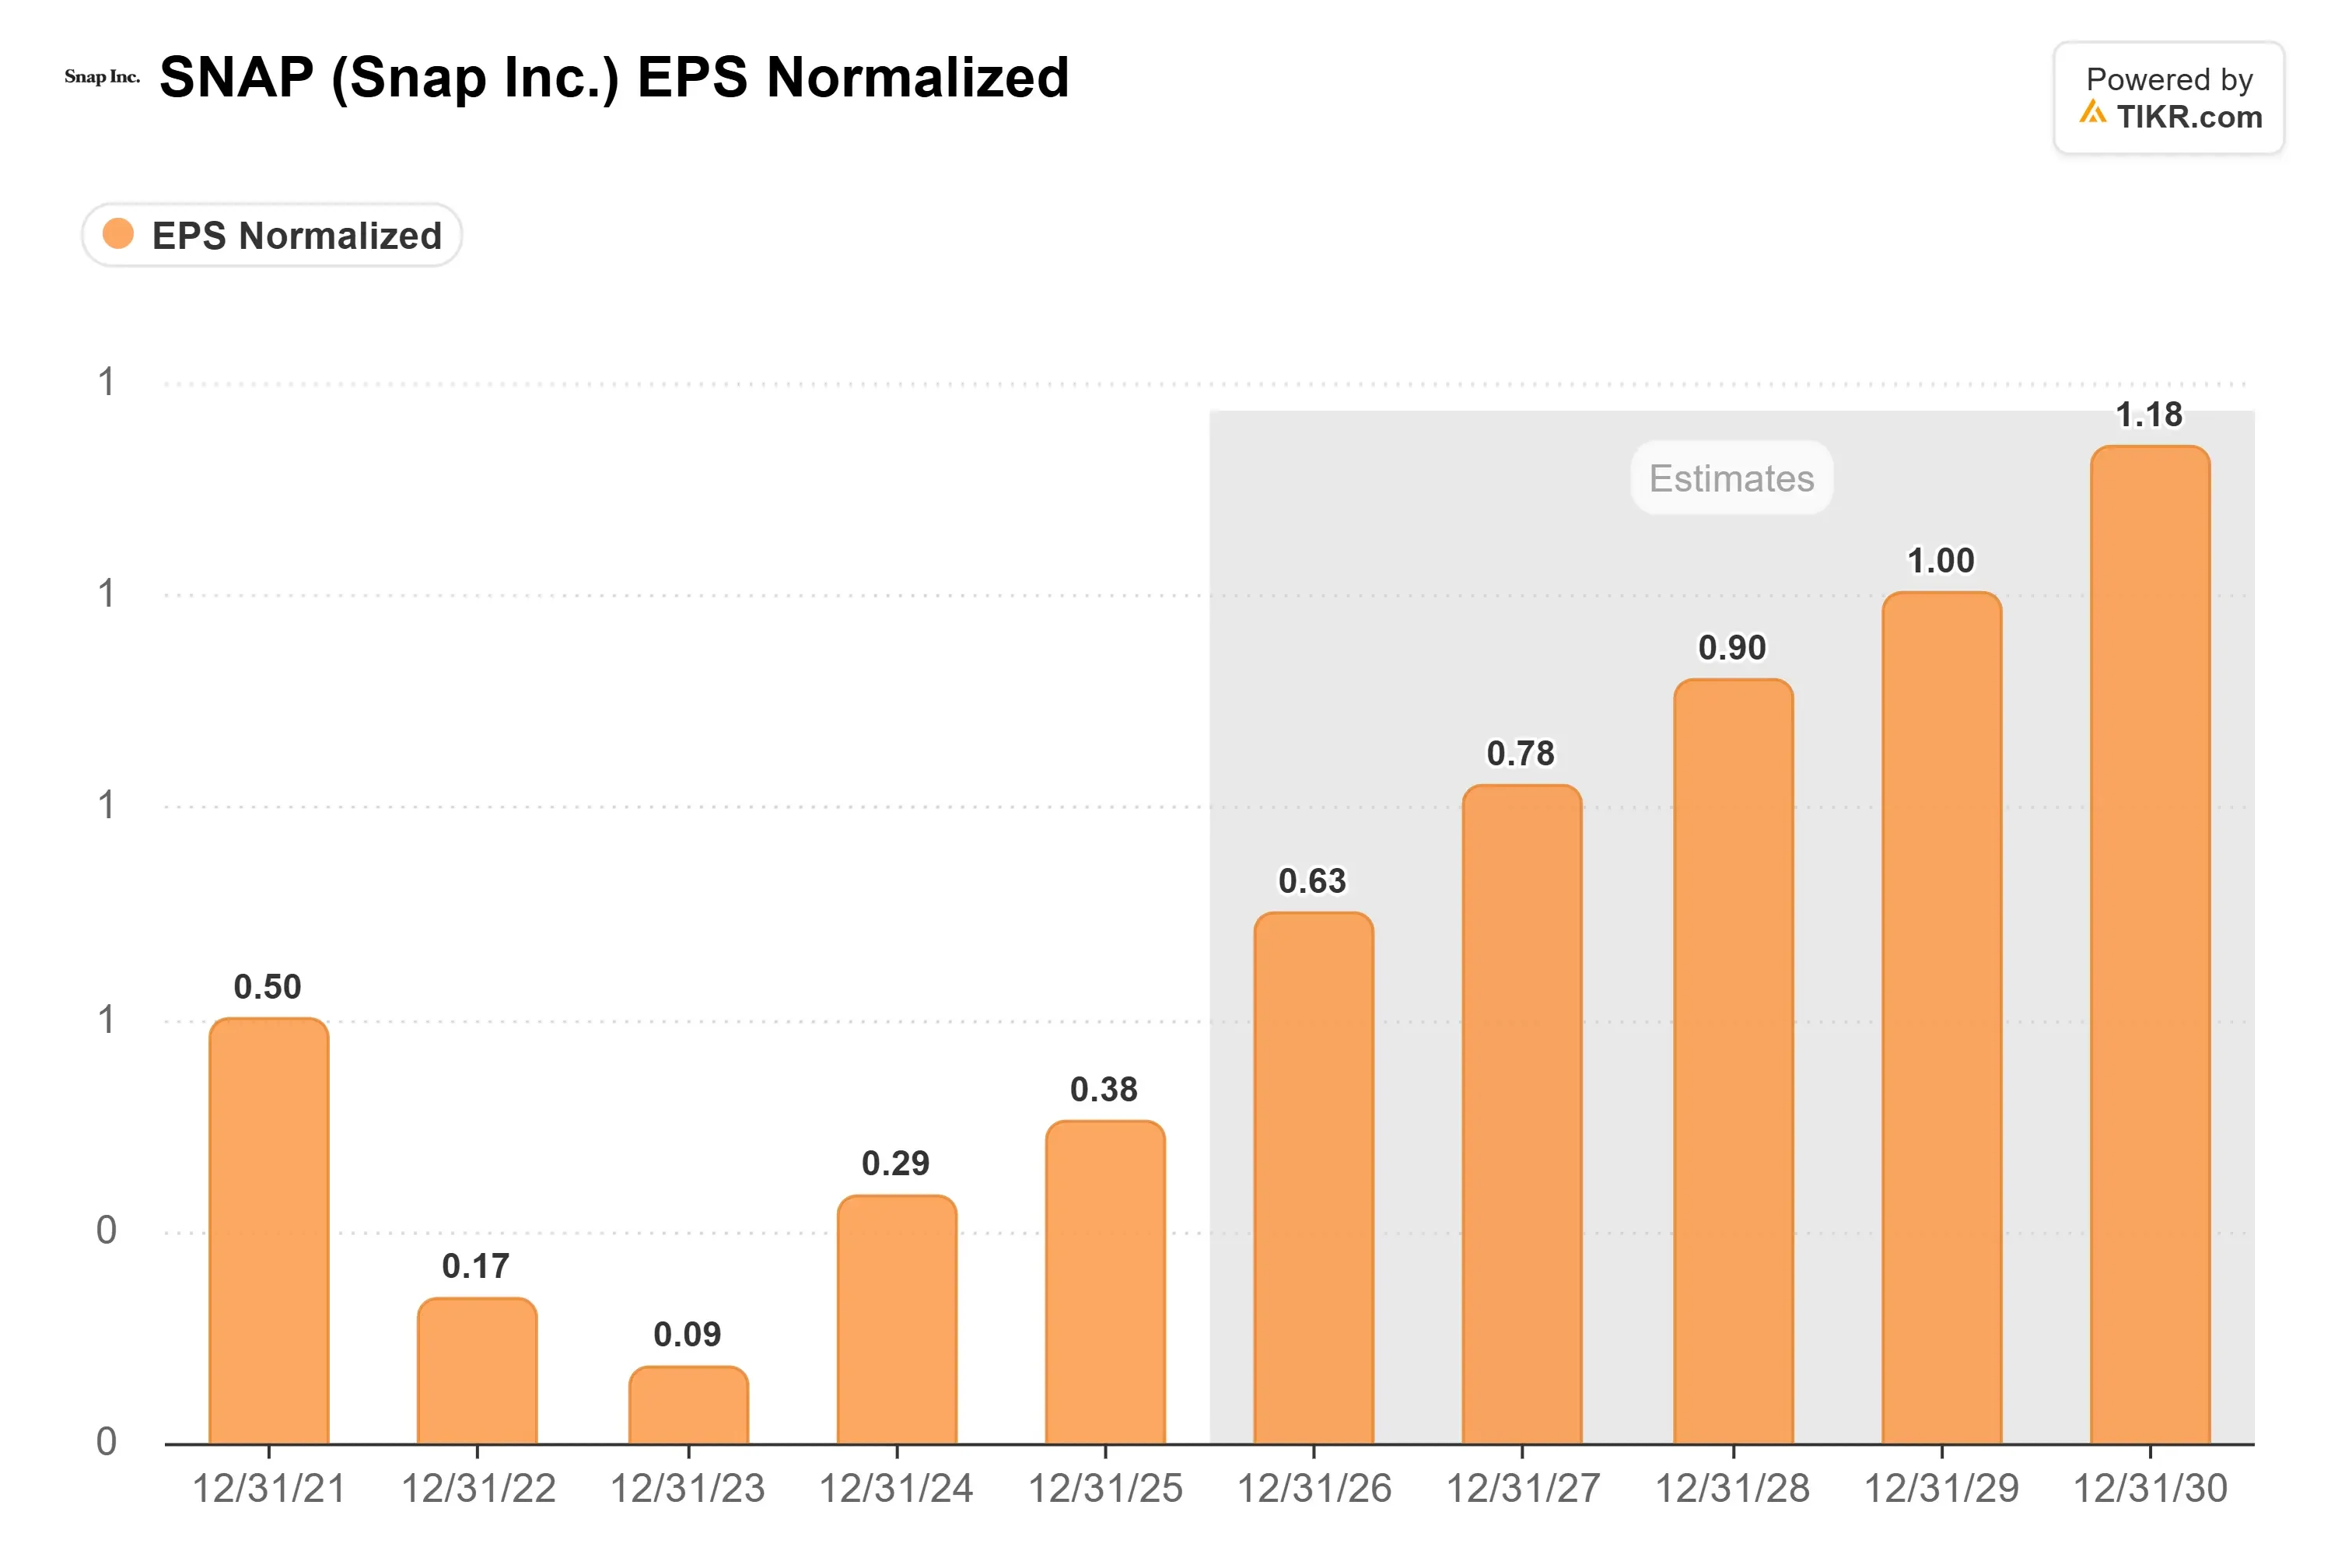
Earnings estimates point the other way. Analysts expect normalized EPS to double from $0.38 in 2025 to $0.78 in 2027.
With EBITDA beating guidance, I don’t see much in this report to push them down.
Snap traded at 6.4x forward earnings at Friday’s close, and even lower after this week’s drop. B. Riley’s $8 works out to 10.3x, below the stock’s 11x average over the past year.
The catch is what normalized earnings leave out. Analysts expect just $0.15 a share of GAAP earnings in 2027. Much of the gap is the stock Snap pays its staff, roughly $1.05 billion this year by management’s guidance.
Free cash flow of $777 million over the past 12 months doesn’t cover the expense, and shares plus stock awards rose 4% in a year to 1.93 billion.
CFO Doug Hott said Snap is aiming for “a stable fully diluted share count in 2027.”
B. Riley has the multiple right, but its $8 assumes the share count stops growing. Until Snap shows it can hold that count flat out of its own cash, I wouldn’t count on $8 within a year.
The Q4 report, due in early February, should bring that plan’s details and 2027 stock-pay guidance. A flat share count funded from free cash flow would make $8 a lot easier to reach.
So what is Snap stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snap could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!






