Key Takeaways
- CoreWeave’s third-quarter revenue rose to $3.66 billion from $1.37 billion, and its CEO said it is delivering capacity “ahead of plan.”
- Galaxy Digital has leased all 800 MW of approved power at its Helios campus to CoreWeave on 15-year terms that it expects to bring in more than $1 billion a year on average.
- CoreWeave expects about $9 billion of customer prepayments and deposits over the next three months. A month ago its bonds were priced to yield close to 15%, and that cash goes straight at the funding worry behind those prices.
- Only 133 MW of Helios has been delivered, so most of Galaxy’s rent still depends on building Phase II, whose first data halls are due in the second quarter of 2027.
CoreWeave (CRWV) had a lot to prove when it reported on Tuesday night. Third-quarter revenue rose to $3.66 billion from $1.37 billion, and its backlog reached about $132.5 billion.
Outside CoreWeave itself, few companies have more riding on that than Galaxy Digital (GLXY). All 800 MW of approved power at Galaxy’s Helios campus in West Texas is leased to CoreWeave on 15-year terms. Galaxy expects those leases to bring in more than $1 billion a year on average, and its stock rose 5% today.
On CoreWeave’s third-quarter call, CEO Michael Intrator summed up the quarter like this:
“We are delivering capacity ahead of plan and the value of that capacity is increasing with our original fleet recontracting at a premium.”
For a landlord with one tenant, that’s about as good as it gets.
TIKR tracks 42 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
The tenant’s funding worry just eased
A month ago, the worry was about CoreWeave’s debt. On Oct. 14, CoreWeave’s 9.625% notes due 2032 fell below 80 cents on the dollar, a yield near 15%. A tenant whose debt trades like that is a real risk to a 15-year lease.
Intrator took that worry on directly. He said CoreWeave collected prepayments on 70% of this year’s deals, and some customers paid up to the full contract value up front. He also said prepayments are a better deal than unsecured debt right now. Then he gave the number:
“In the next 3 months alone, we will collect approximately $9 billion in prepayments and deposits from signed customer contracts.”
That’s real money next to what CoreWeave spends. Its capital spending reached $9.44 billion in the third quarter, about four times the $2.39 billion of a year earlier.
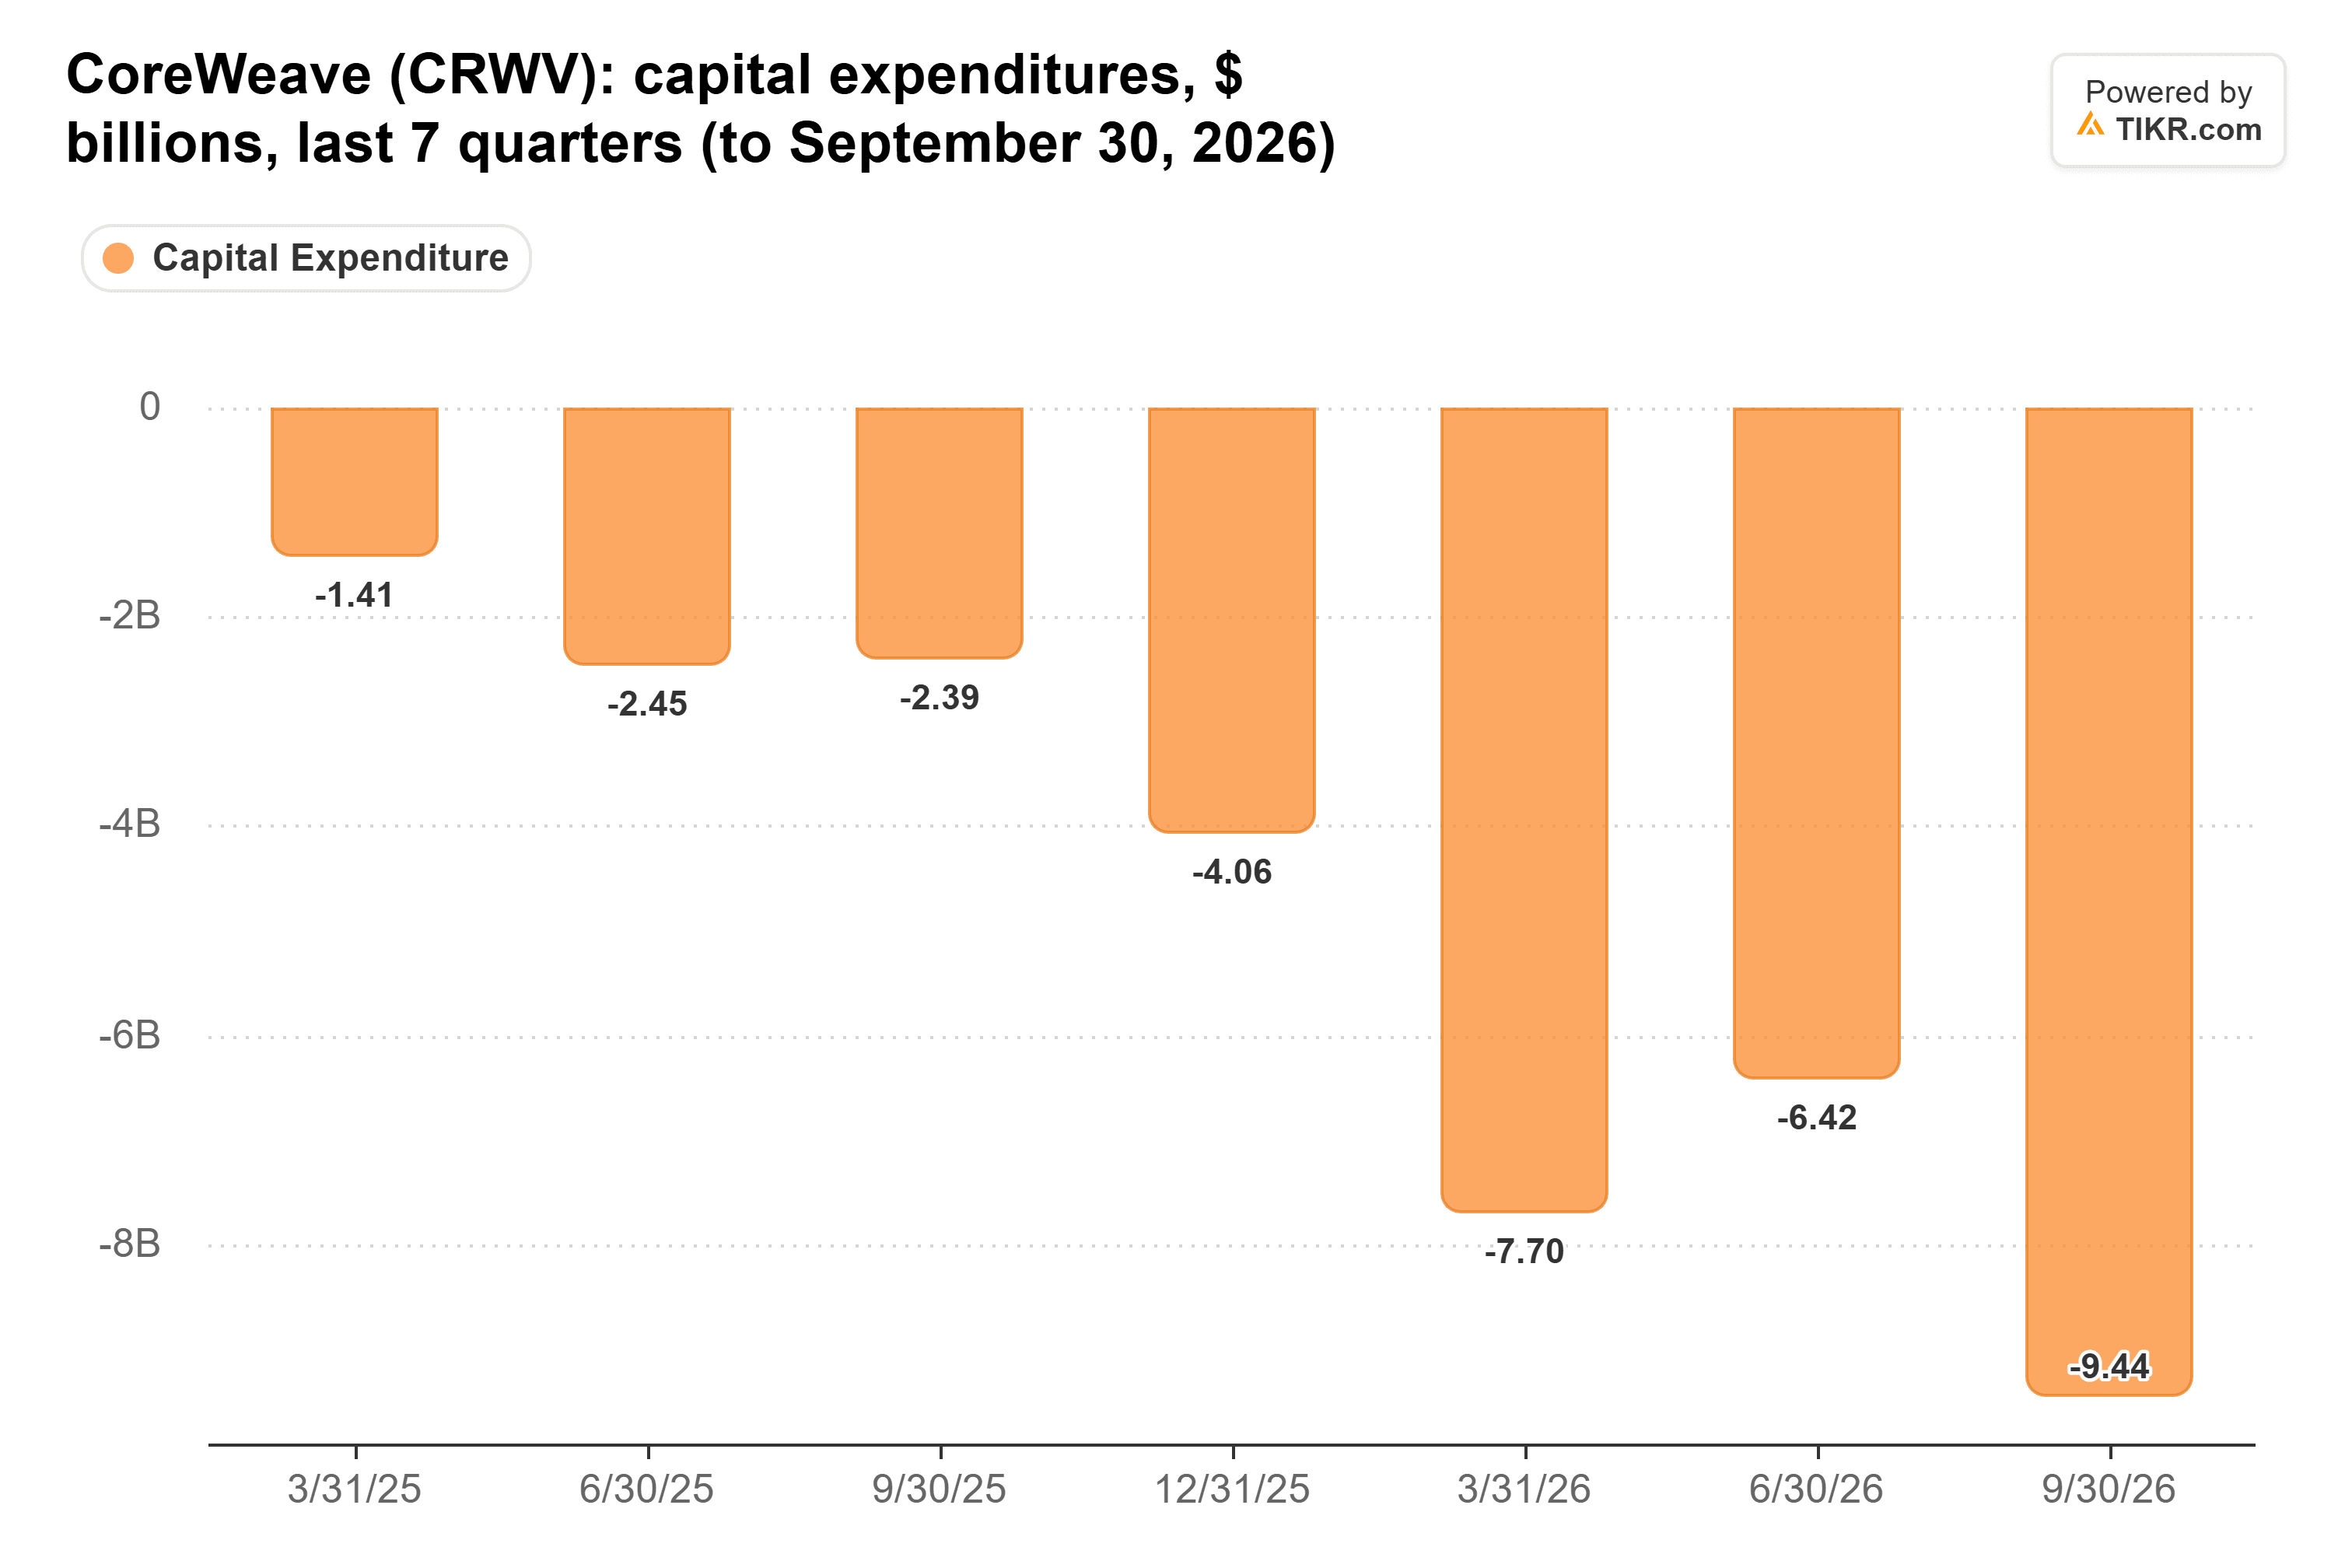
So the prepayments alone cover roughly one quarter of that spending. Intrator expects prepayments, contract cash flow and vendor financing to cover most of CoreWeave’s capital needs through 2027, with only a limited amount raised at the parent company. The debt is still heavy, though. Interest expense of $846 million was more than twice the quarter’s $379 million of adjusted operating income.
Helios is already paying
Galaxy’s earnings swing with bitcoin, and Helios is the steady part. Phase I’s 133 MW was fully delivered to CoreWeave by the end of the second quarter, so the third quarter was the first full quarter of rent. Galaxy’s data center segment earned $79 million of adjusted gross profit, up from $20 million in the second quarter. That puts Phase I alone on pace for more than $300 million a year.
CoreWeave also says it has buyers waiting for the capacity. “We are largely sold out through 2027,” Intrator said on the call. Over 15 years, Galaxy’s leases add up to more than $15 billion. That’s a bigger bet on one tenant than Applied Digital’s, which has about $11 billion riding on CoreWeave.
Analysts expect Galaxy’s normalized EPS to rise from $0.10 in 2027 to $1.05 in 2028, the first full year after Phase II’s data halls start coming online:
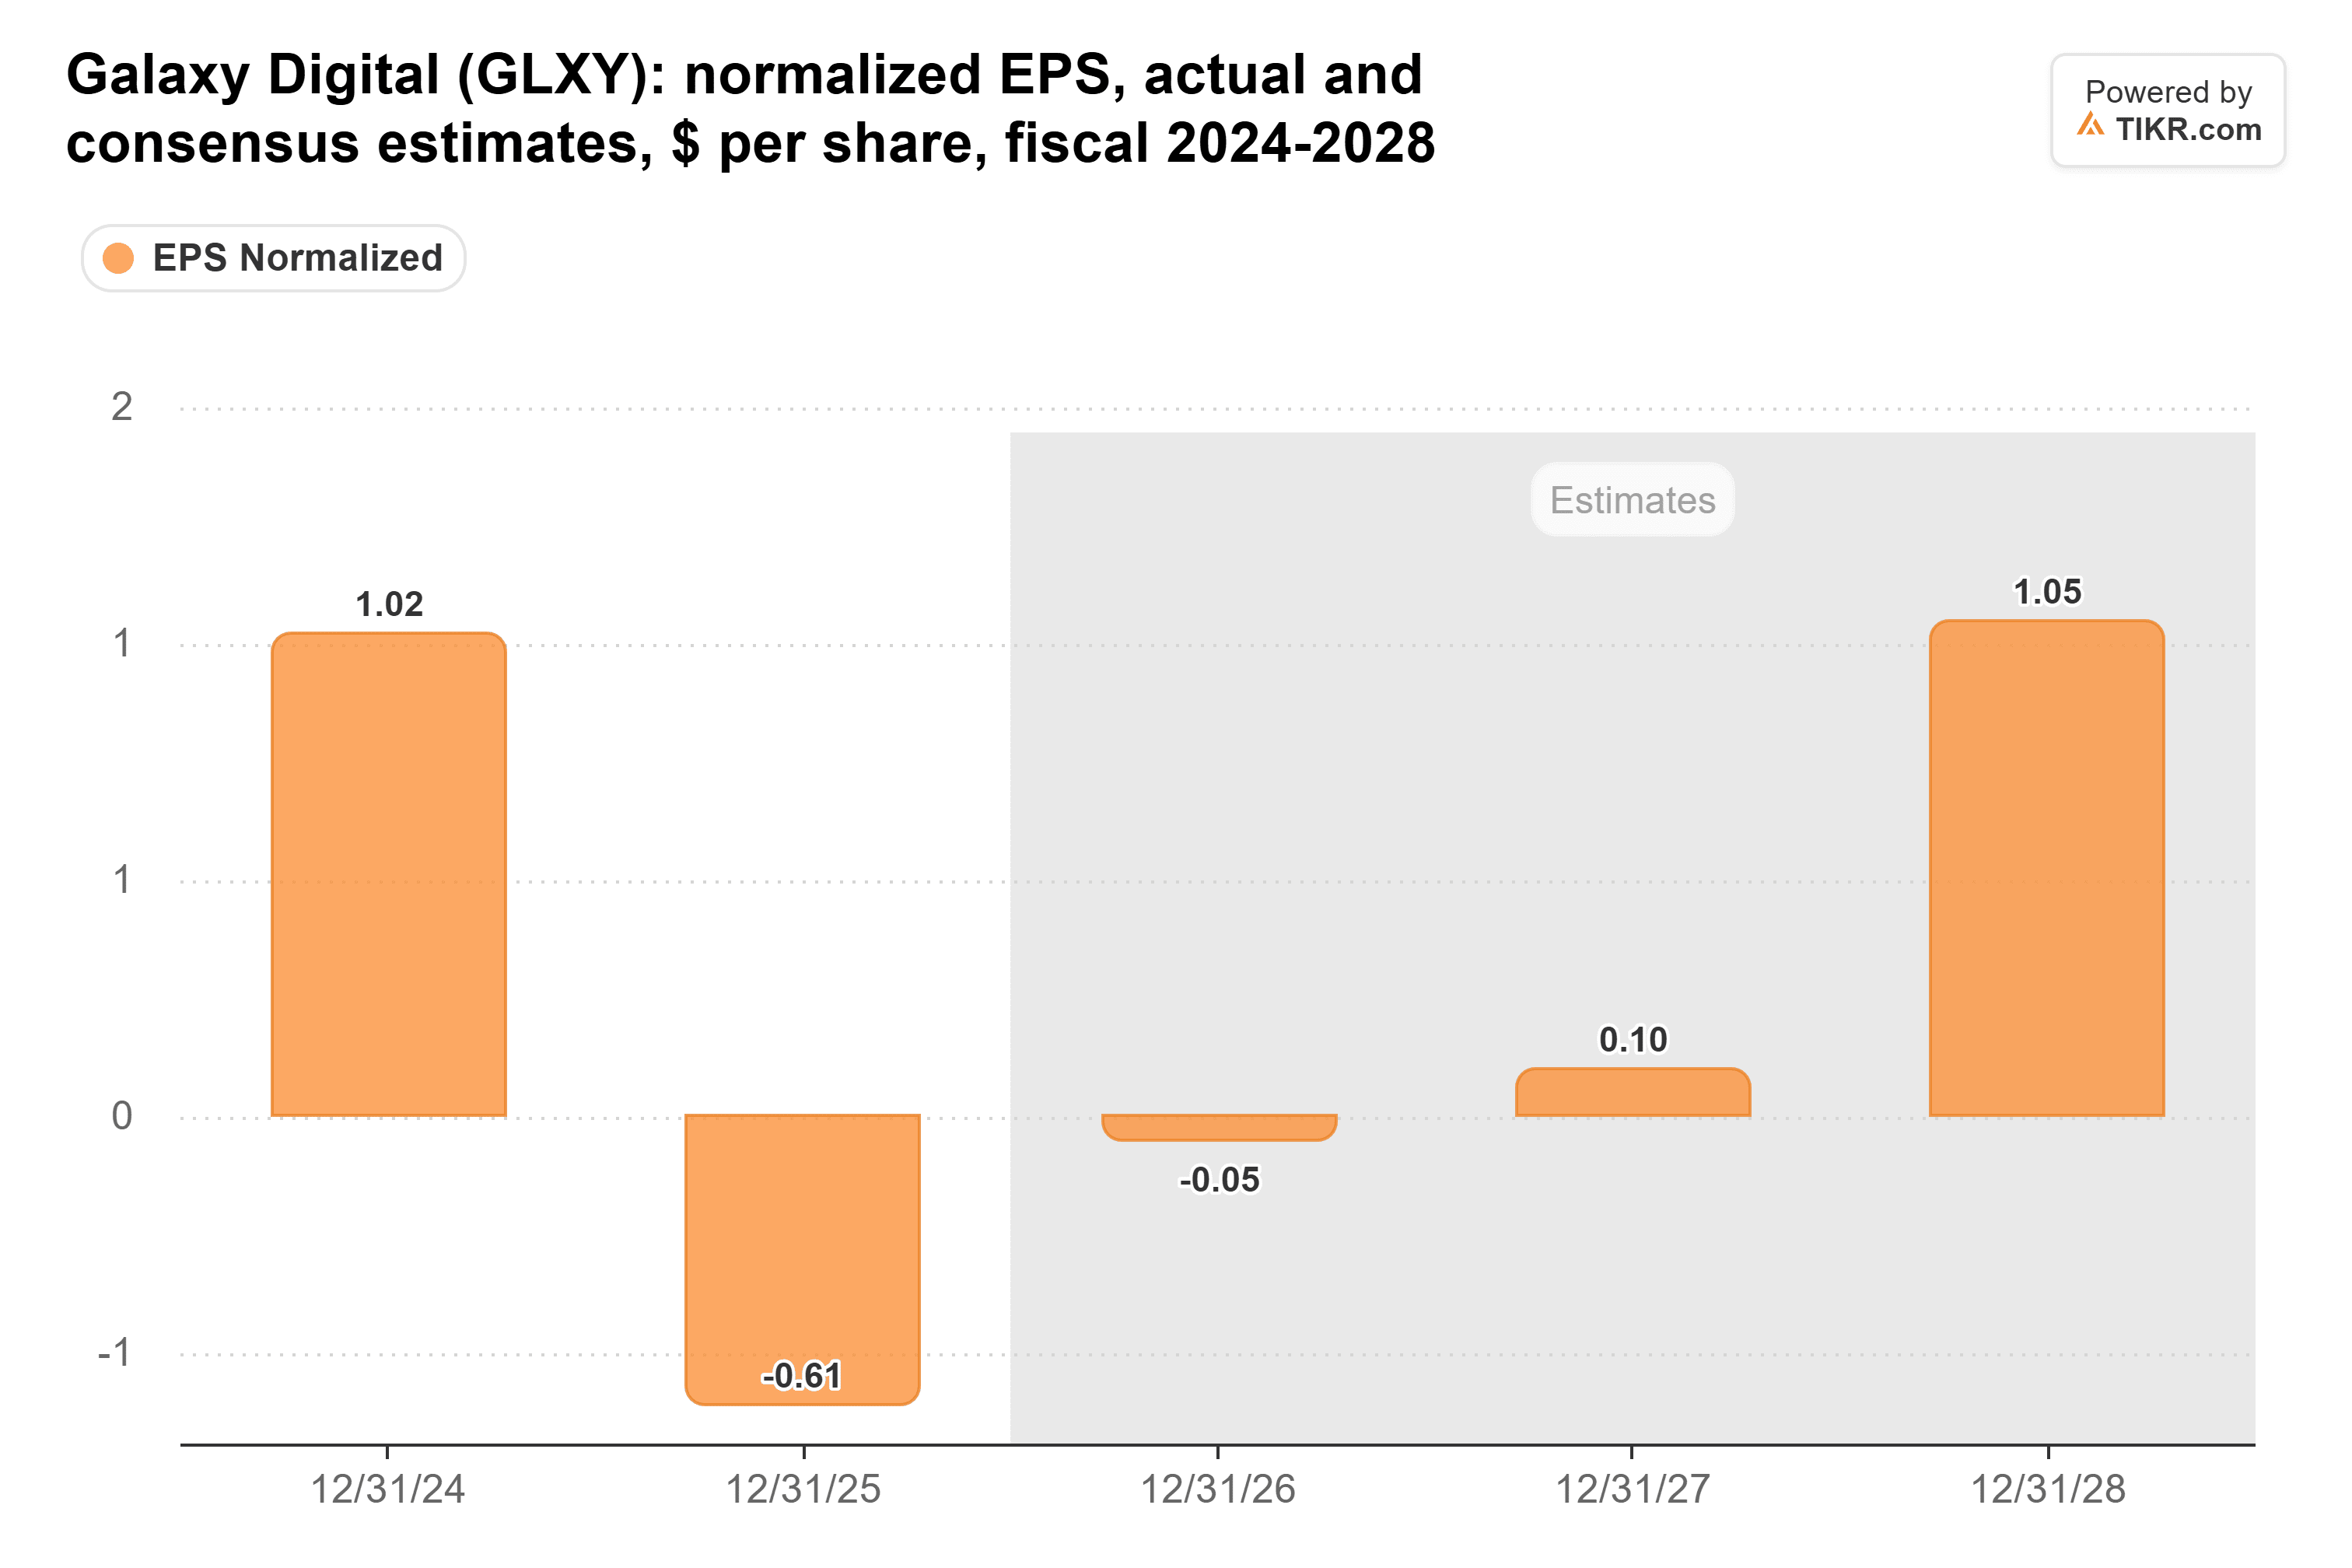
(Only five analysts estimate 2028, against 13 for 2027, so that figure rests on the fewest estimates on the chart.)
Most of the rent is still a construction project
The 133 MW Galaxy has delivered is only about a quarter of the 526 MW of critical IT load that CoreWeave has committed to across Helios’ first three phases. Those three phases use all 800 MW of approved power. Phase II is fully financed and under construction, and data hall deliveries are scheduled to begin in the second quarter of 2027. That means most of the $1 billion-plus a year is still years away, and getting it depends on Galaxy’s own building.
That building shows up in Galaxy’s spending:
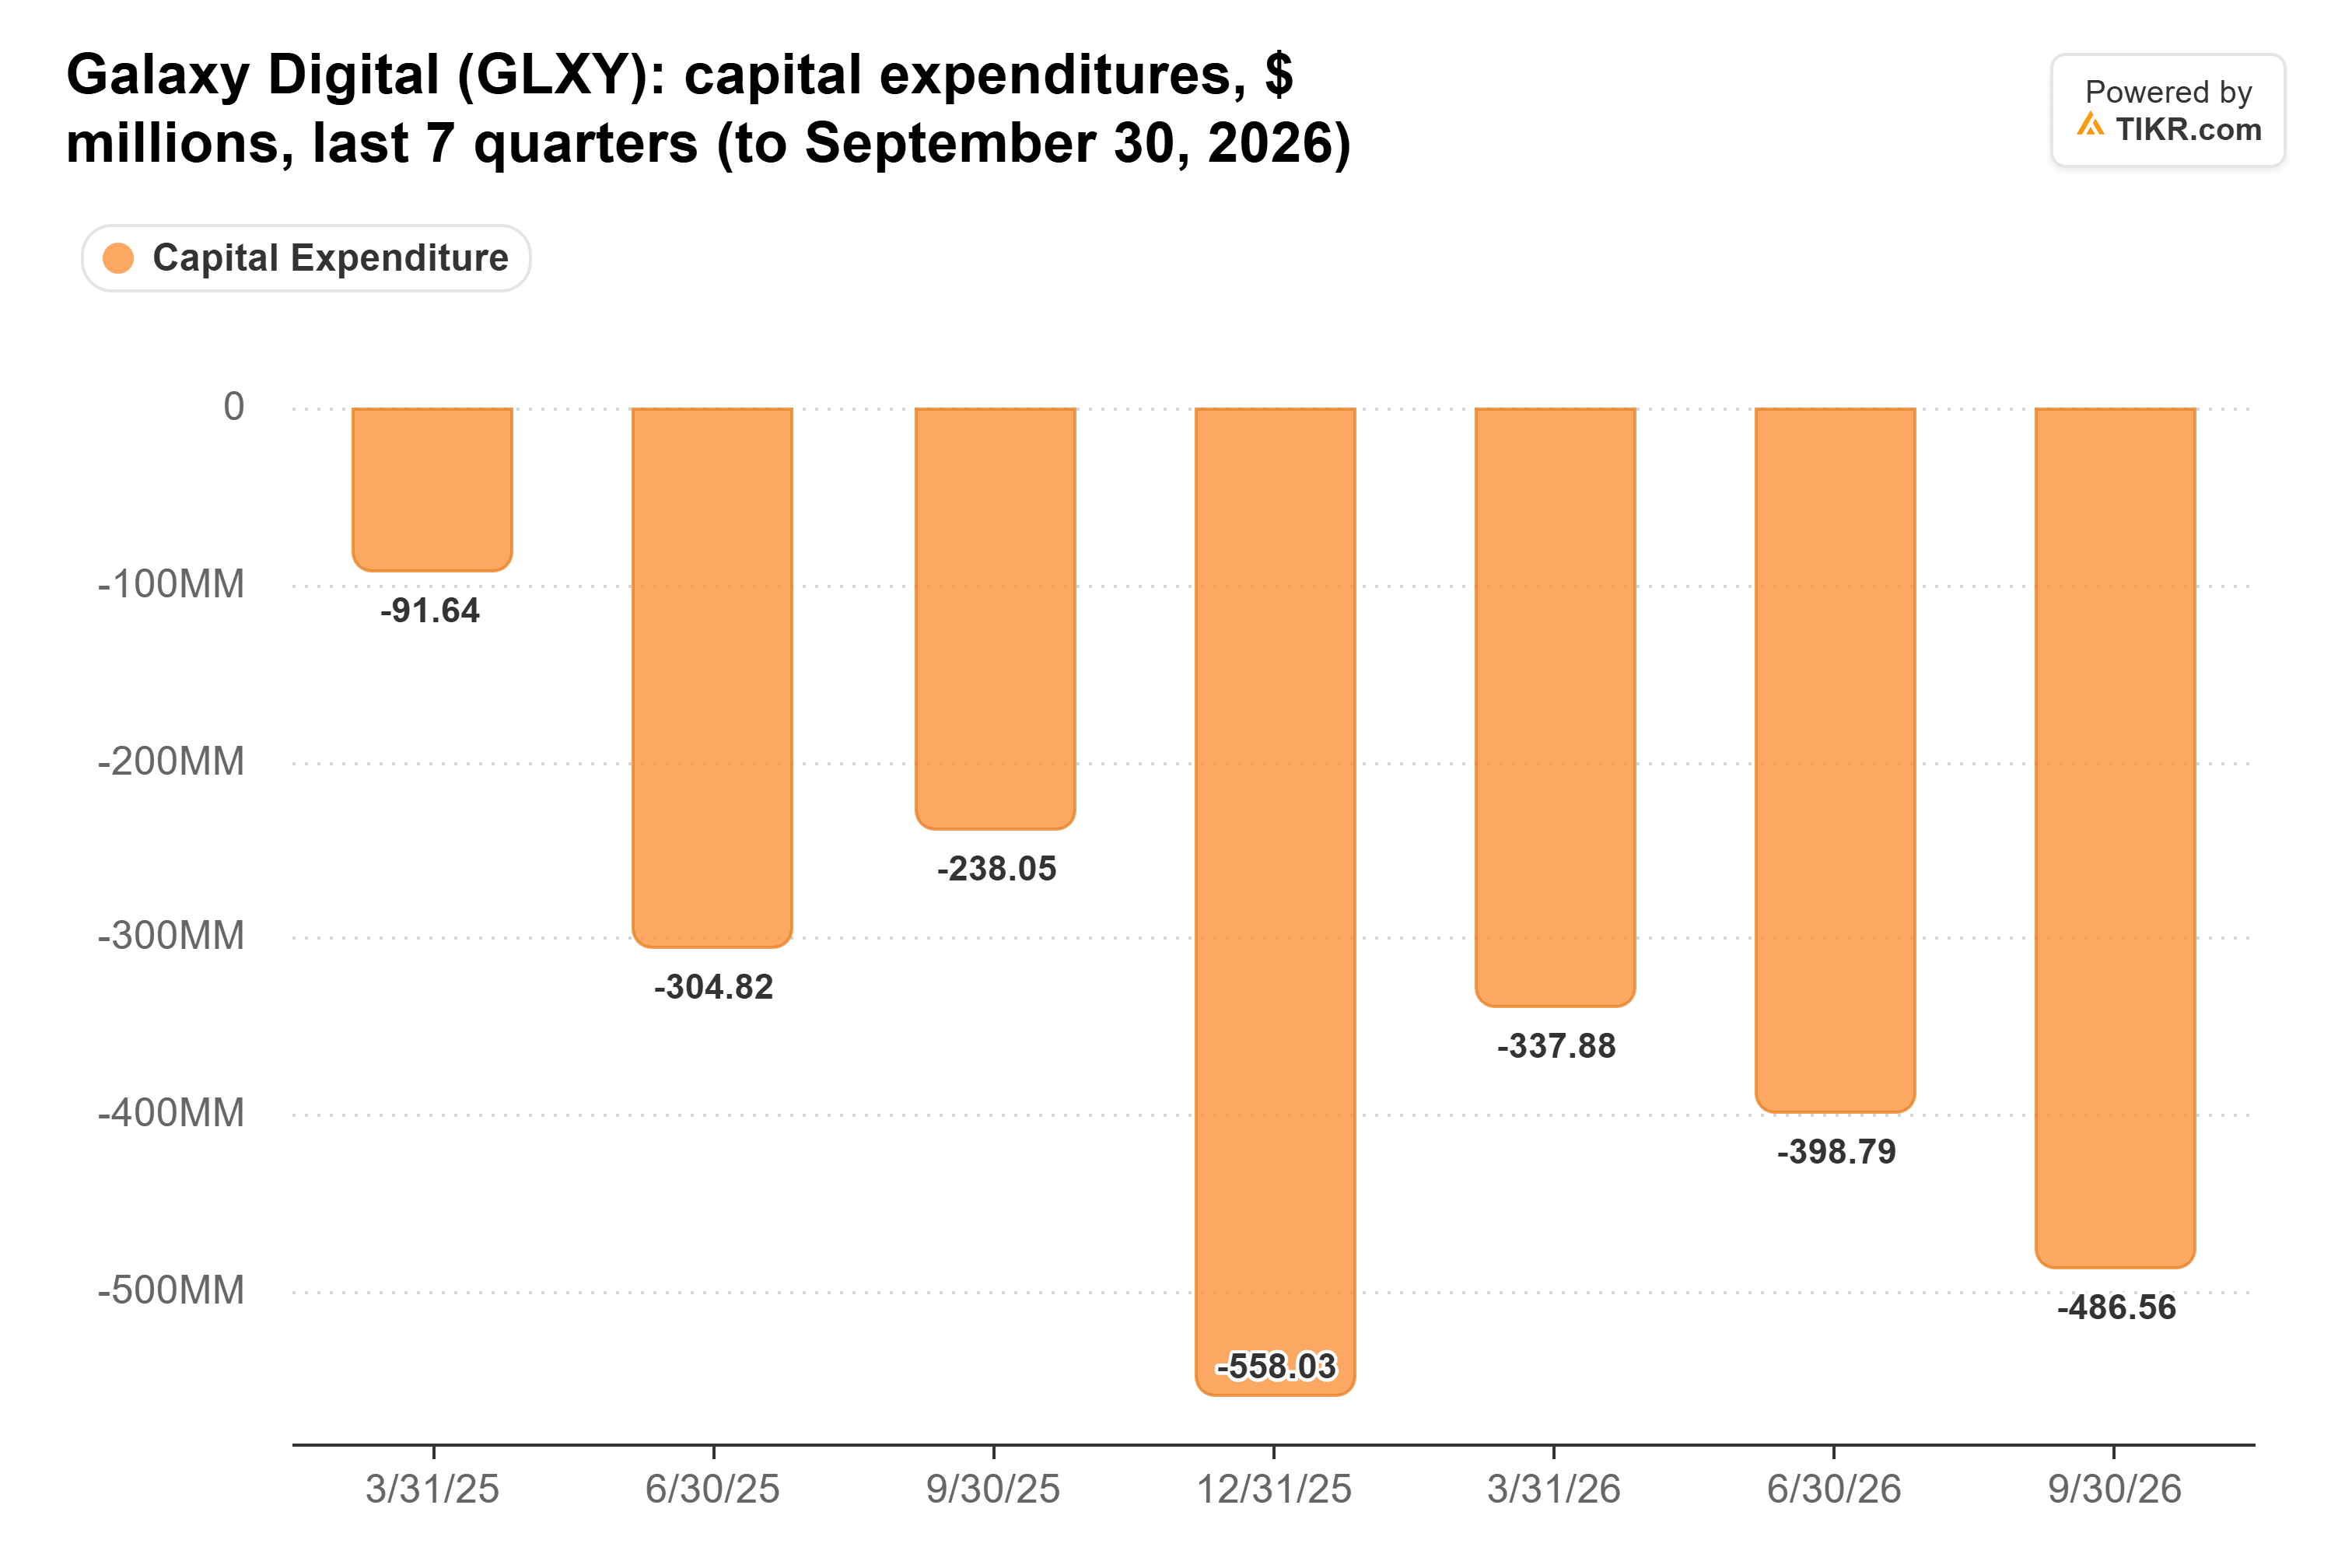
Galaxy spent $487 million in the third quarter, its second-biggest quarter of the past seven, and about $1.78 billion over the last four quarters.
Galaxy’s rent looks safer than it did a month ago
CoreWeave’s quarter answers Galaxy’s scariest question: whether its only tenant can pay. About $9 billion of customer cash is due over the next three months, and capacity is arriving ahead of plan. I think the risk that CoreWeave can’t pay for Helios is smaller now than when its bonds were priced near 15%. What’s left is the risk Galaxy controls, which is getting Phase II built. Given how much the tenant’s biggest worry has eased, a 5% gain looks modest to me, as long as construction stays on schedule.
Of course, one tenant is still one tenant, and CoreWeave still borrows heavily to build. The next milestone is Phase II’s first data halls in the second quarter of 2027. Galaxy’s construction updates in its next few reports will show whether that date holds.
So what is Galaxy Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Galaxy Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!