

Key Takeaways
- CoreWeave reports third-quarter results after the bell today with its unsecured debt yielding about 16%.
- CoreWeave’s 400 MW lease at Polaris Forge 1 is worth about $11.0 billion to Applied Digital, or 30.4% of its $36.2 billion of contracted revenue.
- The lease is take-or-pay, and most of Applied Digital’s other contracted rent comes from investment-grade hyperscalers, so the tenant risk looks smaller than the stock’s slide suggests.
- The bigger test is Applied Digital’s own financing, which cost 2.6x its base rent last quarter while it still has about 800 MW left to fund.
CoreWeave (CRWV) reports third-quarter results after the bell today, and Bloomberg says it has “a sentiment problem even strong earnings can’t fix.”
Most of that problem is CoreWeave’s debt. As MoffettNathanson managing director Nick Del Deo put it on yesterday’s episode of CNBC’s Closing Bell Overtime:
“Their unsecured parent company debt is yielding approximately 16%. It’s pretty uncommon to see a company with debt yielding at that level in the market, but also have a 30 billion or so market cap. One of those two things is wrong.”
If the bond market turns out to be right, CoreWeave’s shareholders won’t be the only ones who feel it. Applied Digital (APLD) leases all 400 MW of its Polaris Forge 1 campus in North Dakota to CoreWeave, and its stock hit a 52-week low last week.
TIKR tracks 42 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
A third of the rent comes from CoreWeave
The Polaris Forge 1 lease runs 15 years on take-or-pay terms and is worth about $11.0 billion over its base term. That’s 30.4% of Applied Digital’s $36.2 billion of contracted revenue as of May 31. Only a tier-one hyperscaler, at 55.8%, accounts for more. CoreWeave also pays the most per megawatt: about $1.83 million a year, roughly 10% more than the $1.65 million to $1.67 million the hyperscalers pay. (That makes sense for the riskier tenant.)
Those leases are why analysts expect Applied Digital’s revenue to more than triple from fiscal 2026 to fiscal 2028.
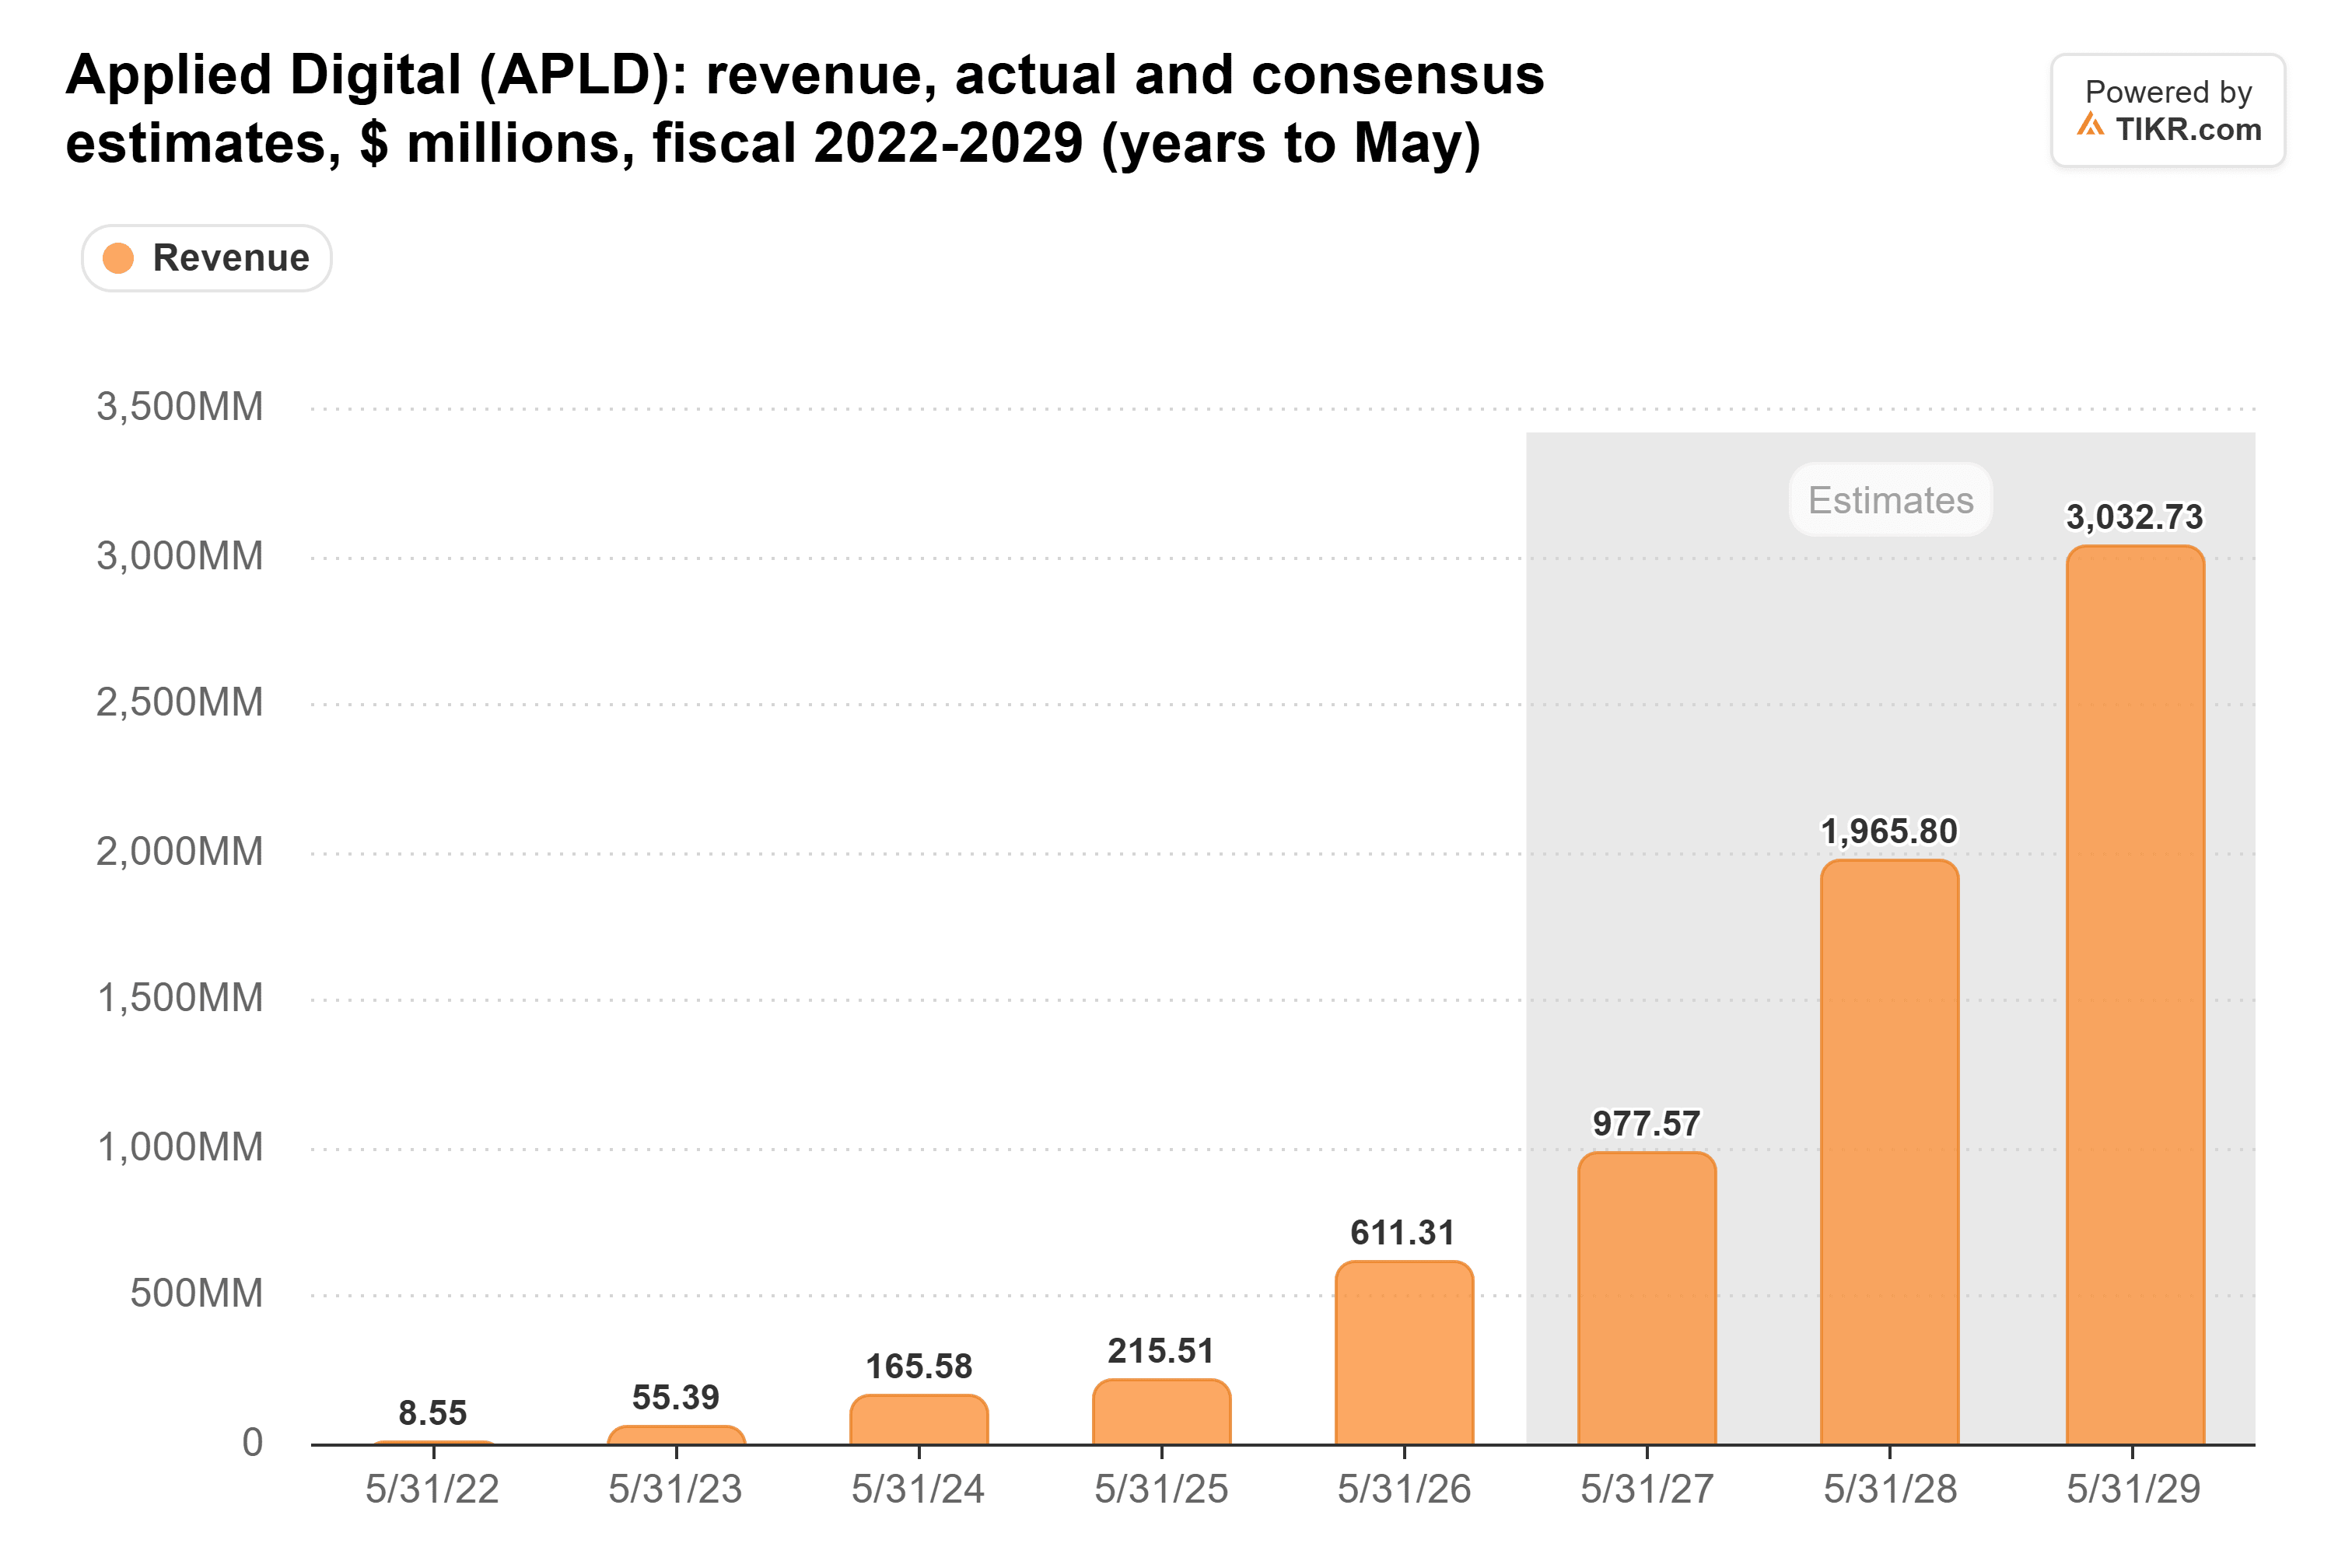
And nothing in CoreWeave’s bond prices changes the rent schedule behind those estimates, as long as CoreWeave keeps paying.
CoreWeave’s debt load keeps climbing
CoreWeave’s total debt more than tripled in a year, to $51.6 billion at June 30.
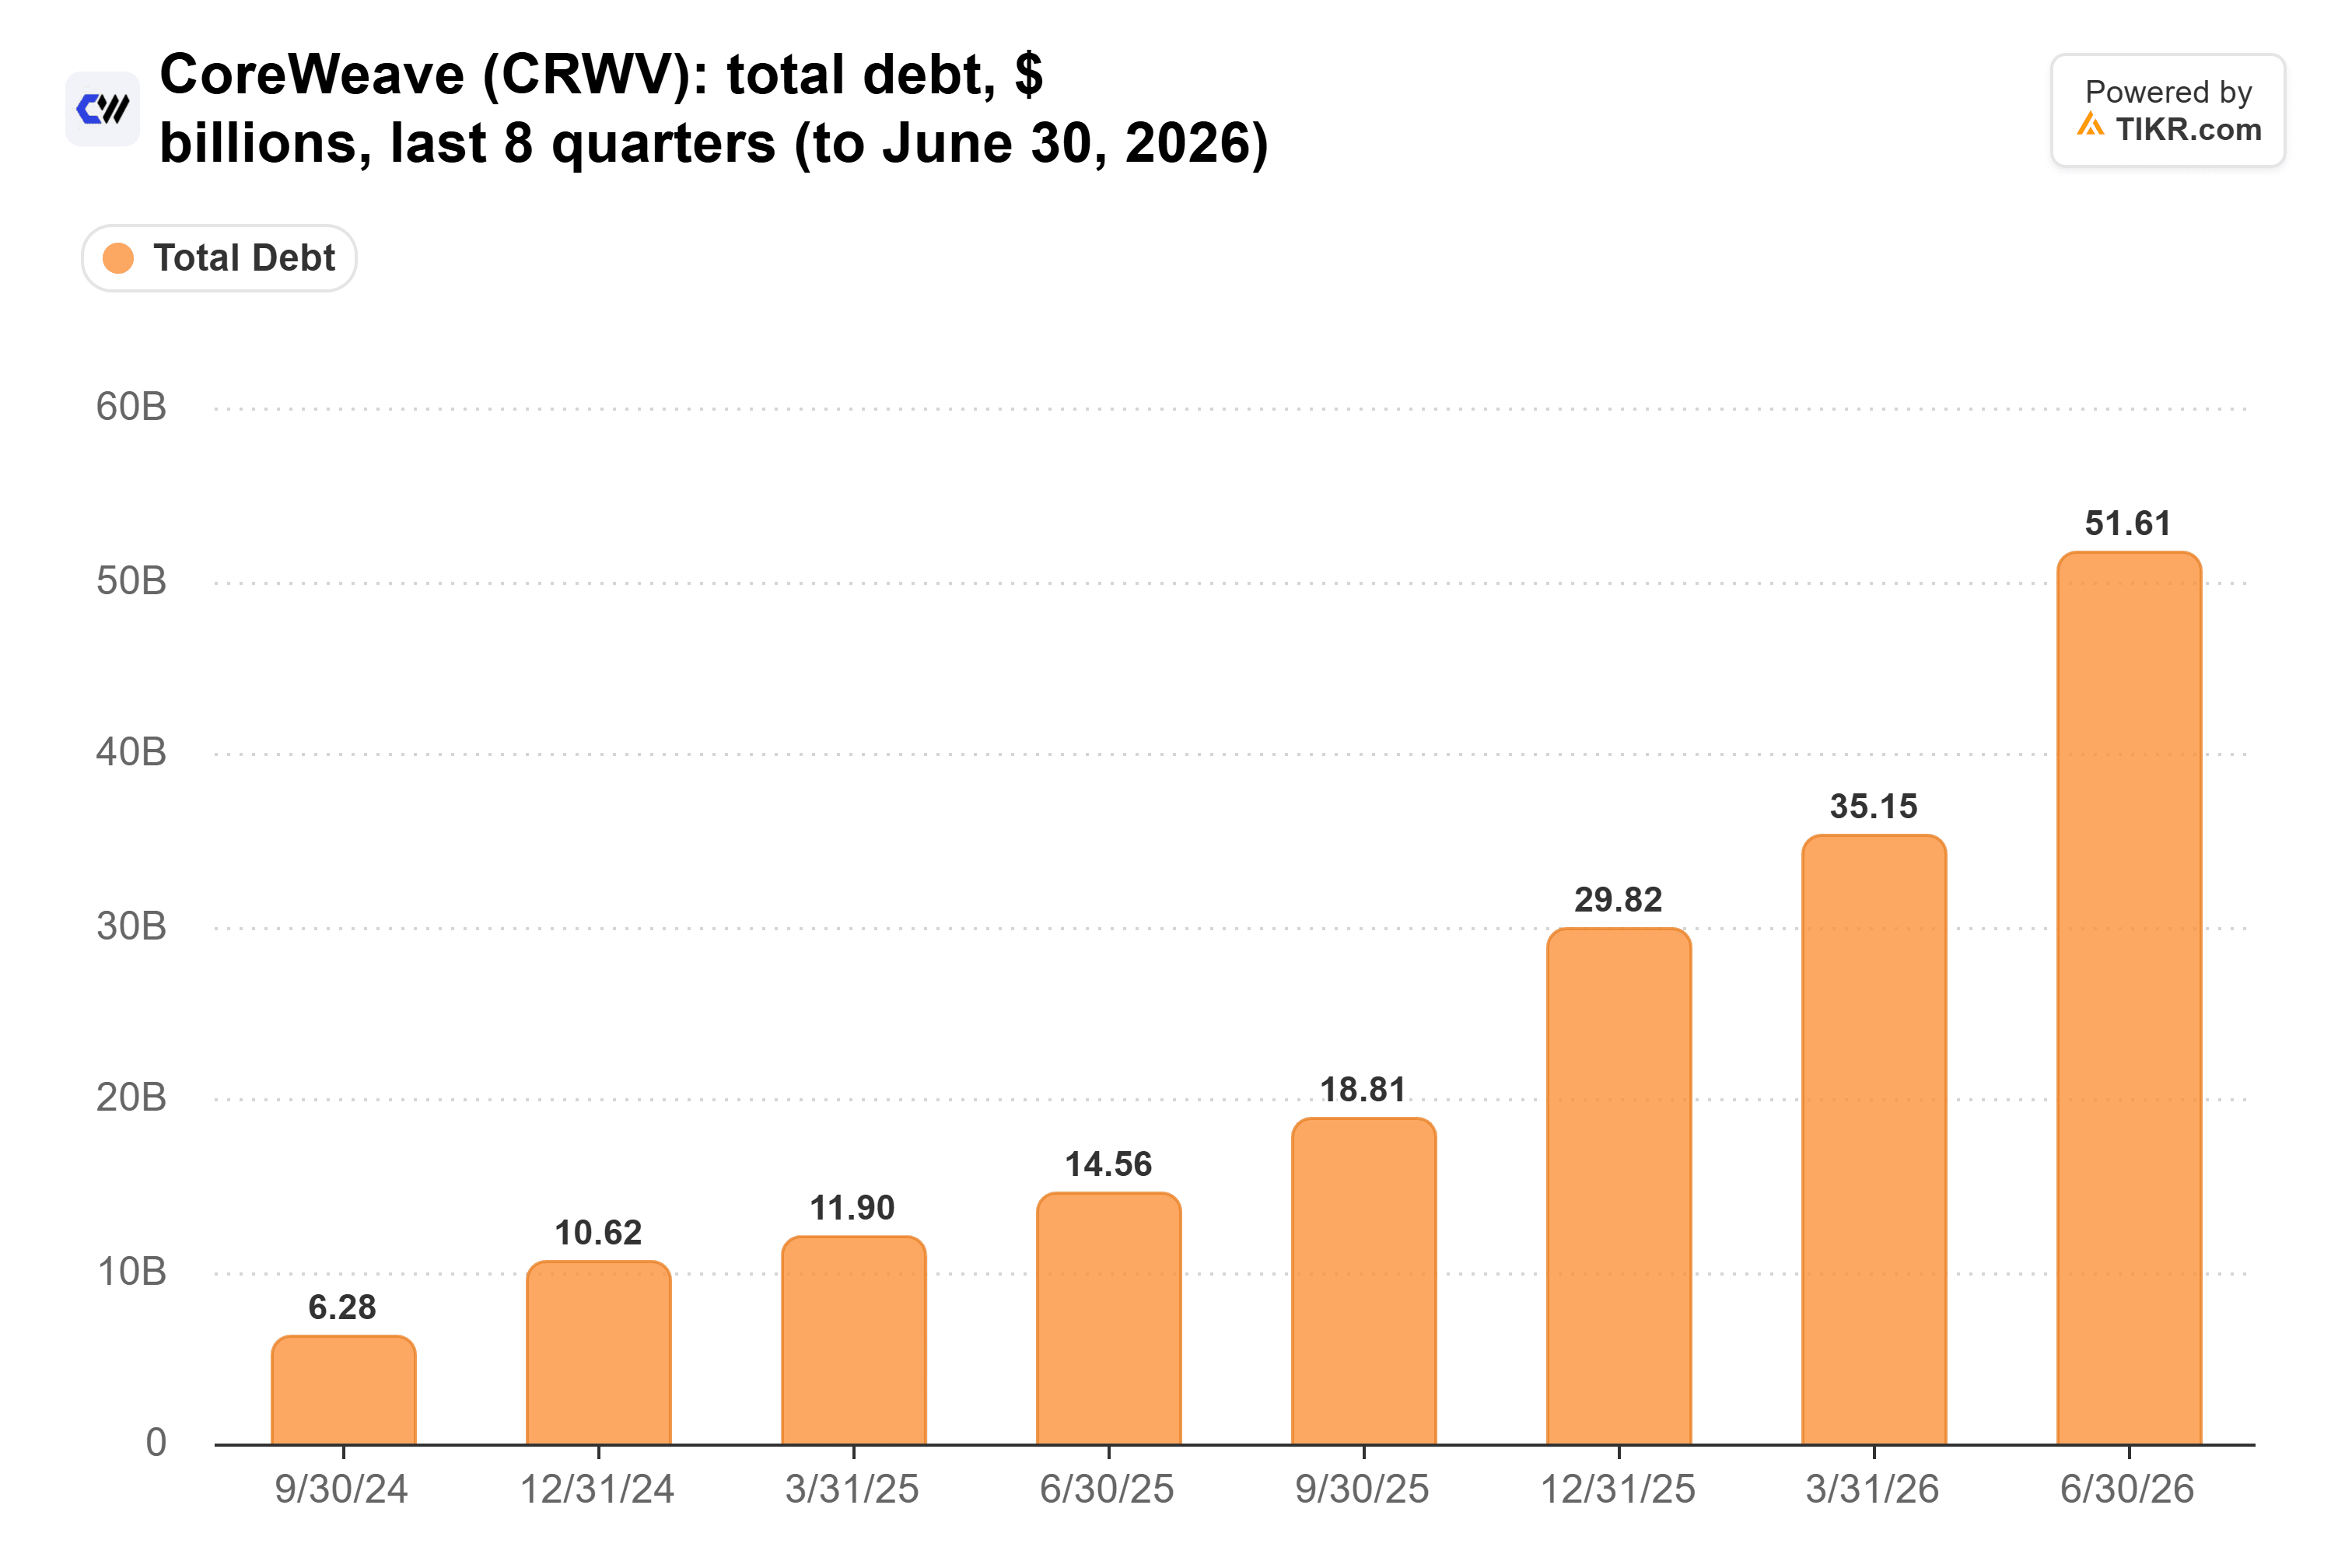
Del Deo added that CoreWeave is largely shut out of the unsecured bond market right now, just as it needs tens of billions of dollars over the coming quarters. That’s the gap bond investors are worried about.
And the backstop many investors have counted on looks shakier this week. Last month, Nvidia (NVDA) CEO Jensen Huang defended CoreWeave after worries about its debt hit the stock. Now Nvidia is investigating Huang’s affair with an alleged Chinese spy. Gil Luria, head of technology research at D.A. Davidson, explained what that means on yesterday’s Squawk on the Street: “if somebody owns CoreWeave with the belief that, oh, Nvidia is just a backstop, that becomes more challenging without Jensen Huang.”
Applied Digital wrote this lease for a week like this
The Polaris Forge 1 lease can’t be cancelled, and Applied Digital says a tenant that walks away for convenience owes the full remaining contract value. In March 2026, CoreWeave also moved parts of two Polaris Forge 1 leases into an A3-rated subsidiary with a parent guarantee, so some of that rent now comes from a stronger credit than CoreWeave’s own. The other 69.6% of contracted rent, $25.2 billion, comes from investment-grade hyperscalers. And Applied Digital’s signed campuses are in North Dakota, Louisiana and Alabama, outside the pause on new data centers that Texas Governor-elect Gina Hinojosa has called for.
Applied Digital’s own financing is the bigger test
Applied Digital’s interest expense jumped to $78.9 million in the quarter to Aug. 31, from $9.6 million a year earlier.
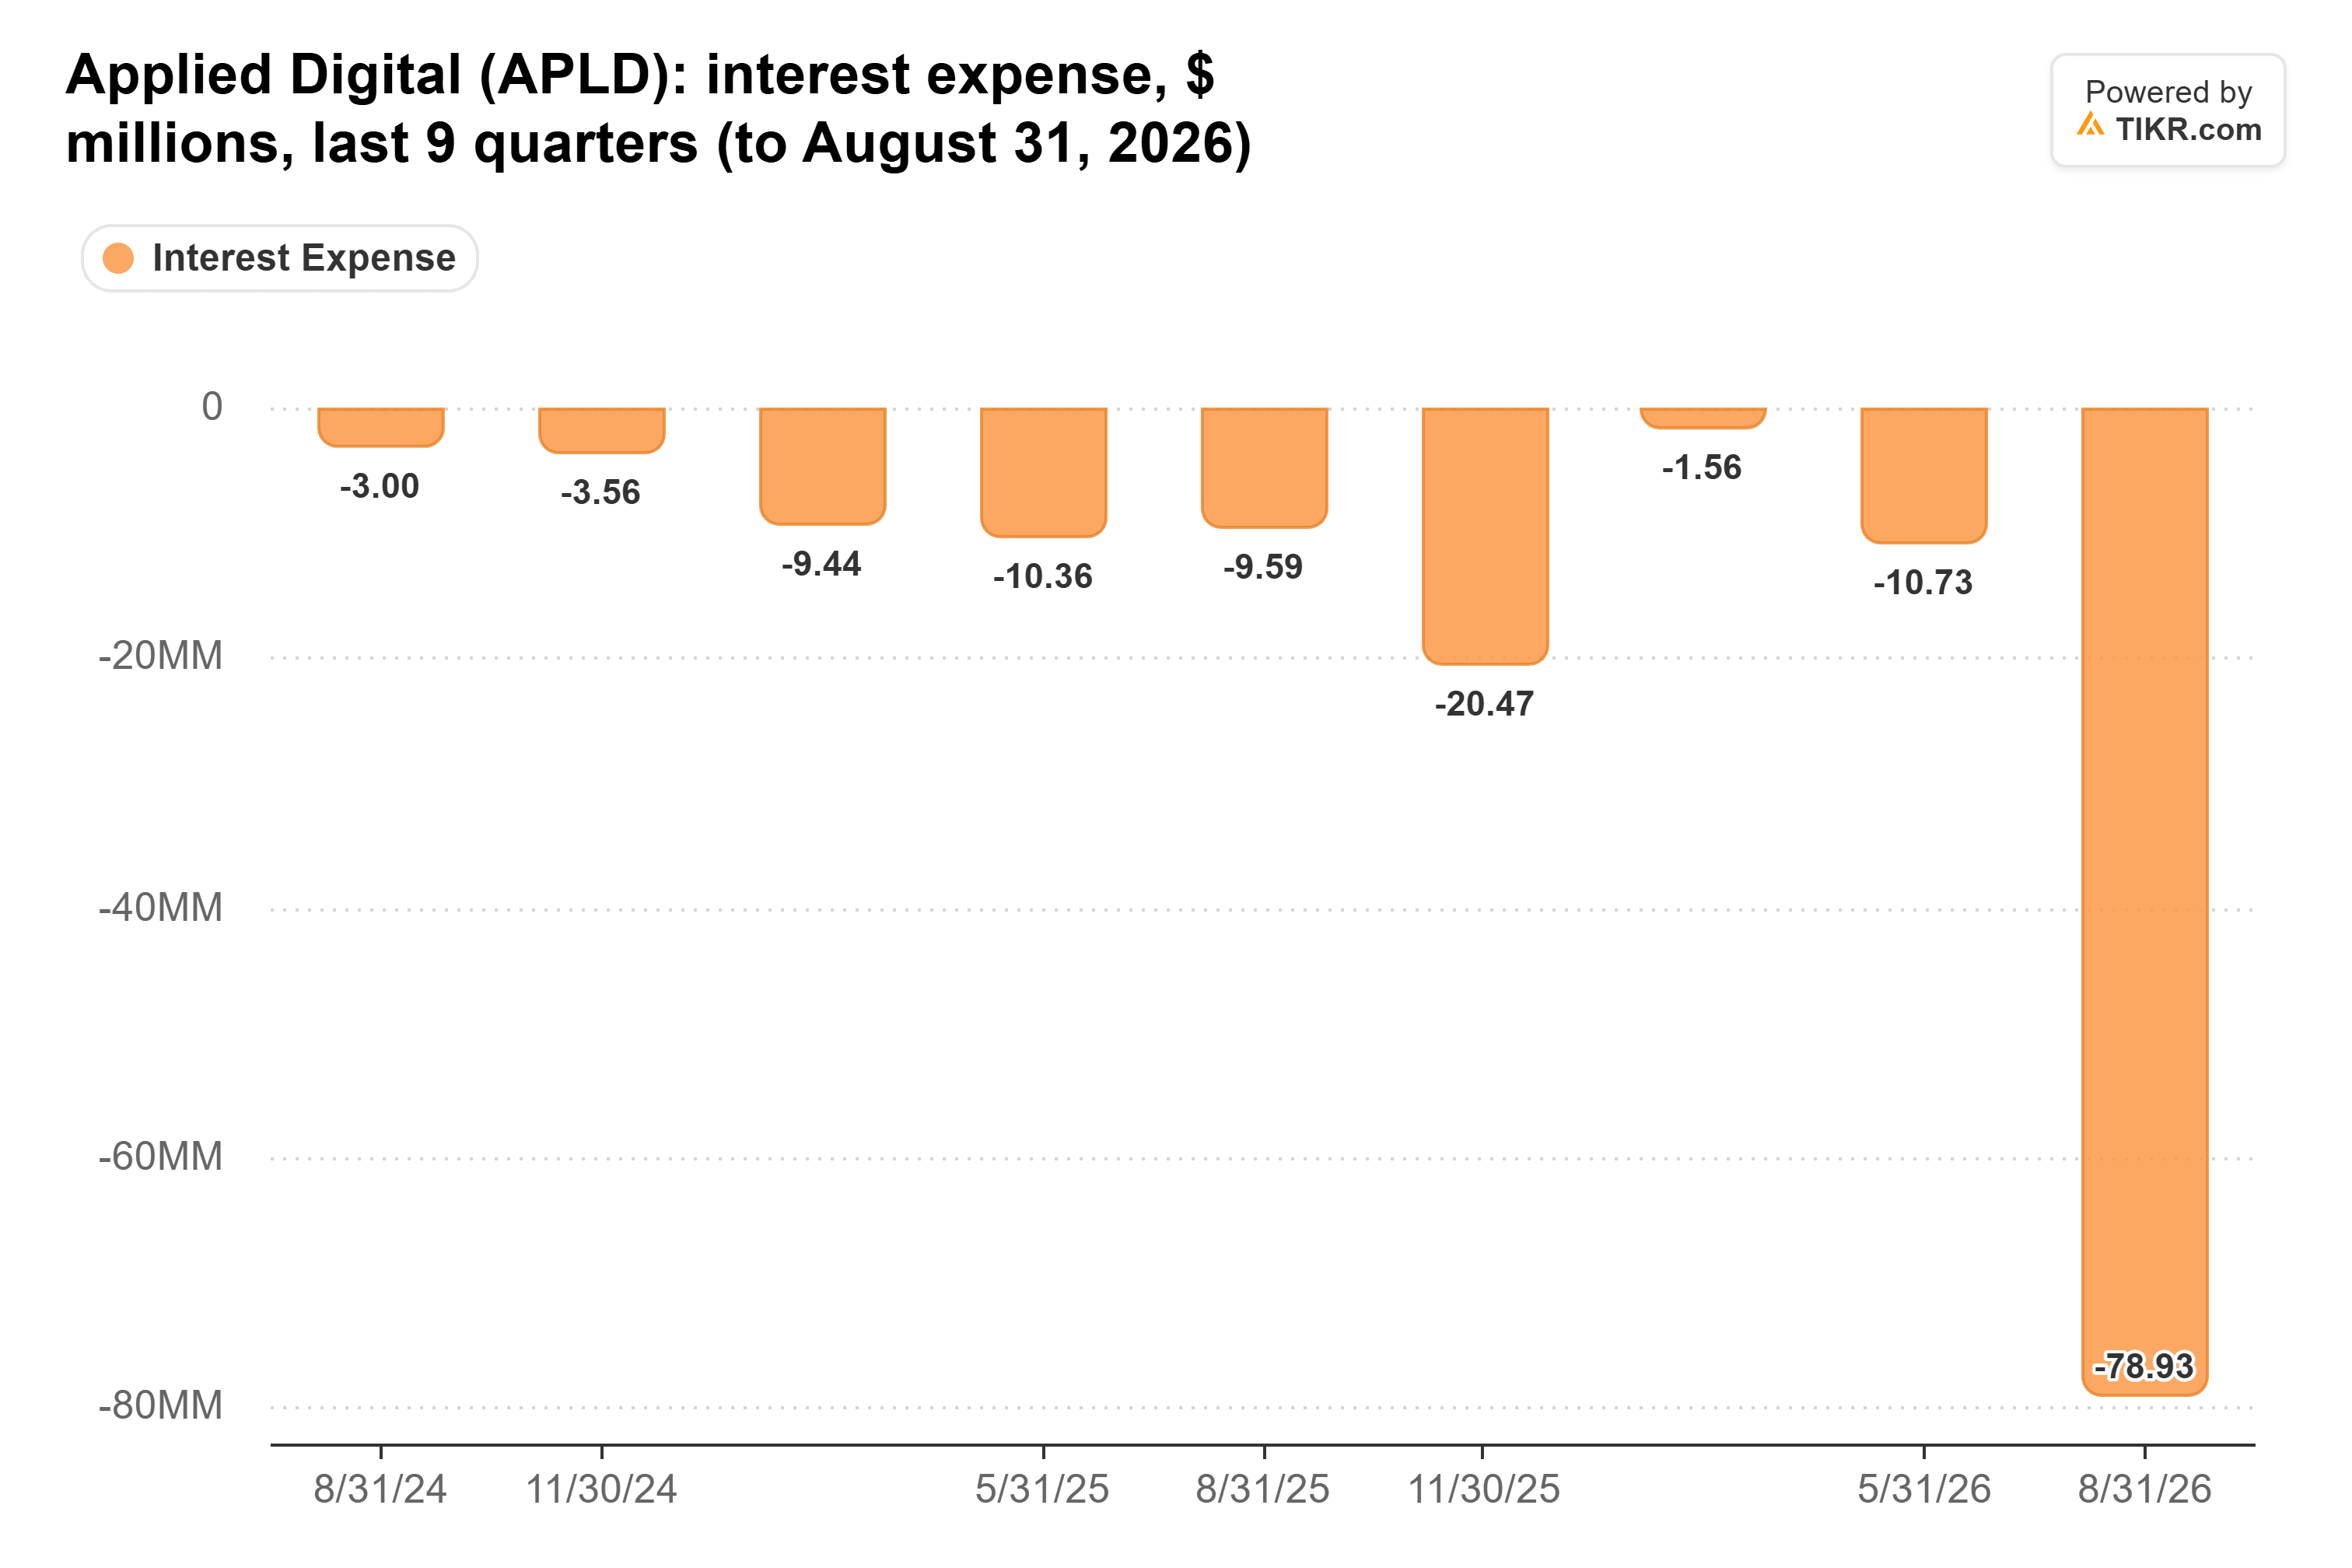
Counting the interest it capitalized into construction and the preferred dividends Macquarie took in kind, financing cost 2.6x the $65.8 million of base rent Applied Digital collected that quarter. Most of the rent is still to come as buildings go live, but so is most of the spending: CEO Wes Cummins said on CNBC on Nov. 2 that the company still needs funding for roughly 800 MW over the next 12 months. Meanwhile, shares outstanding rose from 287.88 million on May 31 to 302.39 million on Oct. 6.
Frankly, I think CoreWeave’s rent check is about as safe as a tenant’s can be with its bonds yielding 16%. I’m more worried that Applied Digital’s stock keeps trading like CoreWeave’s while the company still has to raise money, since every share it sells at these prices costs existing shareholders more.
Of course, if CoreWeave’s results tonight show it can’t raise the money it needs, I’d take the tenant risk a lot more seriously. Applied Digital’s next report, due in January, will be its first full quarter with 250 MW live at Polaris Forge 1.
So what is Applied Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Digital for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





