Key Takeaways
- Freedom Broker downgraded Costco to Hold from Buy on Nov. 10 because of its valuation. It also raised its price target to $1,050, which is 3% below the current price.
- Costco’s stock is up 18% over the past year after strong sales, and hours after the downgrade the company declared a $30-a-share special dividend.
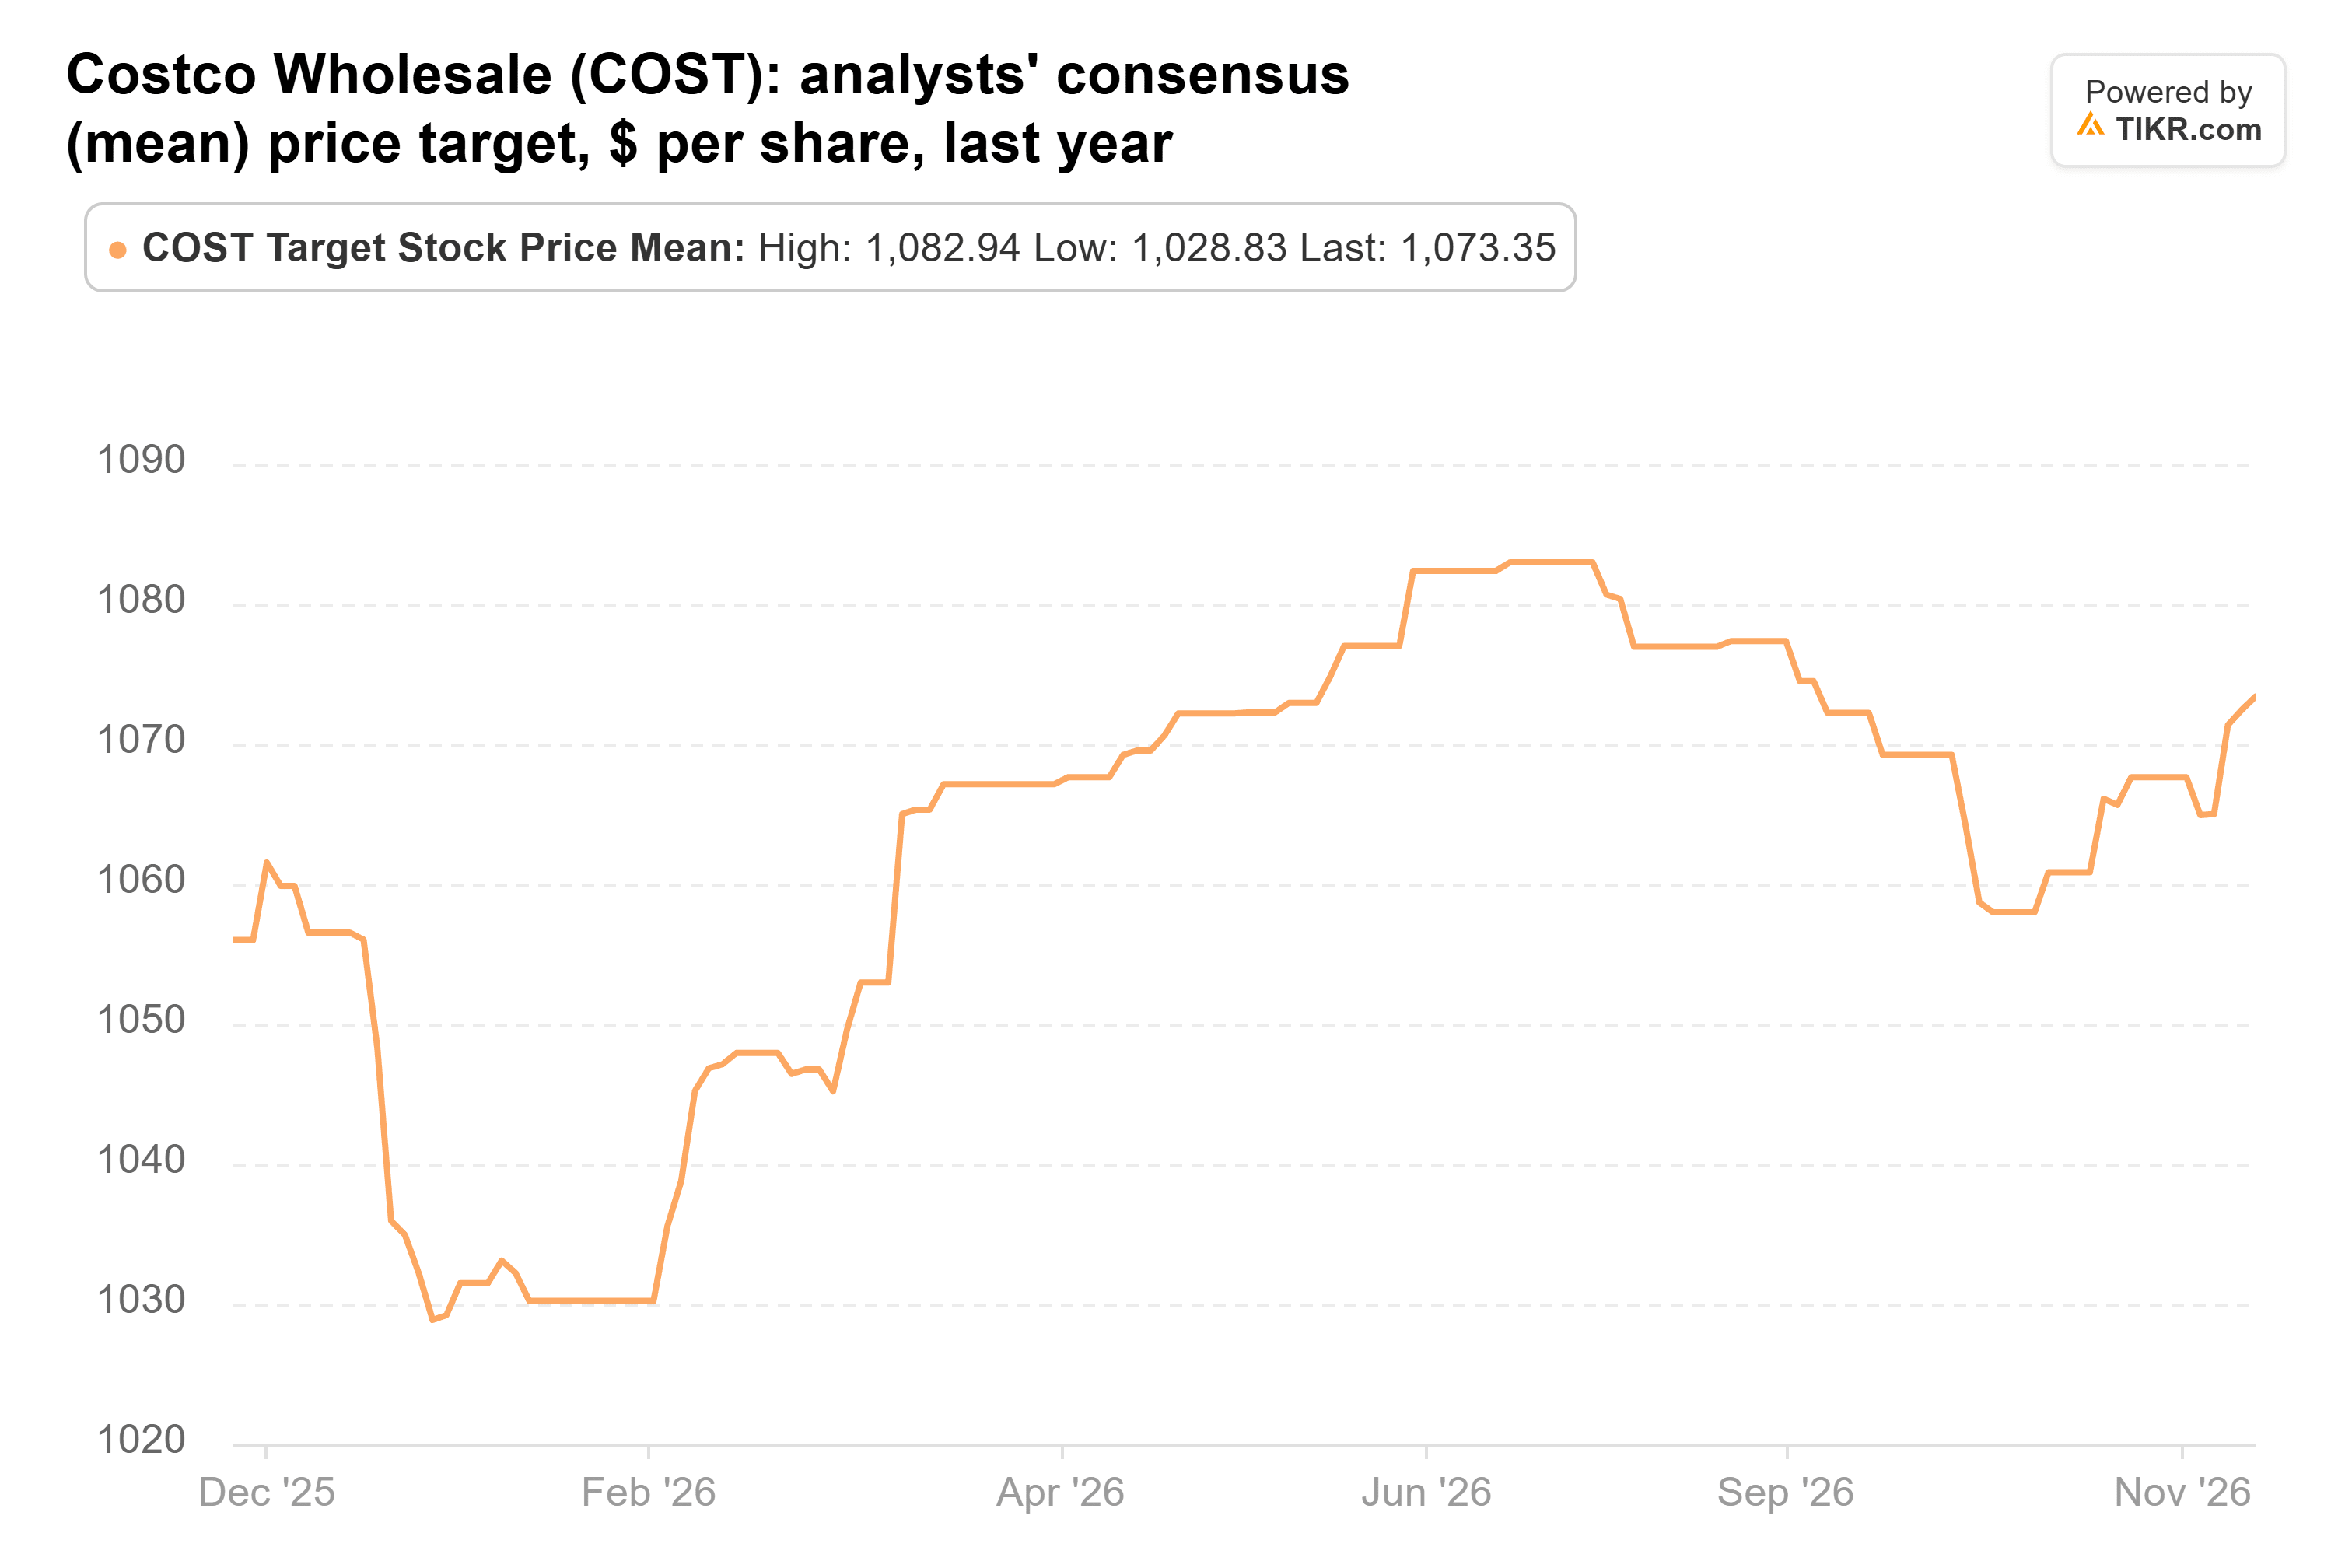
- Analysts expect earnings per share to grow about 10% a year through fiscal 2028, and the consensus price target of $1,073 is just under the current price.
- At 47x expected earnings, Costco is a stock to hold. The first-quarter report on Dec. 10 is the next test.
Costco Wholesale (COST) is coming off a strong October, and the stock is up 18% over the past year. Freedom Broker thinks that’s enough for now: it downgraded Costco to Hold from Buy on Nov. 10 because of its valuation.
A strong month at a full price
Freedom’s case has nothing to do with the business slowing down. Analyst Georgy Vashchenko called October’s sales strong, and they were. Net sales rose 12.6% to $24.5 billion in the four weeks to Nov. 1, and comparable sales excluding gas and currency rose 7.3%. He even raised his price target to $1,050 from $1,010. That target is 3% below today’s price of $1,079.
Then came a $30 check
A few hours after the downgrade, Costco declared a $30-a-share special dividend, payable Dec. 4. A stock usually drops by about the size of the dividend when it goes ex-dividend, which would put Costco at about Freedom’s $1,050, a target set before the announcement. So a holder who sits tight collects $30 a share, and Freedom doesn’t see much more than that from here.
TIKR tracks 41 analysts on Costco. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Costco, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Costco’s Analyst Ratings
Does $1,050 add up?
The consensus target from 41 analysts is $1,073, just under today’s price. Here’s how it has moved over the past year:
Analysts expect normalized EPS of $22.79 in fiscal 2027 and $25.03 in fiscal 2028 (Costco’s years end in August). That’s up from $20.61 in fiscal 2026, or about 10% a year:
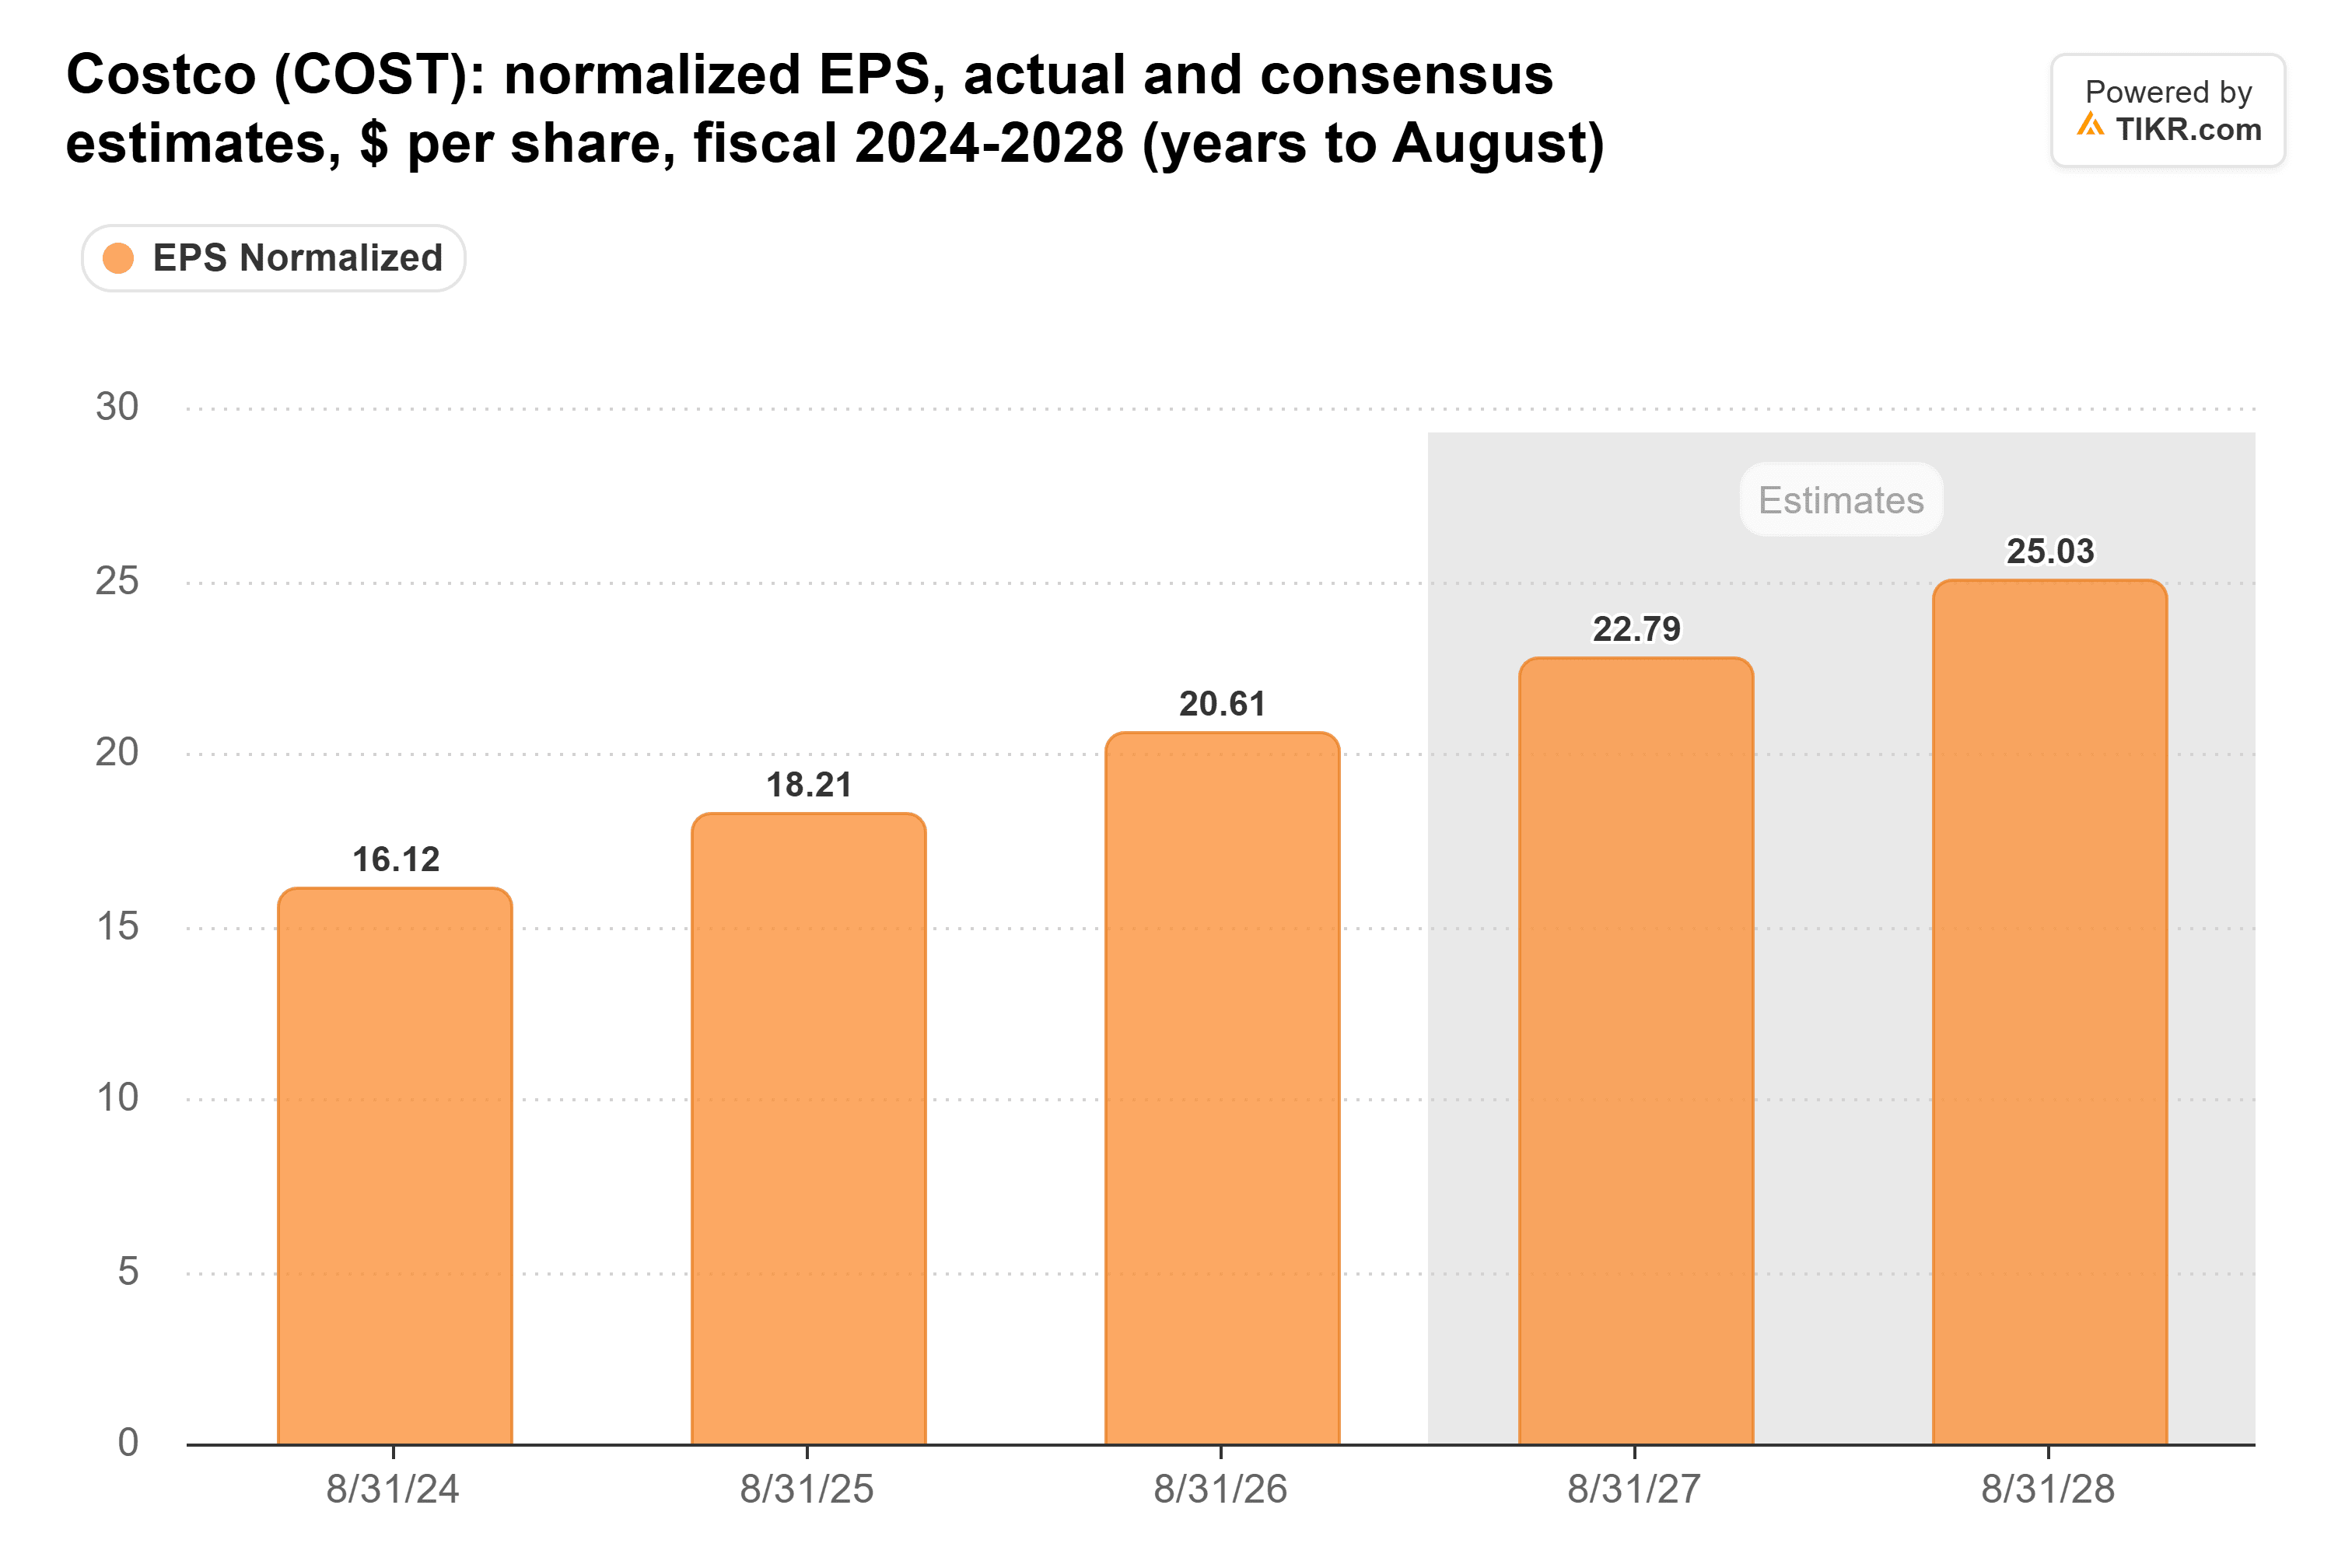
Those estimates have edged up over the past 90 days, and nothing in October’s sales suggests they should come down.
At $1,079, Costco trades at 47x the fiscal 2027 estimate. That’s in line with its three-year average forward P/E of 47x on TIKR and above its five-year average of 43x:
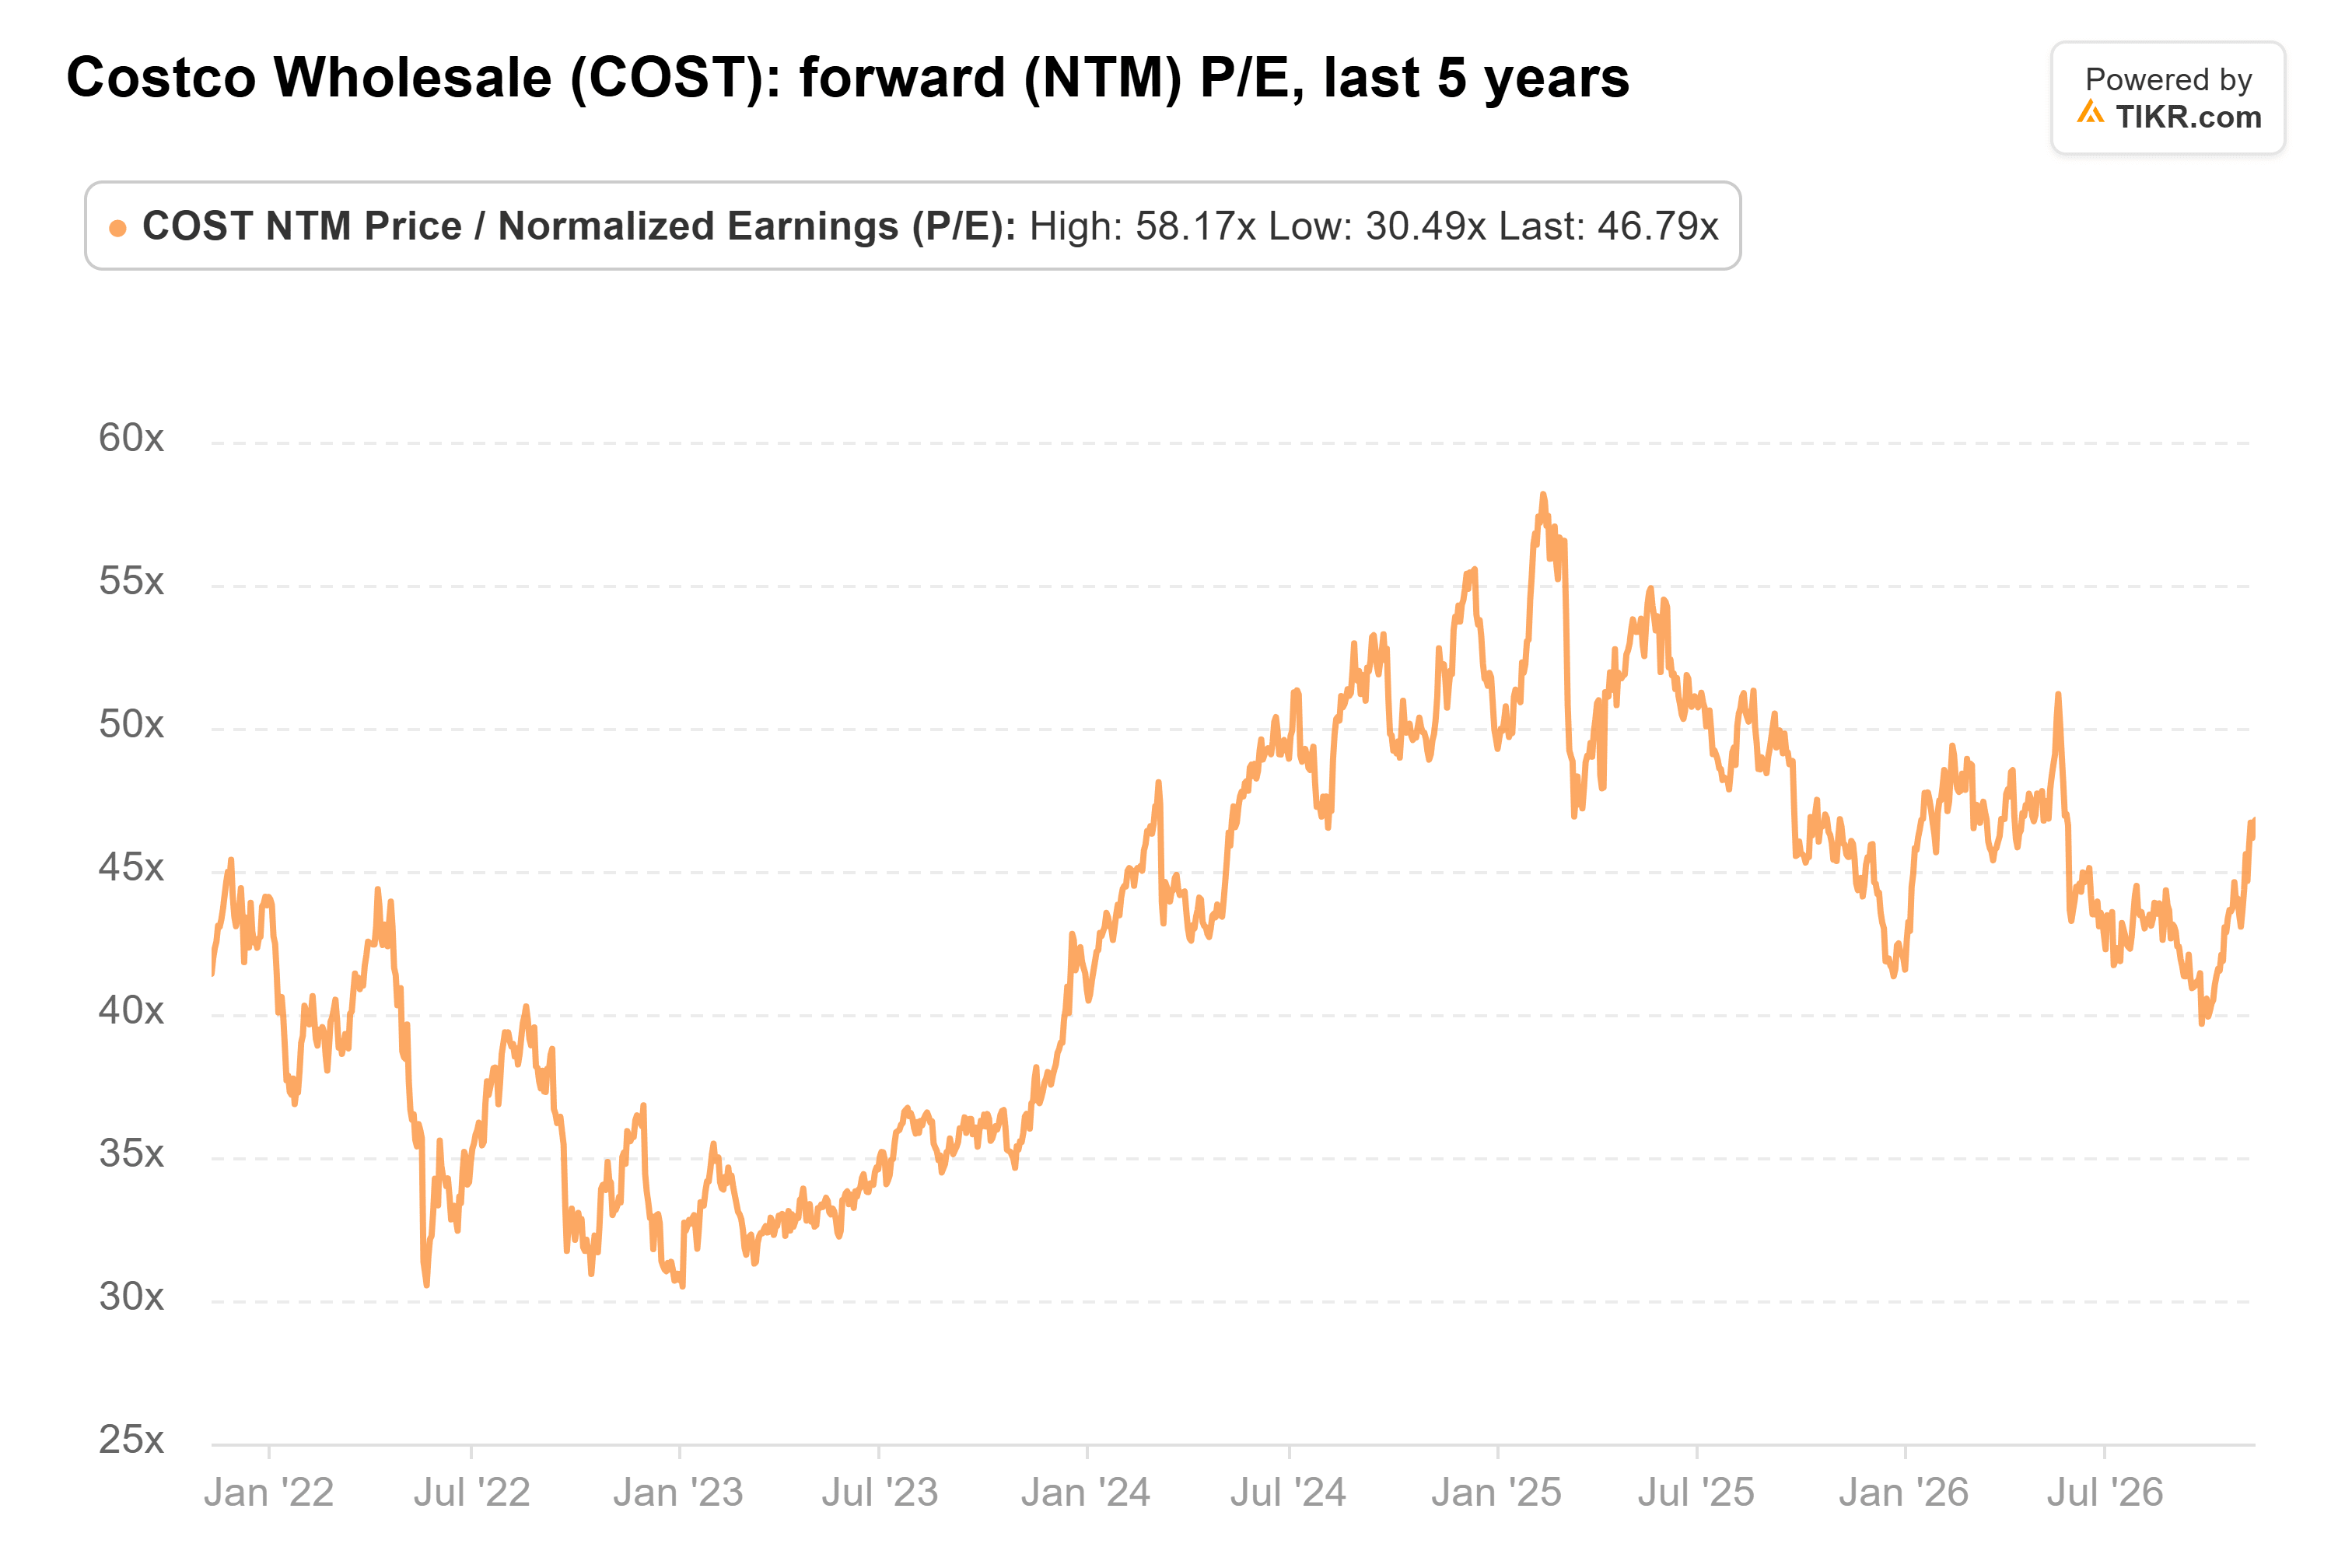
Freedom’s $1,050 works out to about 46x the same estimate, so even its target assumes the multiple stays near today’s level. That’s a lot to pay for about 10% growth when EPS grew about 15% a year from fiscal 2016 to fiscal 2026.
Hold is the right word
The risk to the downgrade is that Costco keeps comparable sales near 7% and raises estimates faster than the stock rises. Still, I’d side with Freedom. At 47x earnings, investors are already paying for more of the same. I’d hold it and wait for a pullback toward its five-year average multiple before buying more.
The first-quarter report on Dec. 10 is the next test. It will be the first quarter with no lift from the 2024 membership fee increase. Paid-member growth at or above the fourth quarter’s 3.8% would make Freedom’s call look too cautious.
So what is Costco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Costco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!