Key Takeaways
- MercadoLibre stock has fallen 29% in a year, and Goldman Sachs cut its price target to $2,100 from $2,230 on Nov. 11 while keeping its Buy rating.
- Third-quarter revenue rose 45%, but operating income fell 6% as the company spent more on free shipping, warehouse space and marketing in Brazil.
- At $2,100, the stock would trade at about 47x forward earnings, close to its usual level since 2023, but analysts keep cutting their earnings estimates.
- The target looks reachable, but it will probably take closer to two years than one, because management won’t commit to a margin recovery.
MercadoLibre (MELI) stock has lost 29% over the past year, and Goldman Sachs just lowered its price target. On Nov. 11, the firm cut it to $2,100 from $2,230 and kept its Buy rating, which still points to 41% upside.
MercadoLibre is spending its margin on growth
In the third quarter, reported Nov. 4, revenue rose 45% to $10.75 billion, but operating income fell 6% to $676 million, and earnings of $8.83 a share missed the $9.27 analysts expected.
Management pointed to more free shipping, extra affiliate marketing in Brazil and new warehouse space added ahead of the holidays. The shareholder letter called the shipping squeeze “the price of the habit we set out to build.”
Goldman still sees margins turning
Goldman’s $2,100 is 6% below the $2,244 consensus target.
Goldman analyst Irma Sgarz made the bull case in her question on the Nov. 4 call. With growth and engagement “remaining so strong,” she said, “it does feel like the inflection point for margins should be coming within the line of sight here.” CFO Martin de los Santos didn’t give a margin target, though: “The approach is to manage for the long term.”
TIKR tracks 26 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
Does $2,100 add up?
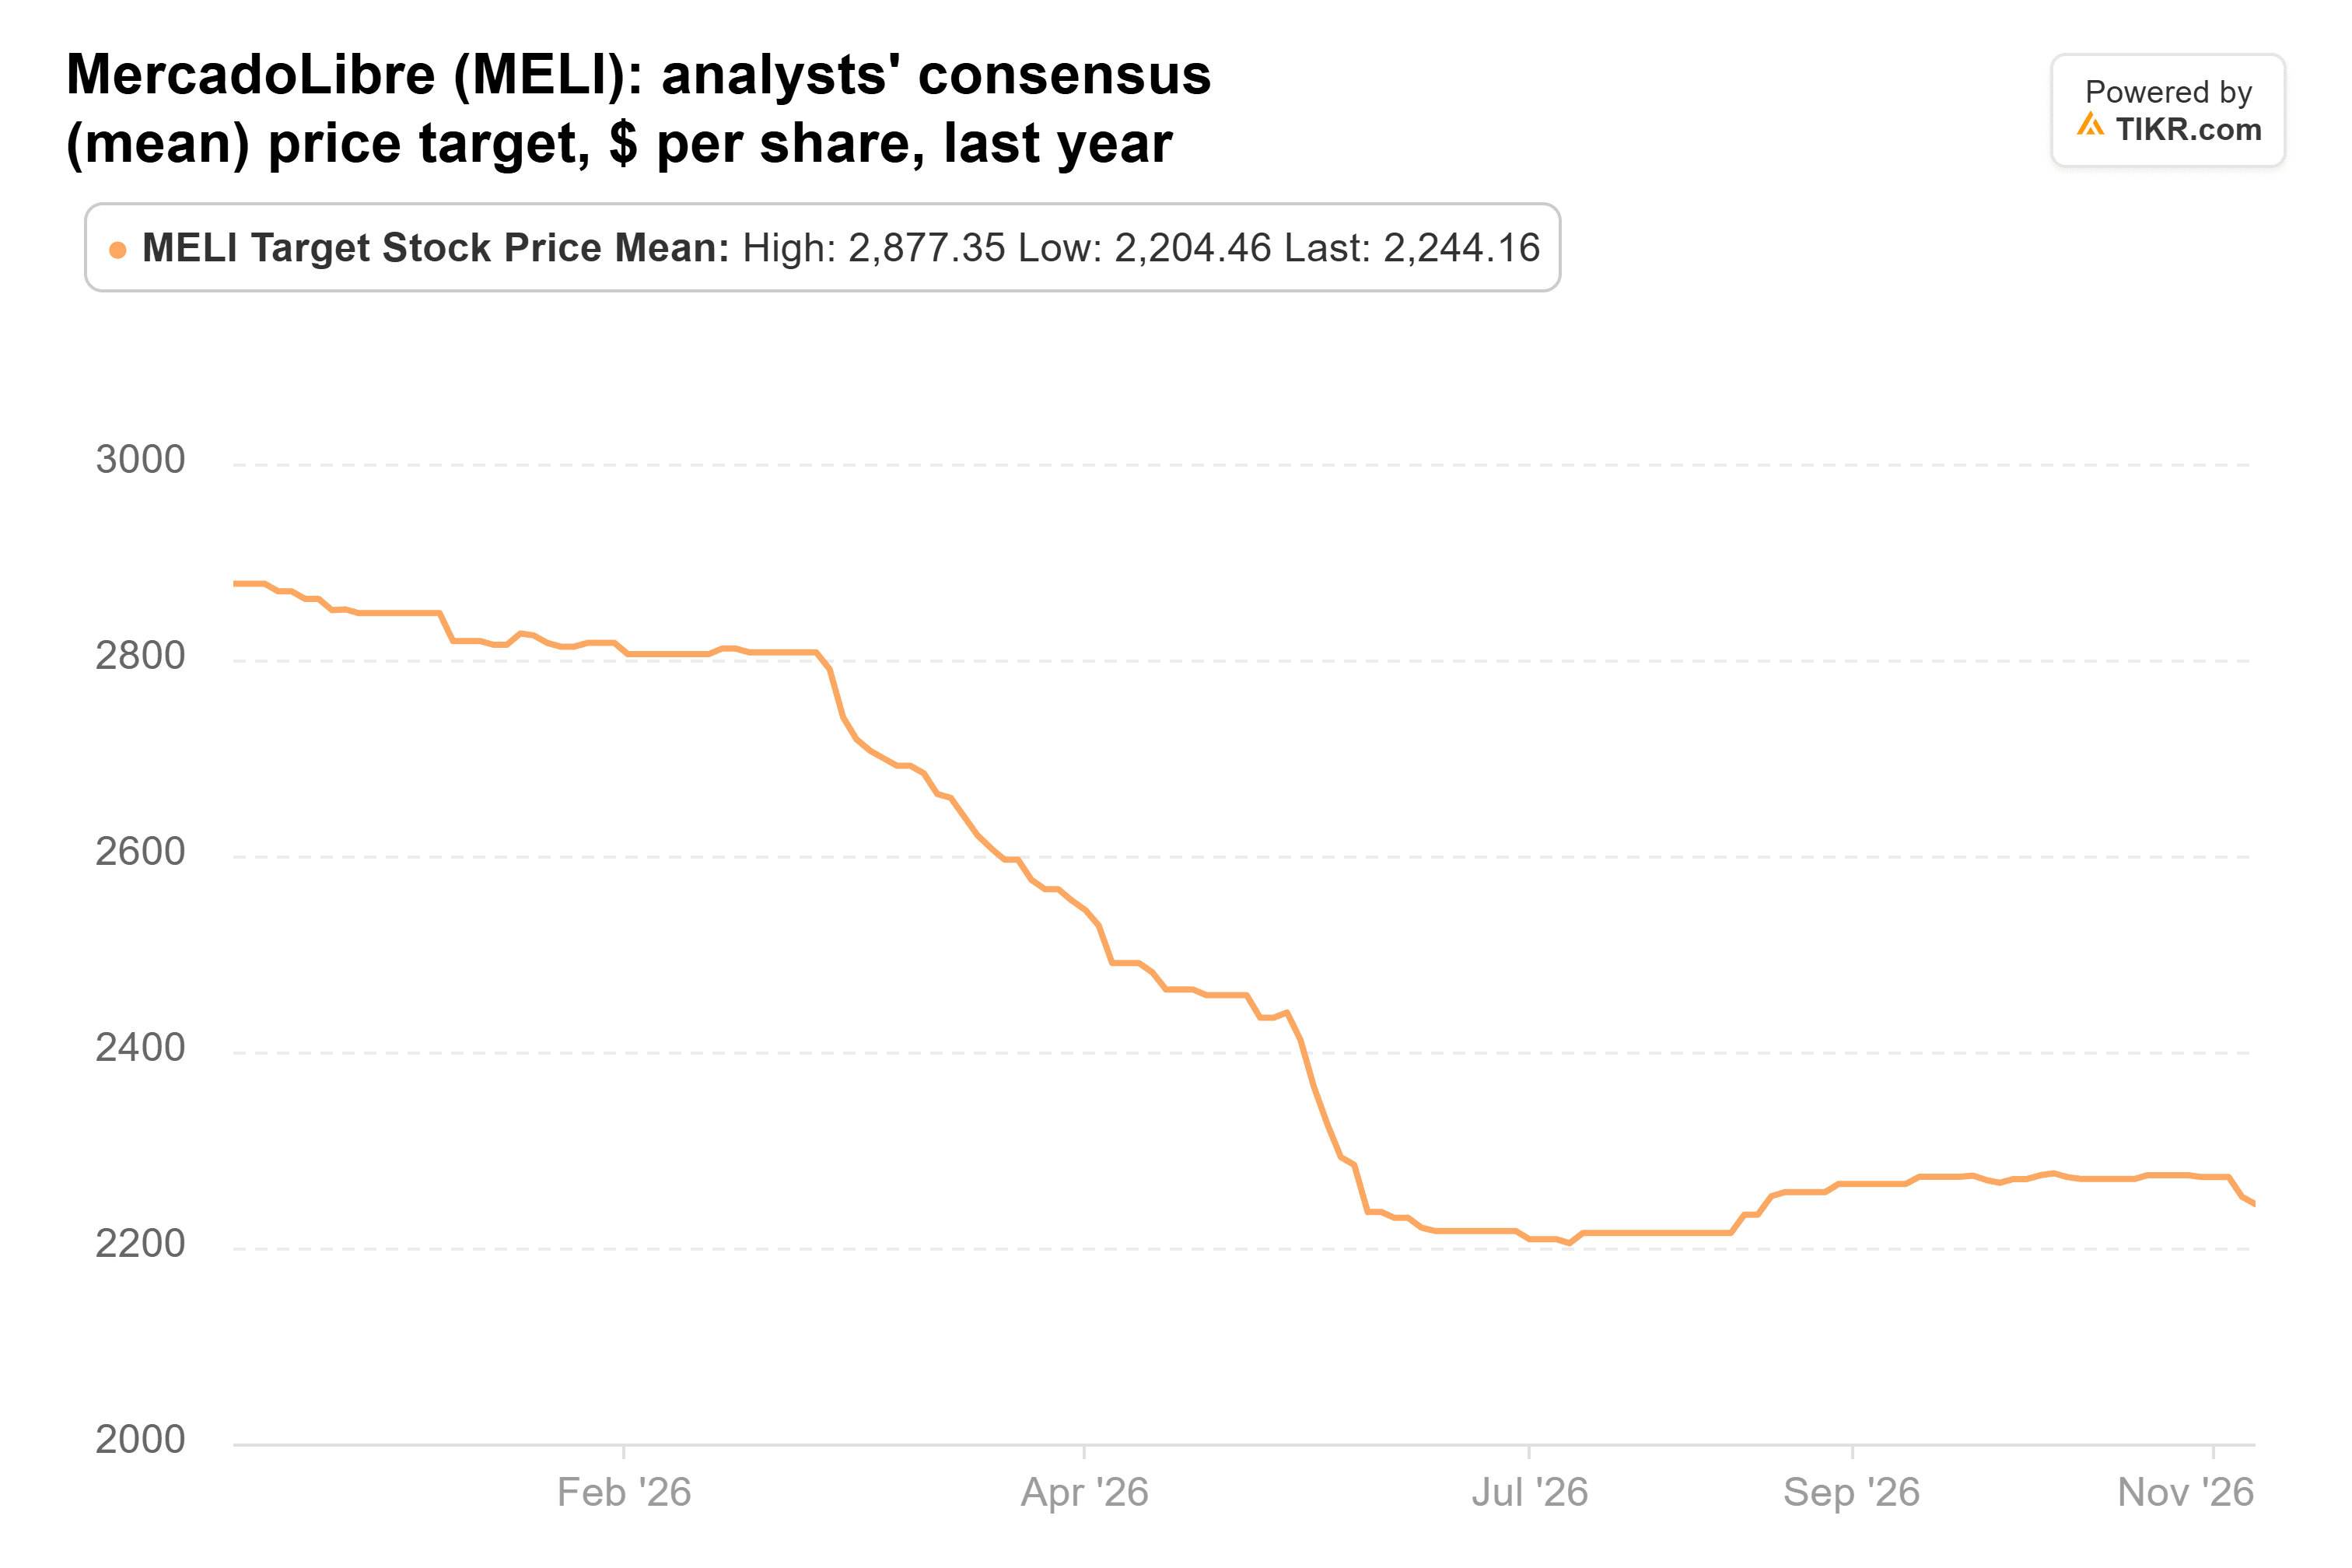
Twenty-six analysts cover the stock, with targets from $1,750 to $2,800. Their average target has fallen all year, from $2,877 a year ago:
Earnings estimates have fallen further. In September 2025, analysts expected $66.55 a share for 2026. Now they expect $37.37, below 2025’s $39.40, followed by a jump to $54.44 in 2027:
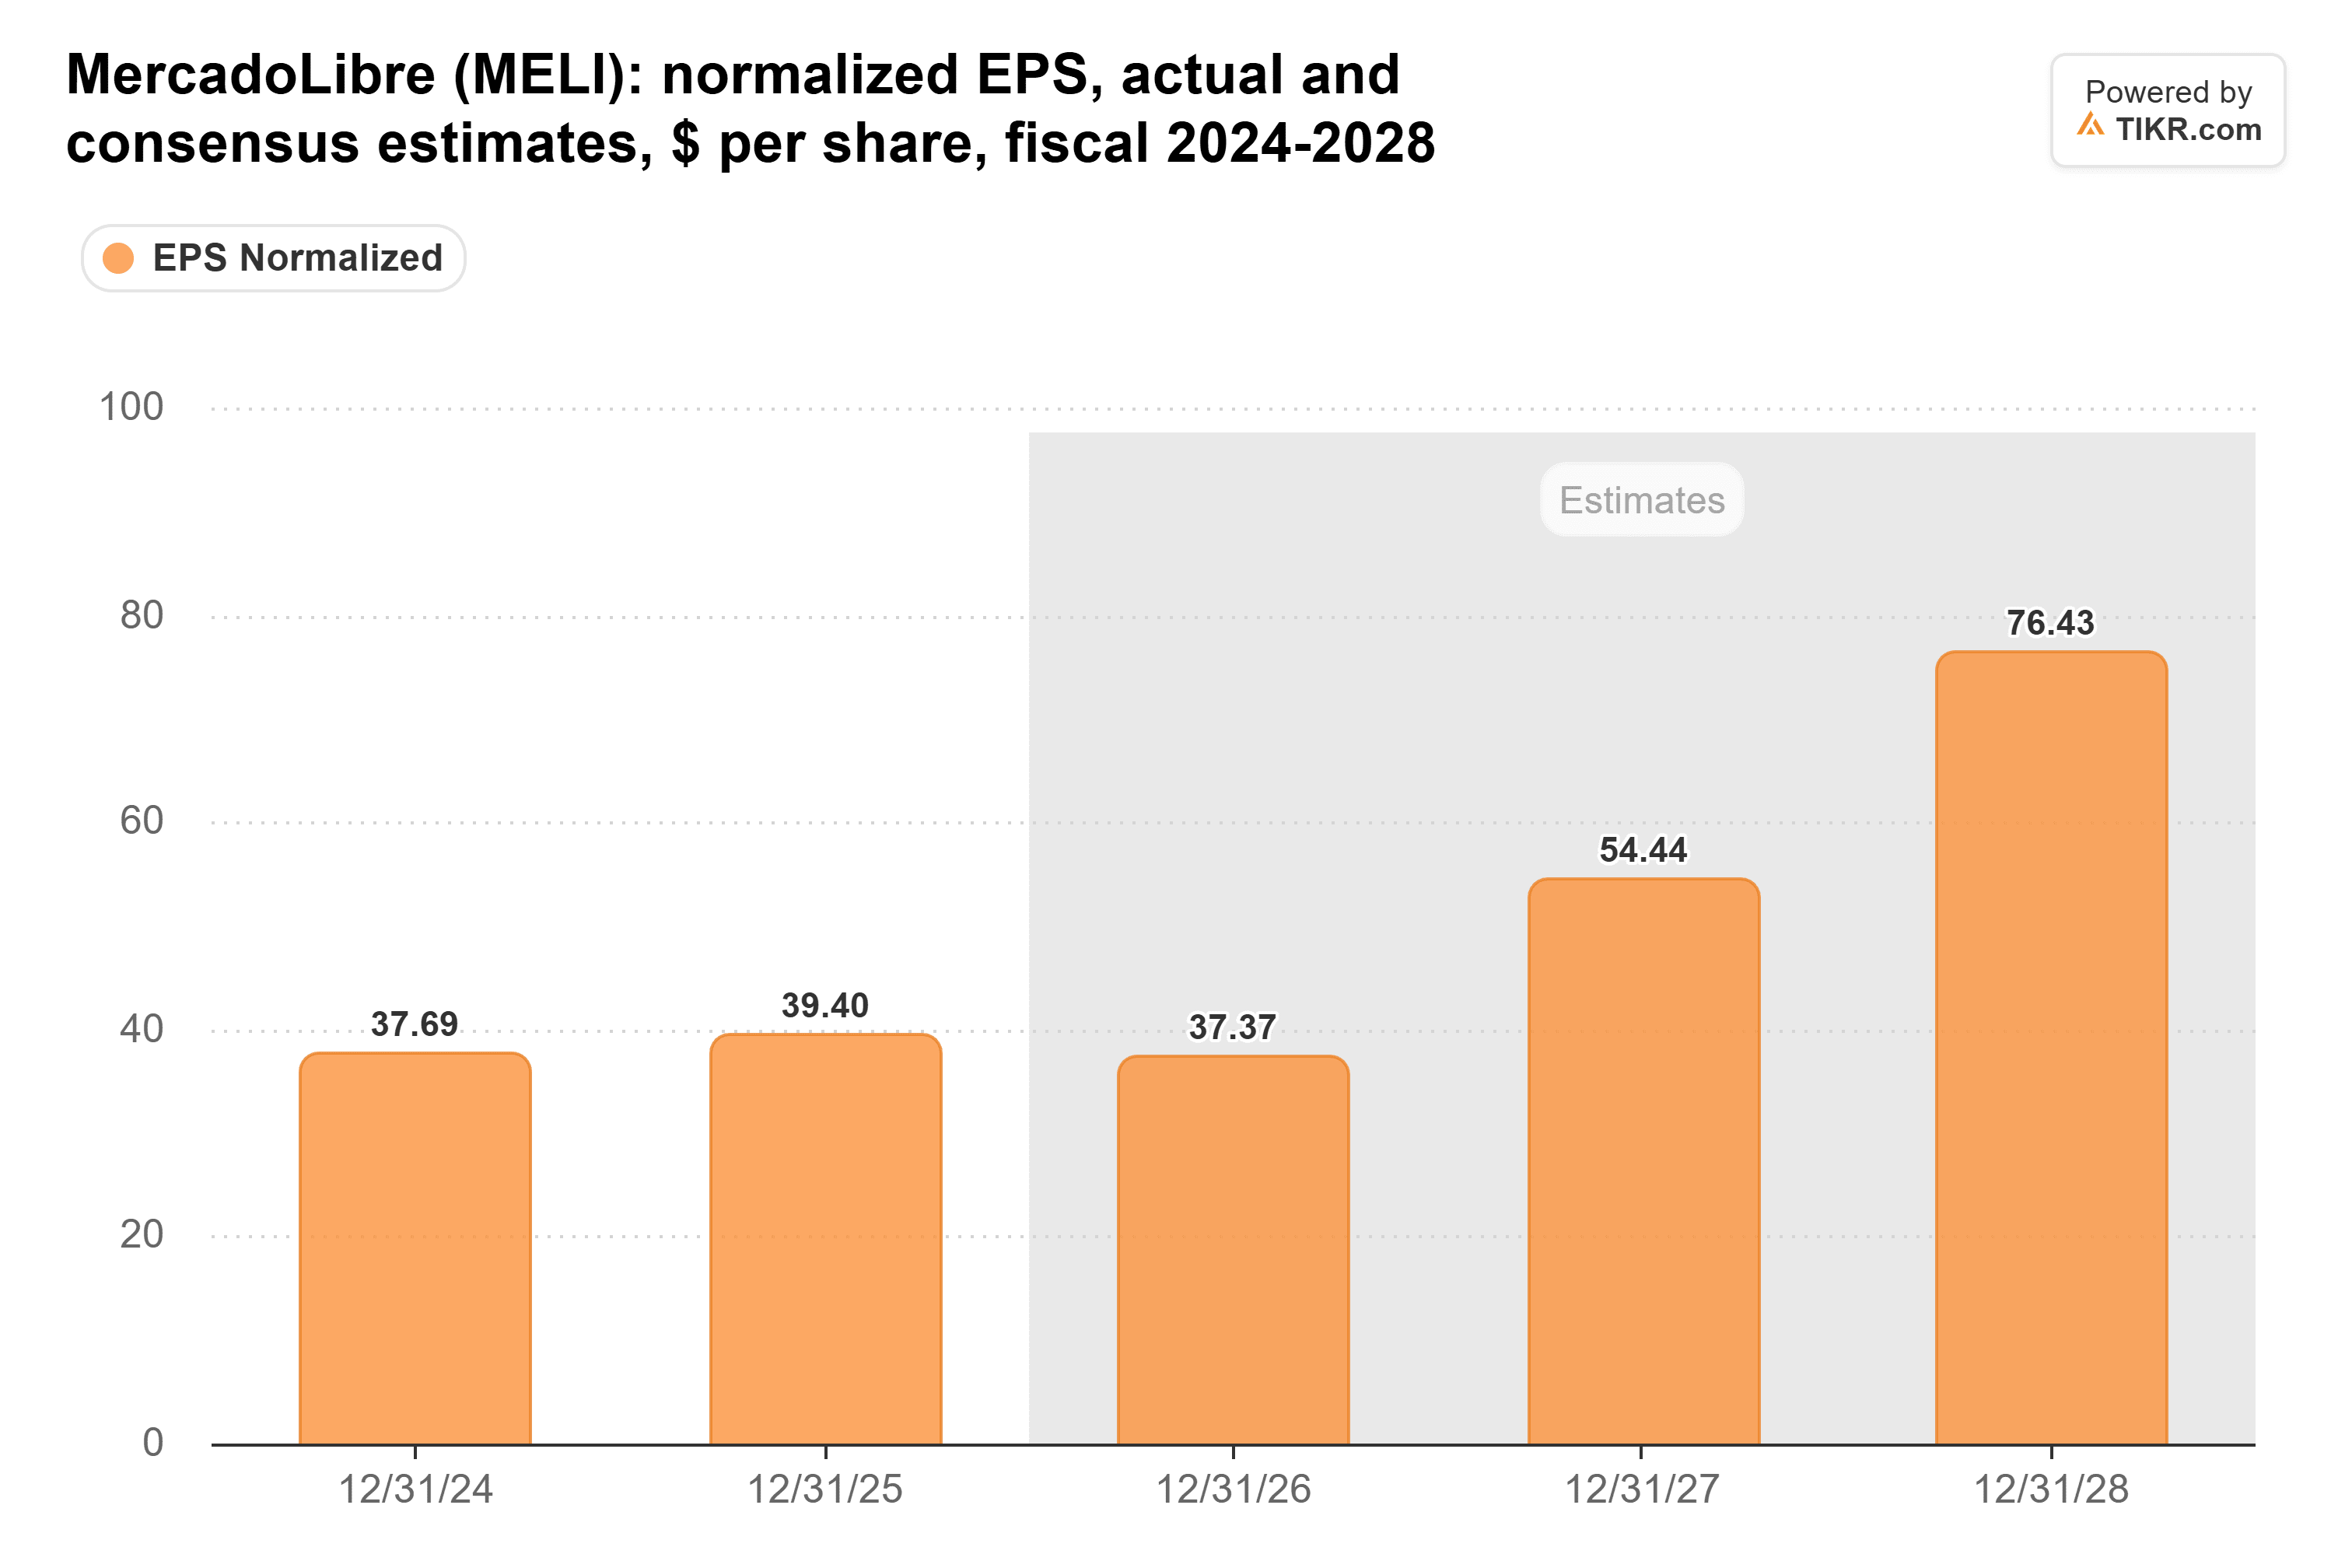
That jump depends on the margin recovery Goldman is counting on, and margins shrank again in the third quarter.
The valuation has already come down a long way. MercadoLibre trades at [33x] forward earnings, close to its five-year low of 30x in March and about half its five-year average of 62x:
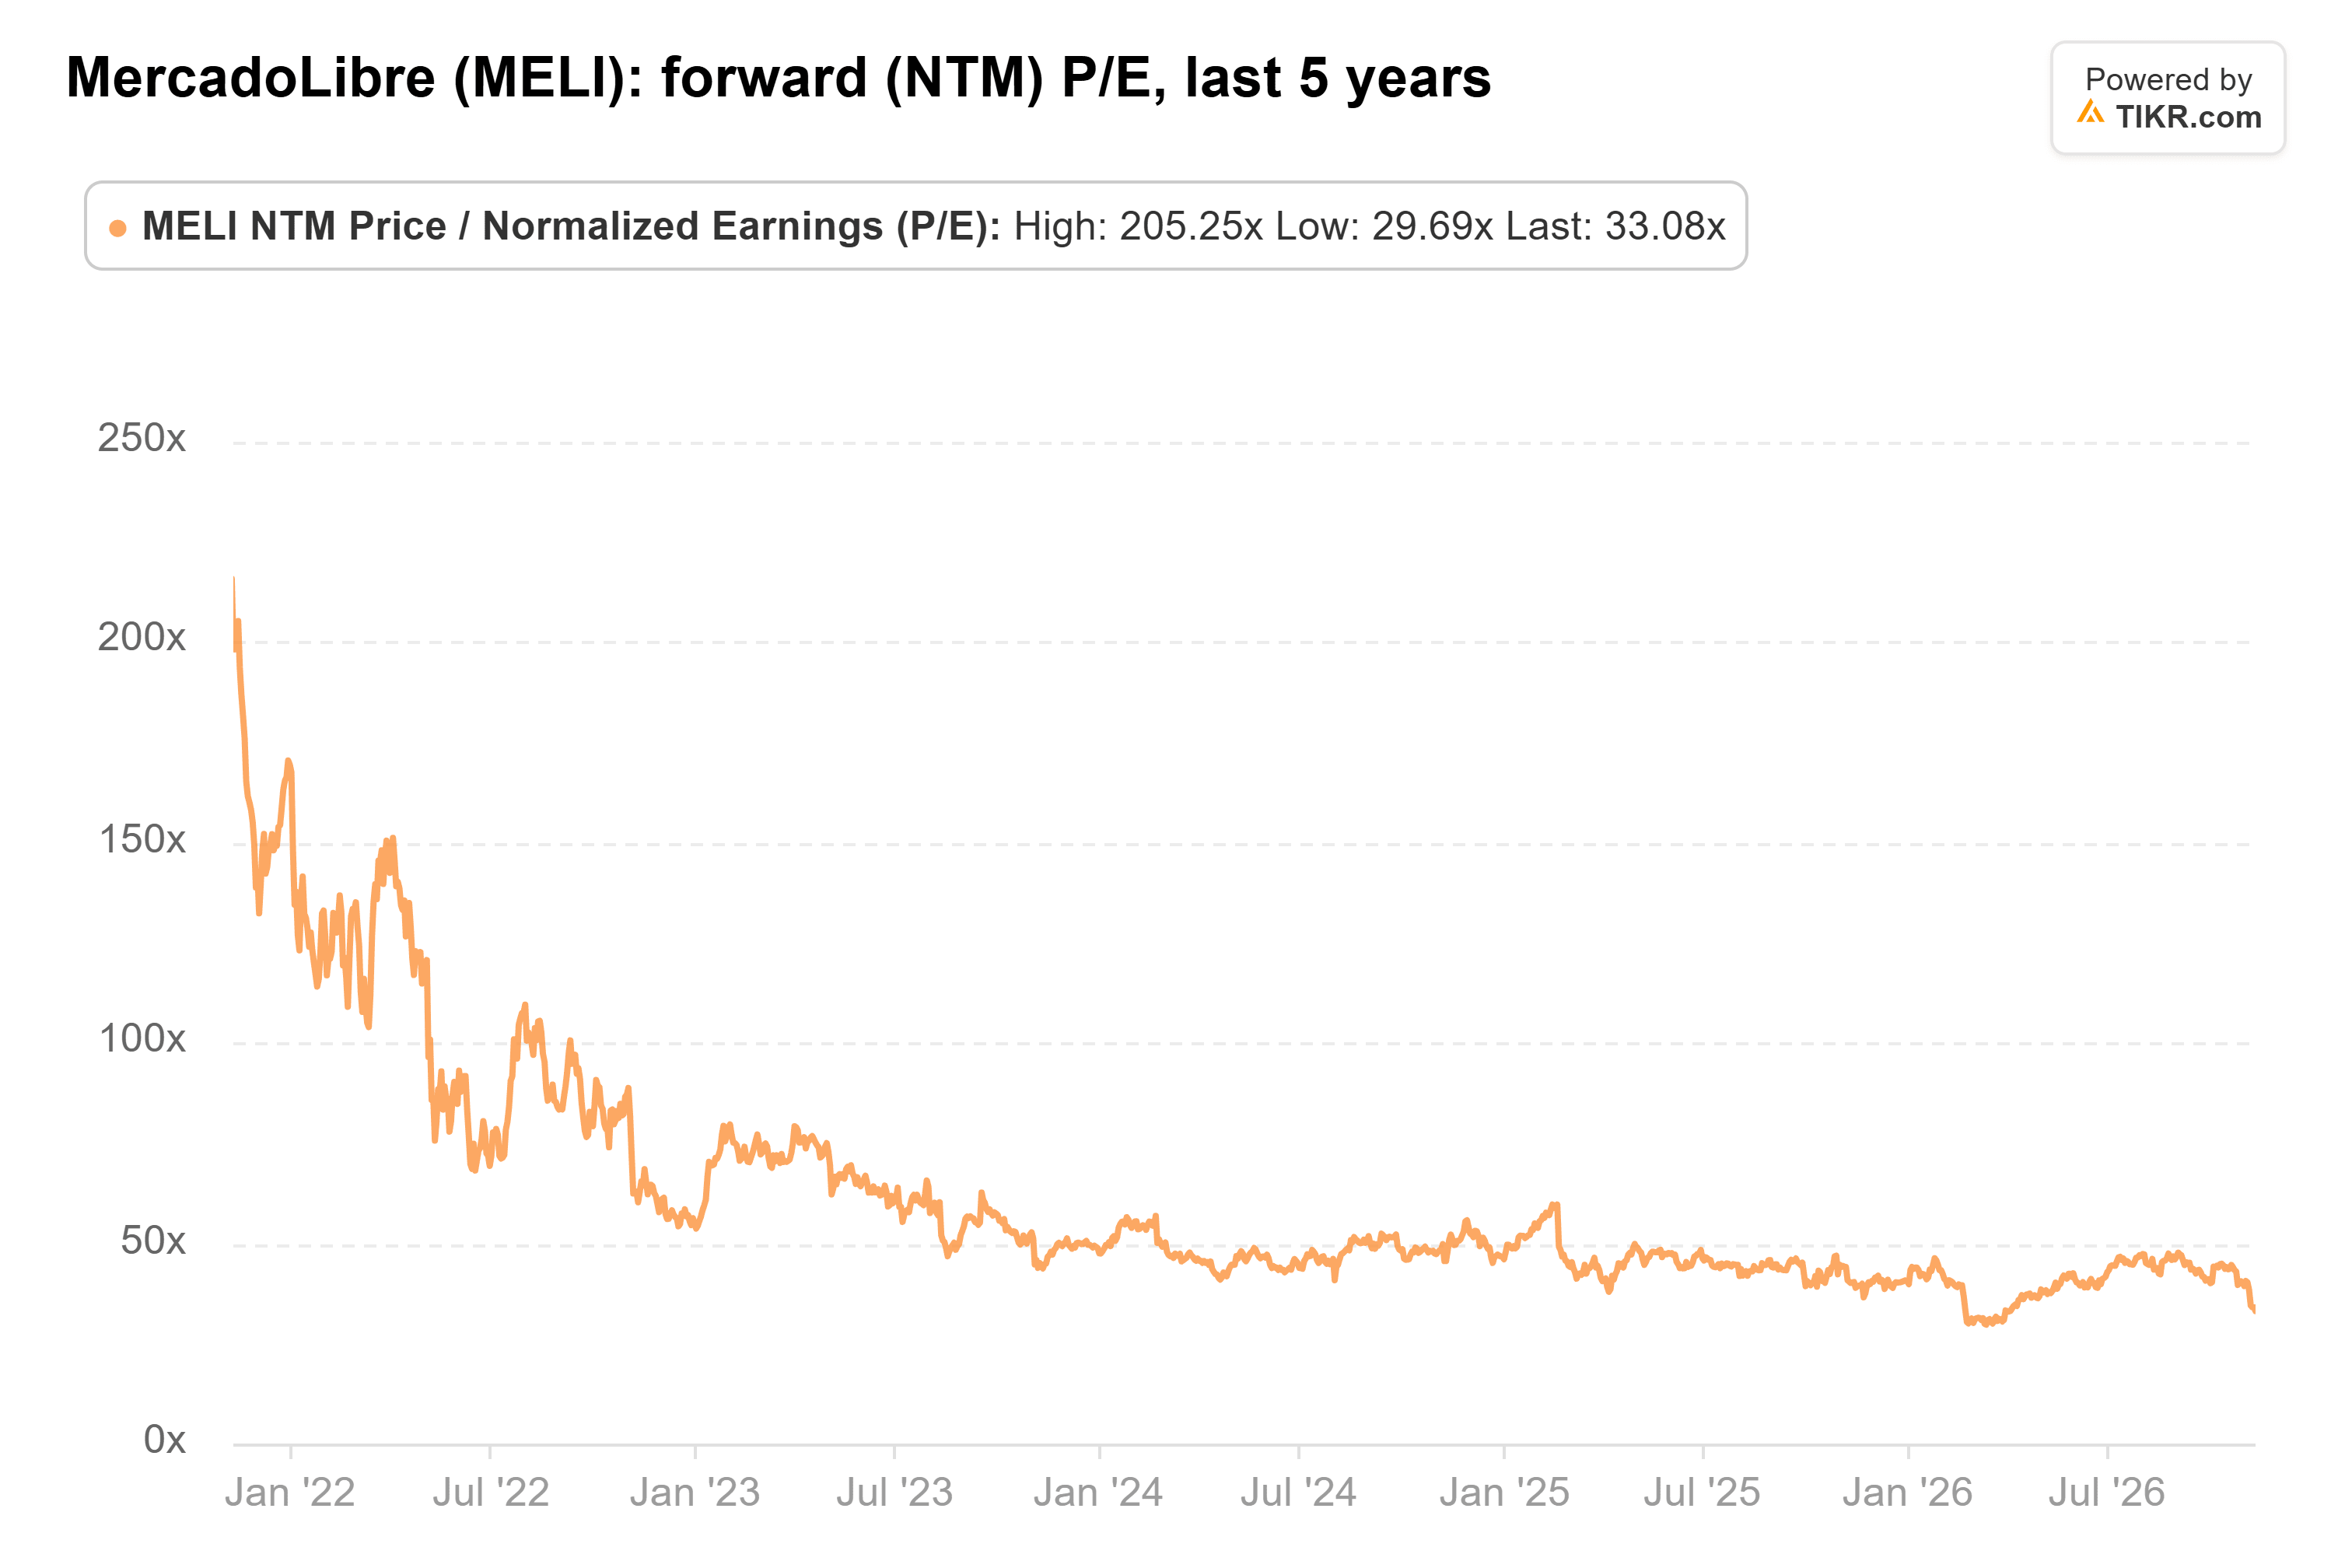
Goldman’s target works out to about 47x the $45 a share analysts expect over the next 12 months. That’s close to the 48x average of the stock’s quarter-end readings from early 2023 through this September.
A sensible target on a longer clock
The main risk is that MercadoLibre keeps putting every gain back into the business.
So $2,100 needs only the stock’s usual multiple since 2023, plus 2027 estimates that stop falling. I’d give the target closer to two years than one. Fourth-quarter results early next year will show whether this fall’s new warehouse space starts paying for itself.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!