Key Stats for CCL Stock
- Past week’s performance: Consolidating
- 52-week range: $22 to $34
- Valuation model target price: $33
- Implied upside: 45.4% over 2.2 years
Translate Carnival’s record yields into your own return estimate (It’s free) >>>
Record Results, Cautious Guidance: The Disconnect at Carnival
Carnival Corporation (CCL) has spent this year setting records, yet the stock keeps trading closer to its 52-week low than its high. In its most recent quarter, Carnival posted revenue of $6.66 billion. Adjusted net income reached $569 million, up more than 20% from a year earlier, marking its twelfth straight quarter of record net yields.
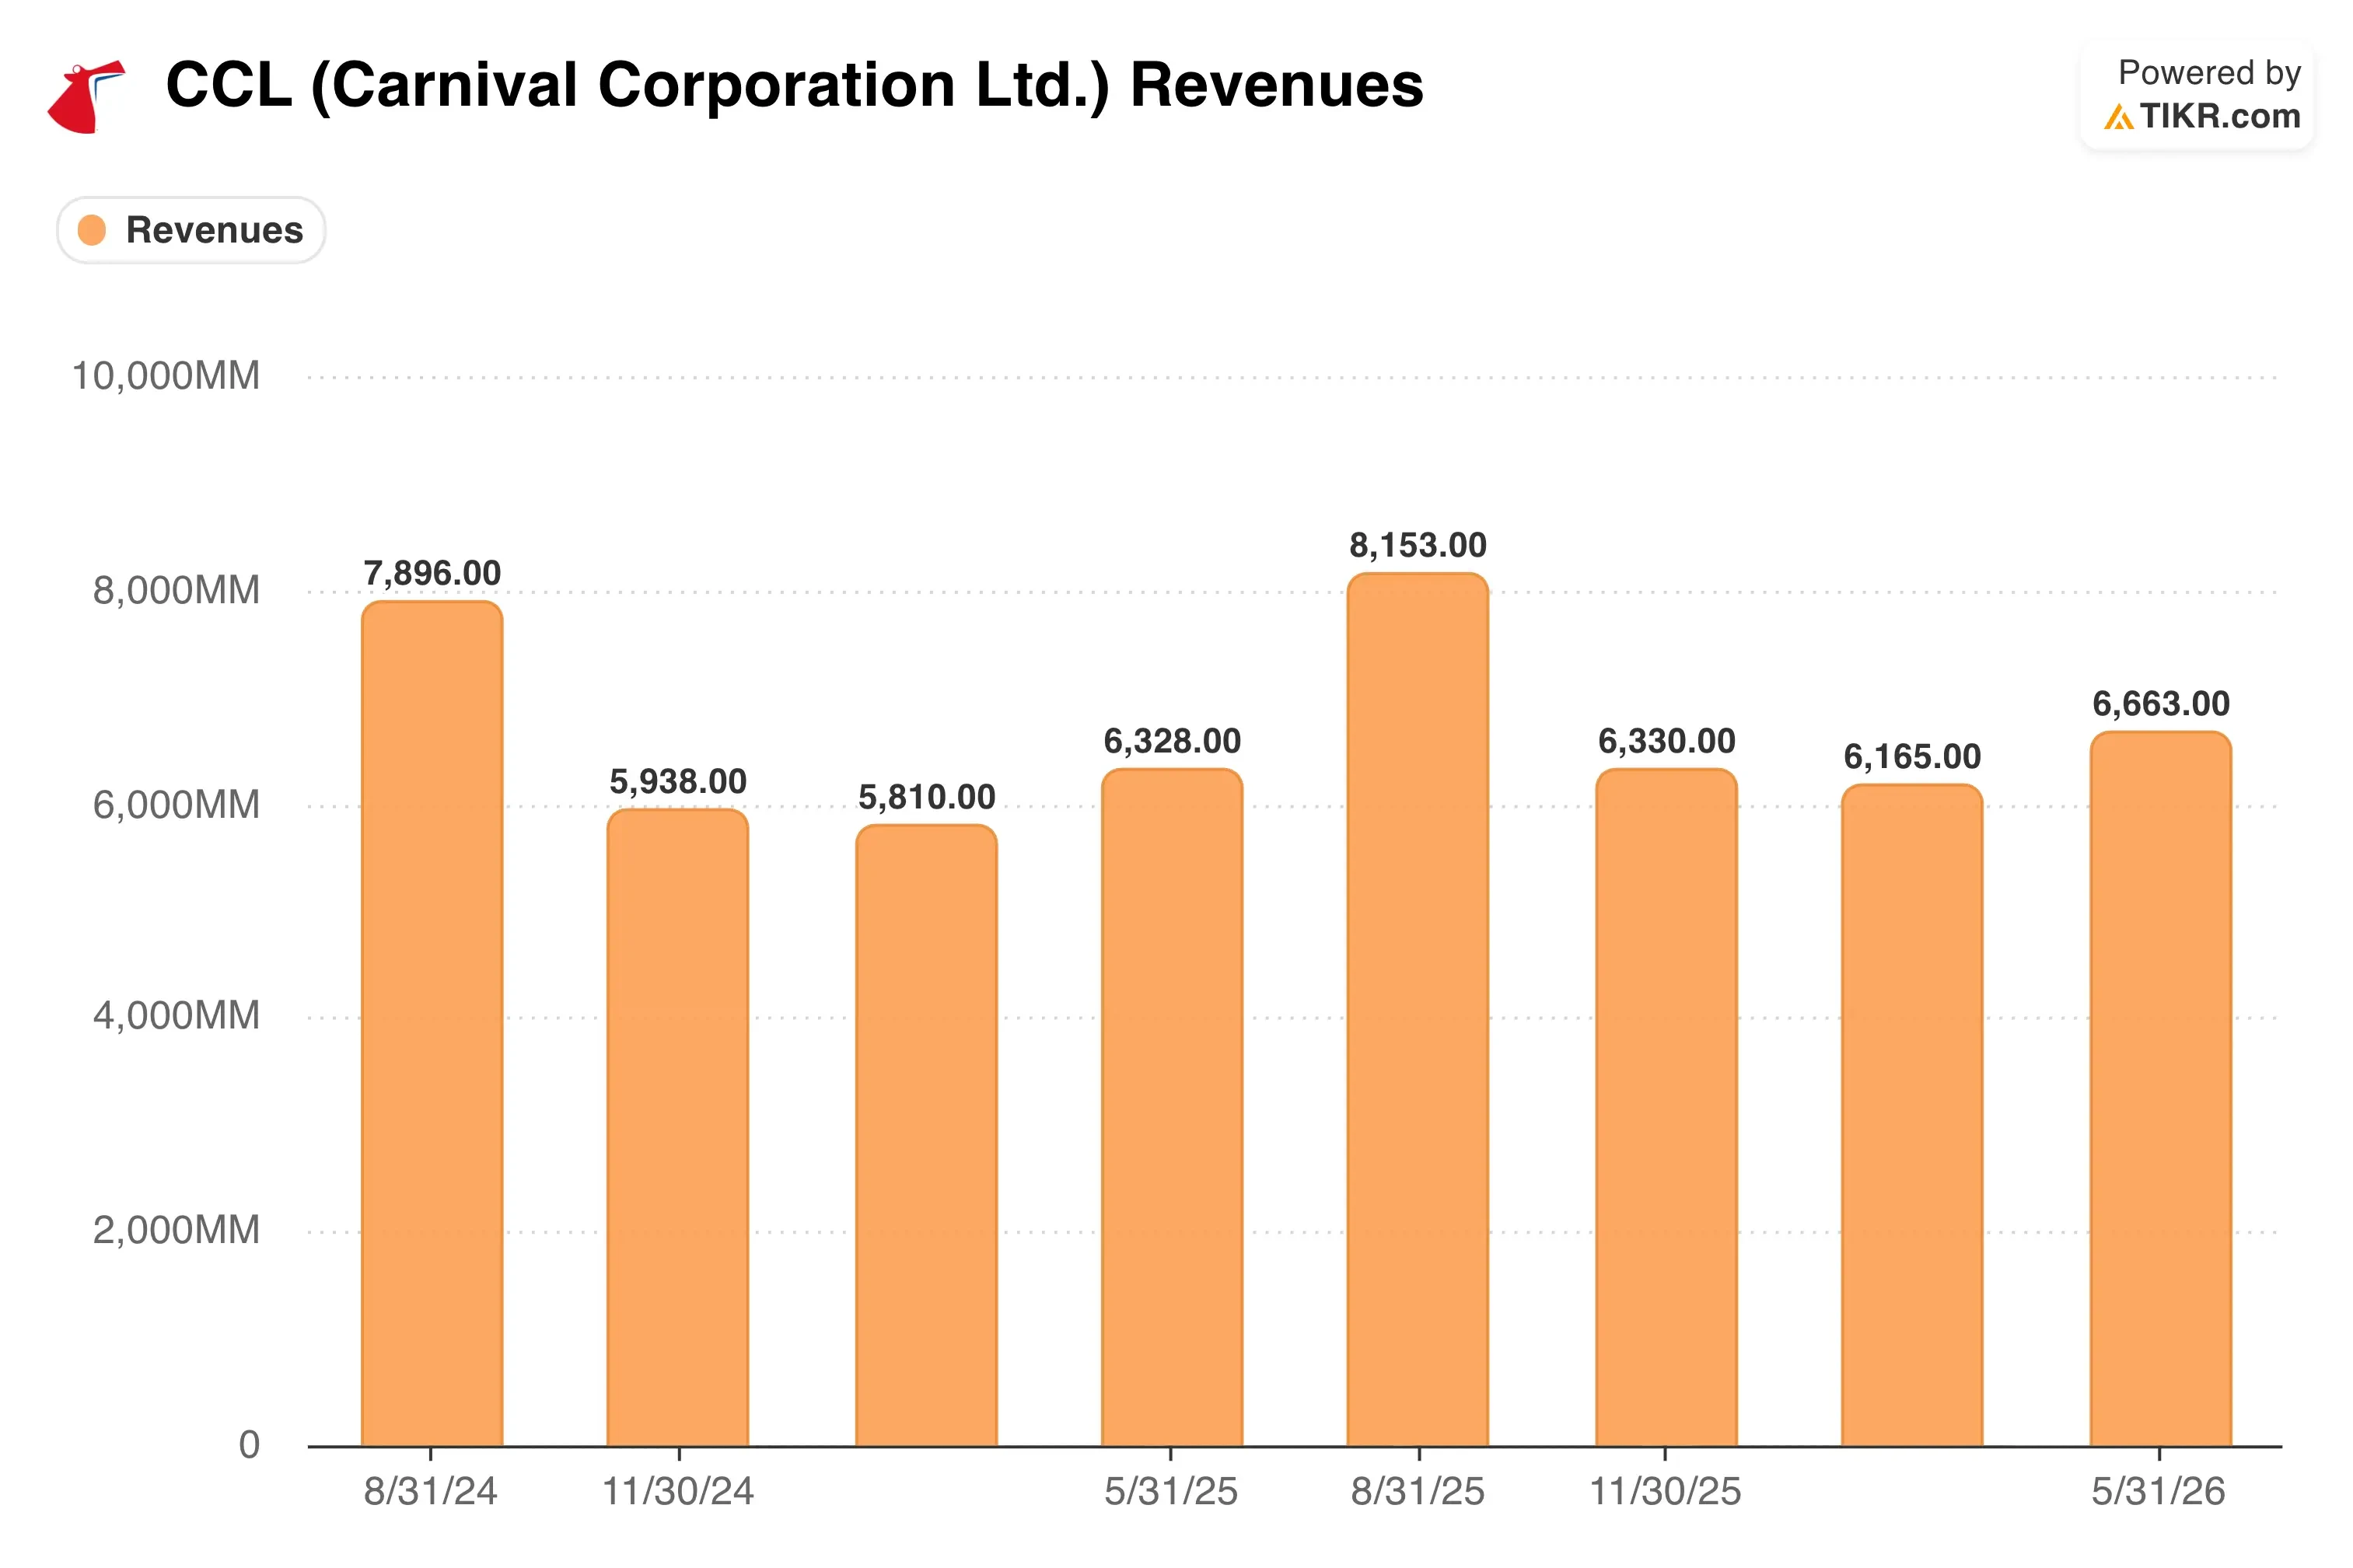
Even so, management guided Q3 profit below Wall Street estimates, citing higher fuel costs and some one-time items. Fuel prices ran nearly 30% higher year-over-year. Carnival still grew adjusted net income at a double-digit pace, showing real operating leverage even as guidance disappointed some investors.
CEO Josh Weinstein said Carnival delivered “over 20% more to the bottom line” while overcoming extreme geopolitical headwinds and higher fuel costs. He also pointed to record customer deposits of $9 billion as evidence demand remains strong. European bookings around the Mediterranean, though, have softened.
Going forward, Carnival reports its next results on September 25. That print will show whether the softer guidance was conservative positioning or an early sign of real cost pressure.
Pressure-test Carnival’s debt load against your own scenario (It’s free) >>>
A Deep Discount, or a Fair Price for Cruise Risk?

Under valuation model assumptions realized through 11/30/28, the stock is modeled using:
- Revenue Growth (CAGR): 3.9%
- Operating Margins: 16.5%
- Exit P/E Multiple: 9.7x
The model estimates a target price of $33, implying a 45.4% total return and an annualized return of 18.4% over the next 2.2 years.
Carnival’s valuation case is built on modest growth, only 3.9% revenue CAGR. It pairs that with a meaningfully lower multiple than the stock has carried in the past. A 9.7x exit P/E sits well below Carnival’s five-year average, which drives most of the projected return.

Margins tell the recovery story. A 16.5% operating-margin assumption would mark real improvement from Carnival’s pandemic-era losses. It reflects the debt paydown and cost discipline management has delivered. Fuel efficiency gains, up more than 5% this year, also support that margin path.
Against its own history, Carnival at $23 trades close to where it sat in early 2024. That holds despite growing revenue, yields, and deposits significantly since then. The gap between operational progress and share price is what makes the low multiple interesting rather than simply cheap for a reason.
The risk is leverage. Carnival still carries a heavy debt load relative to peers. A slowdown in bookings or another fuel spike would hit free cash flow faster than it would a less indebted competitor.
Line up Carnival against Royal Caribbean and Norwegian (Free with TIKR) >>>
Carnival vs. Royal Caribbean and Norwegian: Who’s Winning the Recovery
Royal Caribbean (RCL) has led the cruise recovery on profitability, trading at a much richer multiple than Carnival. Stronger margins and a cleaner balance sheet explain that gap. Norwegian Cruise Line (NCLH), the smallest of the three, has been more volatile, recently falling after Mizuho downgraded the stock to neutral on demand concerns.
On revenue growth, Carnival’s 3.9% model assumption lags what Royal Caribbean has guided for. Royal Caribbean recently lifted its own annual profit forecast even as Norwegian cut its revenue outlook the same week. That divergence shows how differently investors treat each operator despite a shared strong booking backdrop.
Carnival’s advantage is scale. As the largest cruise operator by capacity, it can spread fuel and marketing costs across more ships and brands than either rival. That scale is part of why its margins keep expanding even as its multiple stays the cheapest of the three.
What’s Driving CCL Stock Going Forward?
Carnival’s next major catalyst is its Q3 earnings report on September 25. That will reveal whether softer profit guidance holds or proves conservative. Investors will also watch booking trends for the back half of the year, especially in Europe.
On the balance sheet, Carnival redeemed $500 million of 7% notes due 2029. That move continues its effort to lower interest expense and extend its debt maturity profile. Carnival also raised its greenhouse-gas emissions-intensity reduction target to 25% by 2029, having hit its prior goal five years early. It also completed a pier extension at Celebration Key in the Bahamas that adds new itinerary capacity.
Policy could matter too. The Trump administration recently met with major travel-industry CEOs, including Carnival, to discuss boosting foreign tourism to the United States. If that translates into friendlier port policy, it could support demand for U.S.-based departures over the next few years.
Preview what Carnival’s next report could mean for its valuation (Free with TIKR) >>>
Should You Invest in Carnival?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up CCL, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track CCL alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze CCL stock on TIKR Free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!