


Key Takeaways
- Conagra cut its dividend in half in July to put more cash toward its debt, and it now yields 5.3%, against 7.3% for Kraft Heinz.
- Kraft Heinz’s dividend took 50% of its free cash flow over the twelve months to June 27, 2026, against 76% at Conagra over the twelve months to Aug. 30, 2026.
- Both businesses are shrinking: organic net sales fell 1.3% at Kraft Heinz and 1.1% at Conagra in their latest quarters, each from a year earlier.
- Conagra’s net debt is 4.1x EBITDA against a 3x target, so its pace of debt paydown is the thing to watch.
Conagra Brands (CAG) cut its dividend in half in July, from $1.40 a share in fiscal 2026 to $0.70 a year, to put more cash toward its debt. Its Sept. 30 results showed why: net leverage of 3.99x, against a 3x target.
Over at Kraft Heinz (KHC), the dividend held at $1.60 a share every year from fiscal 2020 to fiscal 2025, and it now yields 7.3%, against Conagra’s 5.3%. Kraft Heinz has troubles of its own, though, including $7.4 billion of non-cash impairments in its second quarter.
So which is the better dividend stock?
| Metric | Kraft Heinz (KHC) | Conagra (CAG) |
|---|---|---|
| Dividend yield | 7.3% | 5.3% |
| Annual dividend | $1.60 | $0.70 |
| 5-yr dividend growth | 0.0% a year (fiscal 2020–2025) | 7.6% a year (fiscal 2021–2026), before July’s cut |
| Cash dividend payout ratio (TTM) | 50% (to June 27, 2026) | 76% (to Aug. 30, 2026) |
| Net debt/EBITDA (LTM) | 2.71x | 4.13x |
| Interest coverage (EBIT/interest, LTM) | 4.93x | 3.45x |
| Forward P/E (NTM) | 11.1x | 9.3x |
Kraft Heinz is holding the line
Kraft Heinz’s dividend is well-covered, taking 50% of free cash flow over the twelve months to June 27, 2026: $1.90 billion of dividends against $3.82 billion of free cash flow.
Free cash flow fell short of the dividend from fiscal 2016 to fiscal 2018 and again in fiscal 2022, but it has covered the dividend in every other year since fiscal 2019.

Management’s priorities, from its pre-recorded second-quarter call: “Our priorities are unchanged and remain very clear, sustaining the dividend and protecting our investment-grade credit profile.” Sustaining is the right word for a dividend that hasn’t grown since fiscal 2020.
Cash is holding up better than profits. Free cash flow was $1.7 billion in the six months to June 27, 2026, up 10.3% from a year earlier. Organic net sales fell 1.3% in the second quarter, dragged down by meats and spoonables in North America, while emerging markets grew 8.5%. Management expects constant-currency adjusted operating income to fall 16% to 18% in 2026 as it lifts incremental investment to about $700 million.
The risk is that the spending doesn’t stick: Kraft Heinz names retailers’ stepped-up price investments in private label among its risks.
Conagra had to reset
Conagra was the grower of the two, with dividends per share up 7.6% a year from fiscal 2021 to fiscal 2026 (its years end in May), from $0.97 to $1.40. The cash behind them didn’t keep up. Its cash dividend payout ratio climbed from 41% in fiscal 2024 to 68% in fiscal 2026, as free cash flow fell from $1.63 billion to $979 million.
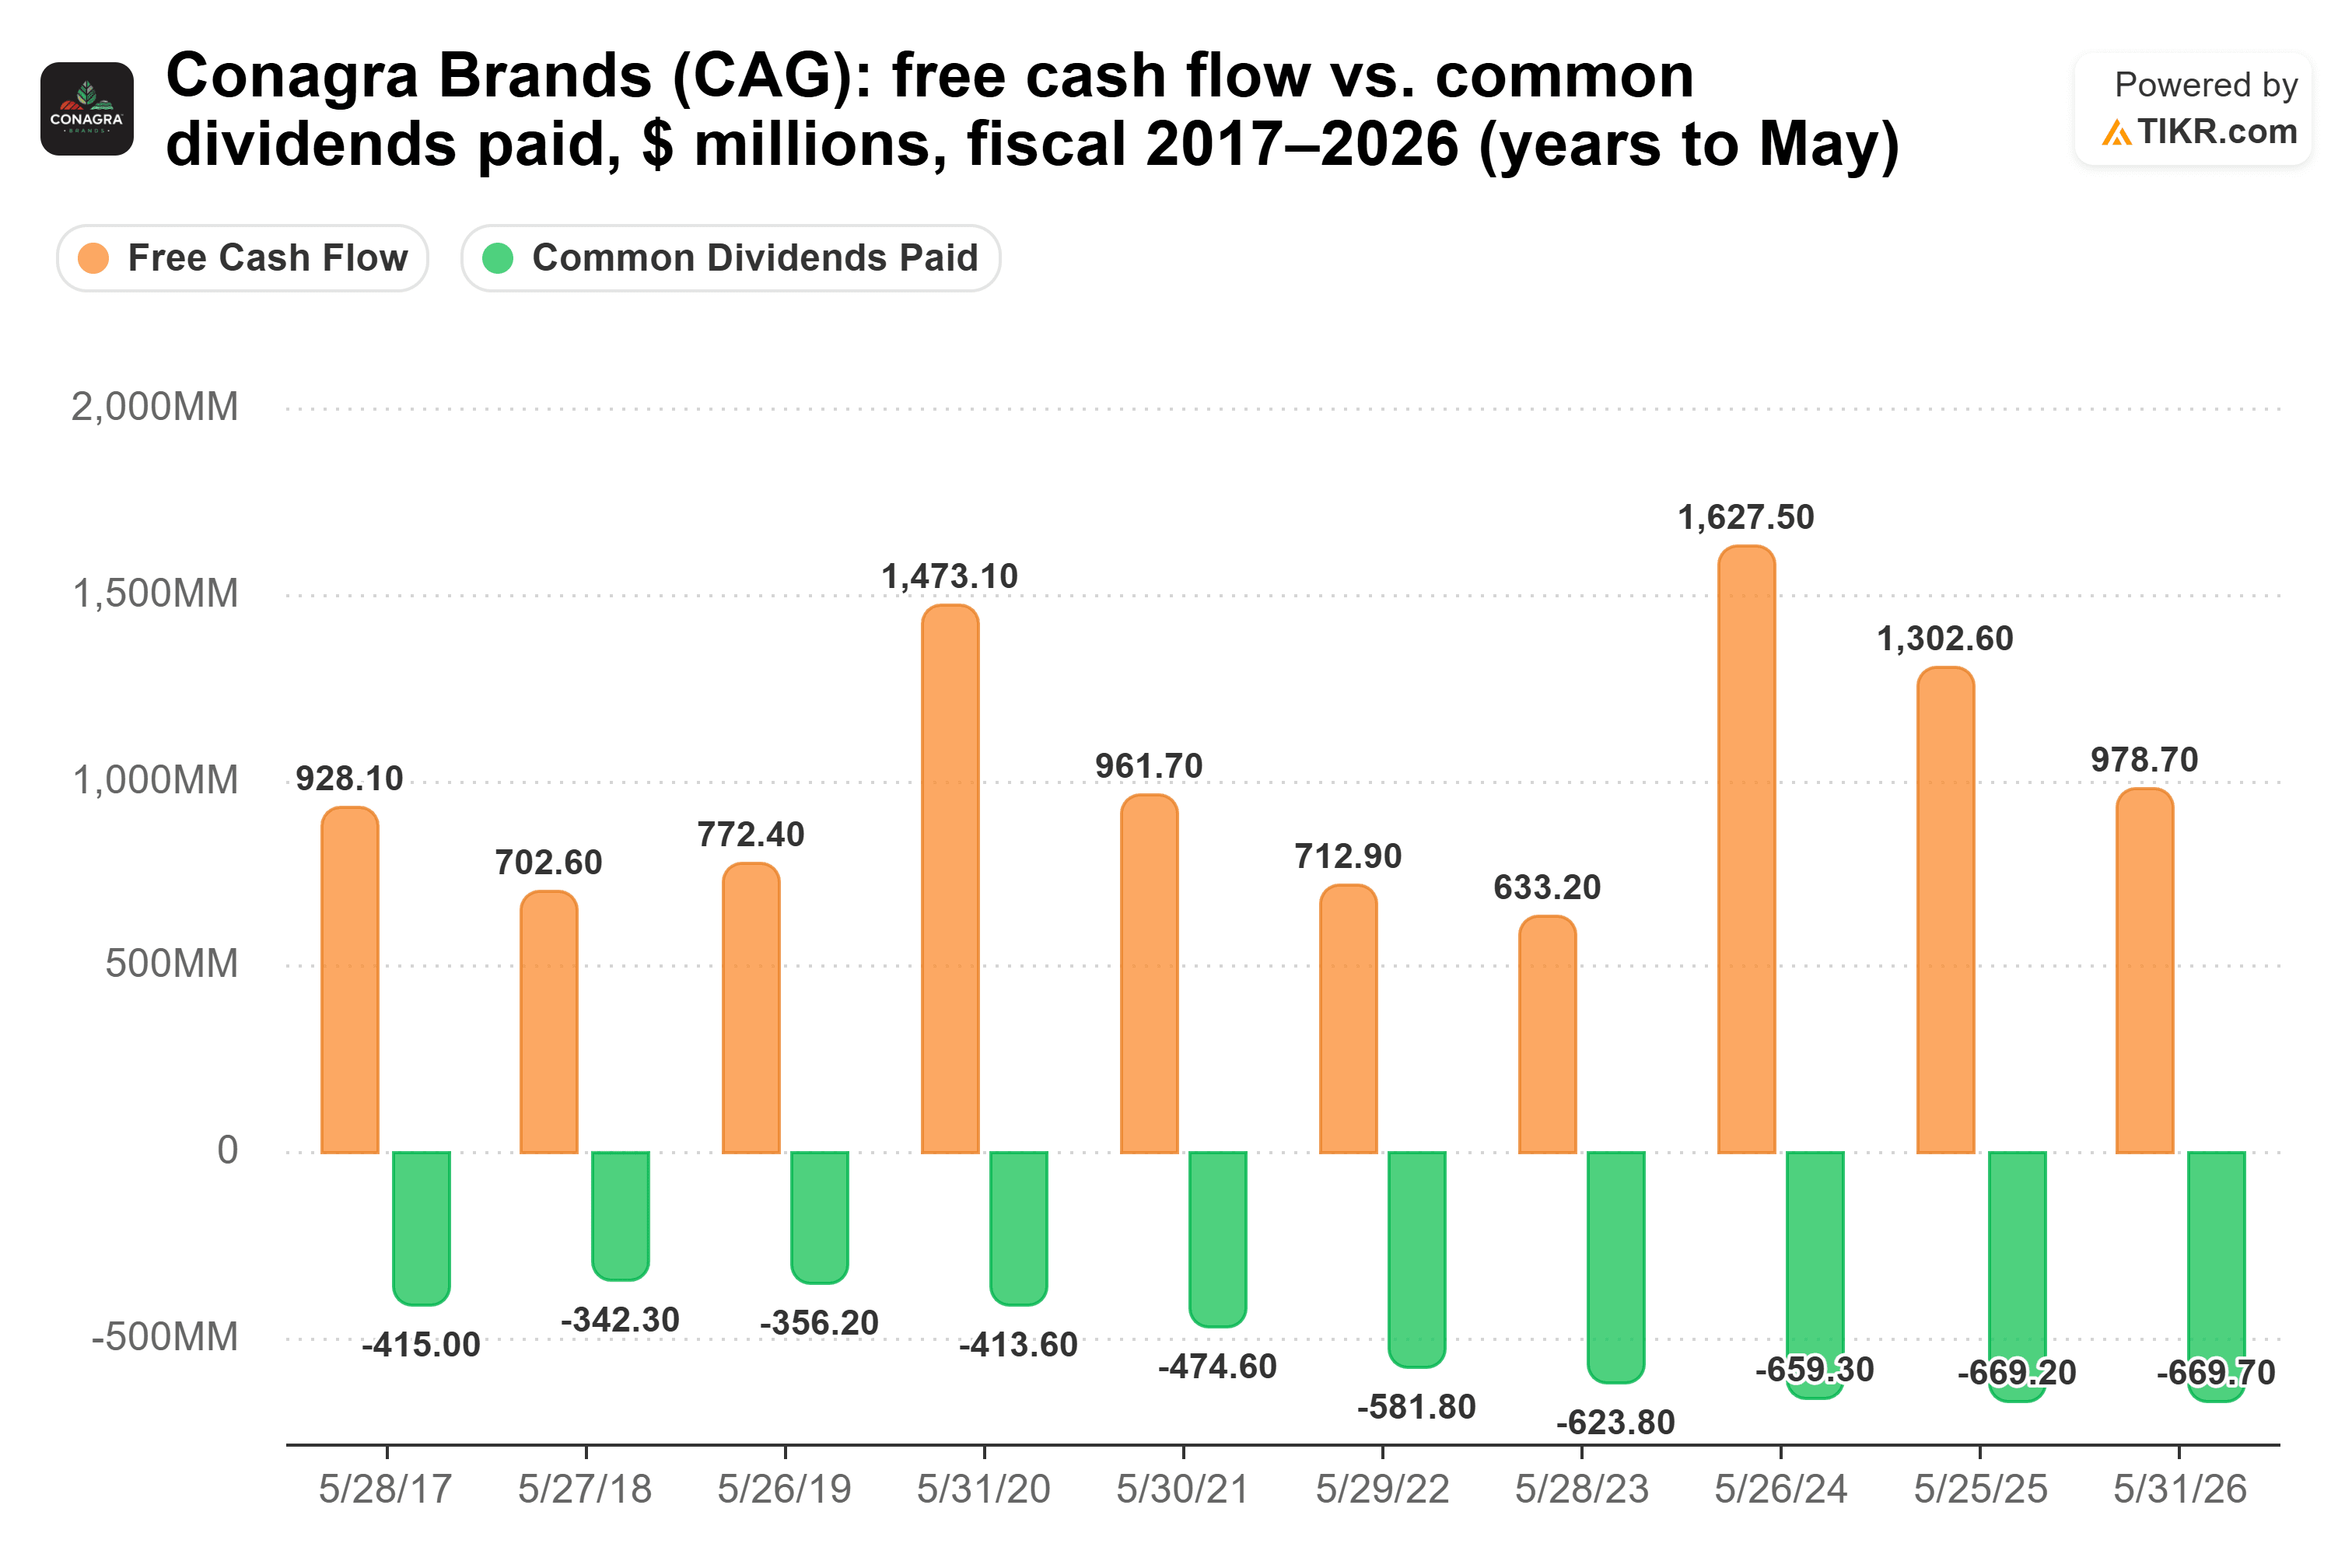
Over the twelve months to Aug. 30, 2026, the ratio was a stretched 76%, still at the old rate. (Dividends paid in the quarter to Aug. 30 were about $168 million, roughly flat with a year earlier.)
Conagra’s explanation, from its pre-recorded first-quarter call: “Finally, on capital allocation, we reset the dividend in July, increasing the cash available for debt reduction and reinforcing our path toward our target leverage ratio of 3x.”
The business is mixed. Organic net sales fell 1.1% in the quarter to Aug. 30, 2026, from a year earlier. Foodservice grew 3.3%, while Grocery & Snacks fell 2.0% as price increases cost it volume. Adjusted EPS still rose 5.1% to $0.41. For fiscal 2027, management guides organic net sales down 1% to 3% and net leverage of about 4.0x at year-end, roughly where it is now.
So which dividend wins?
Kraft Heinz is the better dividend stock. It pays the bigger check, at 7.3% against 5.3%. It covers that check with more room, at 50% of free cash flow against 76%. And it carries less debt, at 2.71x EBITDA against 4.13x.
Conagra’s growth record can’t close that gap after a cut. At each dividend’s pace now, $10,000 pays $730 a year from Kraft Heinz and $530 from Conagra, and about the same in year 10, so Conagra’s income never catches up. Its leverage has also stayed near 4x EBITDA, from 4.4x in fiscal 2022 to 4.0x in fiscal 2026, well above that 3x target.
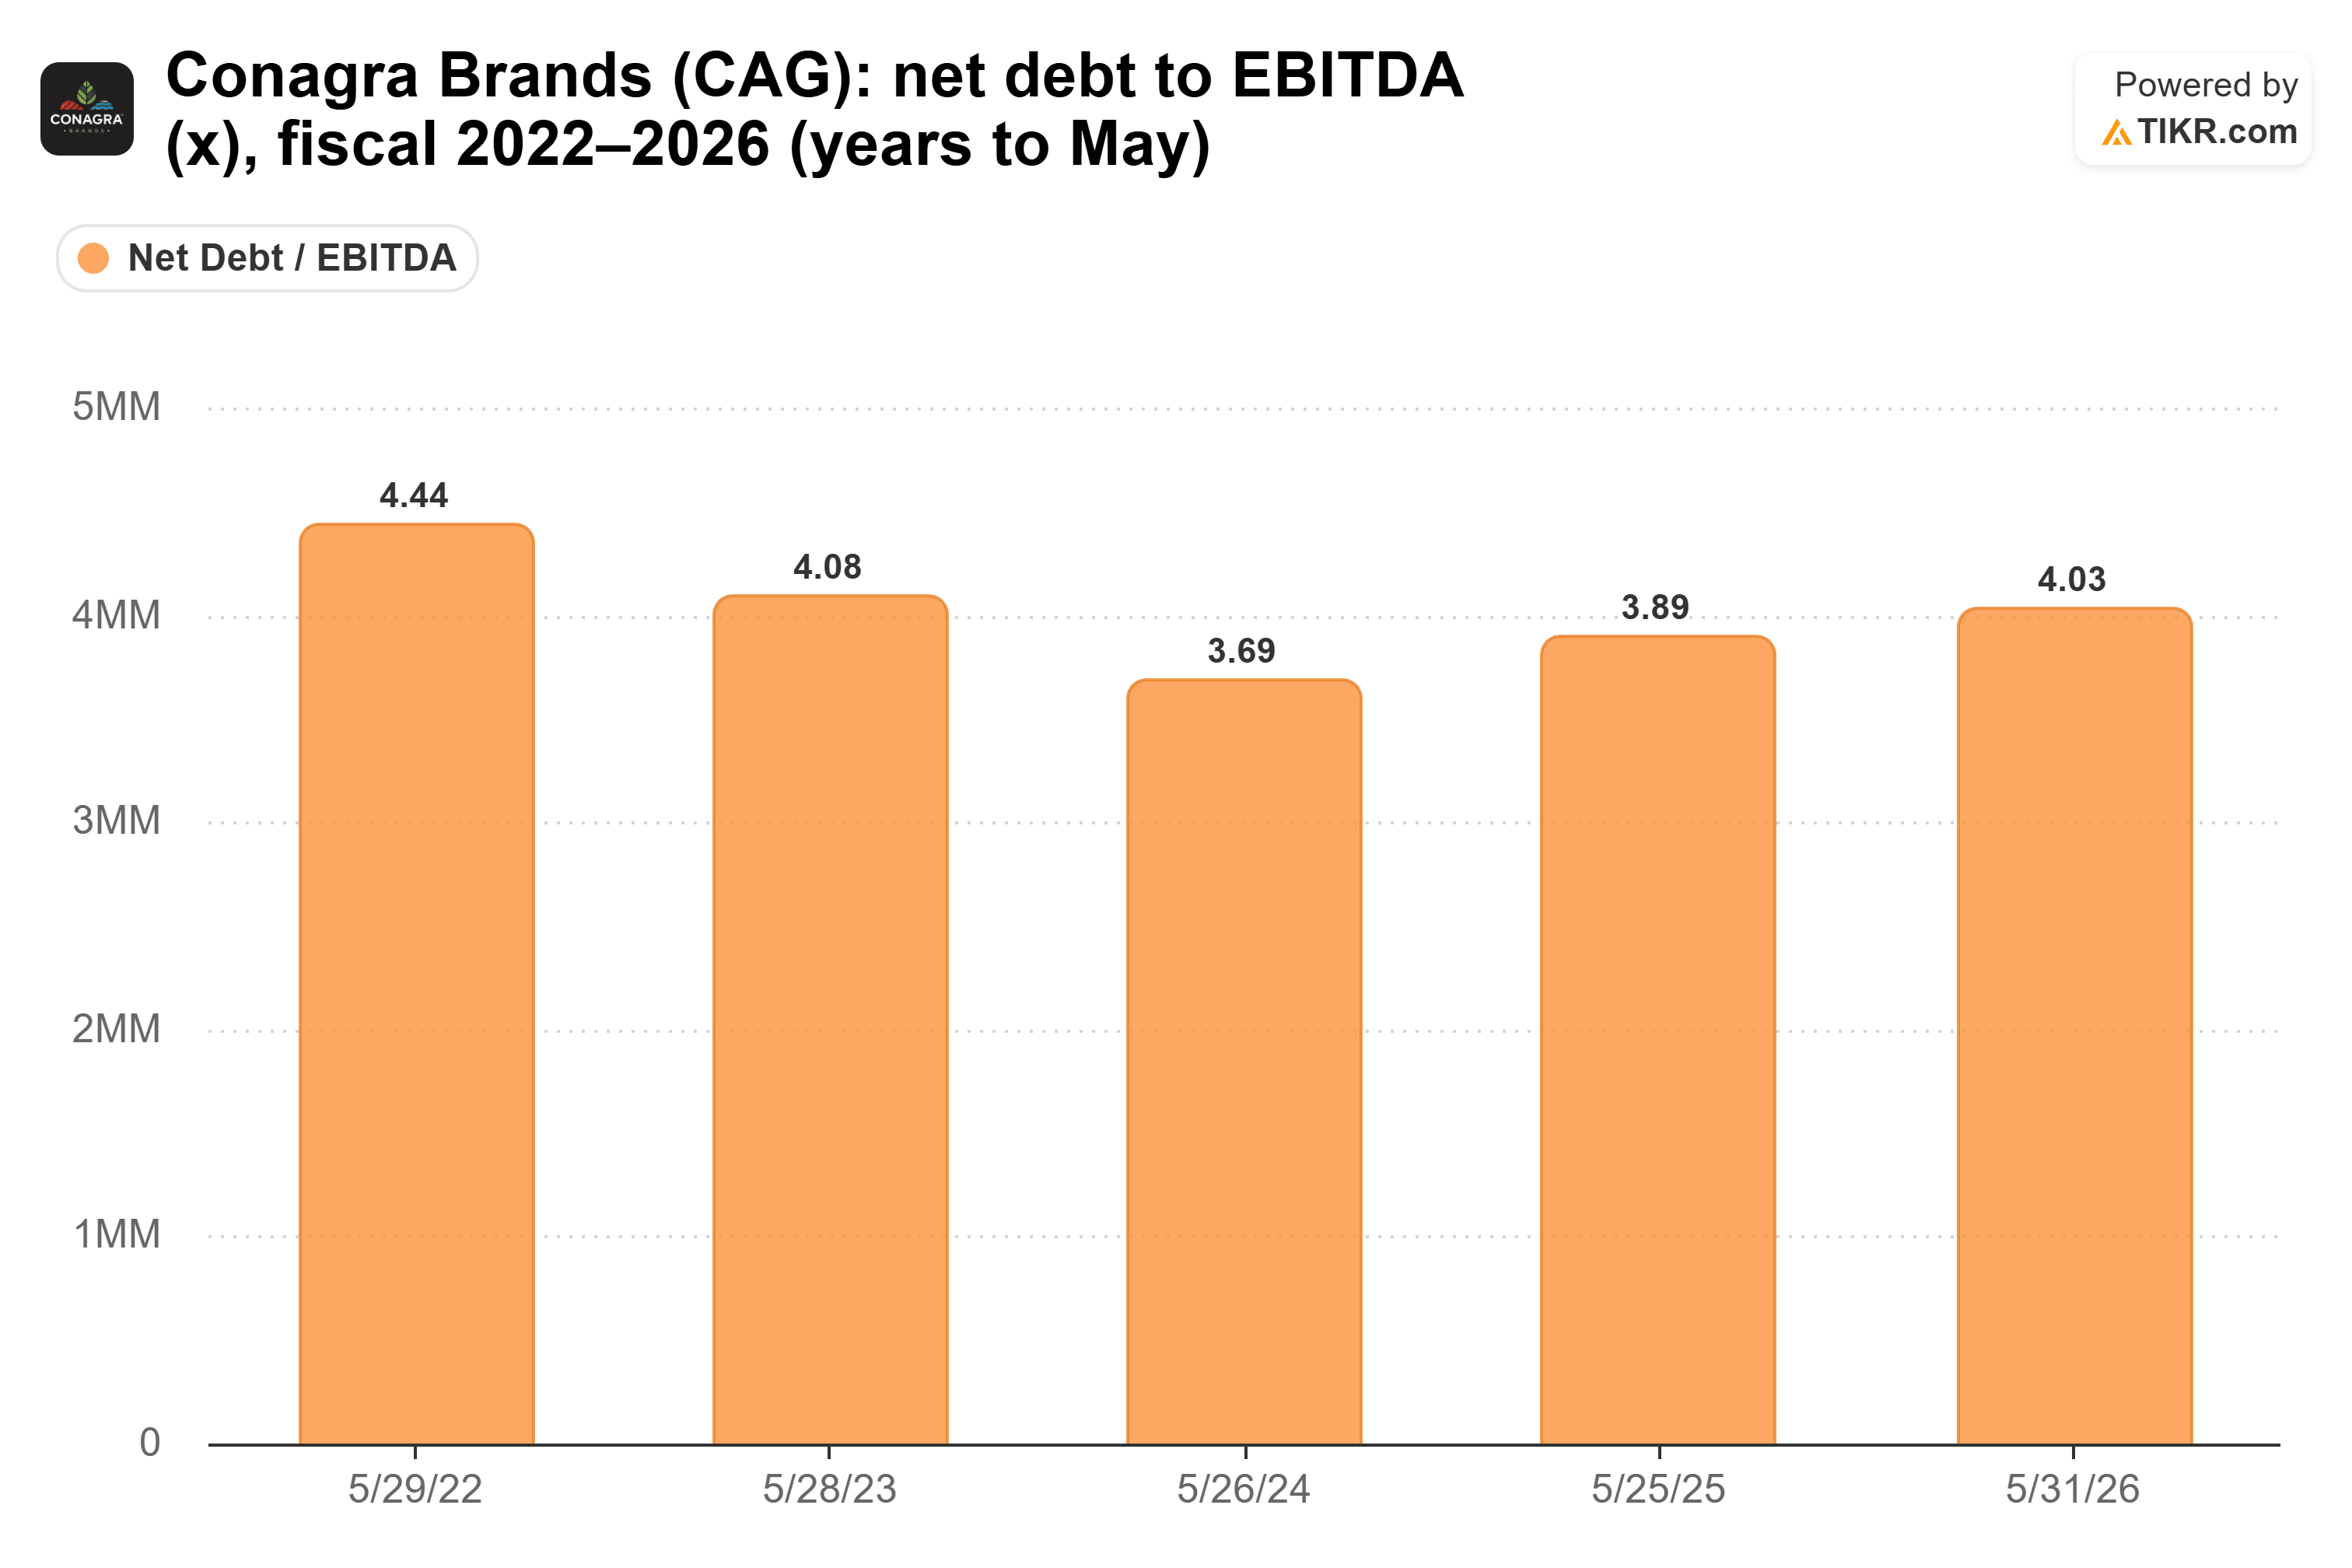
Conagra’s case is real. It’s cheaper, at 9.3x forward earnings against 11.1x. Its adjusted EPS grew in its latest quarter, while Kraft Heinz’s fell 18.8% in its own. And the reset frees up cash for debt. CFO David Marberger: “Our target is 3x. We are maniacally focused on getting there as soon as possible.”
It’s just that, for income, I’d rather own the dividend management puts first than the one it just halved.
Of course, Kraft Heinz’s profits are still falling, and its third-quarter results will show whether the extra investment is starting to pay off.
So what is Kraft Heinz stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Kraft Heinz could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


