


Key Takeaways
- Bessemer Venture Partners’ Sameer Dholakia said Waymo can become a trillion-dollar business, about 8x the $126 billion valuation from its February funding round.
- Alphabet trades at 25.0x forward earnings, close to its usual range, so the market isn’t paying for a Waymo anywhere near that size.
- Waymo’s revenue is tiny for now: Sacra estimates $355 million annualized in February, against Alphabet’s $403 billion of revenue in 2025.
- Telecom analyst Walter Piecyk says the threat from Waymo and Tesla’s Robotaxi is what holds Uber’s stock where it is.
Alphabet (GOOG) might own a trillion-dollar business that barely shows up in its numbers.
That’s the view of Bessemer Venture Partners’ Sameer Dholakia. On a recent episode of the 20VC podcast, he laid out where Waymo goes after ride-hailing:
“But when you take that same technology and capability and apply it to personal car ownership and then apply it to trucking and then apply it to logistics, Waymo is going to be an extraordinary, I think, a trillion-dollar business. Easy.”
“Easy” is a strong word for businesses Waymo hasn’t started yet.
One thing to know up front: Bessemer was one of the investors in Waymo’s $16 billion round in February, which valued the company at $126 billion. So Dholakia’s firm owns a piece of the company he’s talking about.
The math on “easy”
A trillion dollars is about 8x that February valuation. Alphabet’s whole market value was $4.17 trillion on Oct. 16, so Dholakia sees Waymo growing to roughly a quarter of today’s Alphabet.
Ride-hailing comes first. “They’re focused on ride-hailing. They’re crushing it,” Dholakia said. Waymo reached 500,000 paid rides a week in March, ten times its pace in May 2024.
The bigger prize is selling the driver itself. Dholakia said he’d pay a monthly subscription for a Waymo driver on his family’s next car, the way Tesla (TSLA) owners pay for FSD: “I think Waymo has the opportunity to do that for every other OEM on the planet.”
He’s upfront that it’s “not their near-term focus.” Trucking and logistics are even further out.
Alphabet isn’t priced for it
You won’t find much of that in Alphabet’s multiple. The stock trades at 25.0x forward earnings. That’s a bit above its five-year average of 22.6x and well below the 32.7x it reached in April…
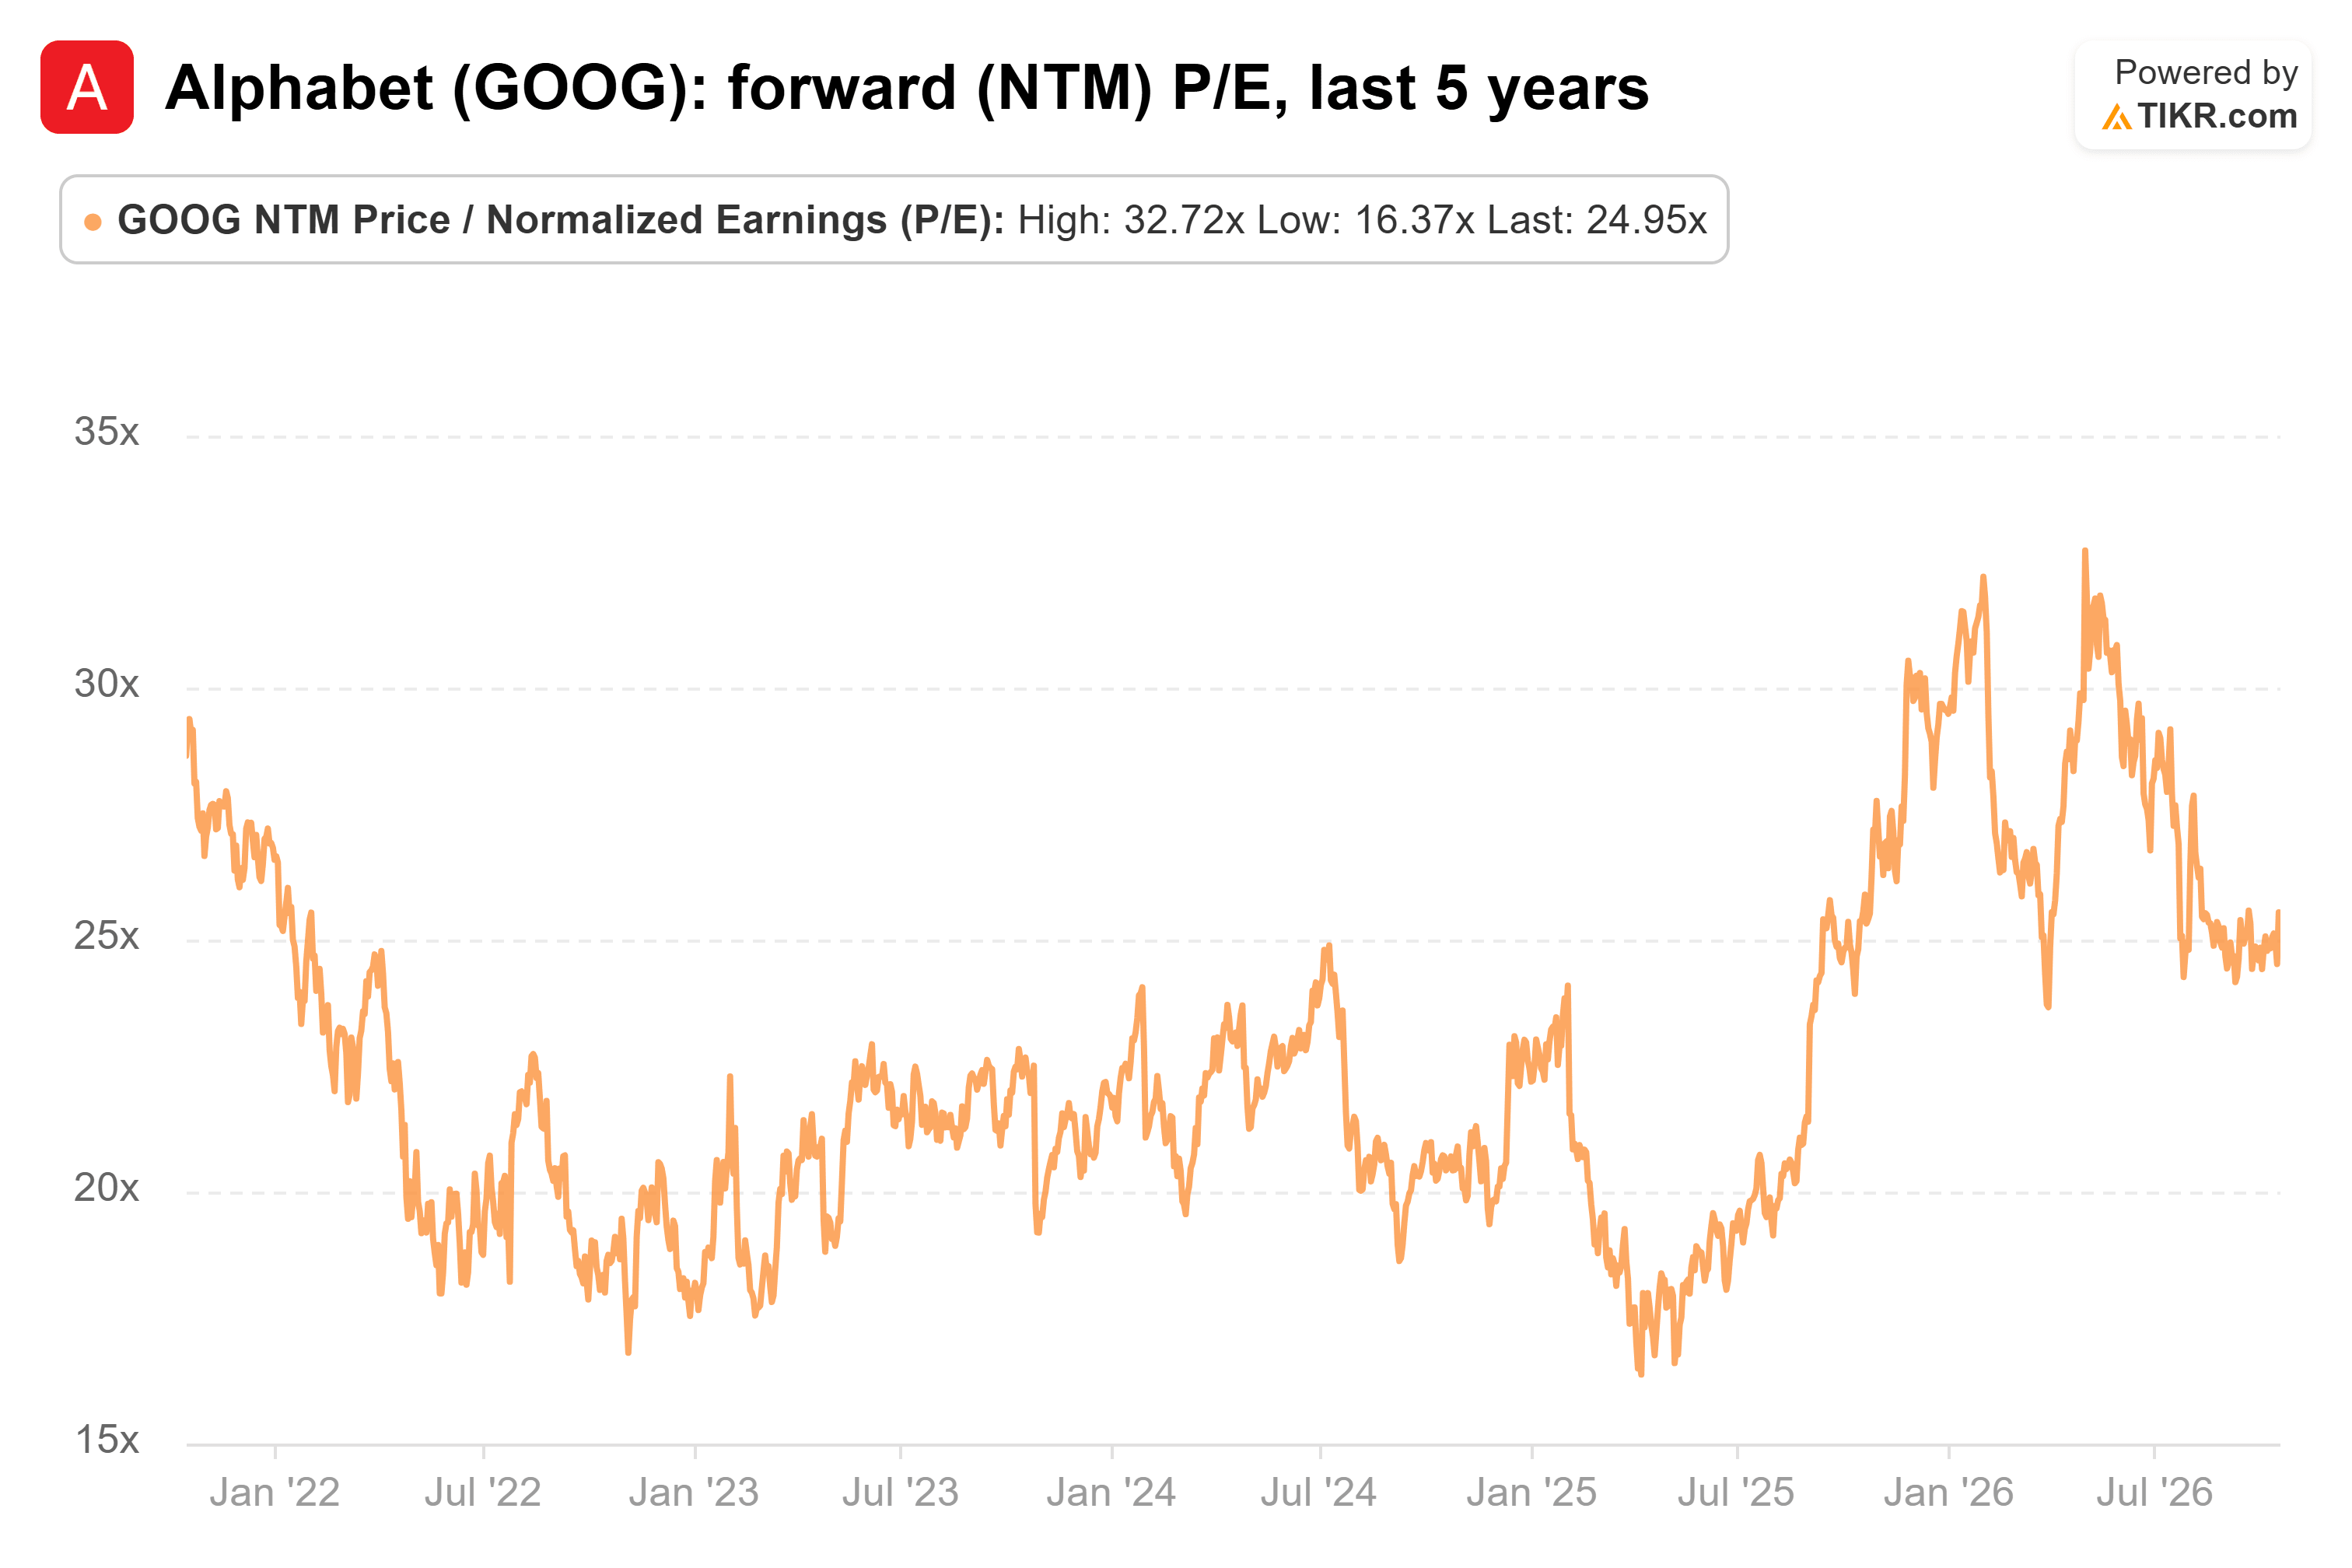
That’s a multiple in Alphabet’s usual range, with no obvious premium for Waymo.
Small potatoes today
Of course, Waymo is a rounding error inside Alphabet for now. Sacra estimates its annualized revenue at $355 million in February. That’s less than 0.1% of the $403 billion Alphabet brought in during 2025.
And analysts expect that base to keep growing fast, to $751 billion by 2028…
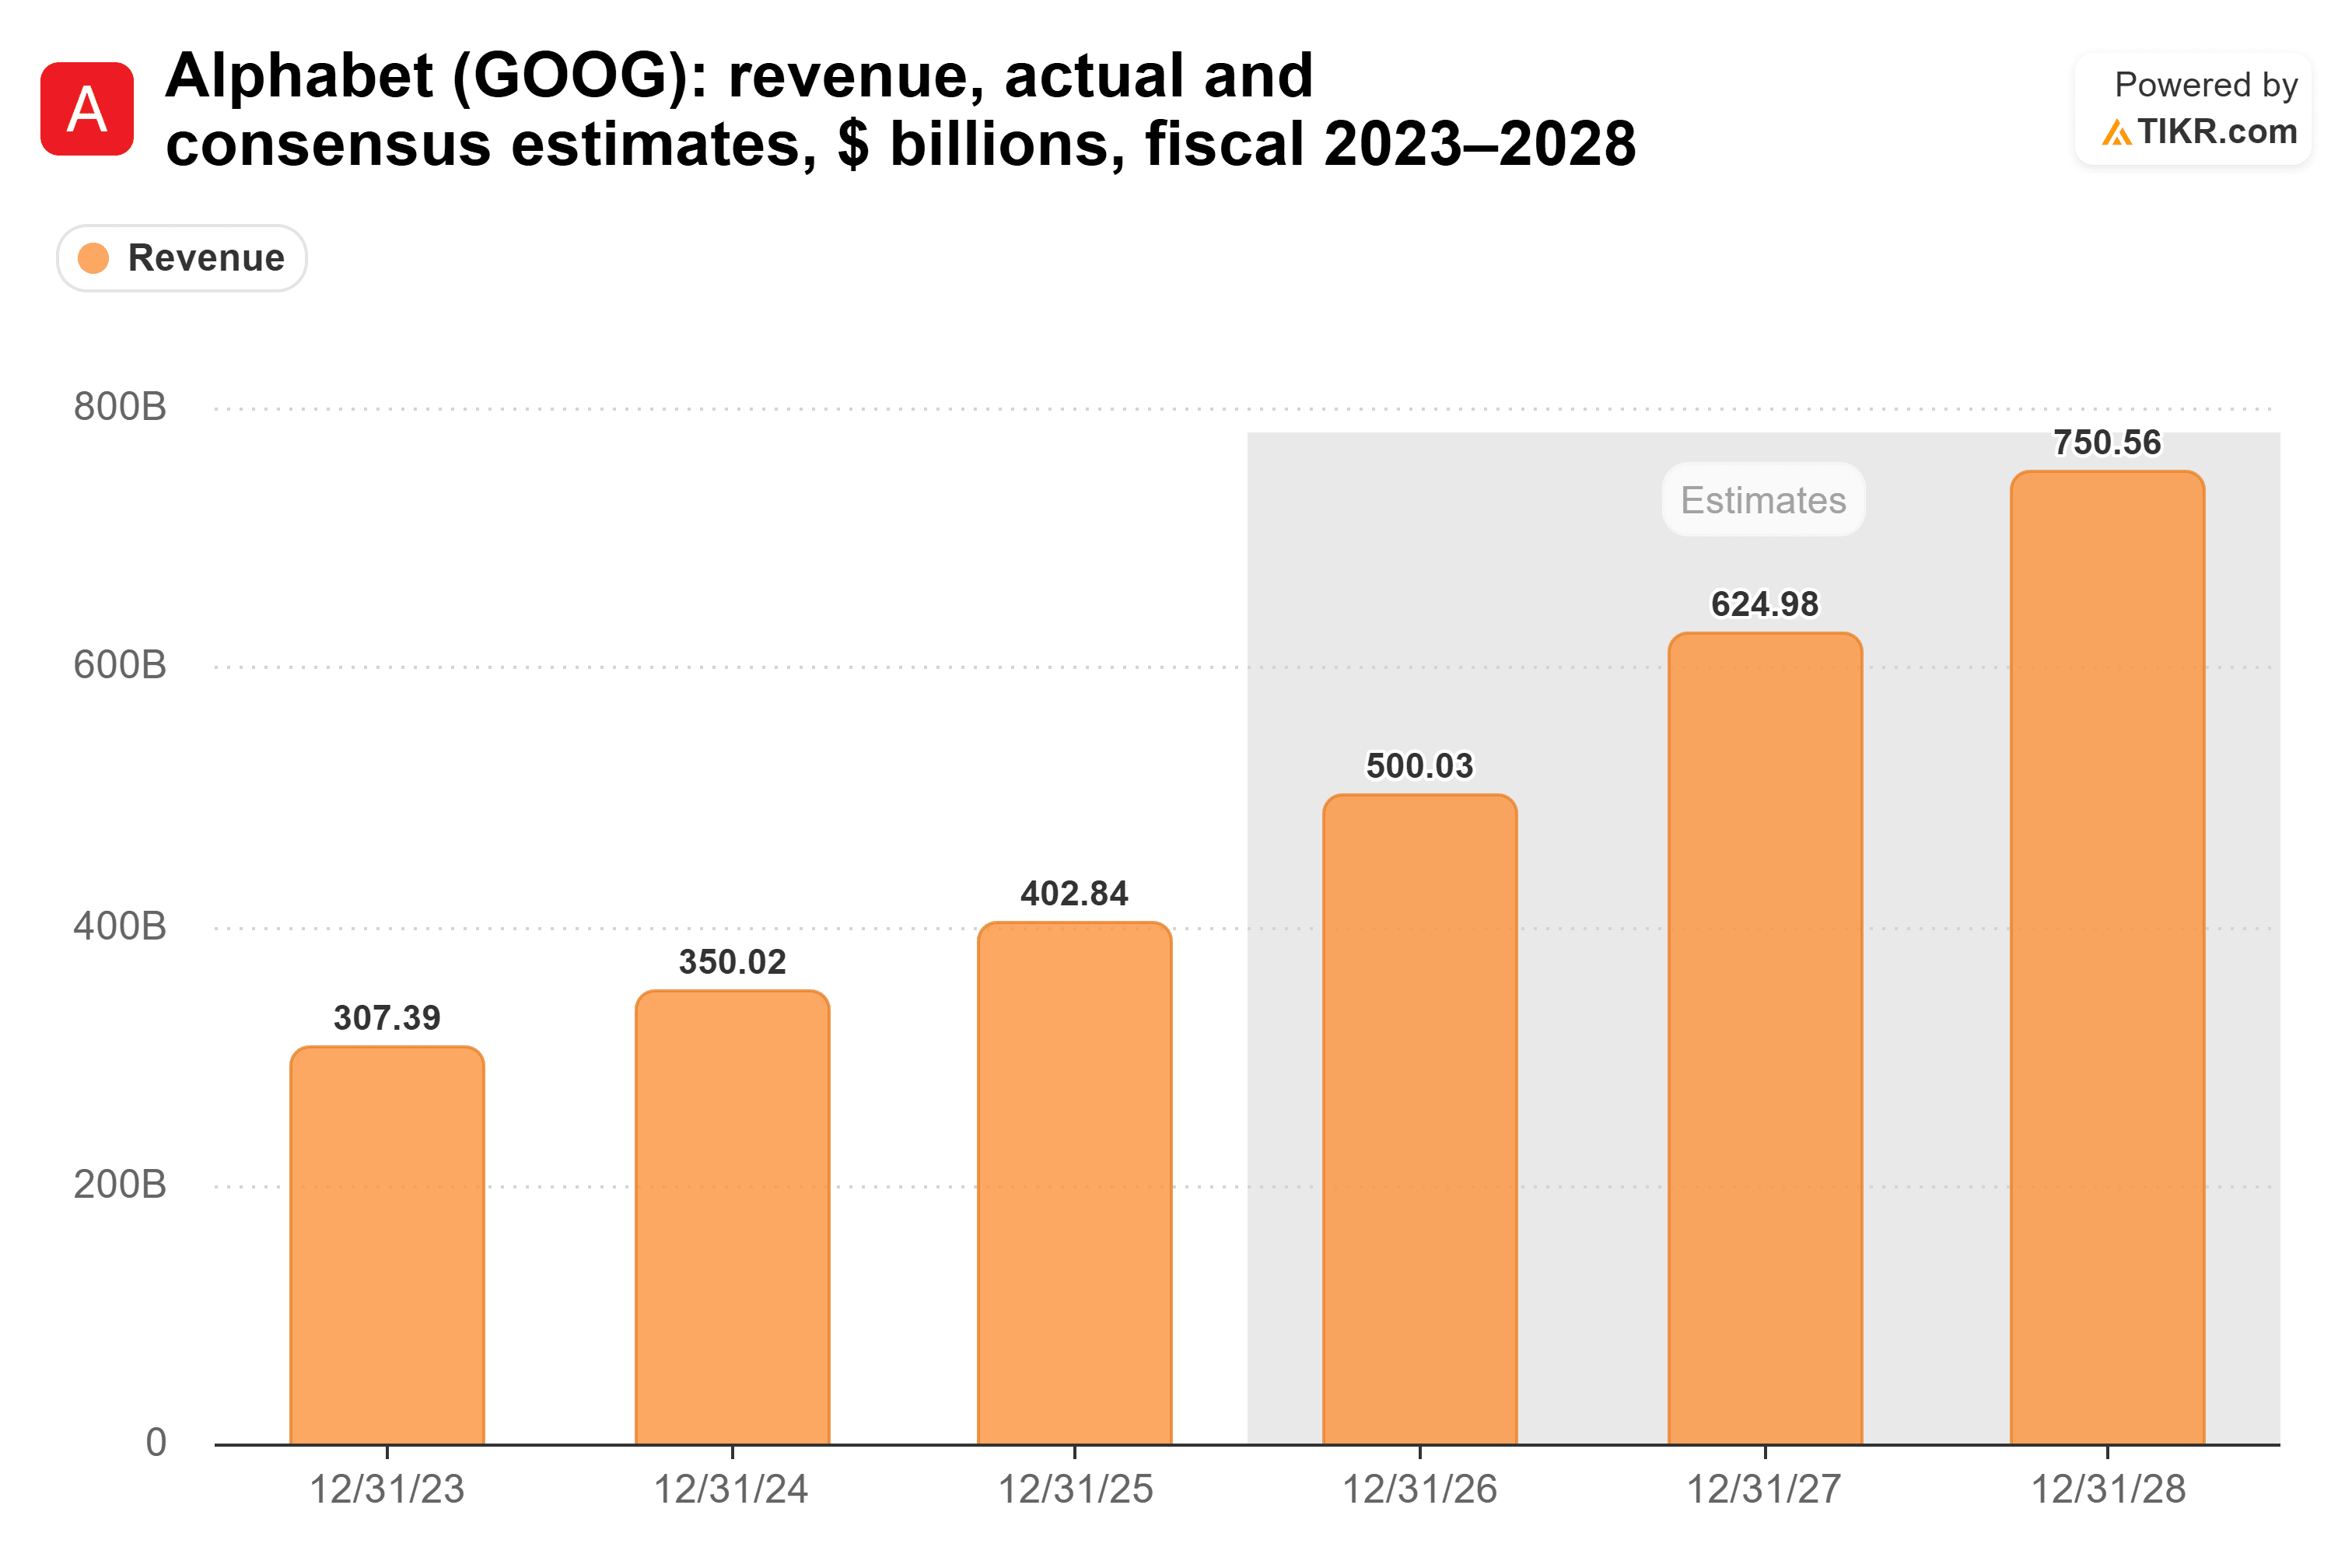
Waymo’s ride growth won’t move those estimates much in the next couple of years. If it pays off, that comes later.
Uber is already paying for the threat
Waymo’s upside barely registers in Alphabet’s stock, but the threat it poses shows up clearly in Uber Technologies (UBER).
Uber shows what it looks like when investors price in the Waymo threat. Telecom analyst Walter Piecyk, speaking on a recent episode of Decoder, put it this way: “The threat of Waymo and Robotaxi is what keeps that stock where it is.”
Waymo’s fleet is far too small to dent Uber’s network of drivers today, Piecyk says, so the pressure comes from what’s ahead. “But the threat of where Waymo is going to be two years from now, three years from now, or Tesla Robotaxi, that’s what investors care about,” he said.
The market is already charging Uber for that future. The stock trades at 18.2x forward earnings, well below Alphabet’s 25.0x…
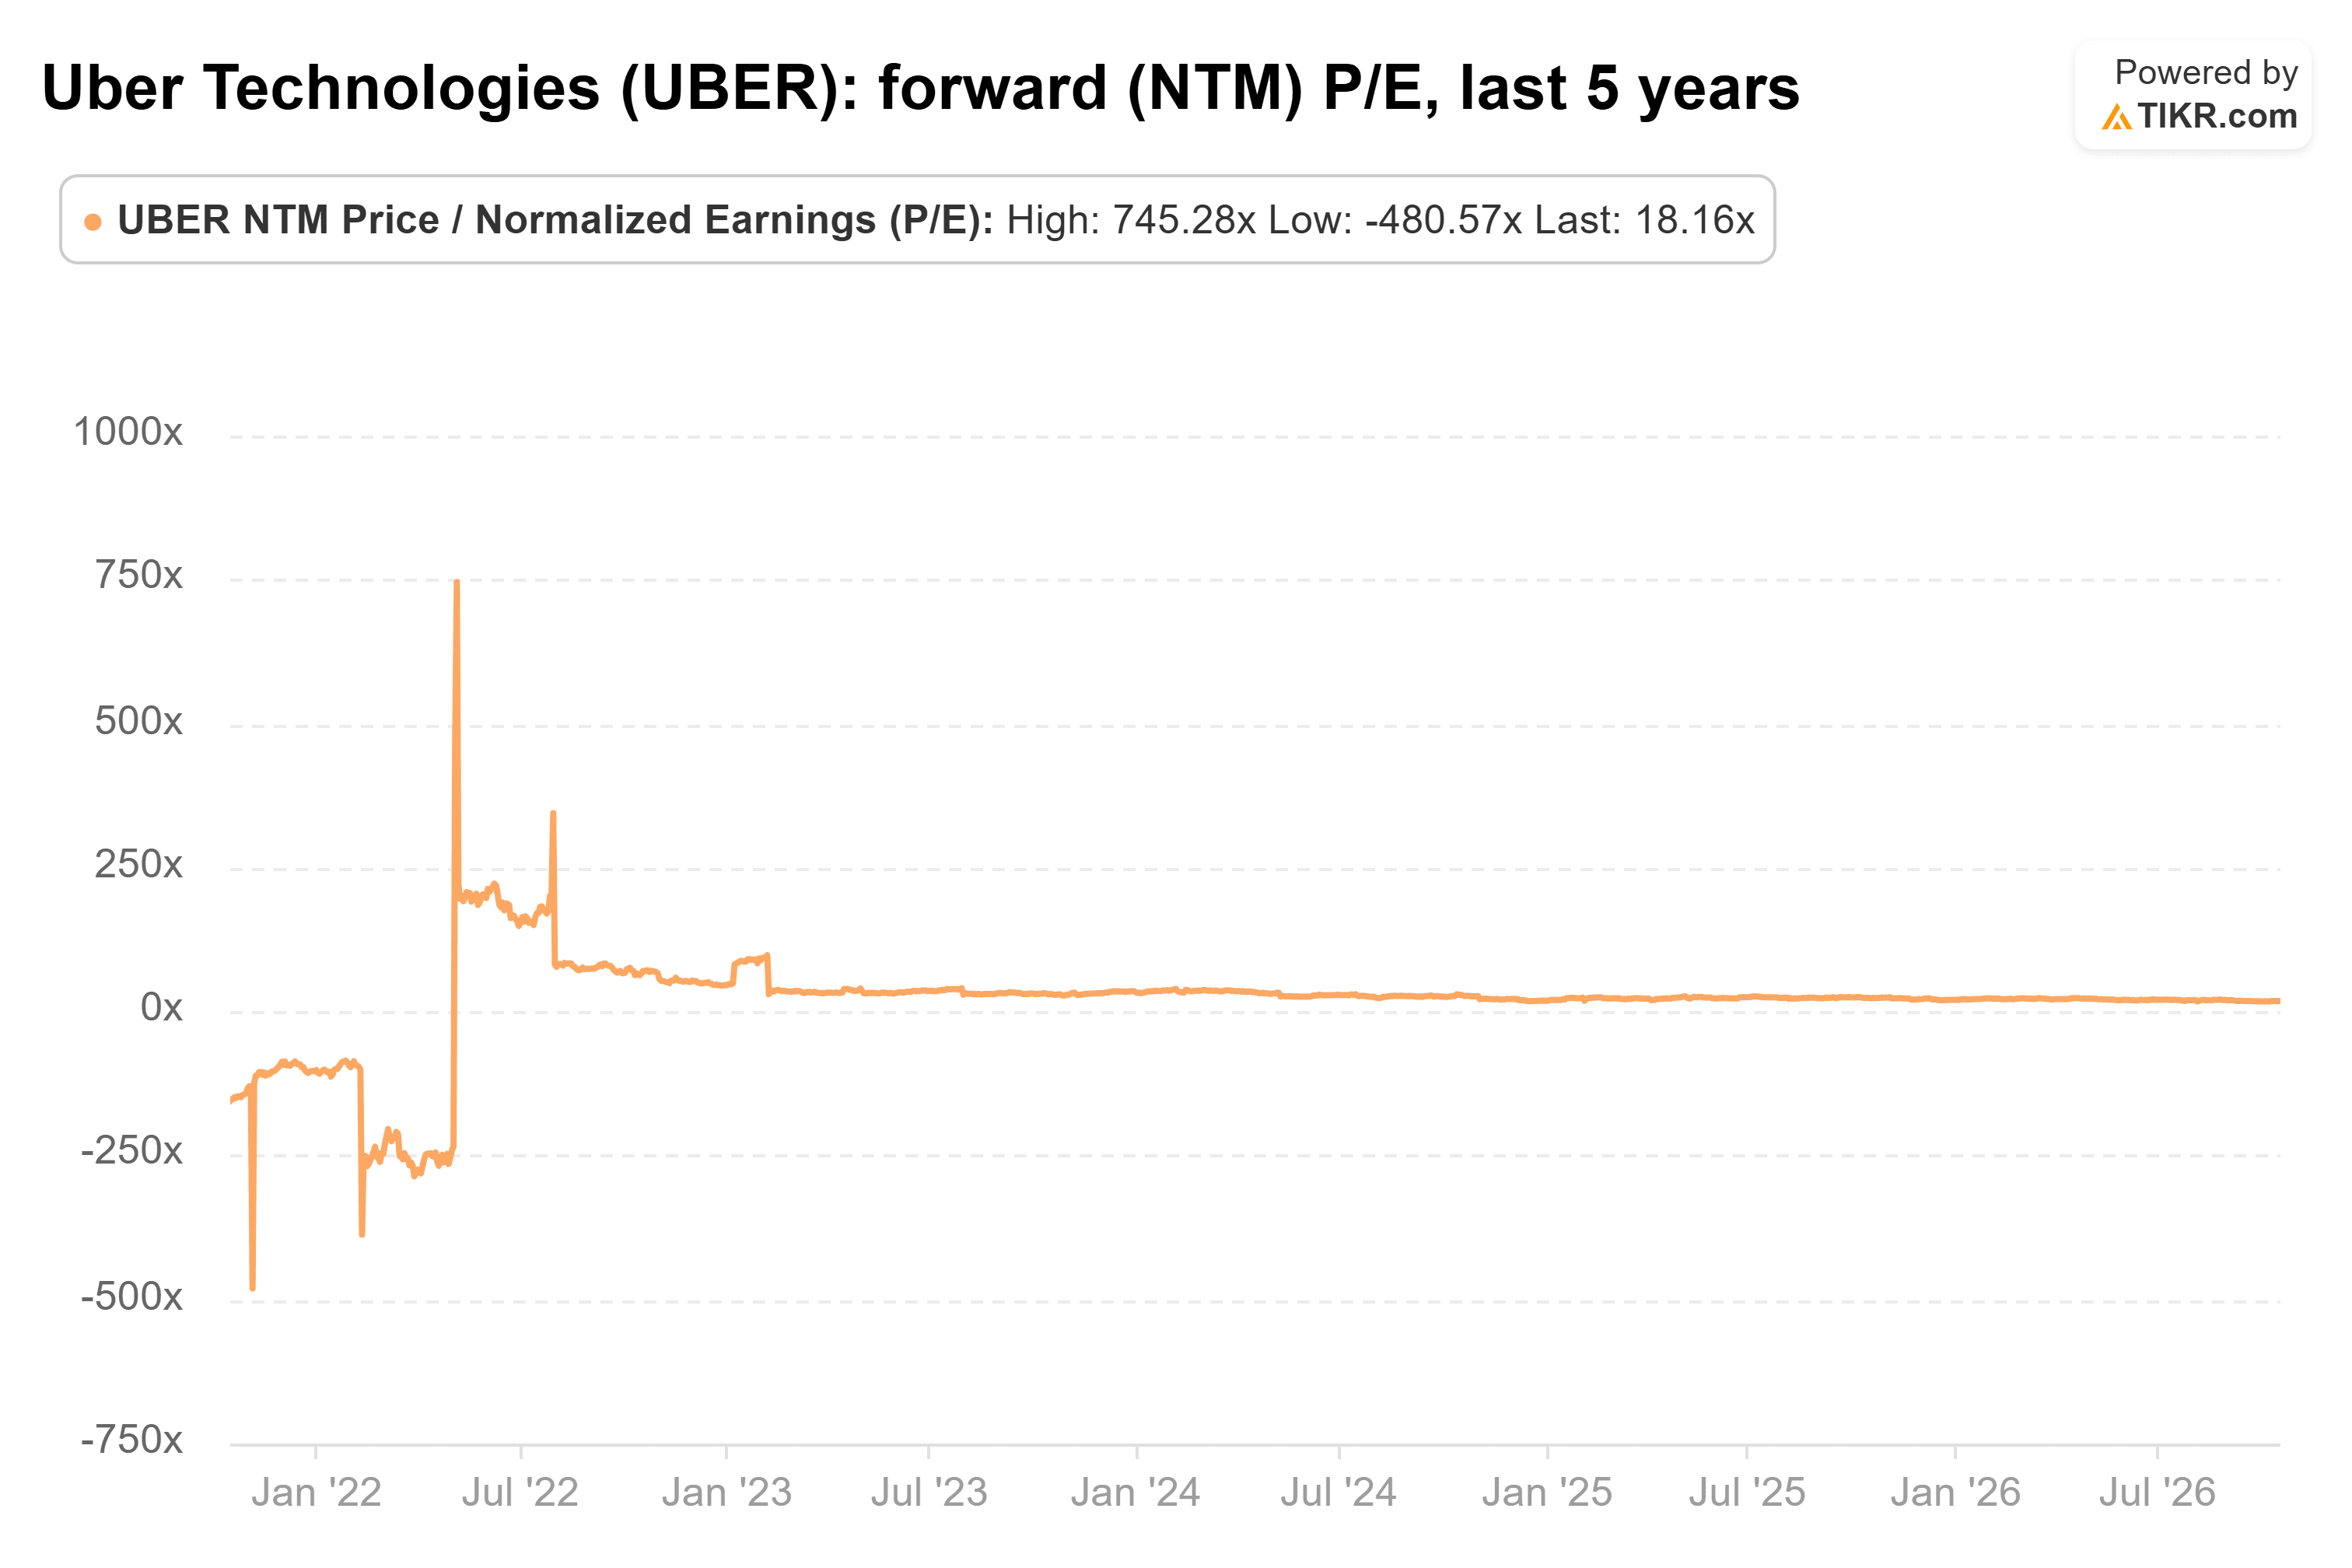
(The wild swings early on that chart come from the years when Uber barely earned anything.)
Waymo is the cheap part of Alphabet
At its February valuation, Waymo made up only about 3% of Alphabet’s market value, which is a small price for what could be the biggest piece of the story.
Dholakia’s “Easy” oversells it, and his firm has a stake in the answer. Alphabet shareholders don’t need him to be fully right, though. Even a Waymo worth half his number would be a $500 billion asset, four times its last round, sitting inside a stock that trades near its usual multiple.
Investors are already marking Uber down to 18.2x forward earnings for the Waymo threat, yet Alphabet’s 25.0x hardly reflects the upside on the other side of that trade. I think that makes Alphabet the simplest way to own the robotaxi trade.
To be fair, personal cars, trucking, and logistics are all still ahead of Waymo, and none of them bring in revenue yet. The number to watch next is Waymo’s weekly paid rides, and co-CEO Tekedra Mawakana said in February that she expects 1 million a week this year.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


