Key Stats for Bank of America Stock
- Current Price: $53.52
- Target Price (Mid): ~$77
- Street Target: ~$67
- Potential Total Return: ~44%
- Annualized IRR: ~9% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Bank of America (BAC) grew adjusted EPS 35.96% in the second quarter. For the third quarter, TIKR’s consensus of around $1.11 implies growth of about 5% from the year-ago $1.06, and Benzinga Pro’s $1.16 implies about 9%. The bank reports before the open on October 14, with shares at $53.52 on October 7, about 18% below their intraday 52-week high of $65.23. Results will post to its investor relations materials.
Price Targets Are Falling Toward a Low EPS Bar
On October 1, Evercore ISI cut its target to $62 from $67 and Truist to $62 from $65, both keeping bullish ratings. TIKR’s Street mean slipped from around $69 on September 30 to around $67 on October 7, and Holds rose from 3 to 4. The mean still sits about 26% above the share price. The backdrop includes CEO Brian Moynihan’s mid-September guidance for roughly flat trading revenue and lower investment banking fees.
TIKR’s consensus puts Q3 EPS about 8% below Q2’s $1.21, and revenue of around $30.6 billion about 3% below Q2’s $31.558 billion. The October 8 estimate snapshot also trimmed the full-year 2026 revenue estimate by 0.21%.
Bank of America has beaten the adjusted EPS estimate in each of the last five quarters, by 2.69% to 11.43%. The largest beat came in Q3 2025, which makes the year-ago base a high one. A beat at the low end of that range would put EPS near $1.14.

See historical and forward estimates for Bank of America stock (It’s free!) >>>
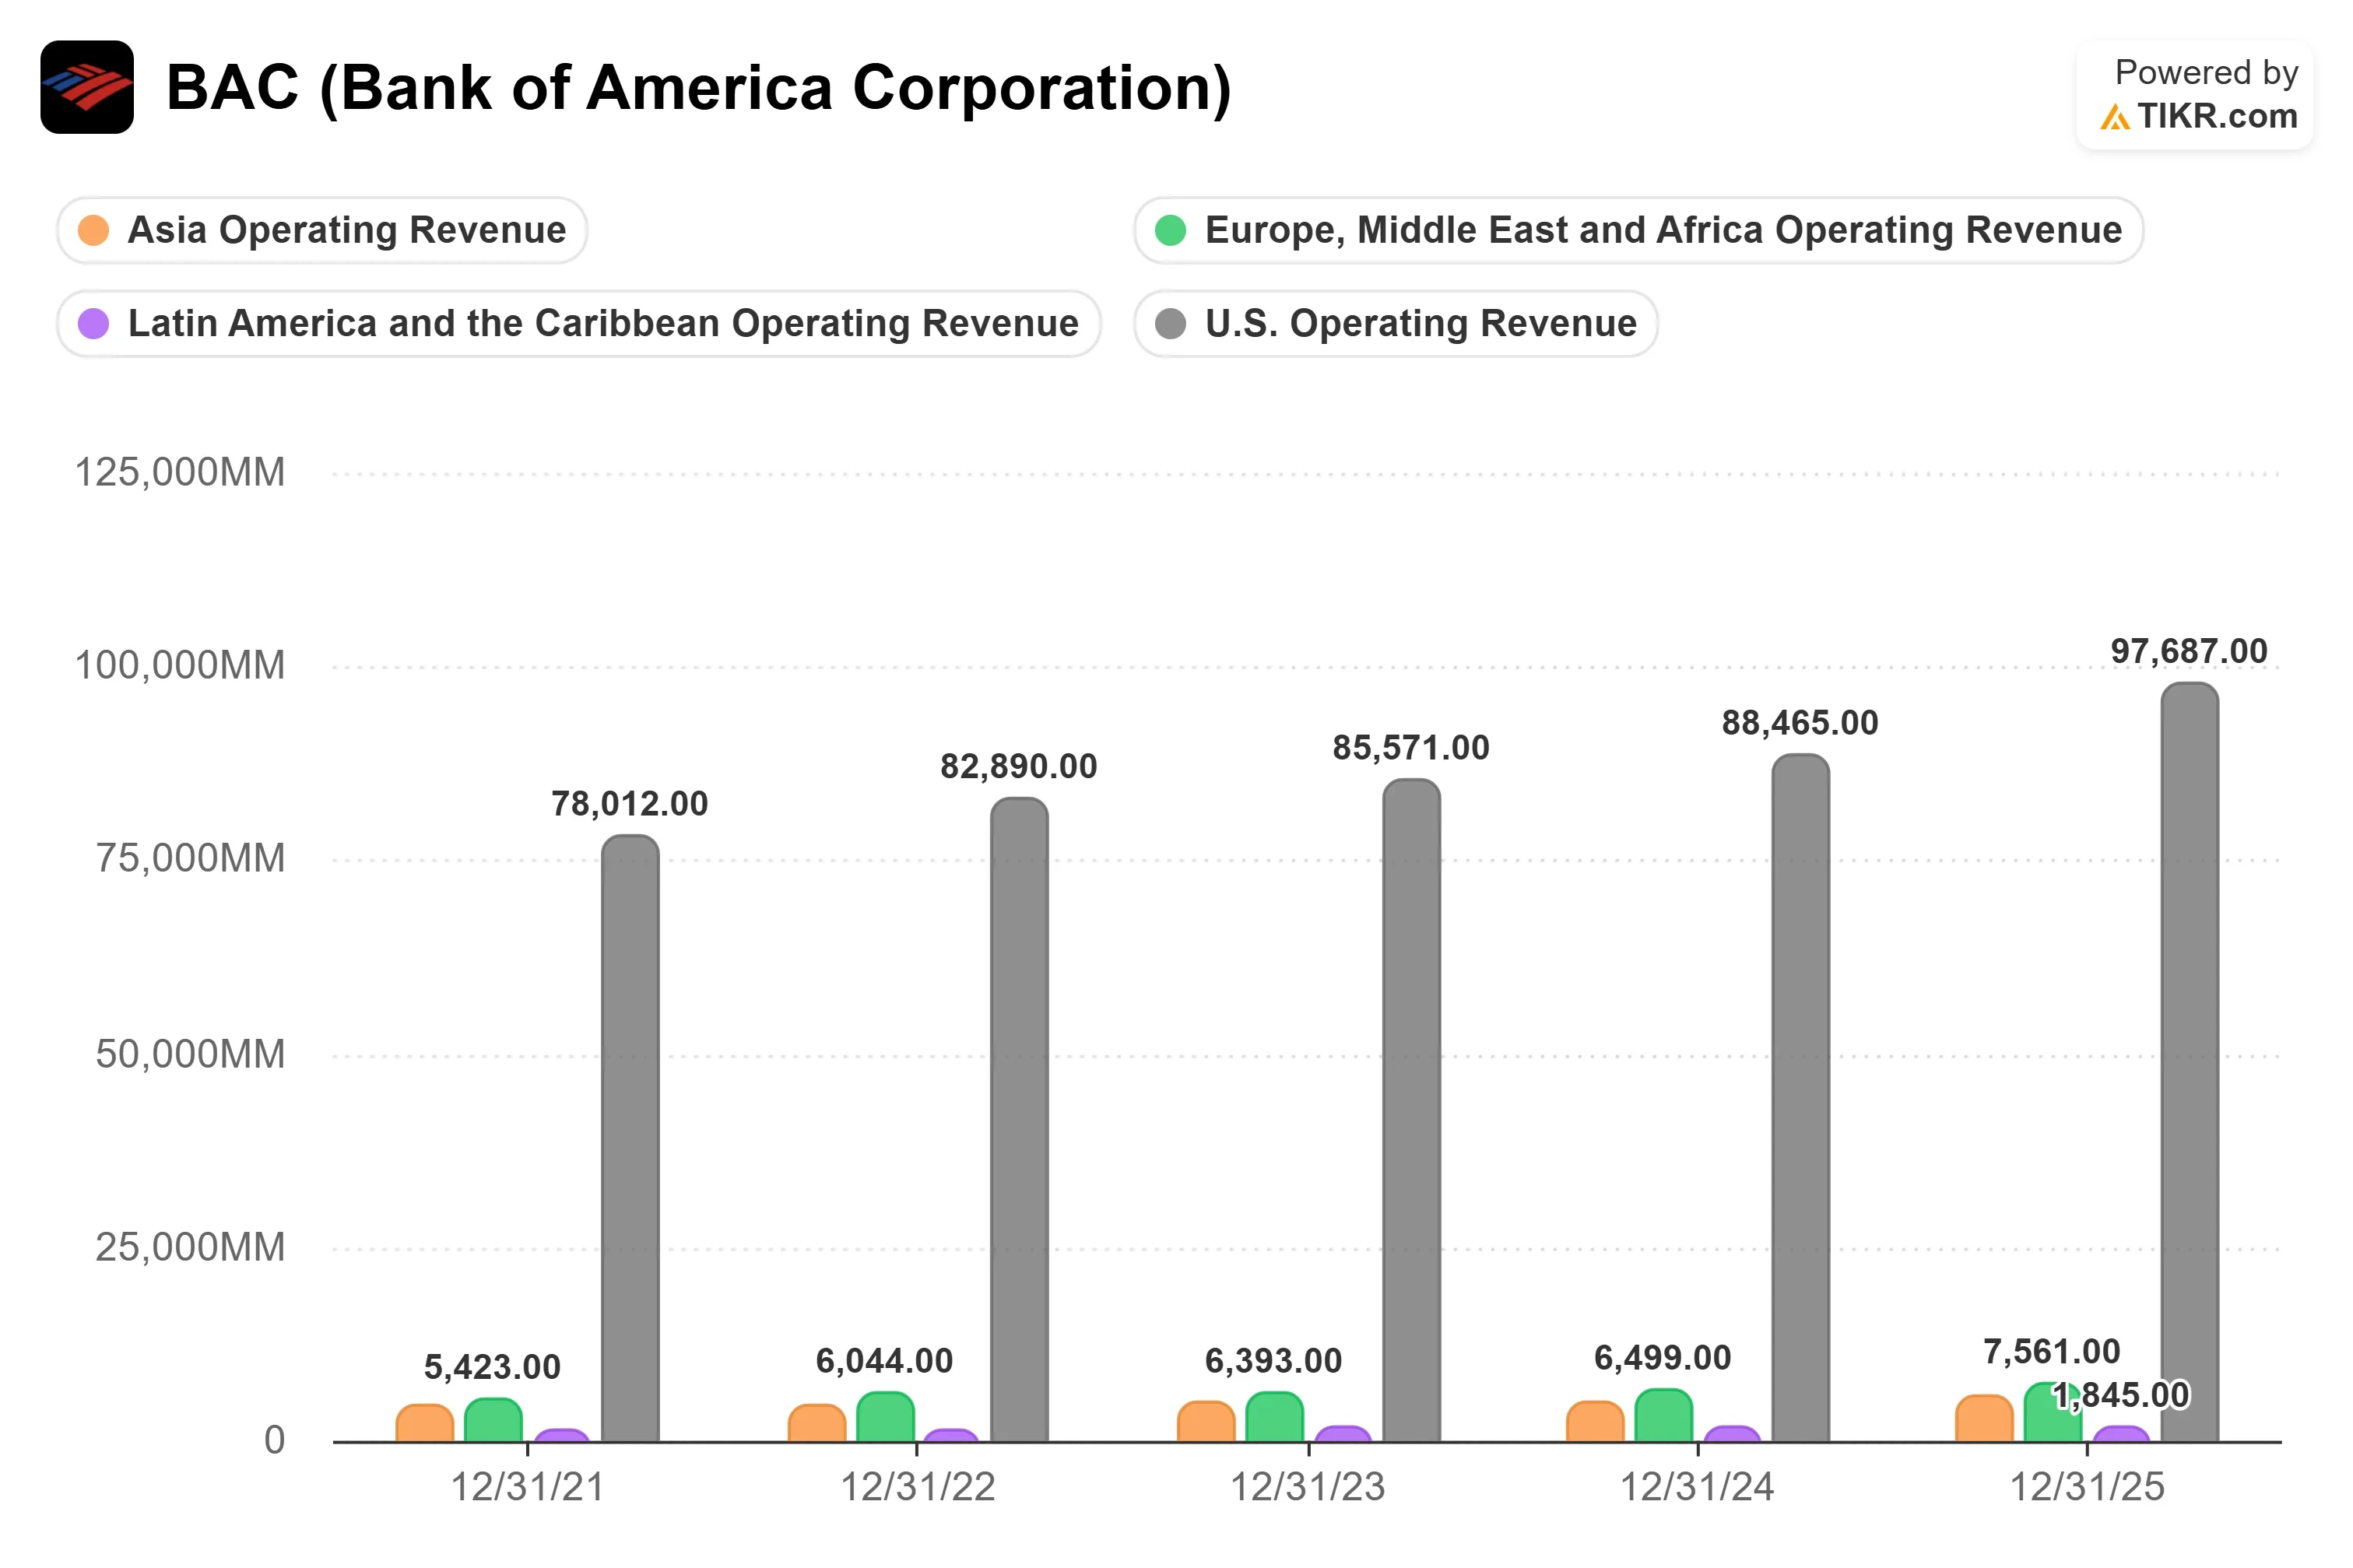
Non-U.S. Revenue Grew 14.8% in 2025. Management Wants $4 Billion More
Speaking in London on September 23, Co-President Jim DeMare restated international targets from the bank’s November 2025 investor day: a $4 billion increase in revenue, about $2 billion of pretax profit, and about an 18% return on allocated capital. One lever he named is U.S. commercial clients with $50 million to about $3 billion in sales that have customers, production, or suppliers abroad. The bank wants the payments, FX hedging, and rates business of their foreign subsidiaries. “It’s a priority,” he said.
TIKR’s geographic data offers a reference point, though the bank has not tied its target to it. Non-U.S. revenue rose 14.8% to $15.41 billion in 2025, ahead of 10.4% U.S. growth, led by a 16.3% gain in Europe, the Middle East, and Africa to $7.561 billion. The $4 billion target equals about 26% of that figure. It also implies a 50% pretax margin on the new revenue; by comparison, the non-U.S. regions’ 2025 net income was about 21% of their revenue. DeMare gave no timeline, and these remain targets.
See how Bank of America performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $53.52
- Target Price (Mid): ~$77
- Potential Total Return: ~44%
- Annualized IRR: ~9% / year

See analysts’ growth forecasts and price targets for Bank of America stock (It’s free!) >>>
The mid case fits because it needs no rerating. Across the model’s 2025 to 2035 forecast window, it assumes revenue growth of around 4% a year, a net income margin of around 28%, and a P/E that shrinks around 2% a year.
- What fills the path: net interest income and fees on the revenue side, operating leverage on the margin side.
- Primary risk: a capital-markets slowdown that outlasts Q3.
- Upside: international revenue tracking DeMare’s targets could lift results above the mid case.
- Downside: if margins stall, returns lean on capital return. The bank raised its quarterly dividend 14% to $0.32 on July 24, which Moynihan tied to “the strength of our earnings, the power of our franchise.” It had about $17 billion of buyback capacity left as of June 30.
Conclusion
EPS above around $1.11 on revenue near $30.6 billion would show the bank absorbed the capital-markets slowdown. Any progress update on international revenue is the longer-term signal. A miss against single-digit growth expectations would suggest the slowdown runs deeper than management signaled in September.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Bank of America stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bank of America could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Bank of America on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!