

Key Stats for AXT Stock
- Current Price: $71.66
- Target Price (Mid): ~$396
- Street Target: ~$92
- Potential Total Return: ~452%
- Annualized IRR: ~39% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
AXT (AXTI) fell 10.19% to $71.66 on October 8, its third straight lower close, as Coherent (COHR) dropped 9.63% in a broad optics selloff. No AXT-specific news came with the move. The figure worth watching is in Wall Street’s models. Fourth-quarter revenue consensus of $77.45 million roughly equals management’s year-end indium phosphide capacity target plus AXT’s other product lines at second-quarter levels, as laid out in its investor relations materials.
The Fourth-Quarter Estimate Sits at AXT’s Capacity Target
On the July 30 call, Tim Bettles, VP of Business Development, agreed that quarterly indium phosphide (InP) capacity should exit 2026 at “about $60 million there or thereabouts.” CFO Gary Fischer reported about $16.9 million of second-quarter revenue from gallium arsenide, germanium, and raw materials. Together, that comes to roughly $77 million. Because $60 million is a year-end exit rate, matching it across the whole fourth quarter would require that capacity from October 1.
Third-quarter consensus of $66.00 million equals the roughly $66 million AXT said it could realize with permits in hand or with none required. That means the third-quarter estimate gives no credit for additional permits.
CEO Morris Young said, “The demand is moving faster than we can move,” and that AXT is “not taking orders” beyond what its full production queue can absorb. The capacity ceiling has some give, though. AXT held $96.3 million of net inventory at June 30, and Fischer said extra permits could unlock orders “for which we have the inventory to support.”
Any headroom would open up in 2027. Answering a question about InP capacity, Bettles said doubling again would “take our revenue to somewhere in the region of about $130 million a quarter exiting the year.” On that reading, consensus for the third quarter of 2027, the latest quarter TIKR shows, sits below capacity at around $124 million. Analysts more than doubled their 2027 revenue estimate between June 30 and September 30, to around $461 million from around $222 million.

See historical and forward estimates for AXT stock (It’s free!) >>>
China, Margins and Cash Decide the Next Leg
Bettles said China, where no export permit is needed, supplied more than half of the second-quarter revenue, and that he would model China at 40% to 60% going forward. InP shipments leaving China still need permits, which AXT’s June-quarter 10-Q calls “the most significant challenge we currently face.”
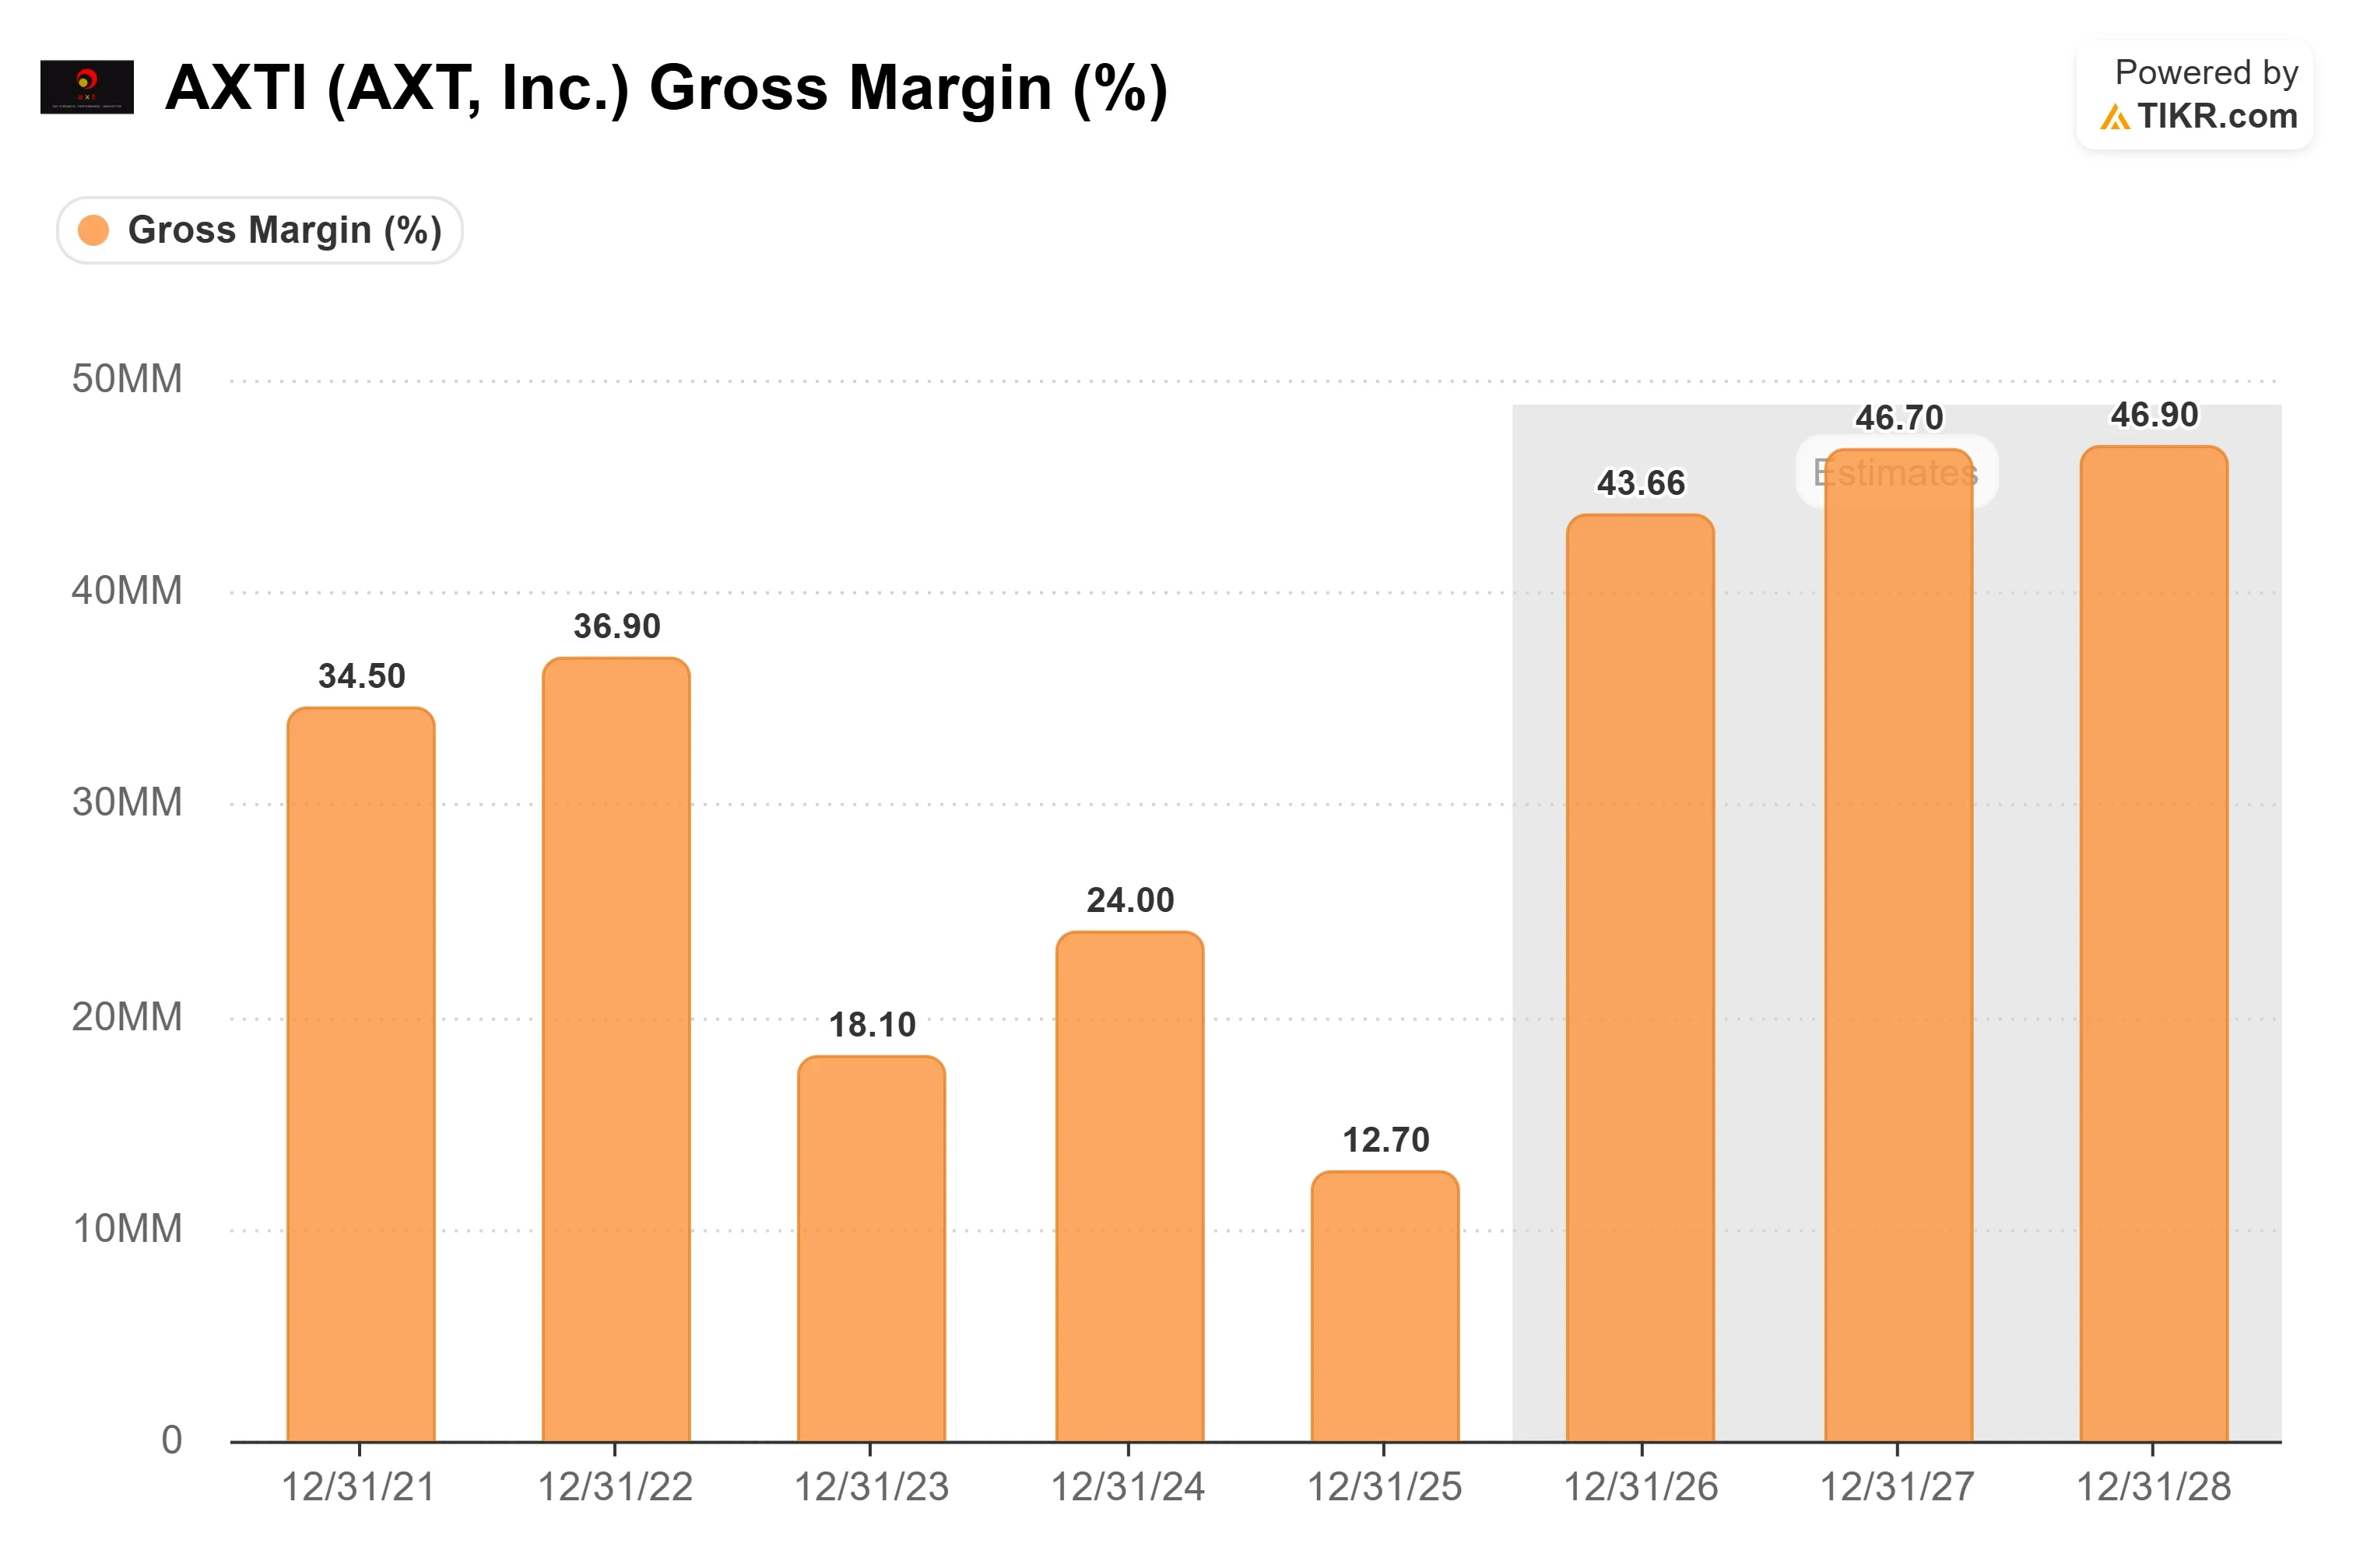
Non-GAAP gross margin reached 45.0% in the second quarter, and consensus puts 2027 around 47%. Fischer said management is “going to target something that begins with a 5,” while adding “we want to be careful what we tell you.”
Consensus has free cash flow negative in 2026 and 2027, at around -$33 million and -$4 million, as capital spending climbs to around $140 million in 2027. AXT ended June with $748.8 million in cash, cash equivalents and investments, mostly from its April stock offering, so the expansion is funded. The valuation leaves less room. At about 45 times next-twelve-months earnings, AXT trades above KLA (KLAC), near 36 times, and above every other company in TIKR’s semiconductor peer group.
See how AXT performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $71.66
- Target Price (Mid): ~$396
- Potential Total Return: ~452%
- Annualized IRR: ~39% / year

See analysts’ growth forecasts and price targets for AXT stock (It’s free!) >>>
TIKR’s mid-case values AXT at around $396 by December 31, 2031, about 452% above the October 8 close. Across its 2025 to 2035 forecast table, the model assumes revenue growth of around 60% a year (CAGR) and a net margin of around 33%. The growth leans on the 2027 capacity doubling and on larger, higher-priced wafers, while a rising InP mix carries the margin. Gross margins in the 50s would add earnings that the consensus doesn’t include. A permit slowdown or cooling China demand would hit a valuation that already prices in near-full factories.
Conclusion
AXT reports third-quarter results after the close on October 29. Revenue above $66 million would show extra permits or faster China orders. The capacity update matters more. Confirmation of roughly $60 million in quarterly InP capacity by year-end supports the $77.45 million fourth-quarter estimate. Any slip leaves that estimate leaning on inventory.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is AXT stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AXT could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


