


Key Takeaways
- Arista Networks stock rose 7% Friday to $171, but it’s still 21% below its record after a broad AI hardware selloff.
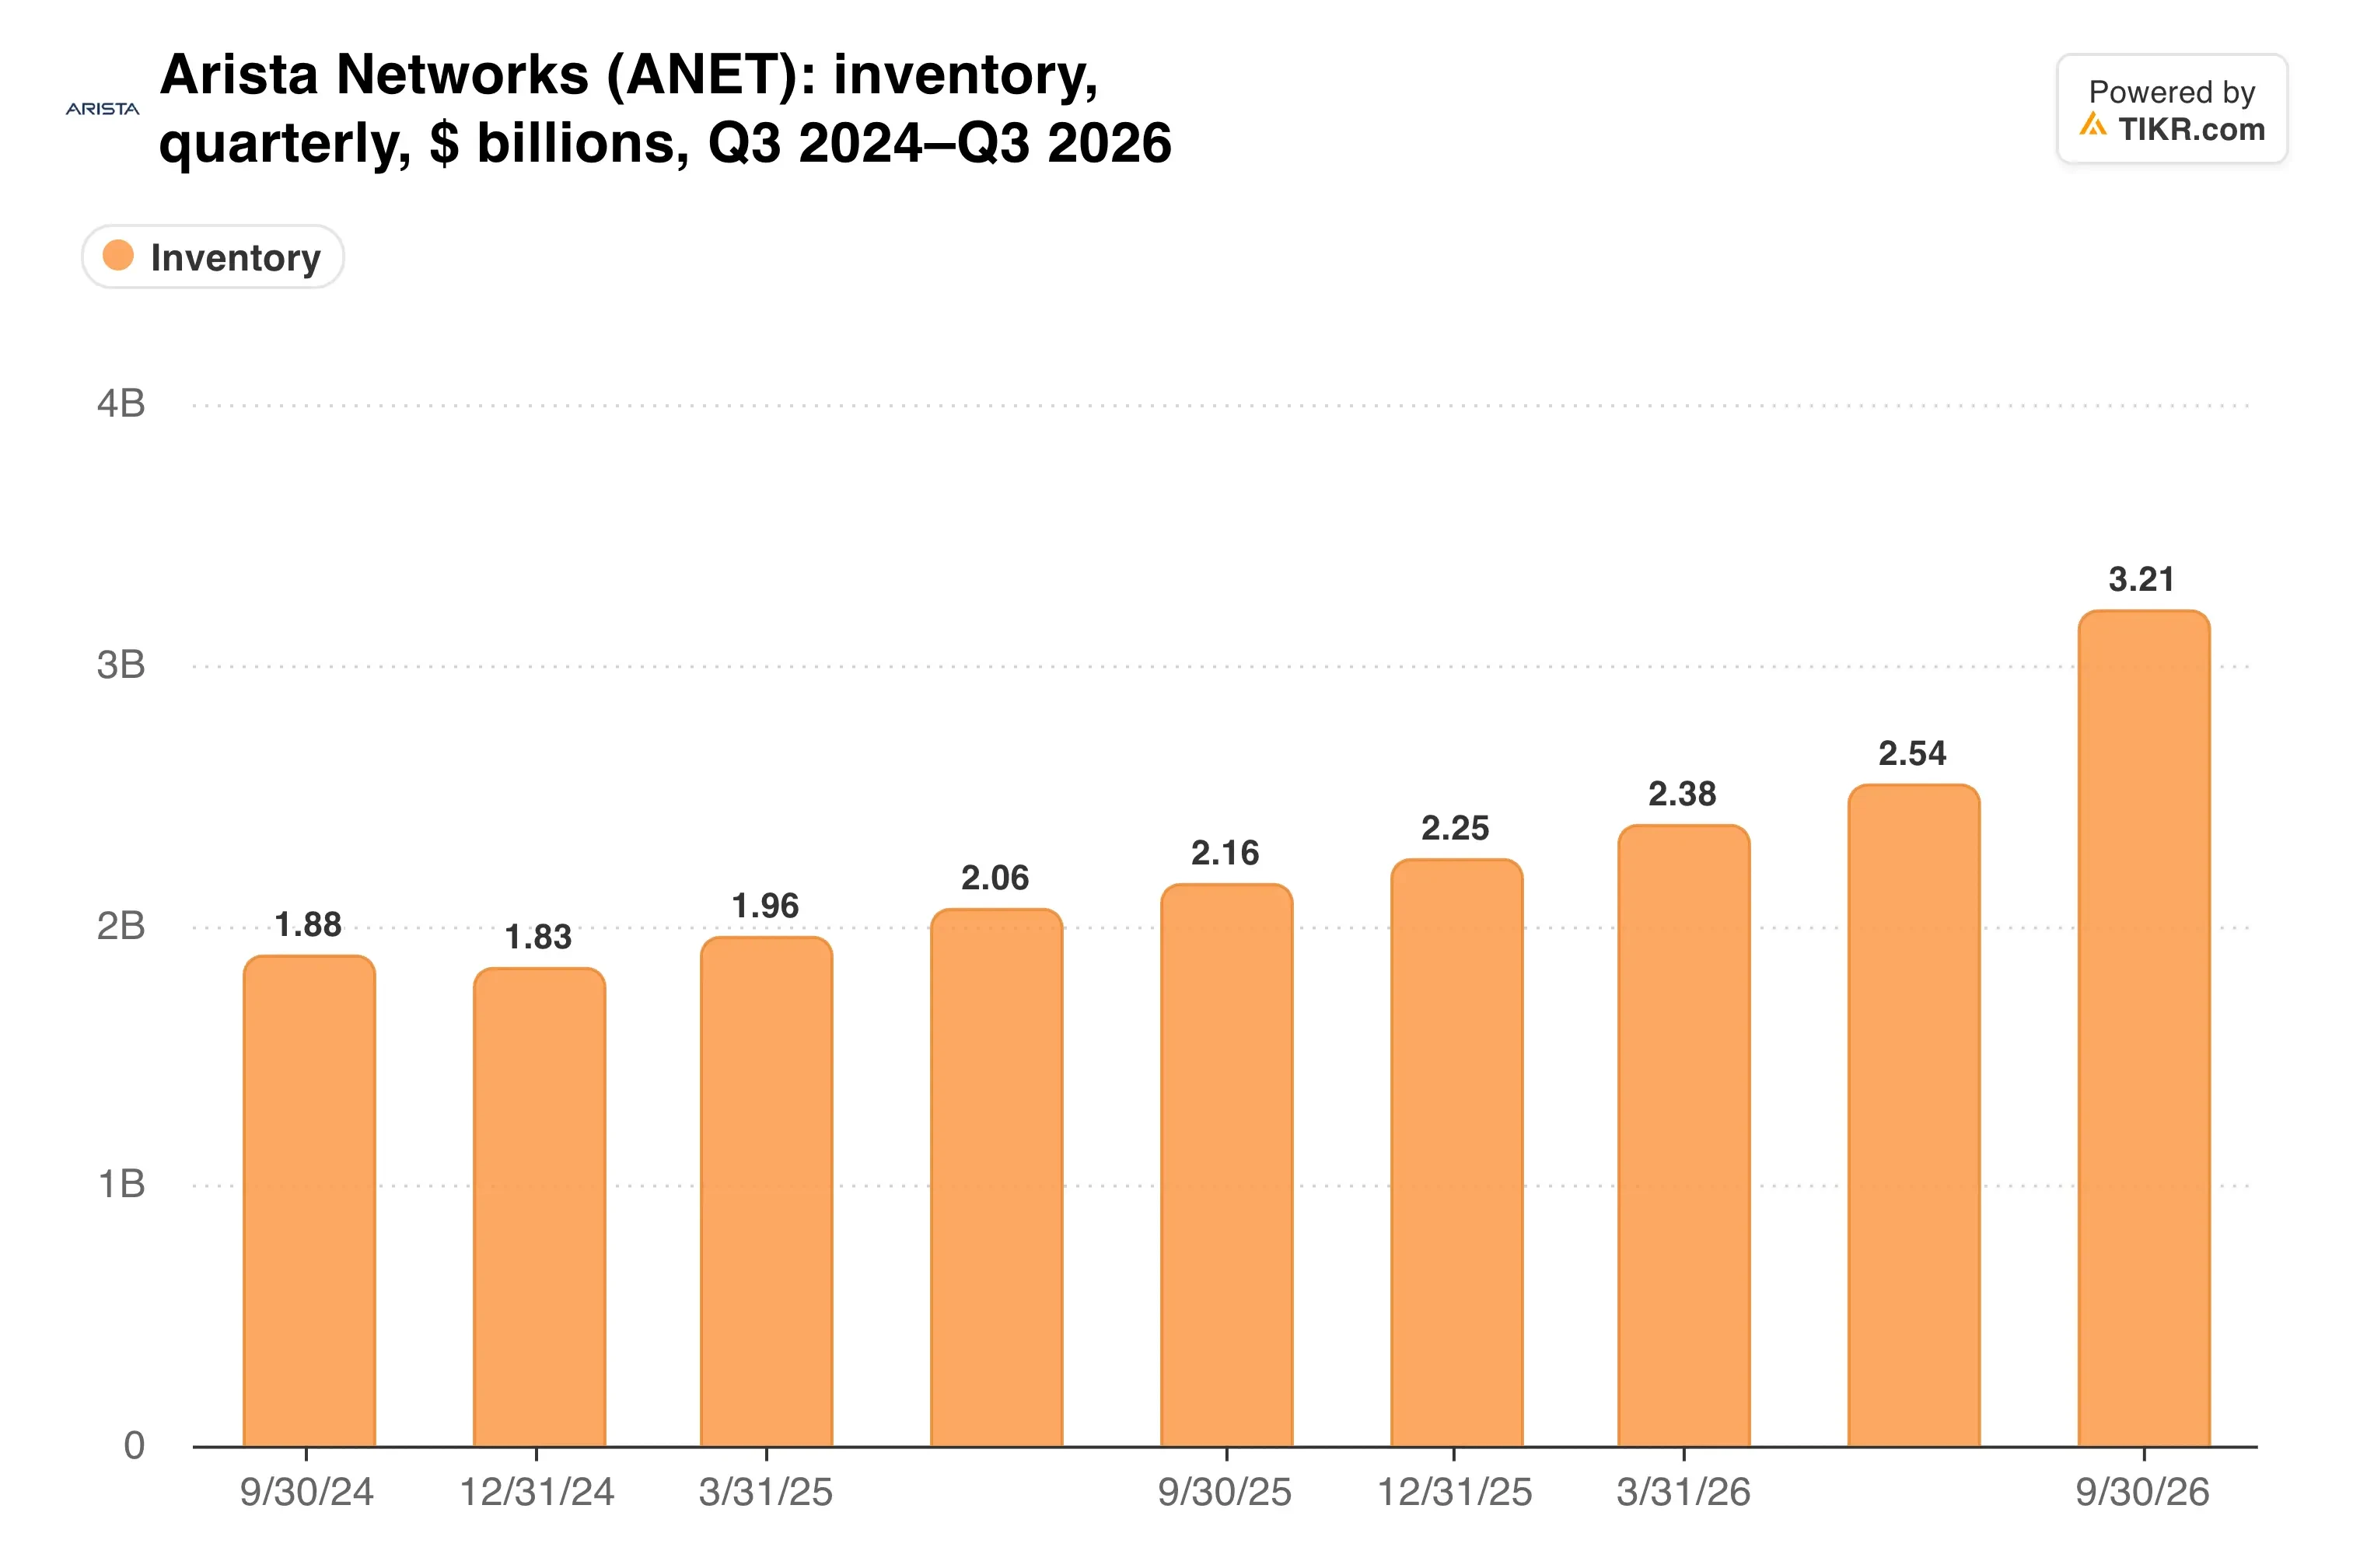
- Purchase commitments climbed to $11.4 billion and inventory to $3.2 billion, backing an initial 2027 outlook of about $18.5 billion.
- Nvidia’s Ethernet switch revenue grew 181.1% in the second quarter against 37.6% for Arista, according to IDC.
- The February 12 report will show whether that supply turns into revenue without eroding gross margin.
Arista Networks (ANET) rose 7% on Friday to $171, making back part of a broad AI hardware selloff. The stock is still 21% below its record.
The selloff hasn’t touched the forecast, though. Arista guided 2027 revenue up 38% to 40%, to about $18.5 billion at the midpoint, and it’s backing that number with real money.
Purchase commitments rose to $11.4 billion last quarter, from $9.7 billion three months earlier. That’s a bet on AI demand, and also on holding off Nvidia (NVDA), whose data center Ethernet switch revenue grew 181.1% in the second quarter against 37.6% for Arista, according to IDC.
A record quarter, then a bigger promise
Arista’s third quarter set records:
- Revenue of $3.66 billion, up 58.5%, against the $3.33 billion consensus
- Non-GAAP EPS of $1.20, against the $1.08 estimate
- A non-GAAP operating margin of 49.1%, up from 48.6%
Revenue grew 20.5% from the second quarter alone:
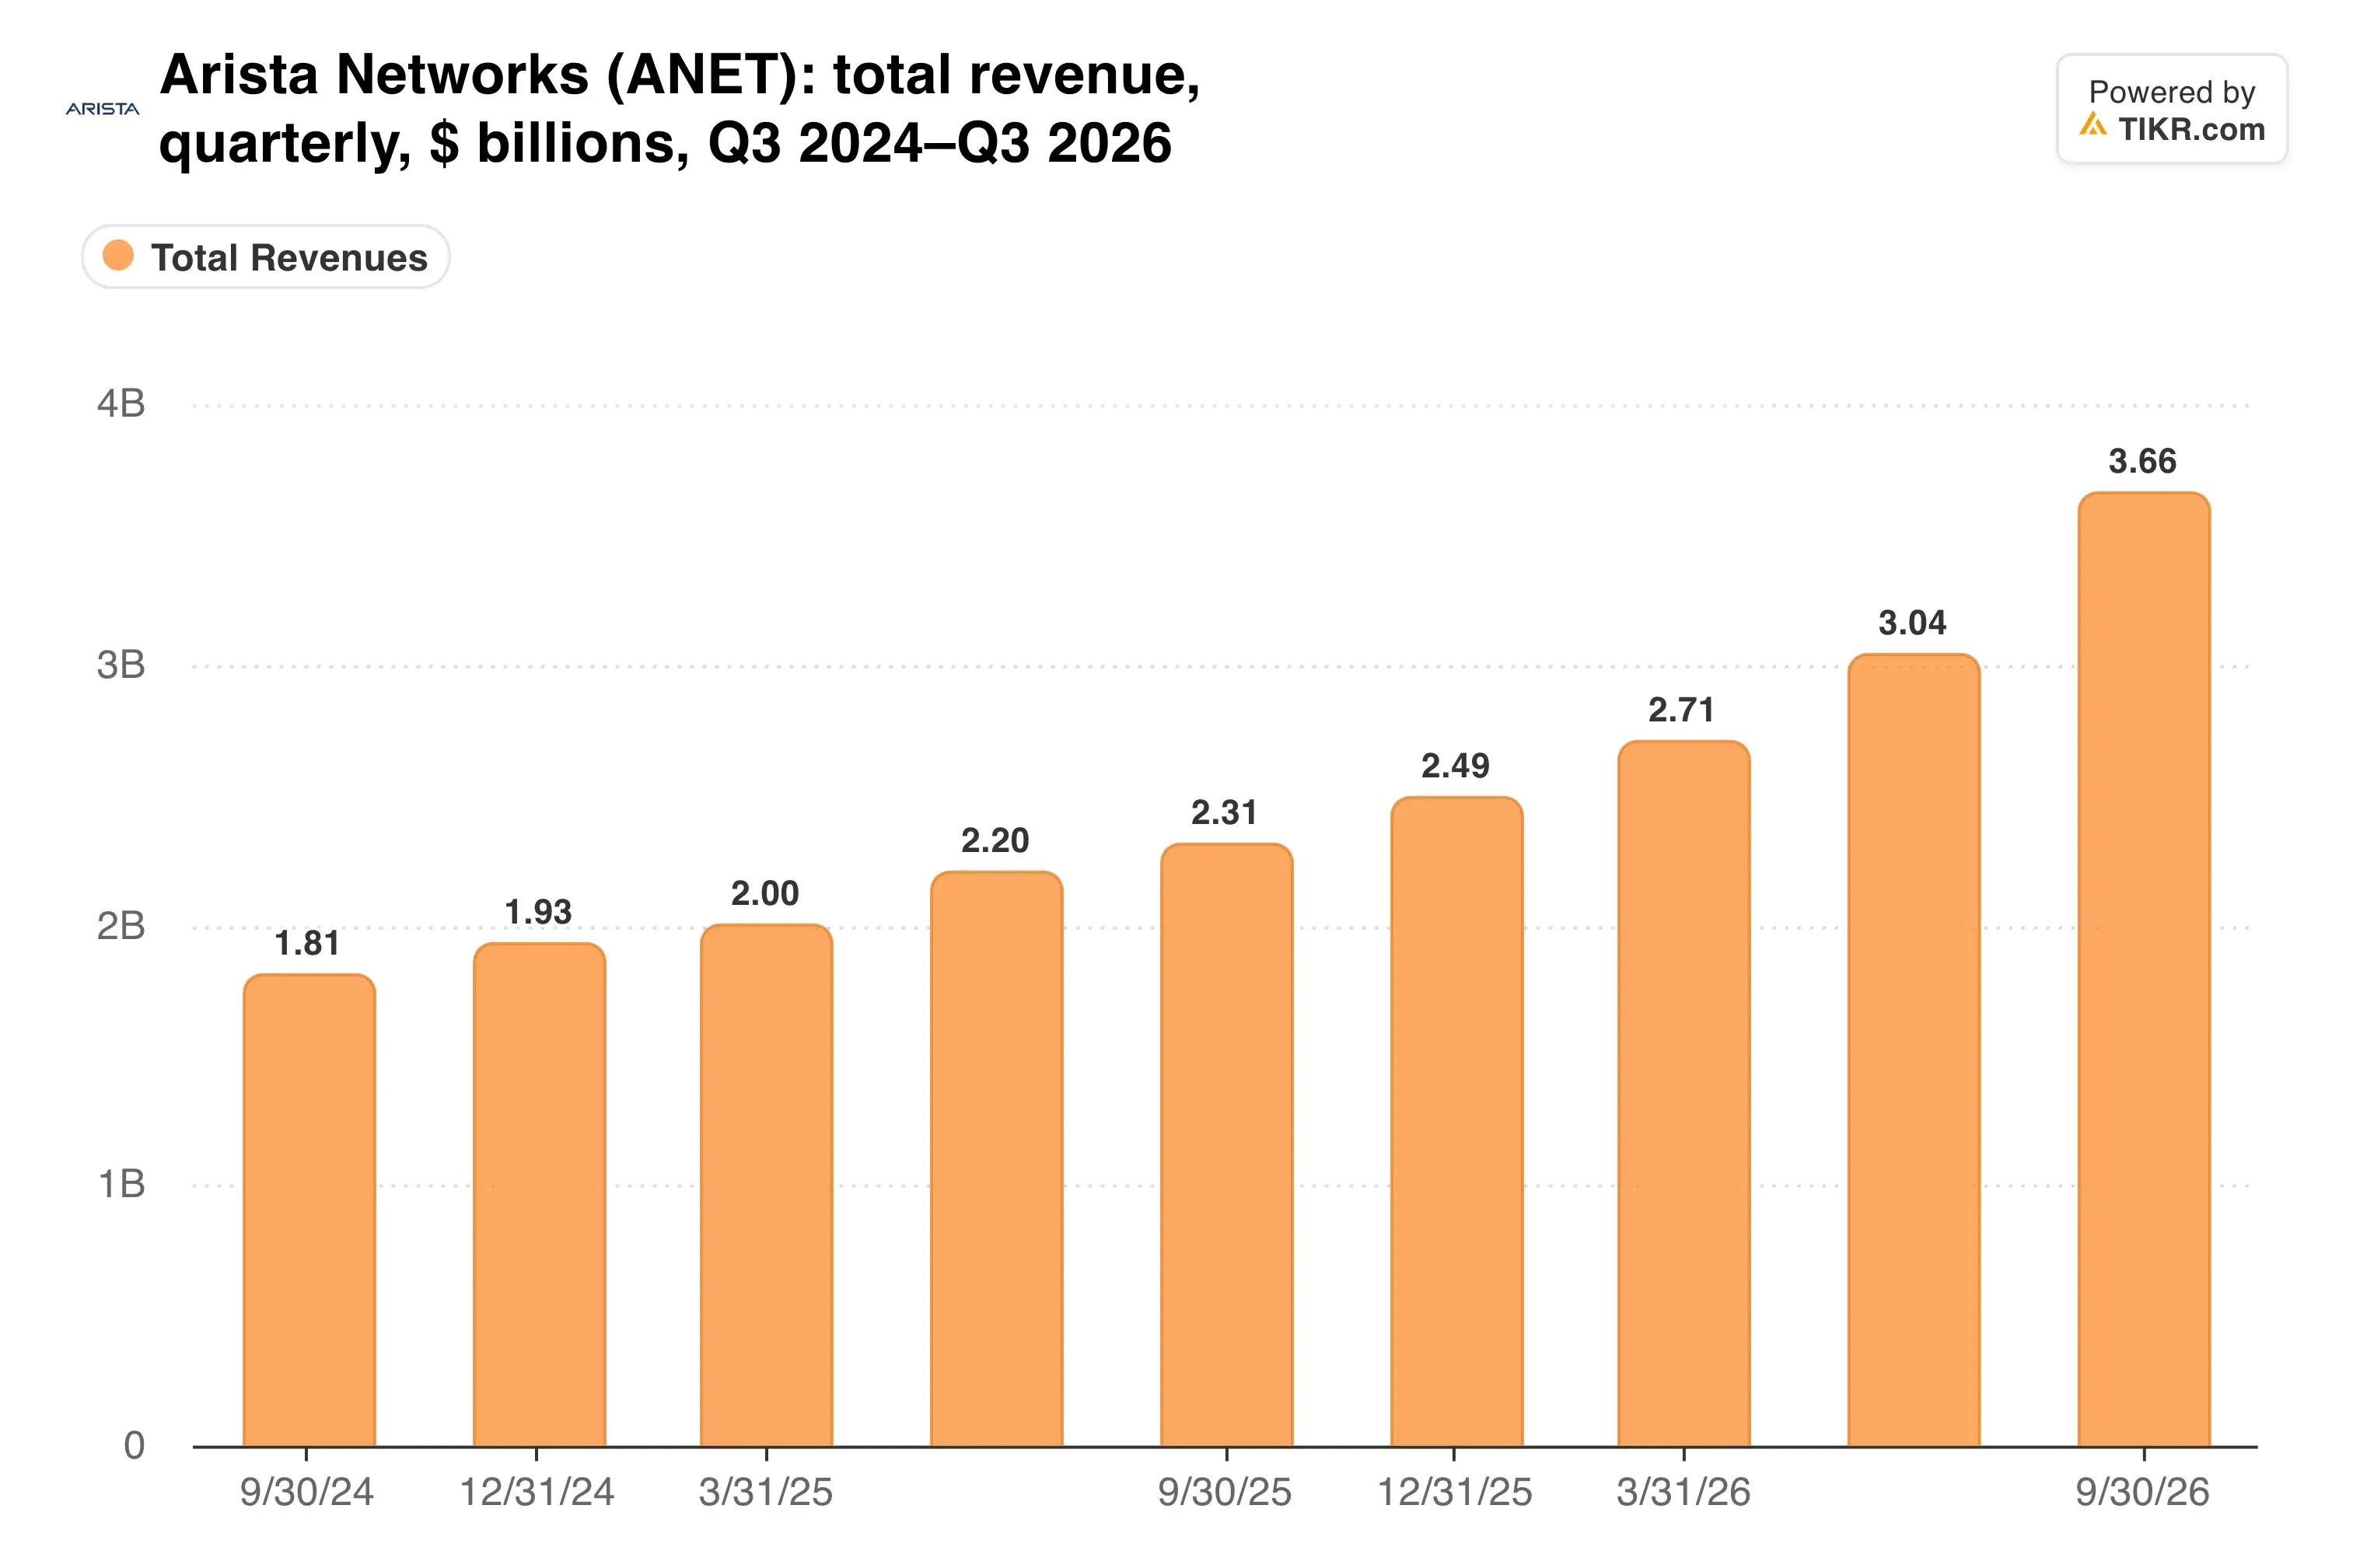
Full-year 2026 revenue is now guided to just over $13.3 billion, the fourth raise this year. Fourth-quarter guidance of $3.9 billion to $4.0 billion points to more growth.
CEO Jayshree Ullal tied it straight to AI: “This strong momentum across customer sectors highlights our increased relevance for the generative and agentic AI era.”
Buying supply ahead of demand
The 2027 plan has AI fabrics doubling to about $7 billion and campus growing about 60% to roughly $2 billion. Neither happens without parts.
That’s why the balance sheet is swelling. Inventory jumped to $3.2 billion from $2.5 billion in a single quarter.
Ullal laid out the strategy back in August: “While the industry-wide supply tightness and rising component costs persist, Arista has taken individual and aggressive proactive steps.”
Arista can afford the bet, since it holds about $14.4 billion of net cash. The risk sits with customers. A handful of cloud giants drive a large share of sales, so a capex pause would leave Arista holding the parts.
TIKR tracks 32 analysts on Arista Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arista Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arista Networks’ Analyst Ratings
Margins and the multiple
Gross margin slipped to 64.0% from 65.2% a year earlier. The fourth-quarter guide of 63% to 64% leaves little room if component costs rise further.
Is the stock still pricing in the growth?
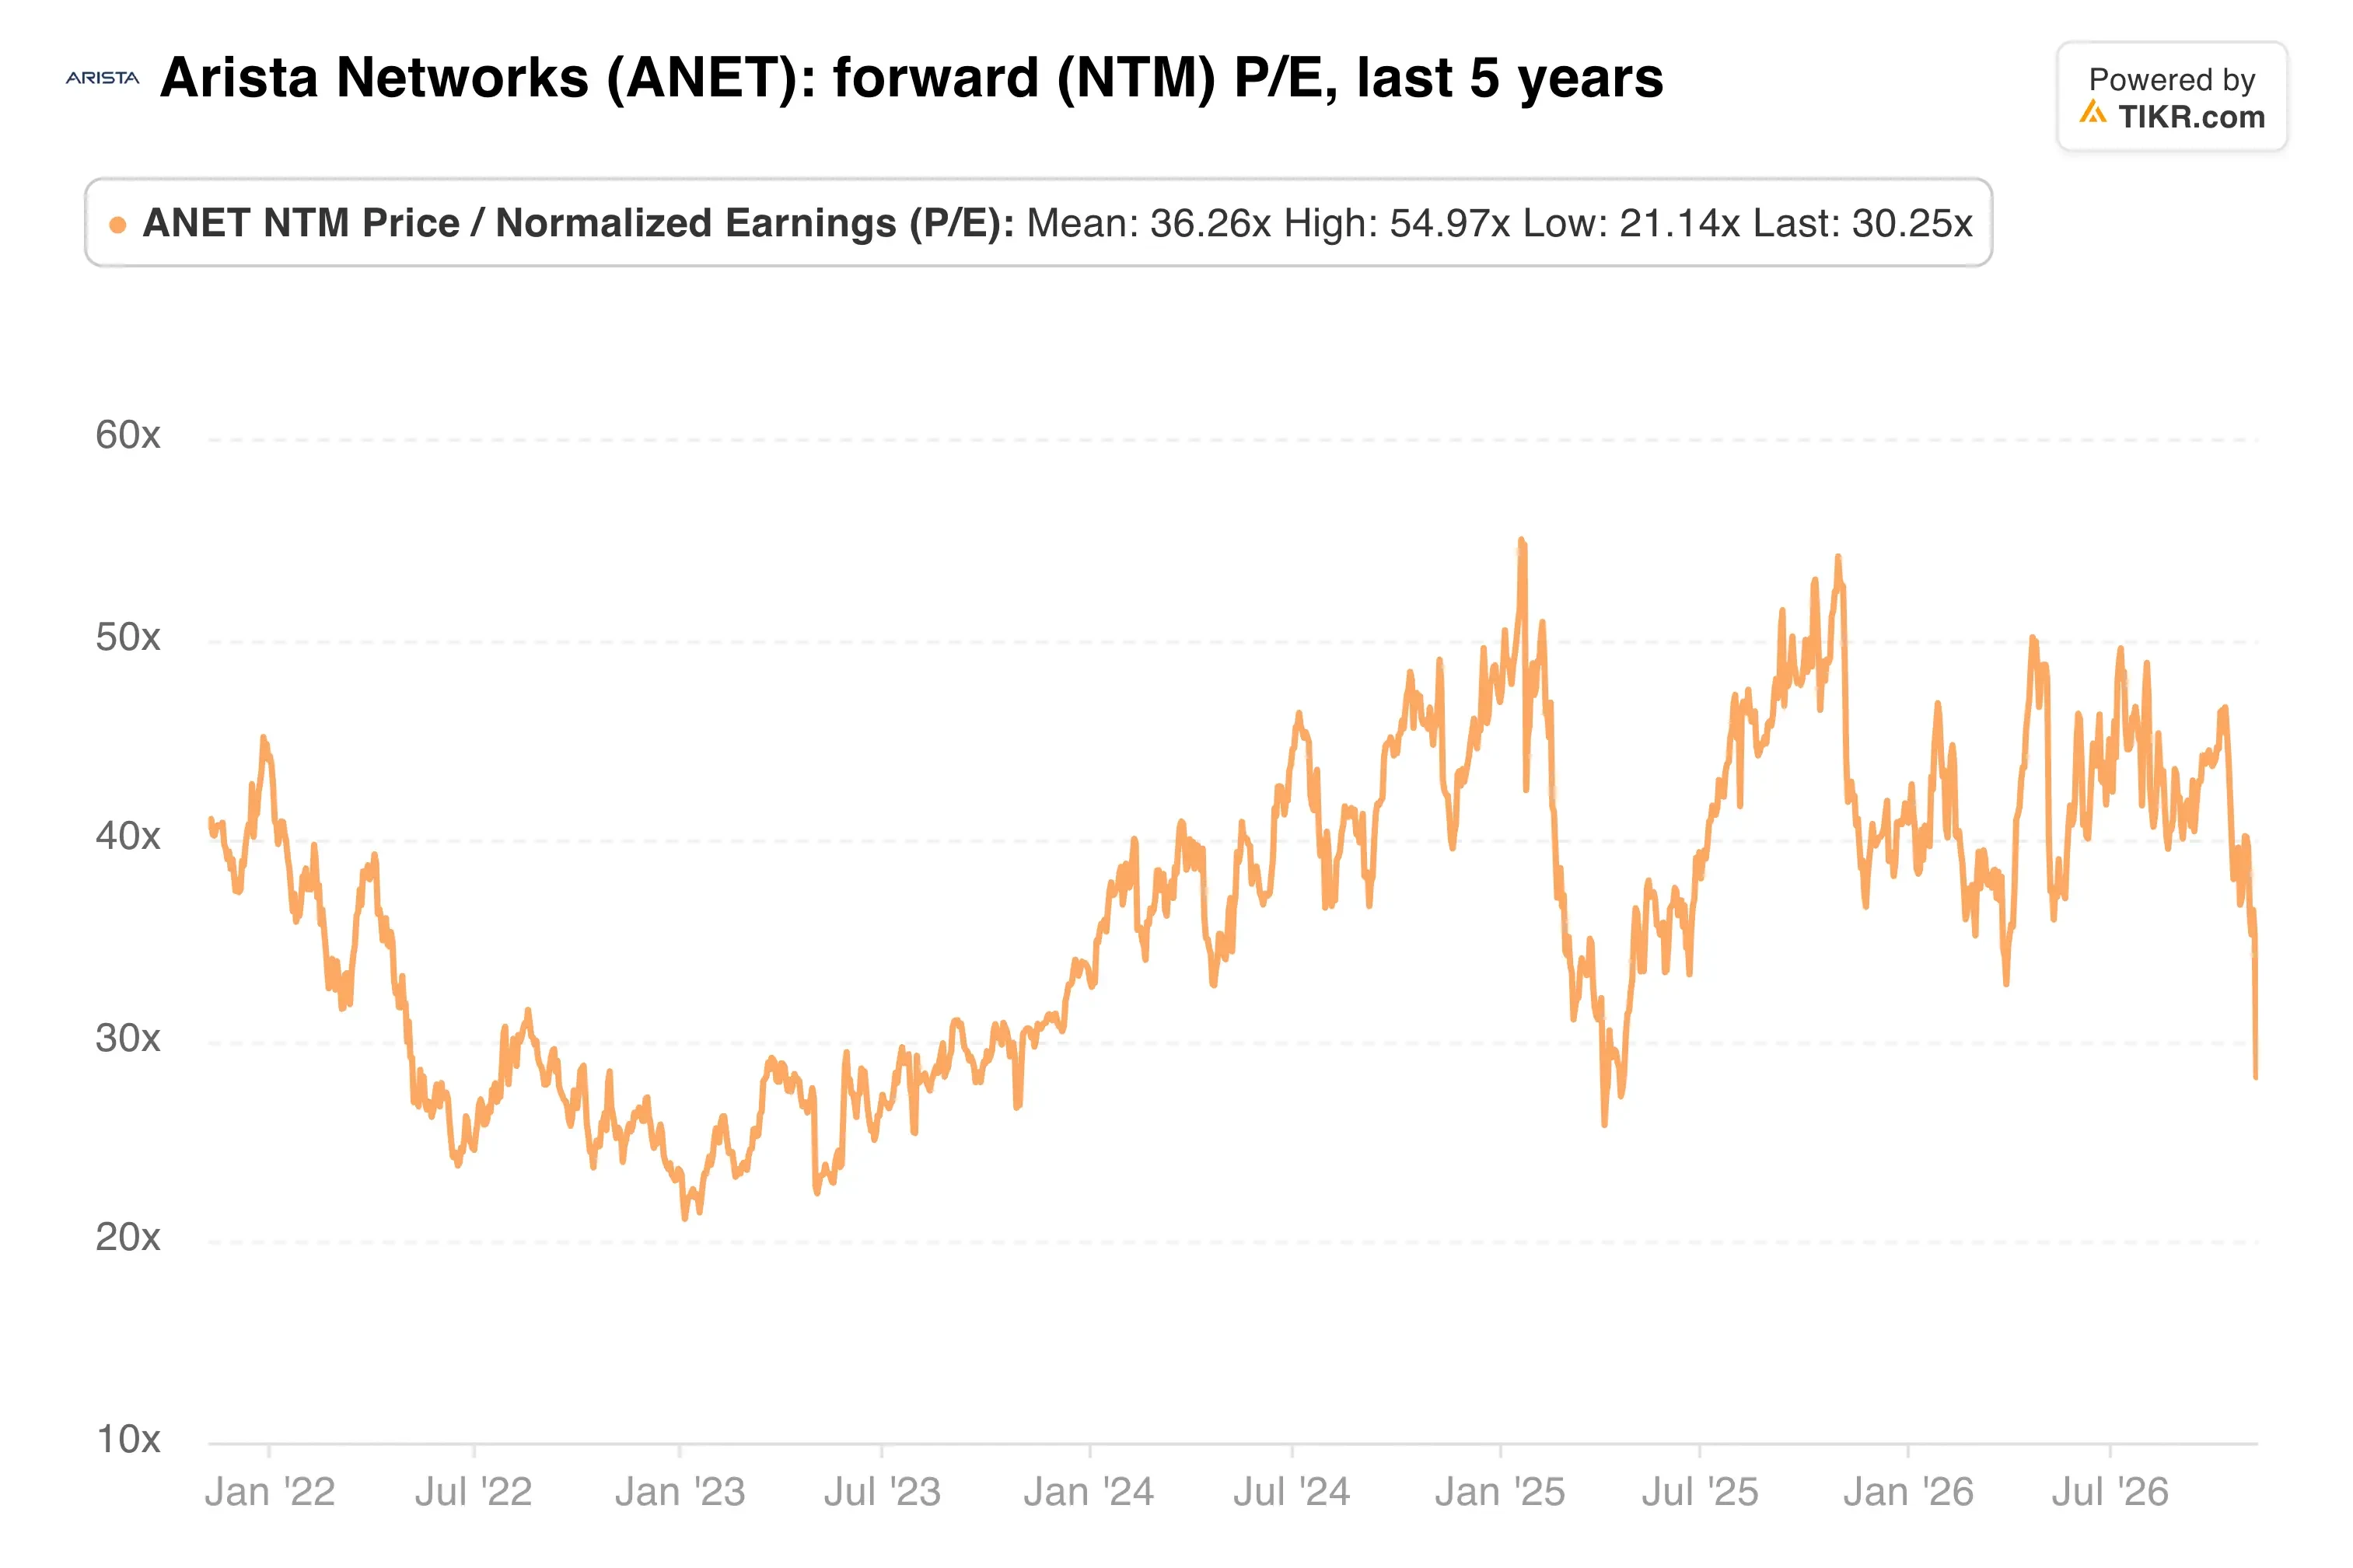
At about 30x forward earnings, Arista trades below its five-year average of about 36x. Wall Street’s average target of $250 implies 46% upside.
Insiders have sold into strength, however. Co-founder Andreas Bechtolsheim reported a $45.9 million sale this month, and Ullal sold about $30 million of shares in October.
My take: Arista is putting real money behind a 38% to 40% growth plan, yet its multiple now prices in less than that. I’d buy on weakness, and I’d treat gross margin as the number that could change my mind.
February 12 is the next checkpoint. Fourth-quarter revenue near $4 billion, with gross margin holding at 63% or better, would show the supply bet is paying off.
So what is Arista Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arista Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


