Key Takeaways
- AppLovin stock closed at $391 on Friday, up 71% in about a week after a record third quarter and a strong fourth-quarter guide.
- AppLovin bought back and withheld 4.1 million shares for $1.4 billion last quarter, then added $3.2 billion to its buyback authorization.
- Revenue grew 55%, while CFO Matt Stumpf said the largest ad platforms grew between roughly 10% and the mid-20s.
- February’s fourth-quarter report will show whether the rest of the model rollout keeps growth above 40%.
AppLovin (APP) closed at $391 on Friday, up 71% in about a week. The third quarter beat, the fourth-quarter guide beat, and the board gave management another $3.2 billion to spend on its own stock.
That last part says the most. AppLovin bought back and withheld 4.1 million shares for $1.4 billion in the third quarter, about $341 a share on average.
Still, the stock sits 47% below its 52-week high of $738.
Unity Software (U), its main rival for mobile game ad budgets, is also growing fast. Unity said revenue from its Vector ad platform rose 126% from a year earlier, so the category is expanding for both.
A record quarter on every line
AppLovin’s third quarter:
- Revenue up 55% to $2.18 billion, against about $2.08 billion expected
- Net income up 72% to $1.44 billion, a 66% margin
- Diluted EPS of $4.30, against a $4.04 estimate
Revenue grew 14% from the second quarter alone…
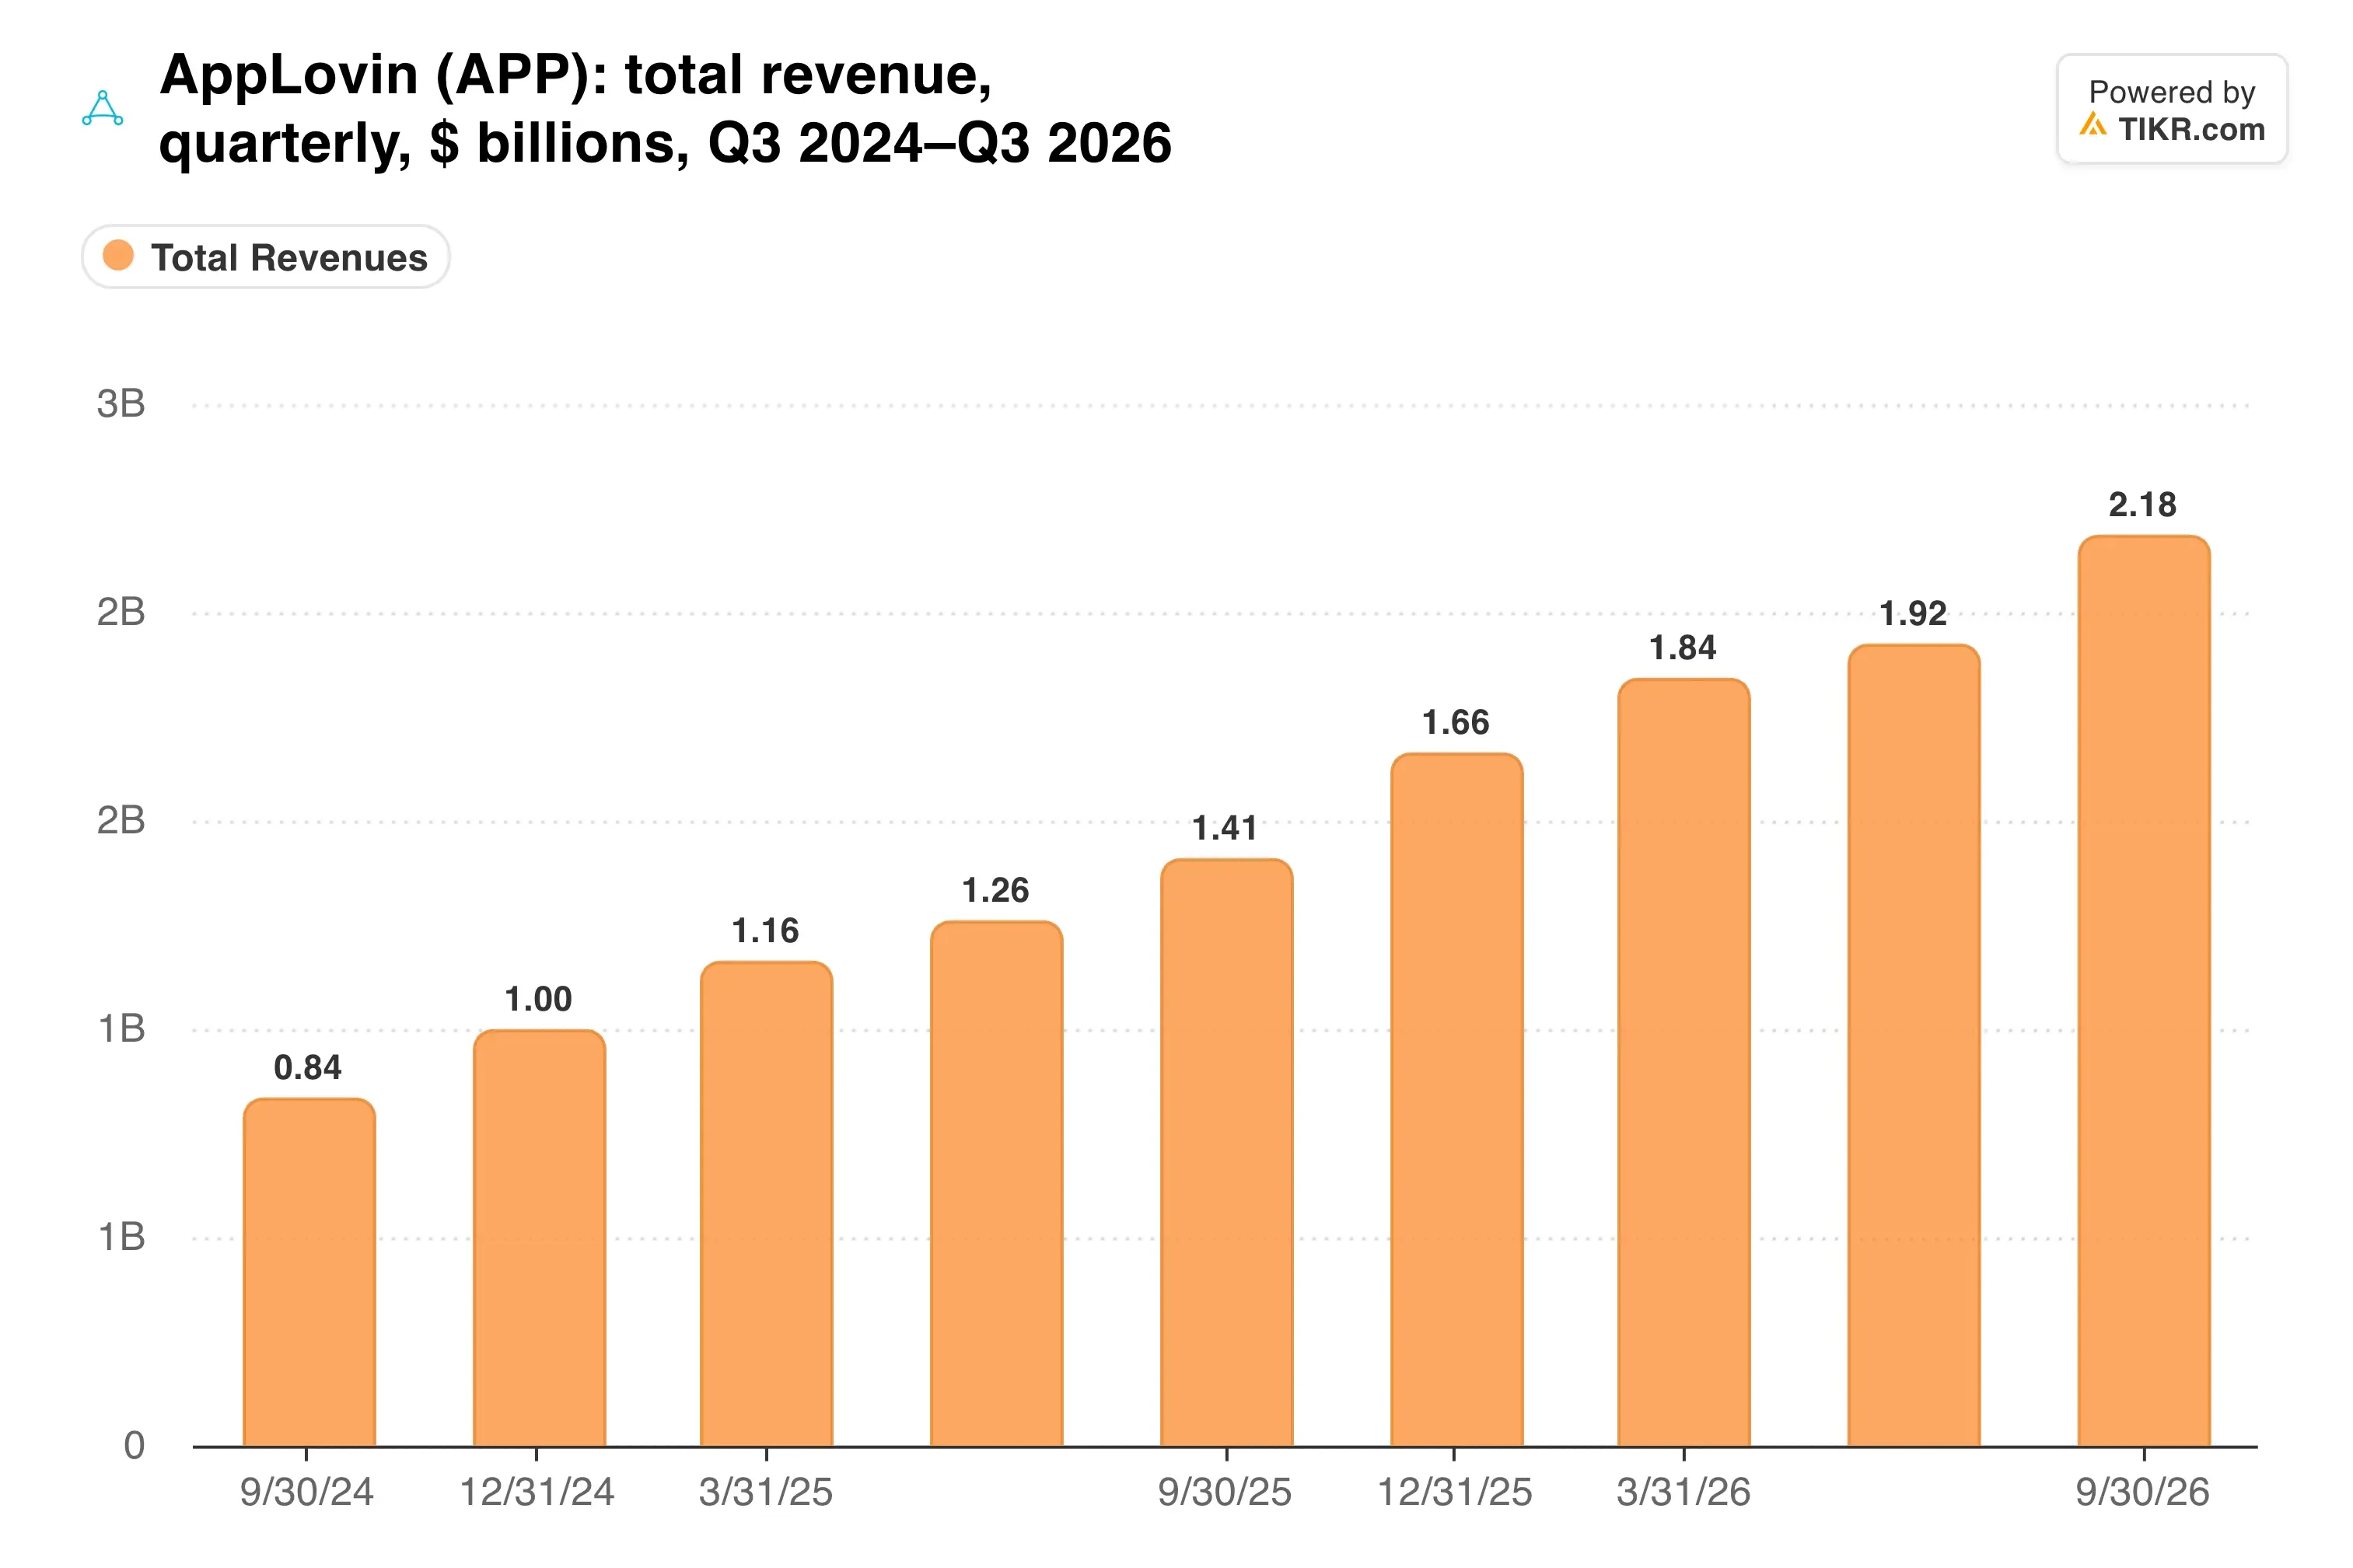
The fourth-quarter guide calls for $2.365 billion to $2.395 billion of revenue, up 43% to 44%, and adjusted EBITDA of $1.995 billion to $2.025 billion. Analysts had expected about $2.25 billion of revenue.
Gaming carries, consumer follows
CEO Adam Foroughi said the gaming business grew nearly 50%, “re-accelerating right alongside the rollout” of its new ad models.
He was also candid about how much room is left in games: “We have every mobile gaming company live, probably.”
So the next leg is consumer advertising, which covers e-commerce and other non-gaming brands. Foroughi said that business is growing at triple digits from a year ago.
For context, Stumpf said the largest digital ad platforms grew between roughly 10% and the mid-20s this earnings season. AppLovin grew 55%.
Nearly all of that profit turns into cash, and more of it is going back to shareholders:
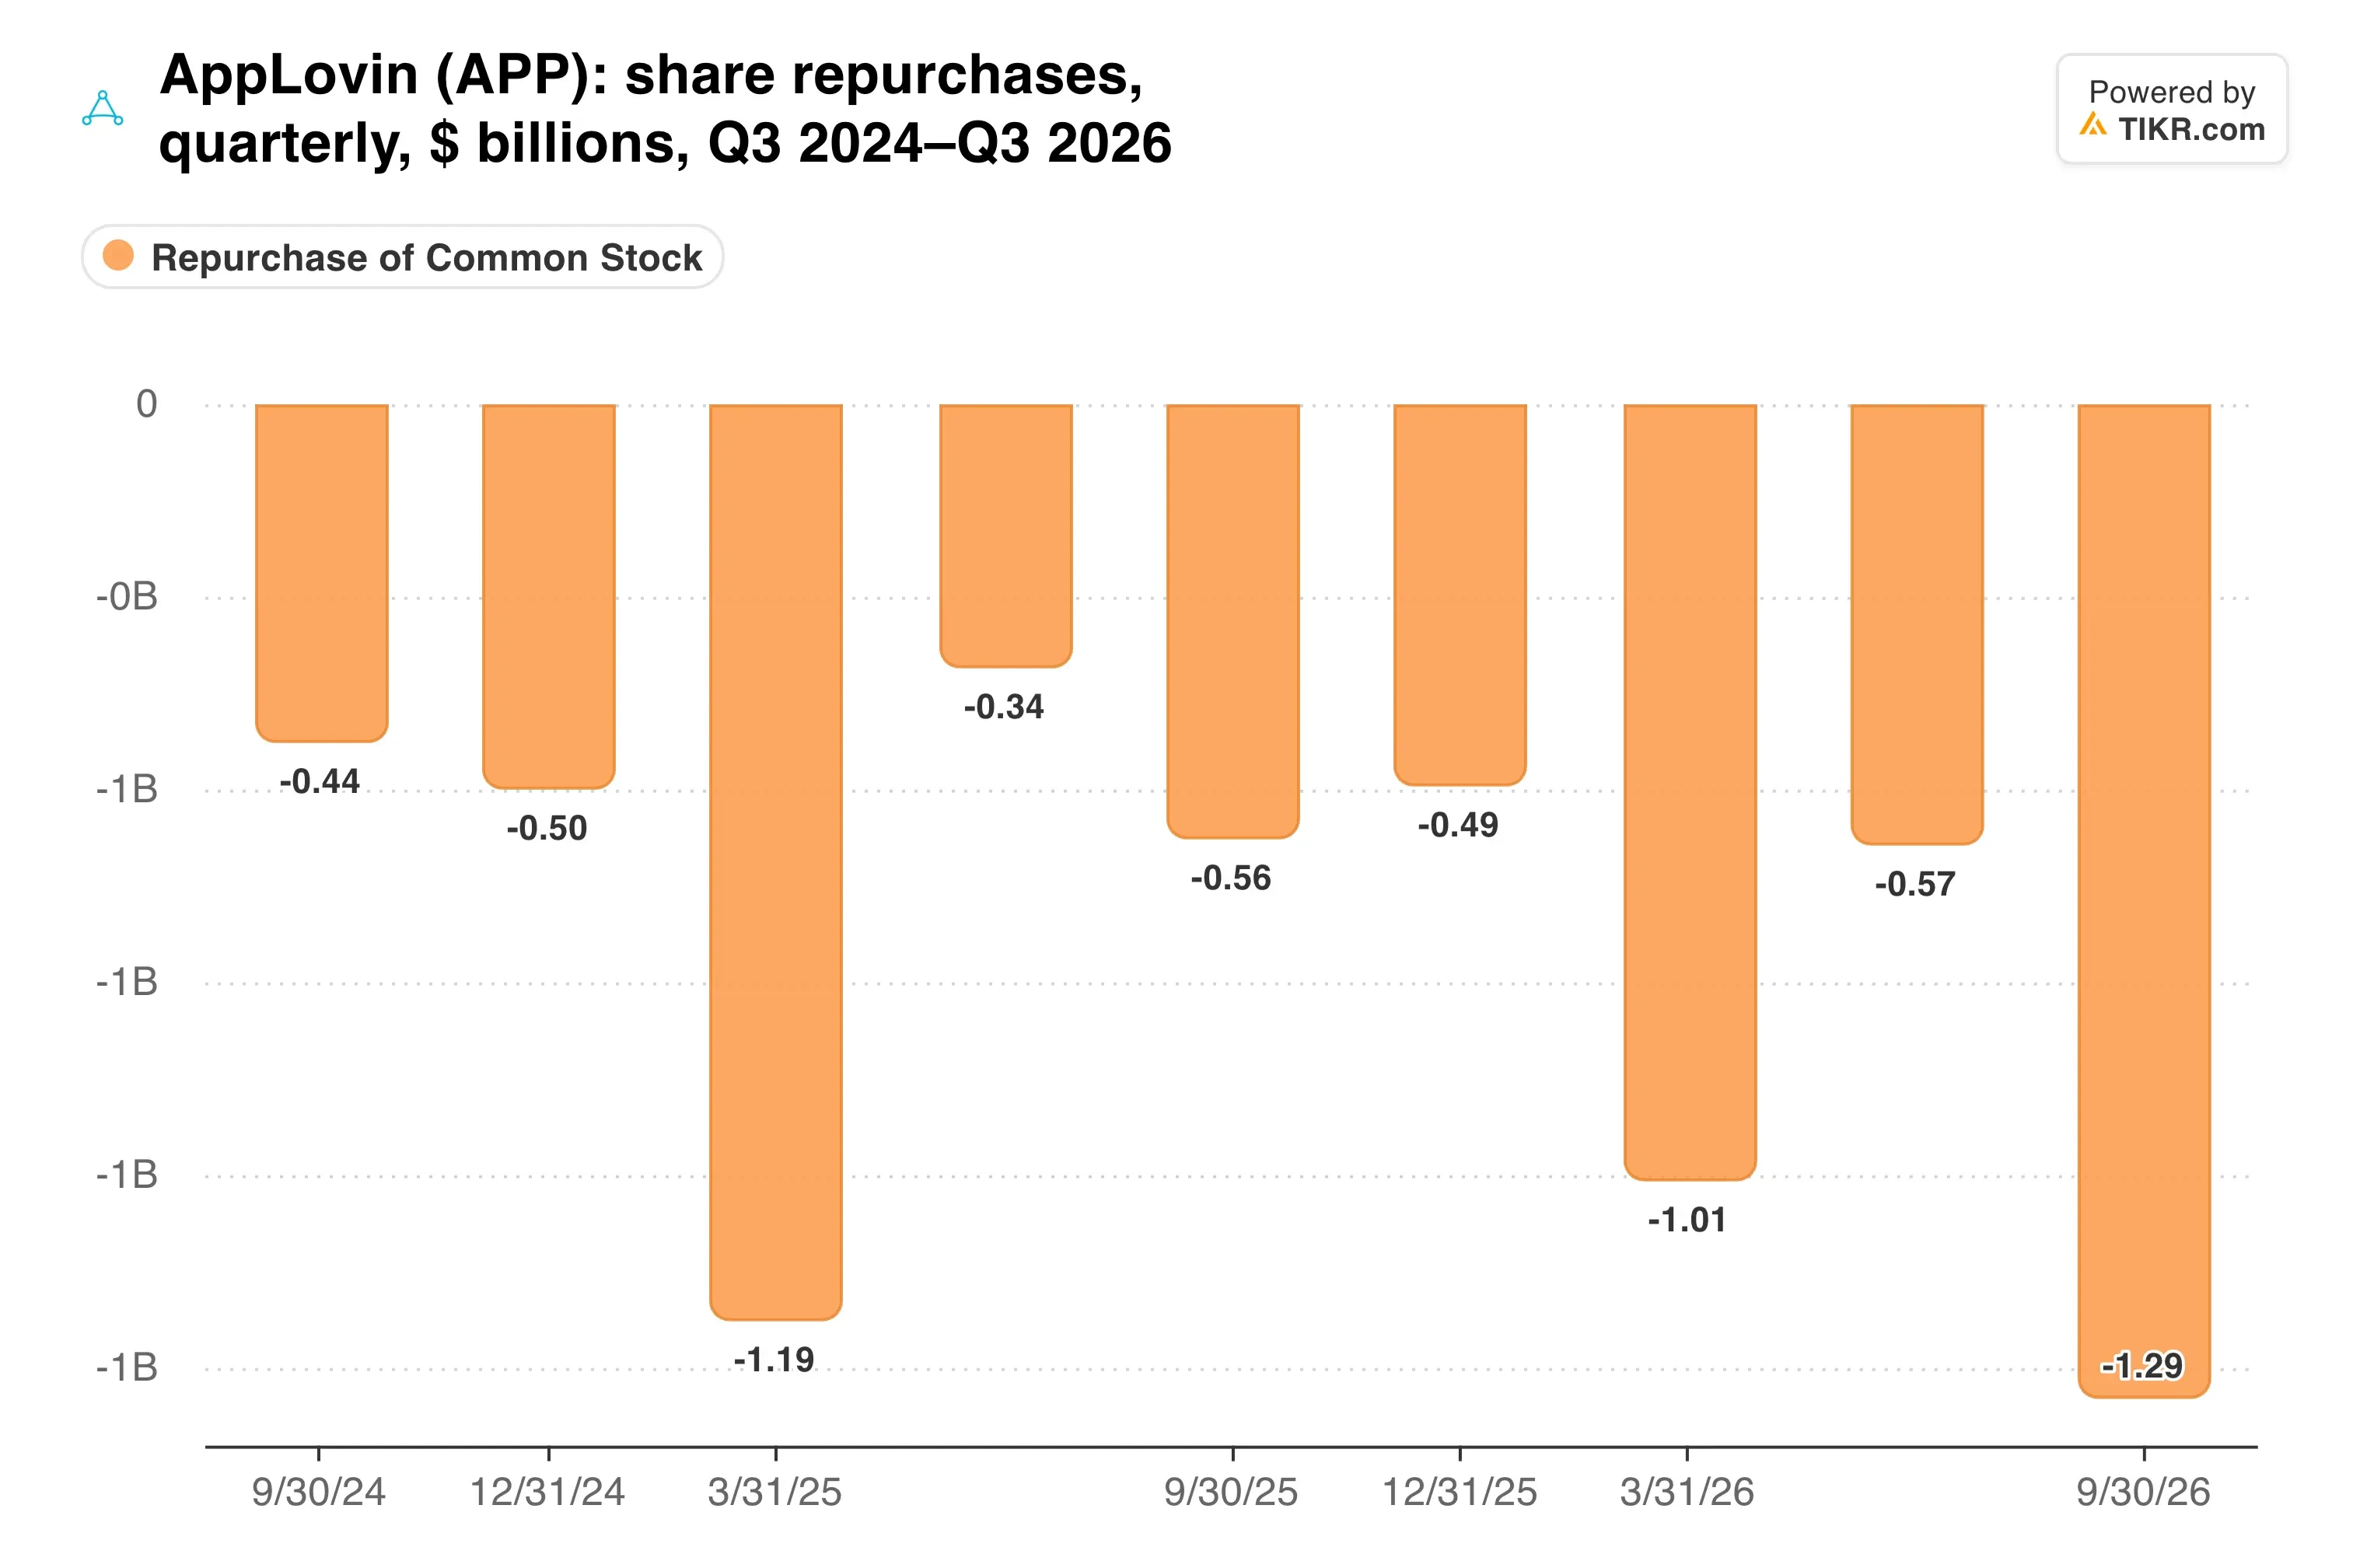
Net debt has also dropped to about $342 million, from roughly $1 billion at the start of the year, so the new authorization has room to run.
TIKR tracks 33 analysts on AppLovin. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AppLovin, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AppLovin’s Analyst Ratings
What the rebound leaves
So how much of the recovery is already in the price?
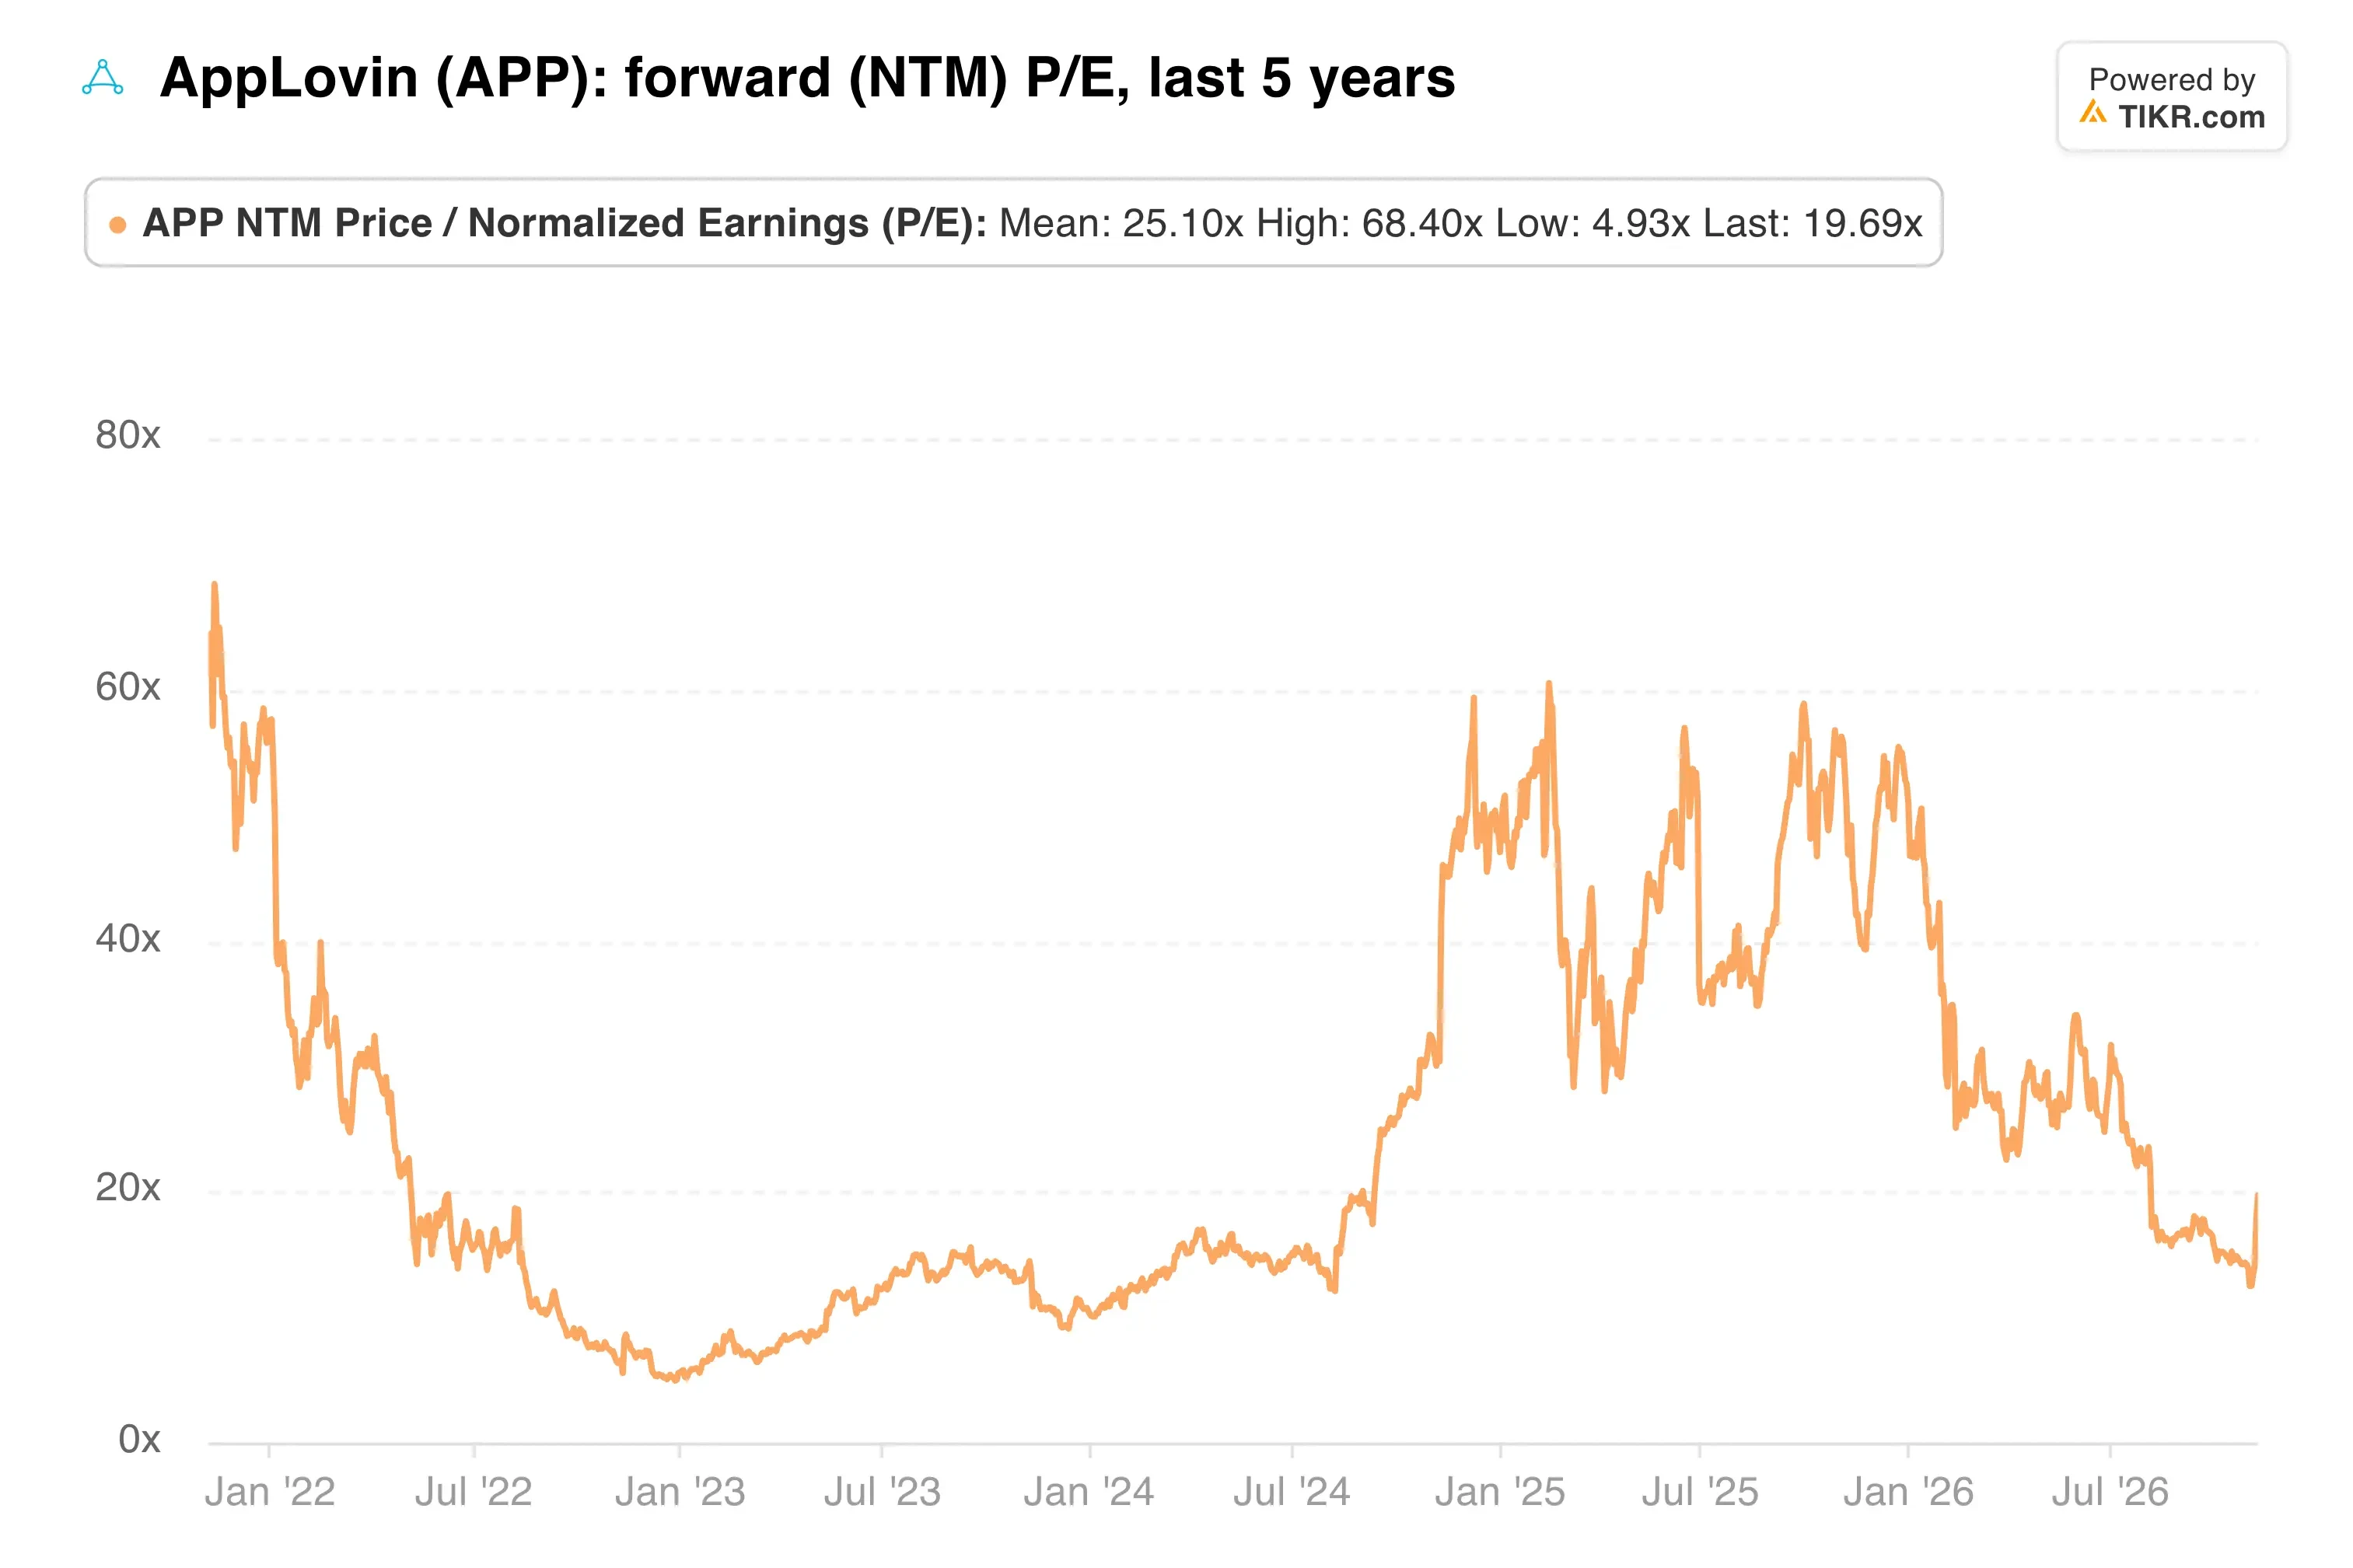
Even after the jump, AppLovin trades at 19.7x forward earnings, below its five-year average of about 25x. Analysts expect EPS to grow about 39.5% a year over the next two years, and Wall Street’s average target of $460 implies 17.5% more upside.
The risks haven’t disappeared. Foroughi said the new models are only partly rolled out, and he couldn’t commit to a date for the full rollout. A securities class action over AppLovin’s AI disclosures is also pending, while holiday spending flatters any fourth quarter.
My take: Management bought $1.4 billion of stock near the lows and then authorized more, so it clearly sees value at these prices. At under 20x earnings, AppLovin still looks cheap to me, although the easy part of the rebound is done.
The next test is the fourth-quarter report, expected around February 10. Revenue near the top of the guide, with consumer advertising still growing at triple digits, would show this quarter wasn’t a one-off.
So what is AppLovin stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AppLovin could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!