Key Takeaways
- Palo Alto Networks reports fiscal first-quarter results on November 18, with revenue guided to $3.30 billion to $3.31 billion, up 33% to 34%.
- Adjusted EPS is guided to $0.96 to $0.98, only about 4% above last year’s $0.93, because the CyberArk deal swelled the share count.
- Fortinet fell more than 25% after its product growth slowed to 37%, which shows how little room premium security stocks have.
- At 75x forward earnings, Palo Alto needs NGS ARR of about $9.55 billion and a reaffirmed fiscal 2027 outlook.
Palo Alto Networks (PANW) reports fiscal first-quarter results after the close on Wednesday, November 18. The setup is unusual: revenue is guided up about a third, but adjusted EPS only about 4%.
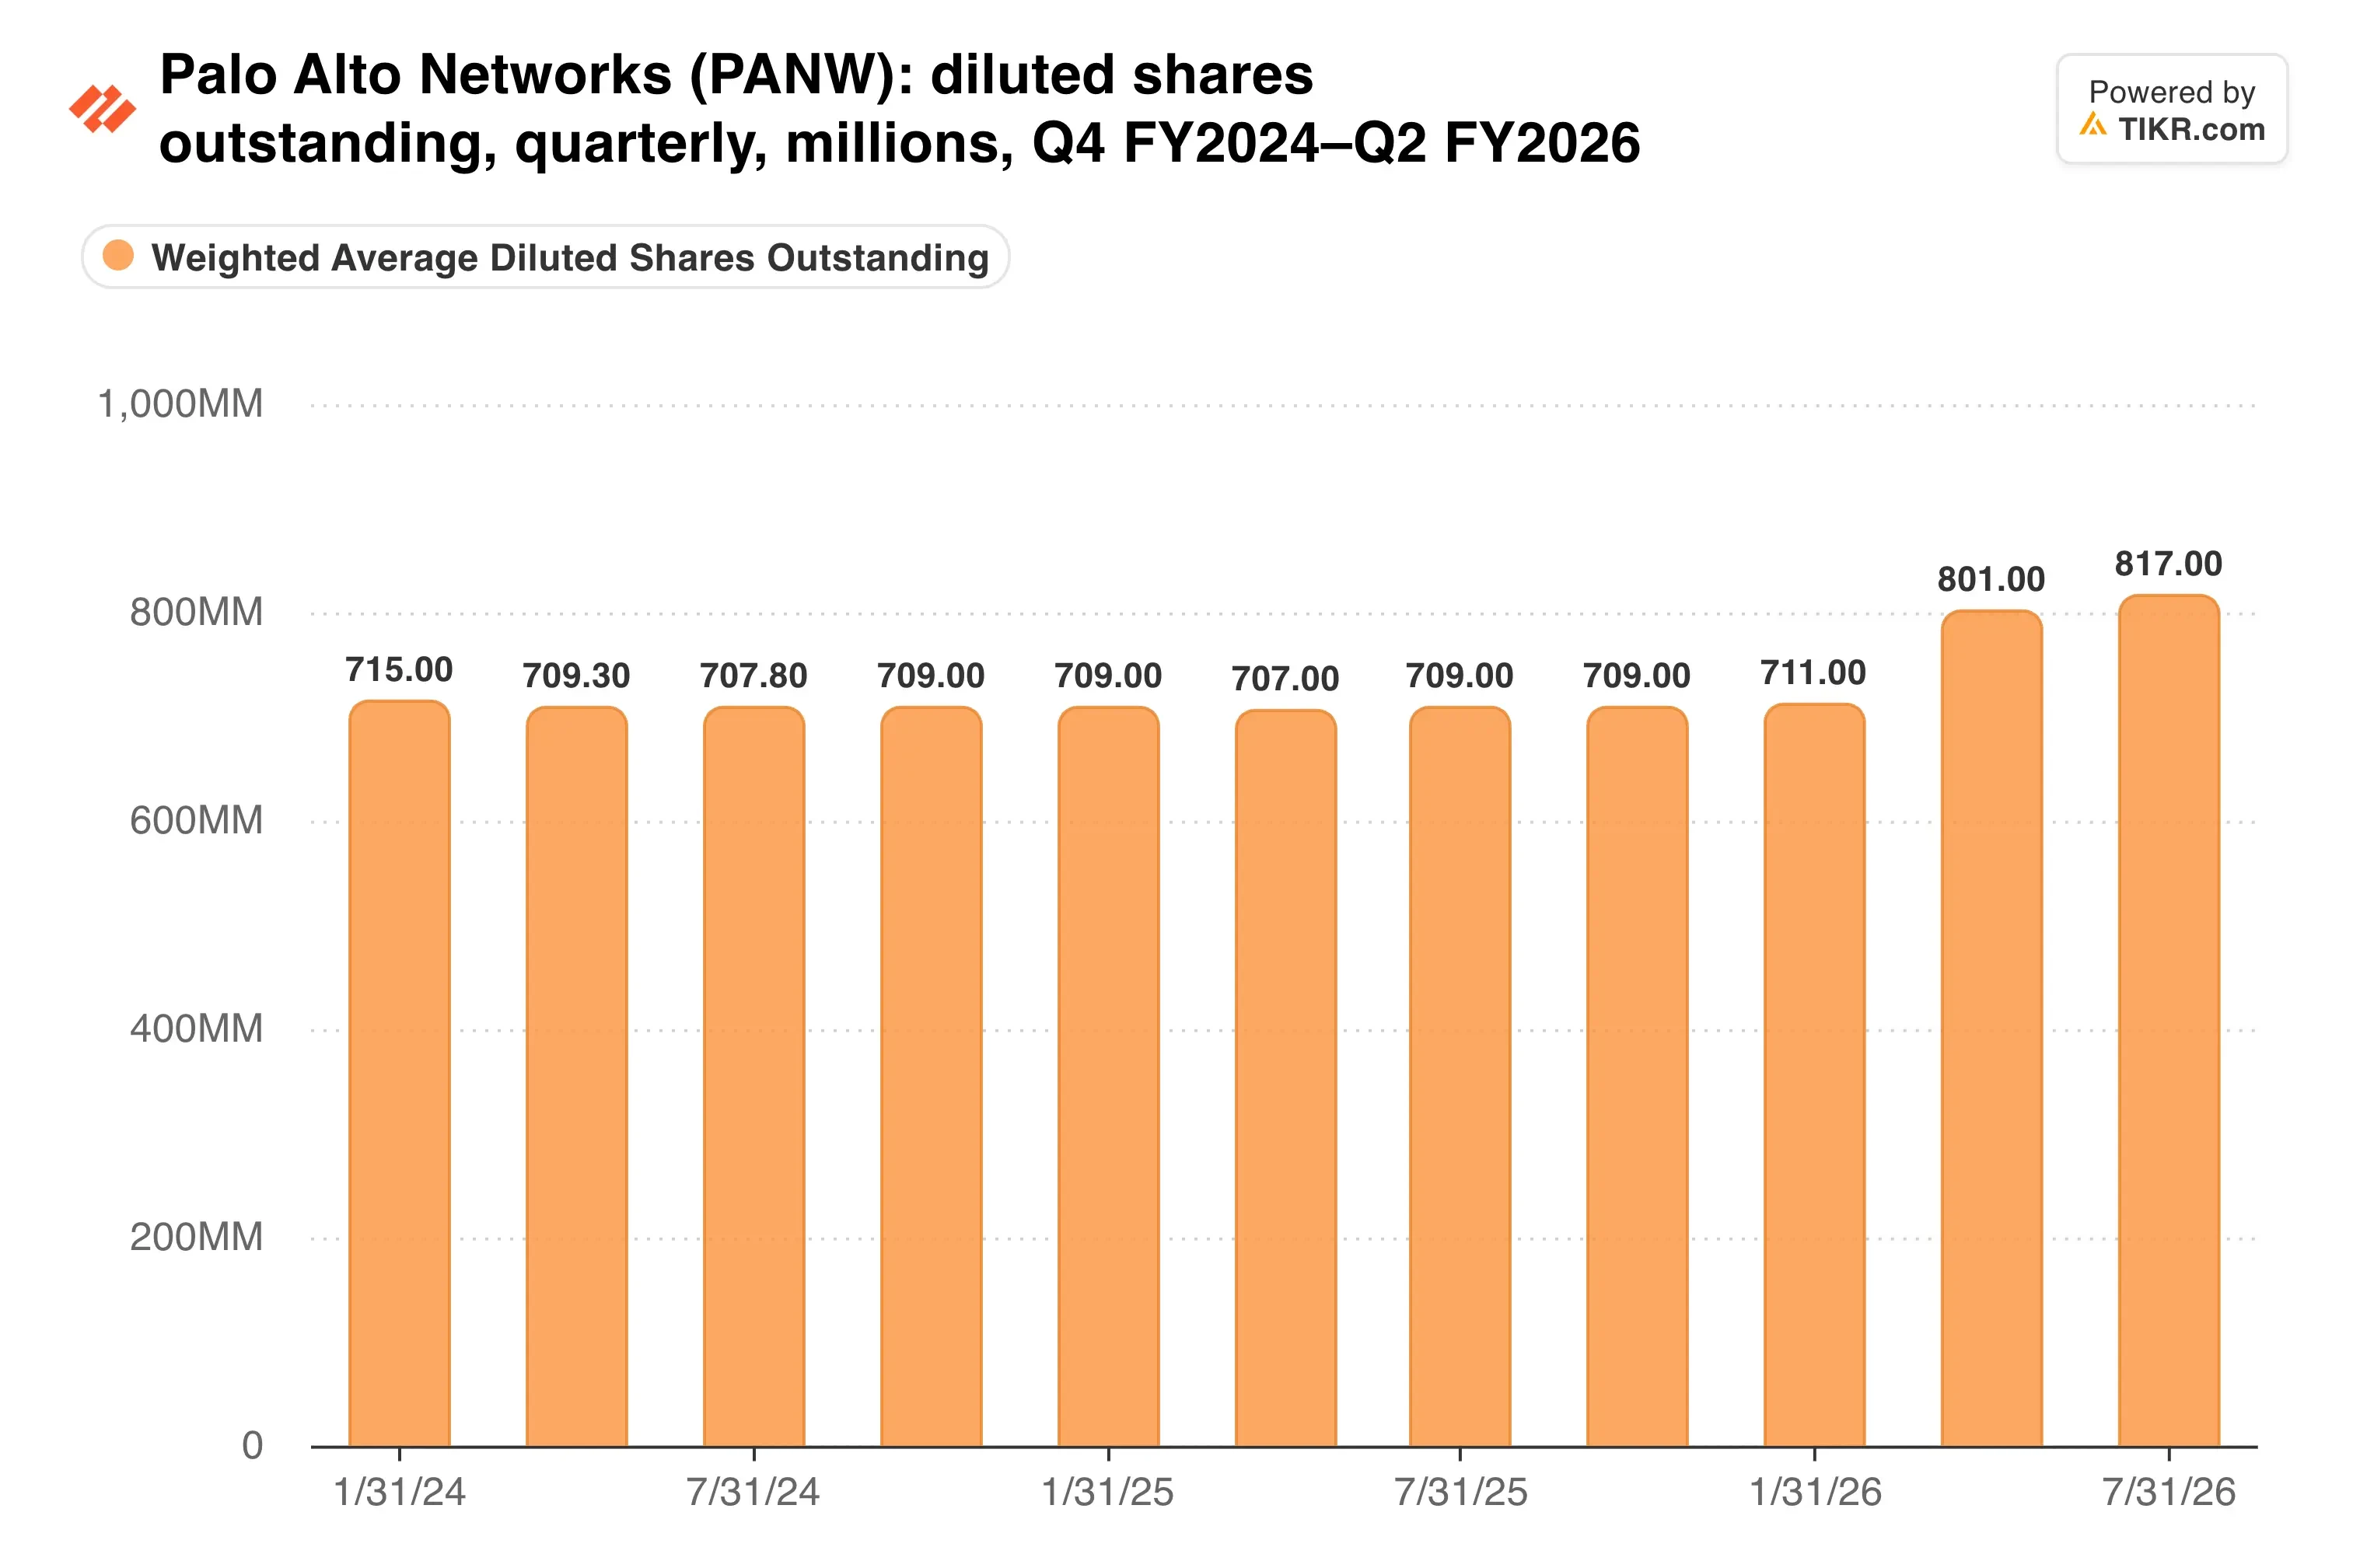
That gap is the cost of CyberArk. Palo Alto paid for the $25 billion identity deal largely in stock, and its share count rose to about 818 million from 668 million in July 2025.
The stock closed Friday at $314, down 11% for the week and 27% below its 52-week high.
Fortinet (FTNT) shows what a stretched security stock risks. It beat estimates on October 29 and still fell more than 25% as product revenue growth slowed to 37% from 52%.
The bar for November 18
Palo Alto guided the quarter to:
- Revenue of $3.30 billion to $3.31 billion, up 33% to 34%
- NGS ARR of $9.54 billion to $9.56 billion, up 63%
- Adjusted EPS of $0.96 to $0.98
Consensus sits right inside that range, at $3.31 billion and $0.97.
Last quarter gave it a strong base. Fiscal fourth-quarter revenue rose 34% to $3.41 billion, and Palo Alto added nearly $1 billion of net new NGS ARR in a single quarter.
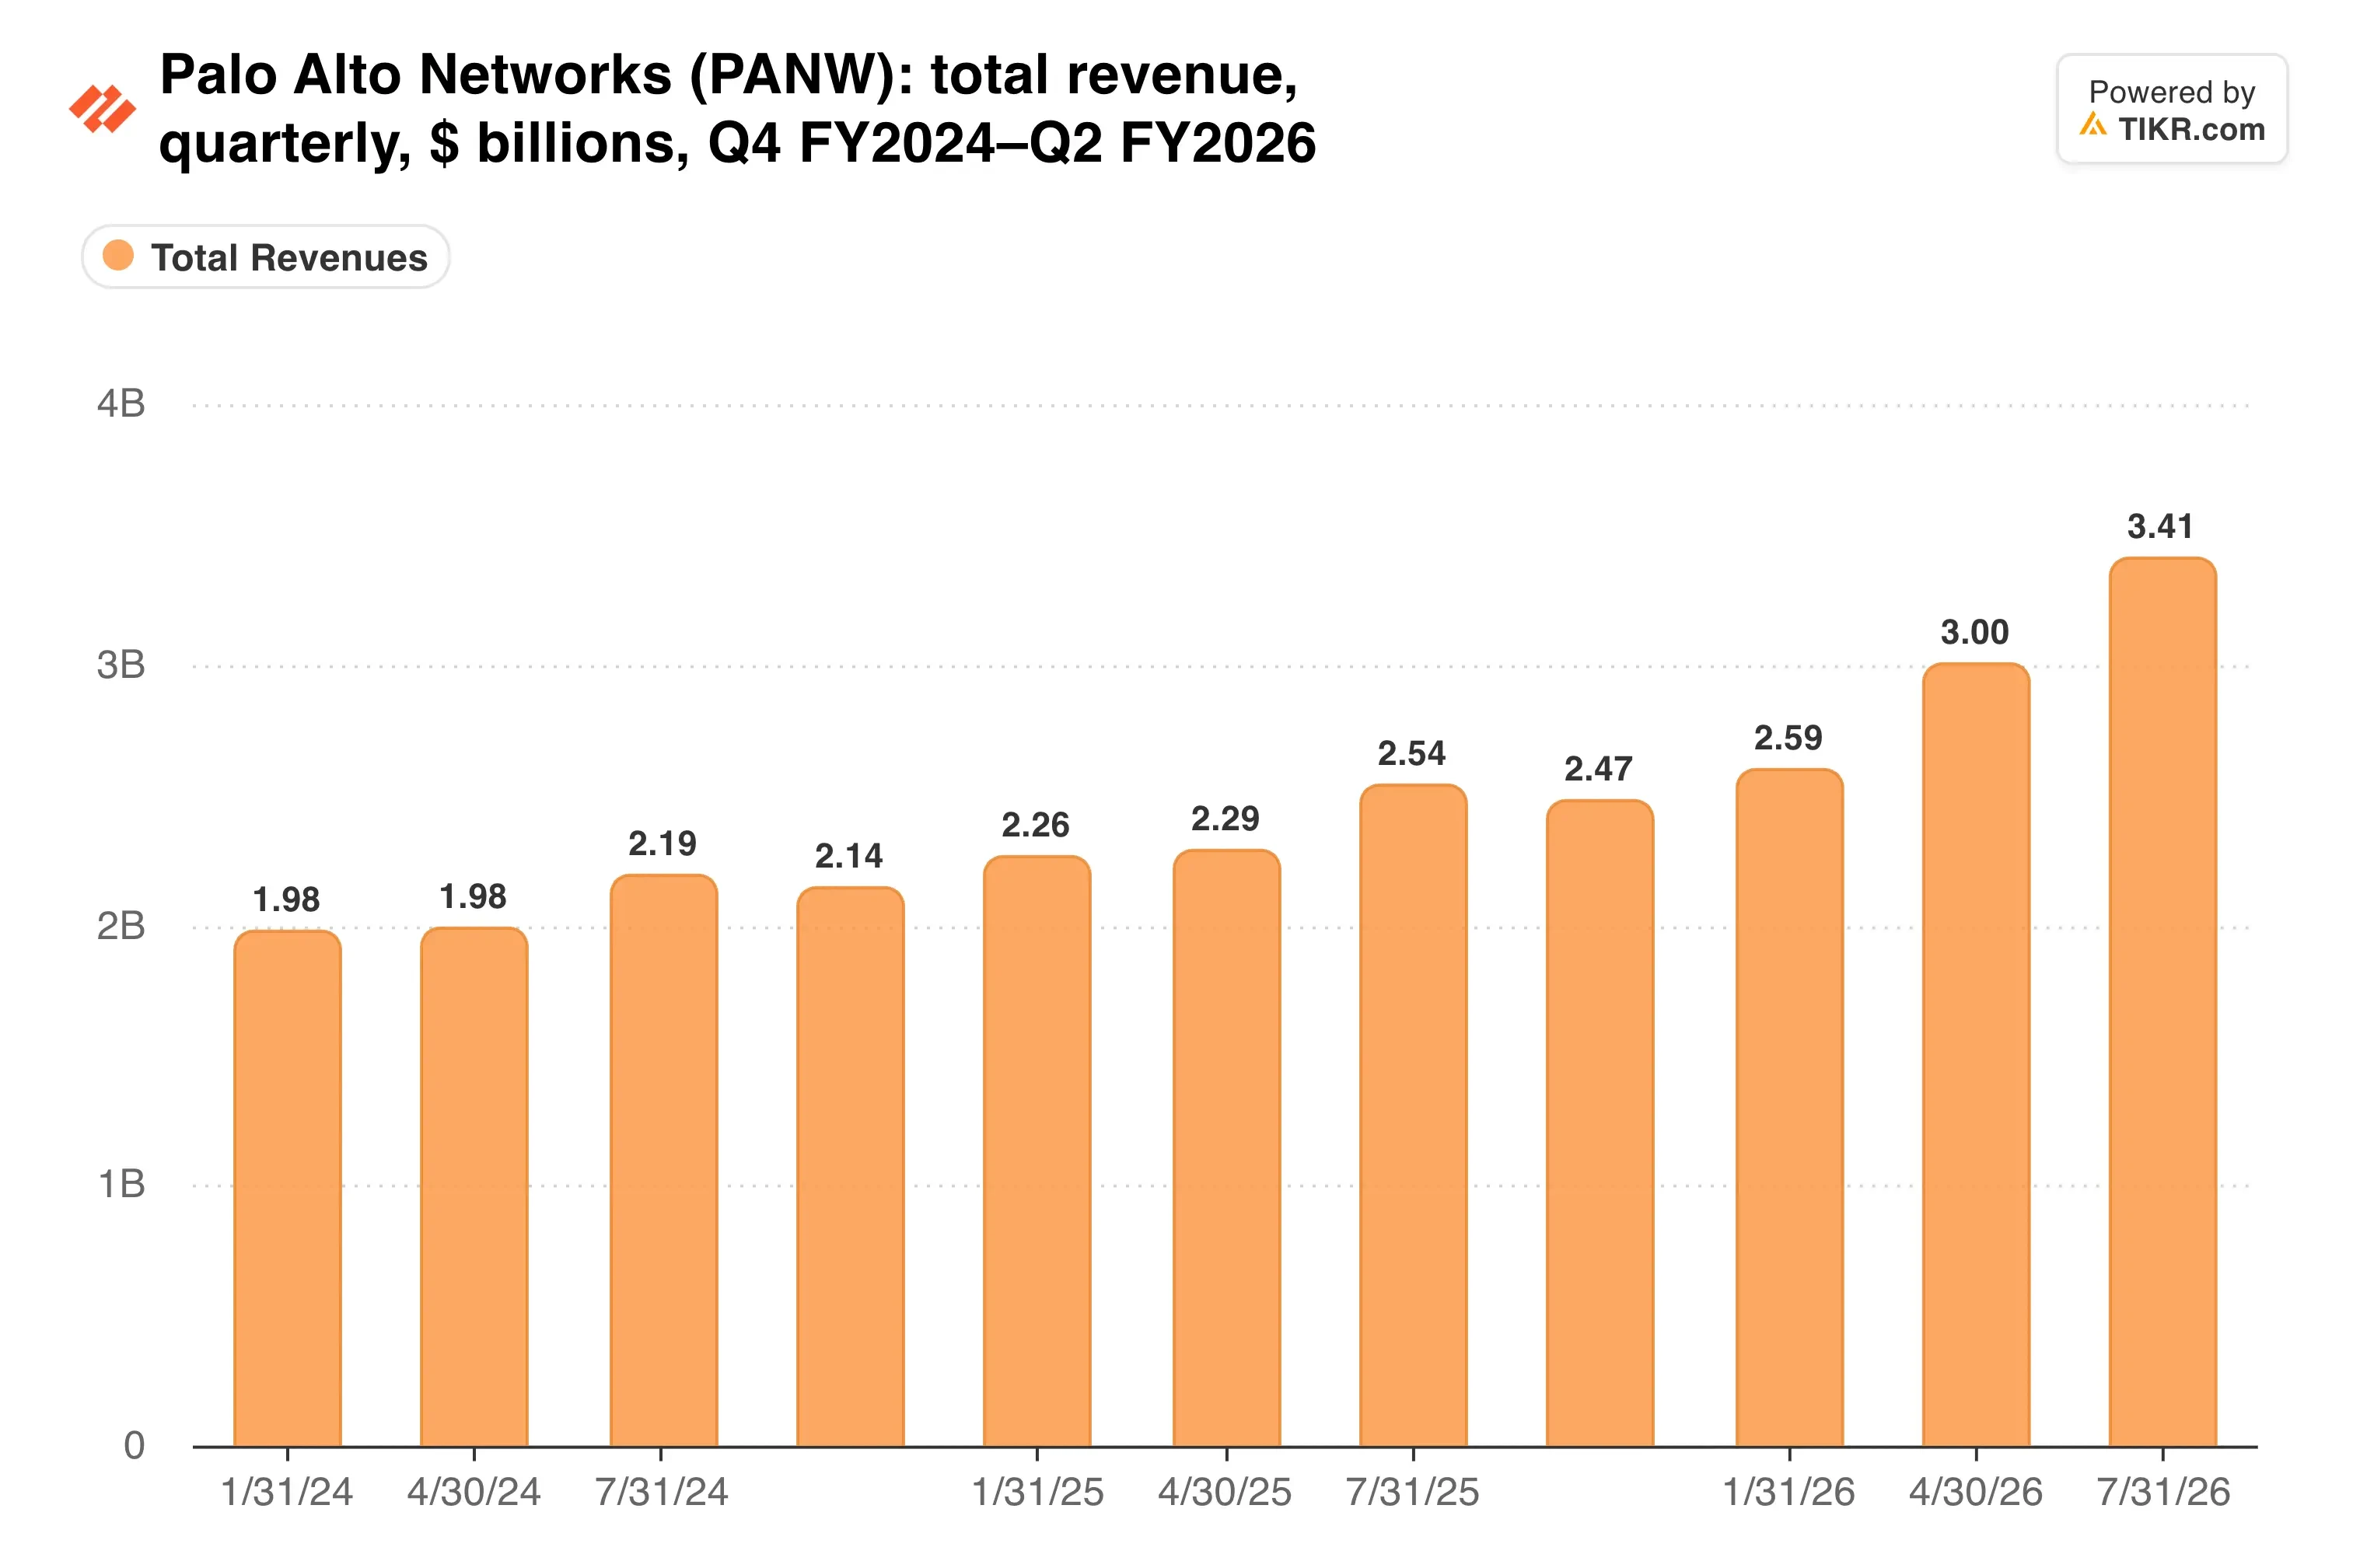
A big part of that jump came with CyberArk, which closed in February. So the headline growth rates will look very different once that deal laps.
Growth paid for in shares
The fiscal 2027 outlook already shows the slowdown. Palo Alto guides revenue to $14.1 billion to $14.2 billion, up 23% to 24%, and NGS ARR growth of 22% to 23%, down from 63%.
Per share, the math is tighter. Full-year adjusted EPS is guided to $4.16 to $4.19, on as many as 847 million shares. Here’s how quickly that count climbed…
CEO Nikesh Arora argues the demand will last. In the fiscal fourth-quarter release, he said AI advances “are elevating cybersecurity to the top of the CIO priority list.”
Palo Alto is still buying, too. It’s in talks to pay $500 million for AI security startup Clutch Security, according to The Information.
Margins are the other thing to watch. Adjusted gross margin narrowed about a point to 74.8% last quarter, and CFO Dipak Golechha said cloud hosting costs will grow faster than revenue this fiscal year.
TIKR tracks 56 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
Priced for no stumbles
Fortinet’s drop came from a stock that still grew revenue 20% and guided fourth-quarter growth of 15%. Investors were paying for more. So where does Palo Alto’s multiple sit next to it?
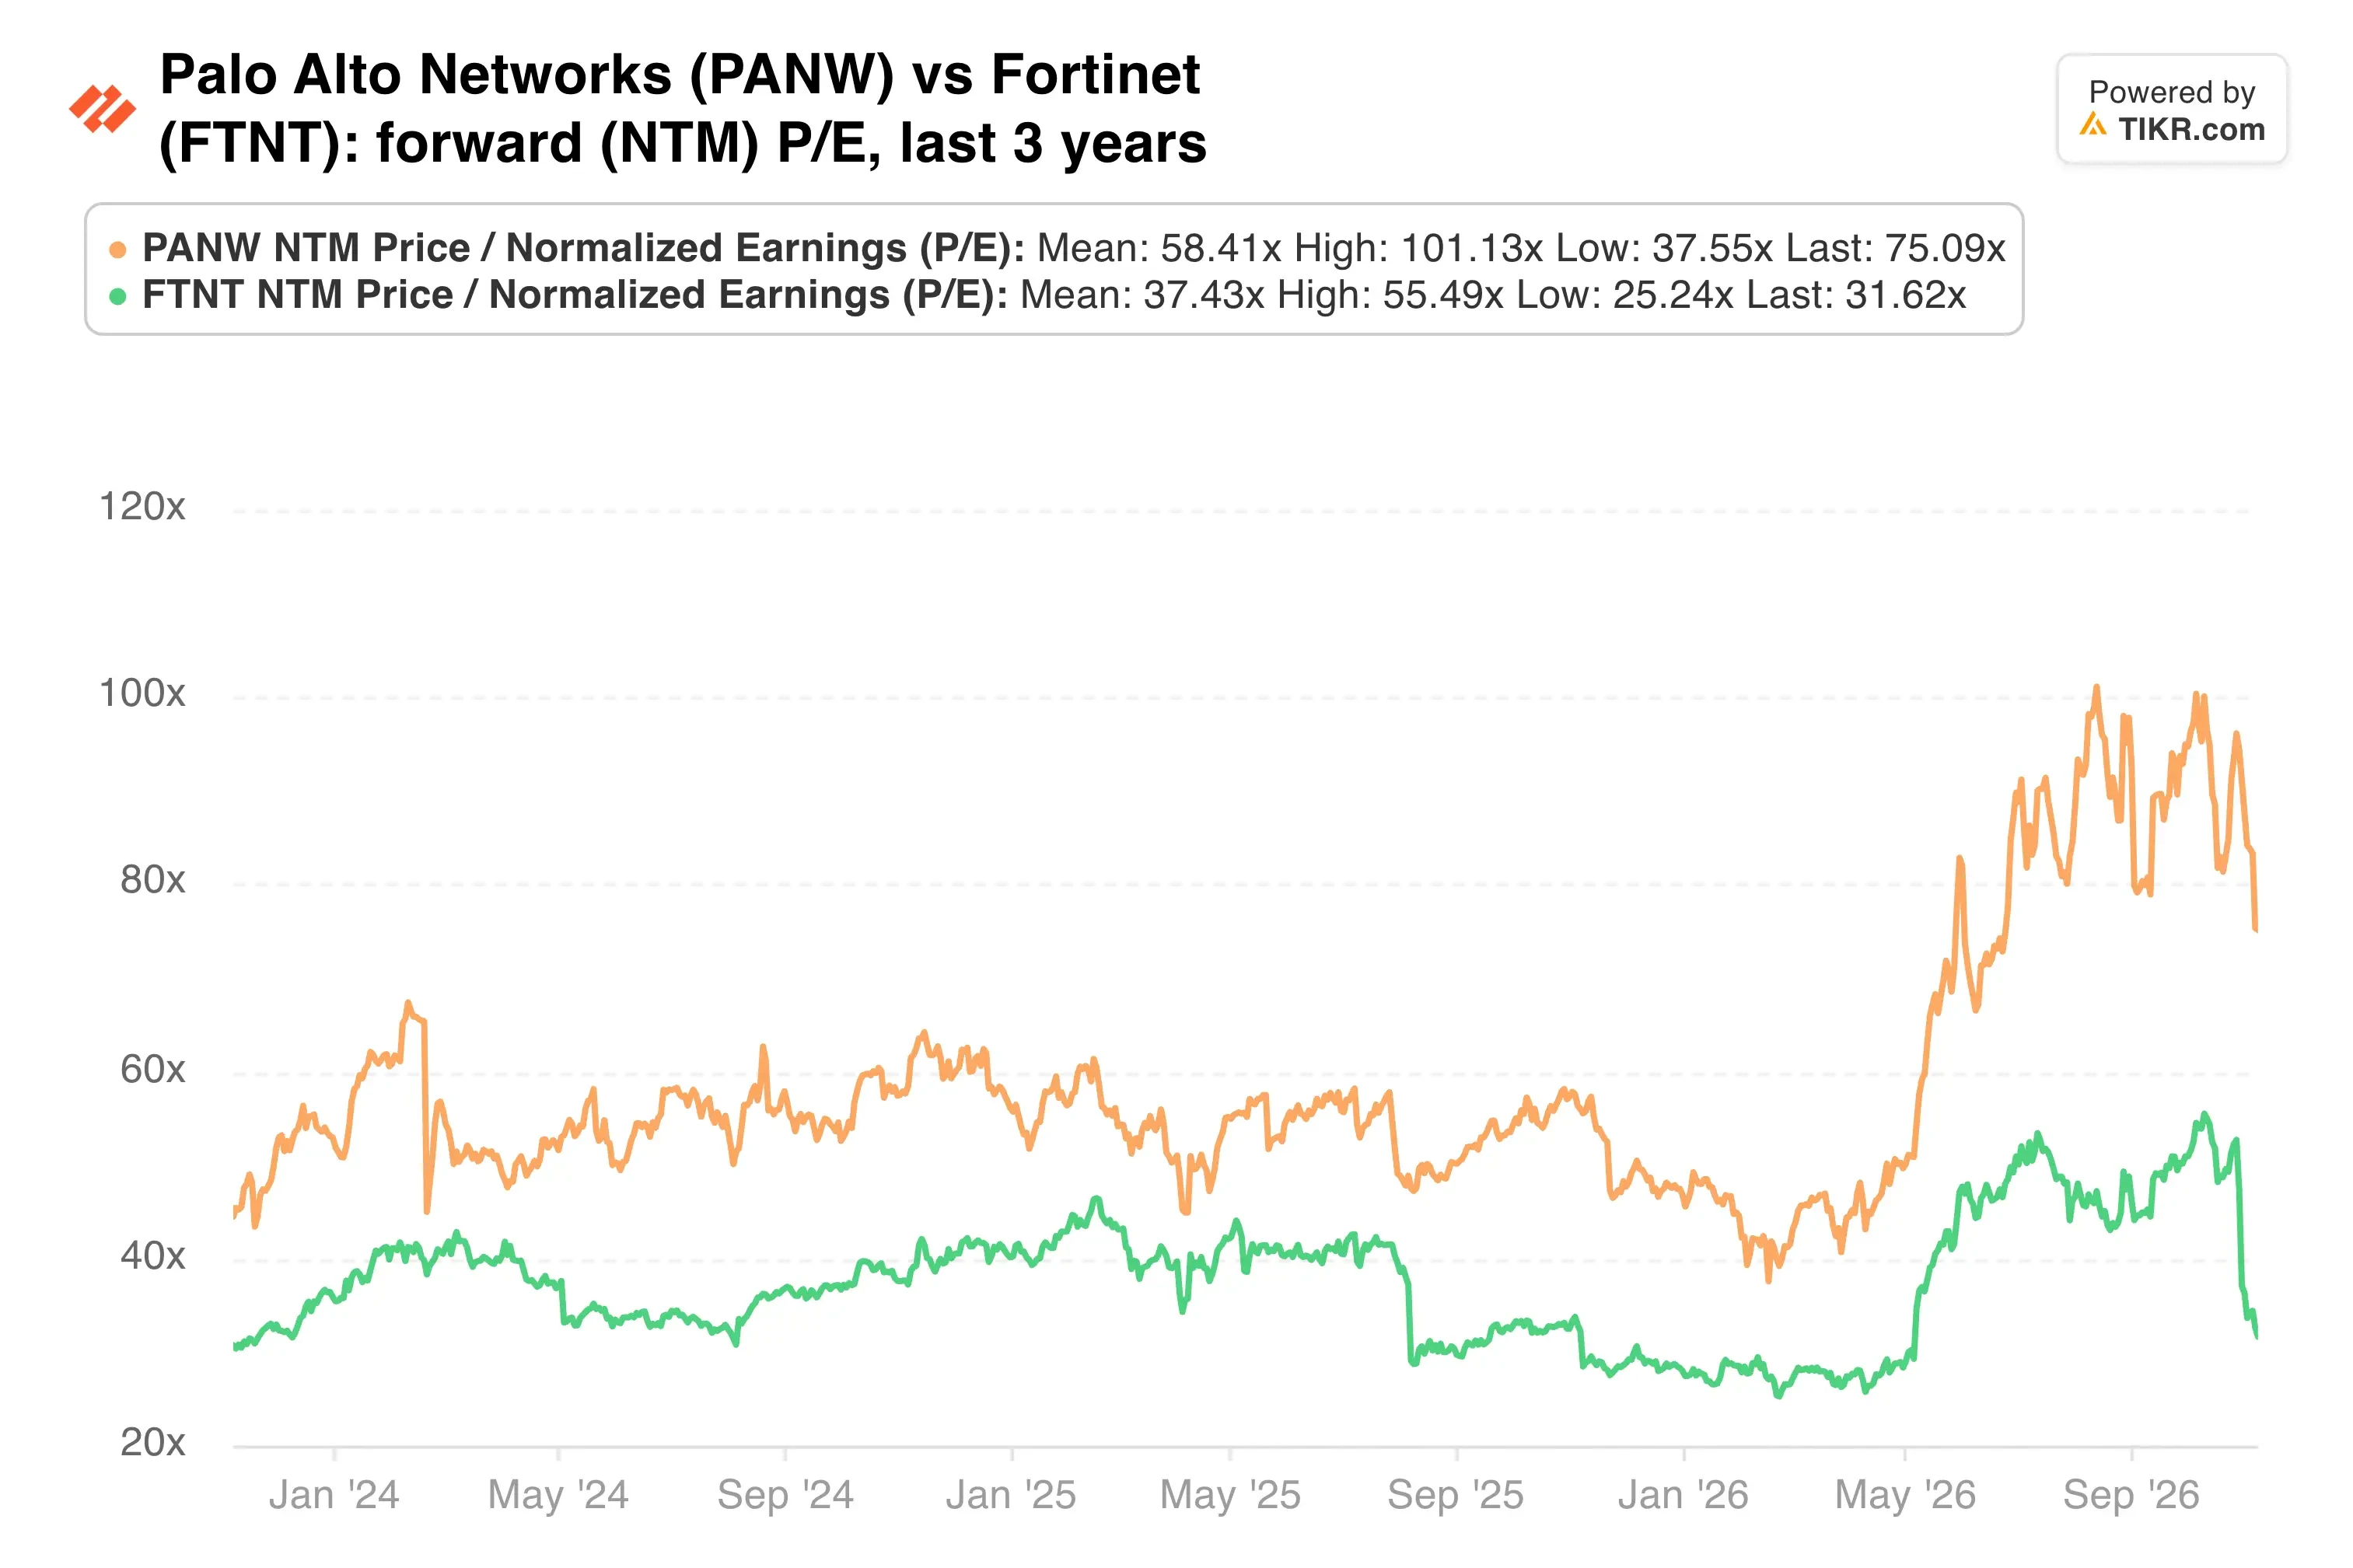
At 75x forward earnings, Palo Alto carries far more expectation than Fortinet did going into its report.
Insiders have been selling into the rally. President William Jenkins reported two sales this month worth about $71 million combined.
Wall Street’s average target of $400 still implies 27% upside. That case leans on fiscal 2028, once CyberArk is fully in the base and Palo Alto reaches its 40% adjusted free cash flow margin target.
My take: The business is executing, and the AI security demand Arora describes looks real. But a stock at 75x earnings, guiding 4% EPS growth this quarter, needs every number to land. I’d wait for the report before buying.
November 18 is the checkpoint. NGS ARR at or above $9.56 billion, along with a reaffirmed fiscal 2027 revenue guide, would show the CyberArk integration is holding up.
So what is Palo Alto Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!