Key Takeaways
- SoFi’s adjusted net revenue rose 44% to a record $1.4 billion, and EPS of $0.18 beat the $0.17 consensus.
- The company raised 2026 revenue guidance to $5.04 billion and guided 2027 EPS to $0.90, about 48% above this year’s $0.61.
- Shares still sit near $16, about 41% below the $27.50 price of last December’s $1.5 billion stock sale.
- SoFi Plus growth missed internal plans, and the fourth-quarter report, expected around January 25, will show whether member growth holds.
SoFi Technologies (SOFI) just had the best quarter in its history. Its stock still trades like nobody noticed.
Shares closed at $16 on Friday, down 10% over the past three months. That’s despite the October 27 report sending them toward their best day since April 2025.
It also leaves SoFi 41% below the $27.50 price at which it sold $1.5 billion of stock last December.
CEO Anthony Noto clearly expected more credit. “We had exceptional Q3 results against the backdrop of any environment, but they are even more remarkable given how 2026 has unfolded,” he said in the earnings release.
Records on almost every line
The headline numbers were clean:
- Adjusted net revenue rose 44% to a record $1.4 billion.
- EBITDA on an adjusted basis jumped 70% to $470 million, a 34% margin.
- GAAP net income reached $241 million, or $0.18 per share, beating the $0.17 consensus.
Guidance moved even more. SoFi lifted its 2026 revenue forecast to $5.04 billion from a prior range of $4.75 billion to $4.85 billion. It also nudged EPS to $0.61, ahead of the $0.59 consensus.
Then came the first look at 2027: about $6.4 billion of revenue, $1.28 billion of net income and $0.90 of EPS, all well ahead of analyst estimates…
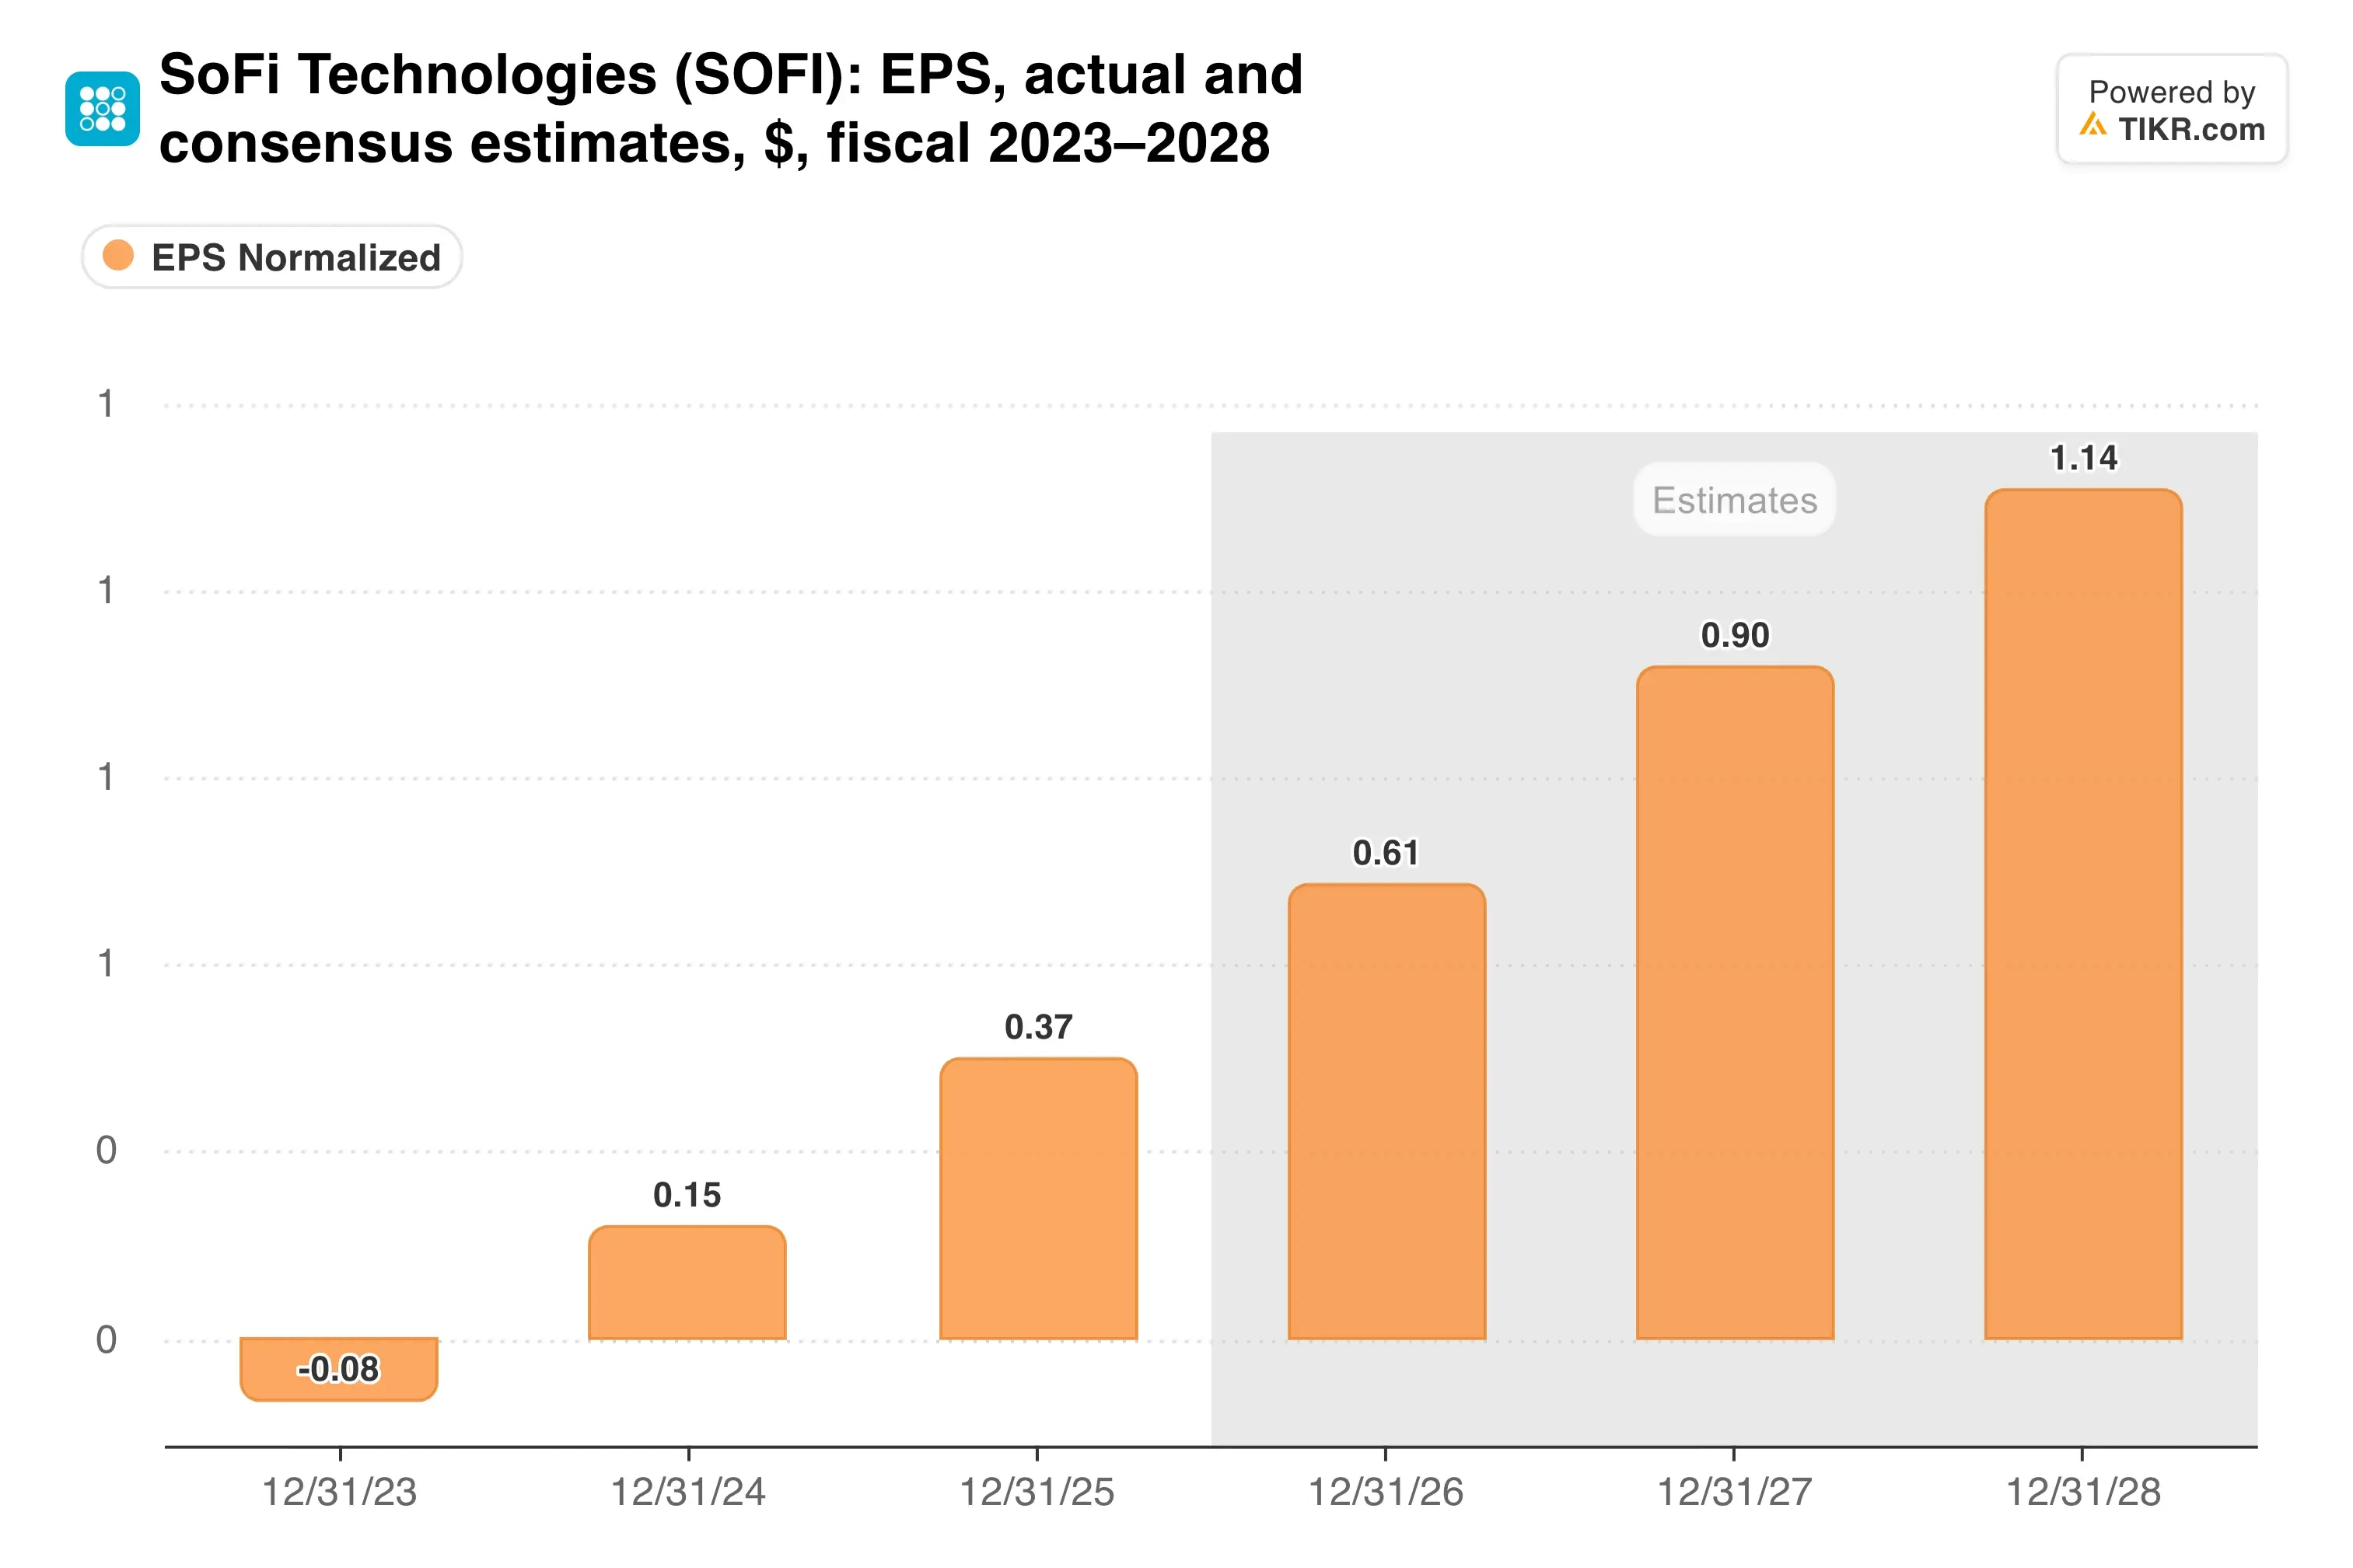
That $0.90 sits roughly 48% above this year’s guide. And it comes from a management team that just raised every 2026 line it reports.
More products per member
SoFi added a record 1.2 million members in the quarter, taking the total to 17.1 million, up 35%. Products grew faster, up 44% to 26.7 million.
That gap is the whole strategy. Products per member climbed to 1.56 from 1.47, and 51% of new products came from existing members.
Noto now wants investors to track three numbers. “We are adding more members, who are using more products, and generating more revenue per product,” he said.
Deposits grew $5.8 billion in the quarter to $51.3 billion, giving the bank more funding for its loan book. Fee-based revenue reached $570.6 million, or 42% of the total, so the business leans less on interest income than it used to.
Where is the money actually coming from?
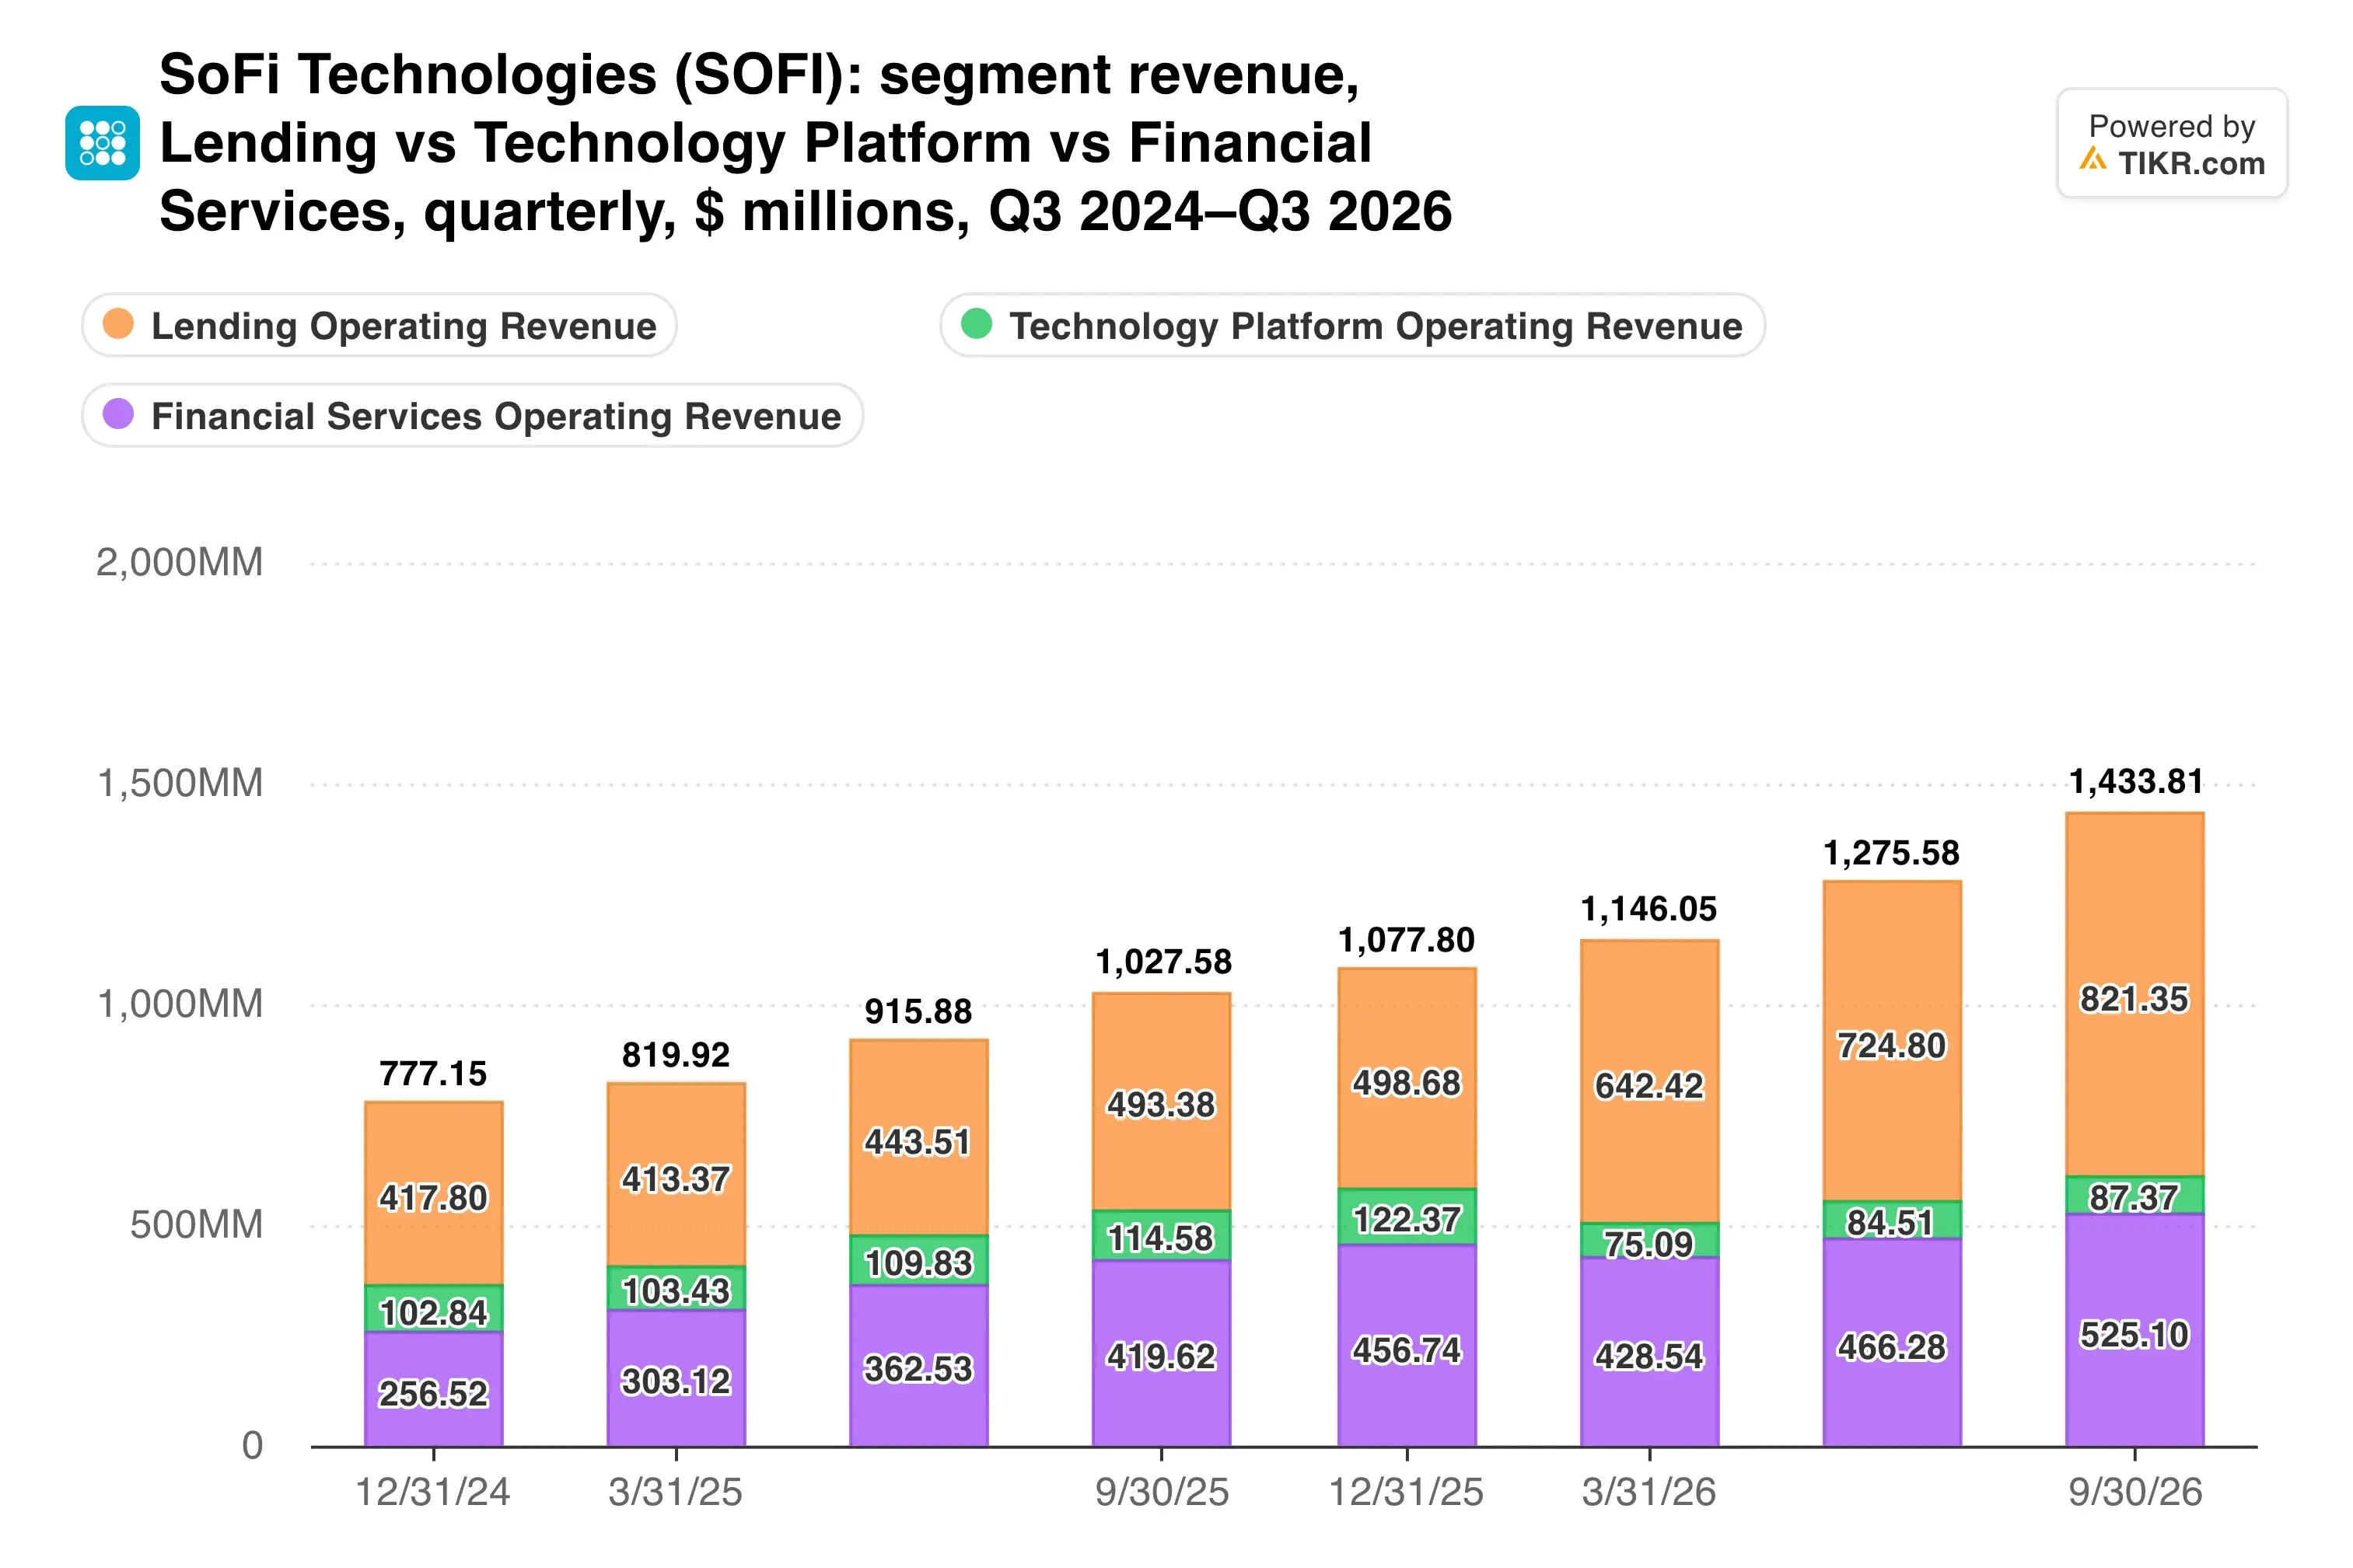
Lending is still the biggest engine, which keeps credit as the swing factor even while fee income grows.
TIKR tracks 25 analysts on SoFi. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SoFi, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SoFi’s Analyst Ratings
Too cheap for the guide
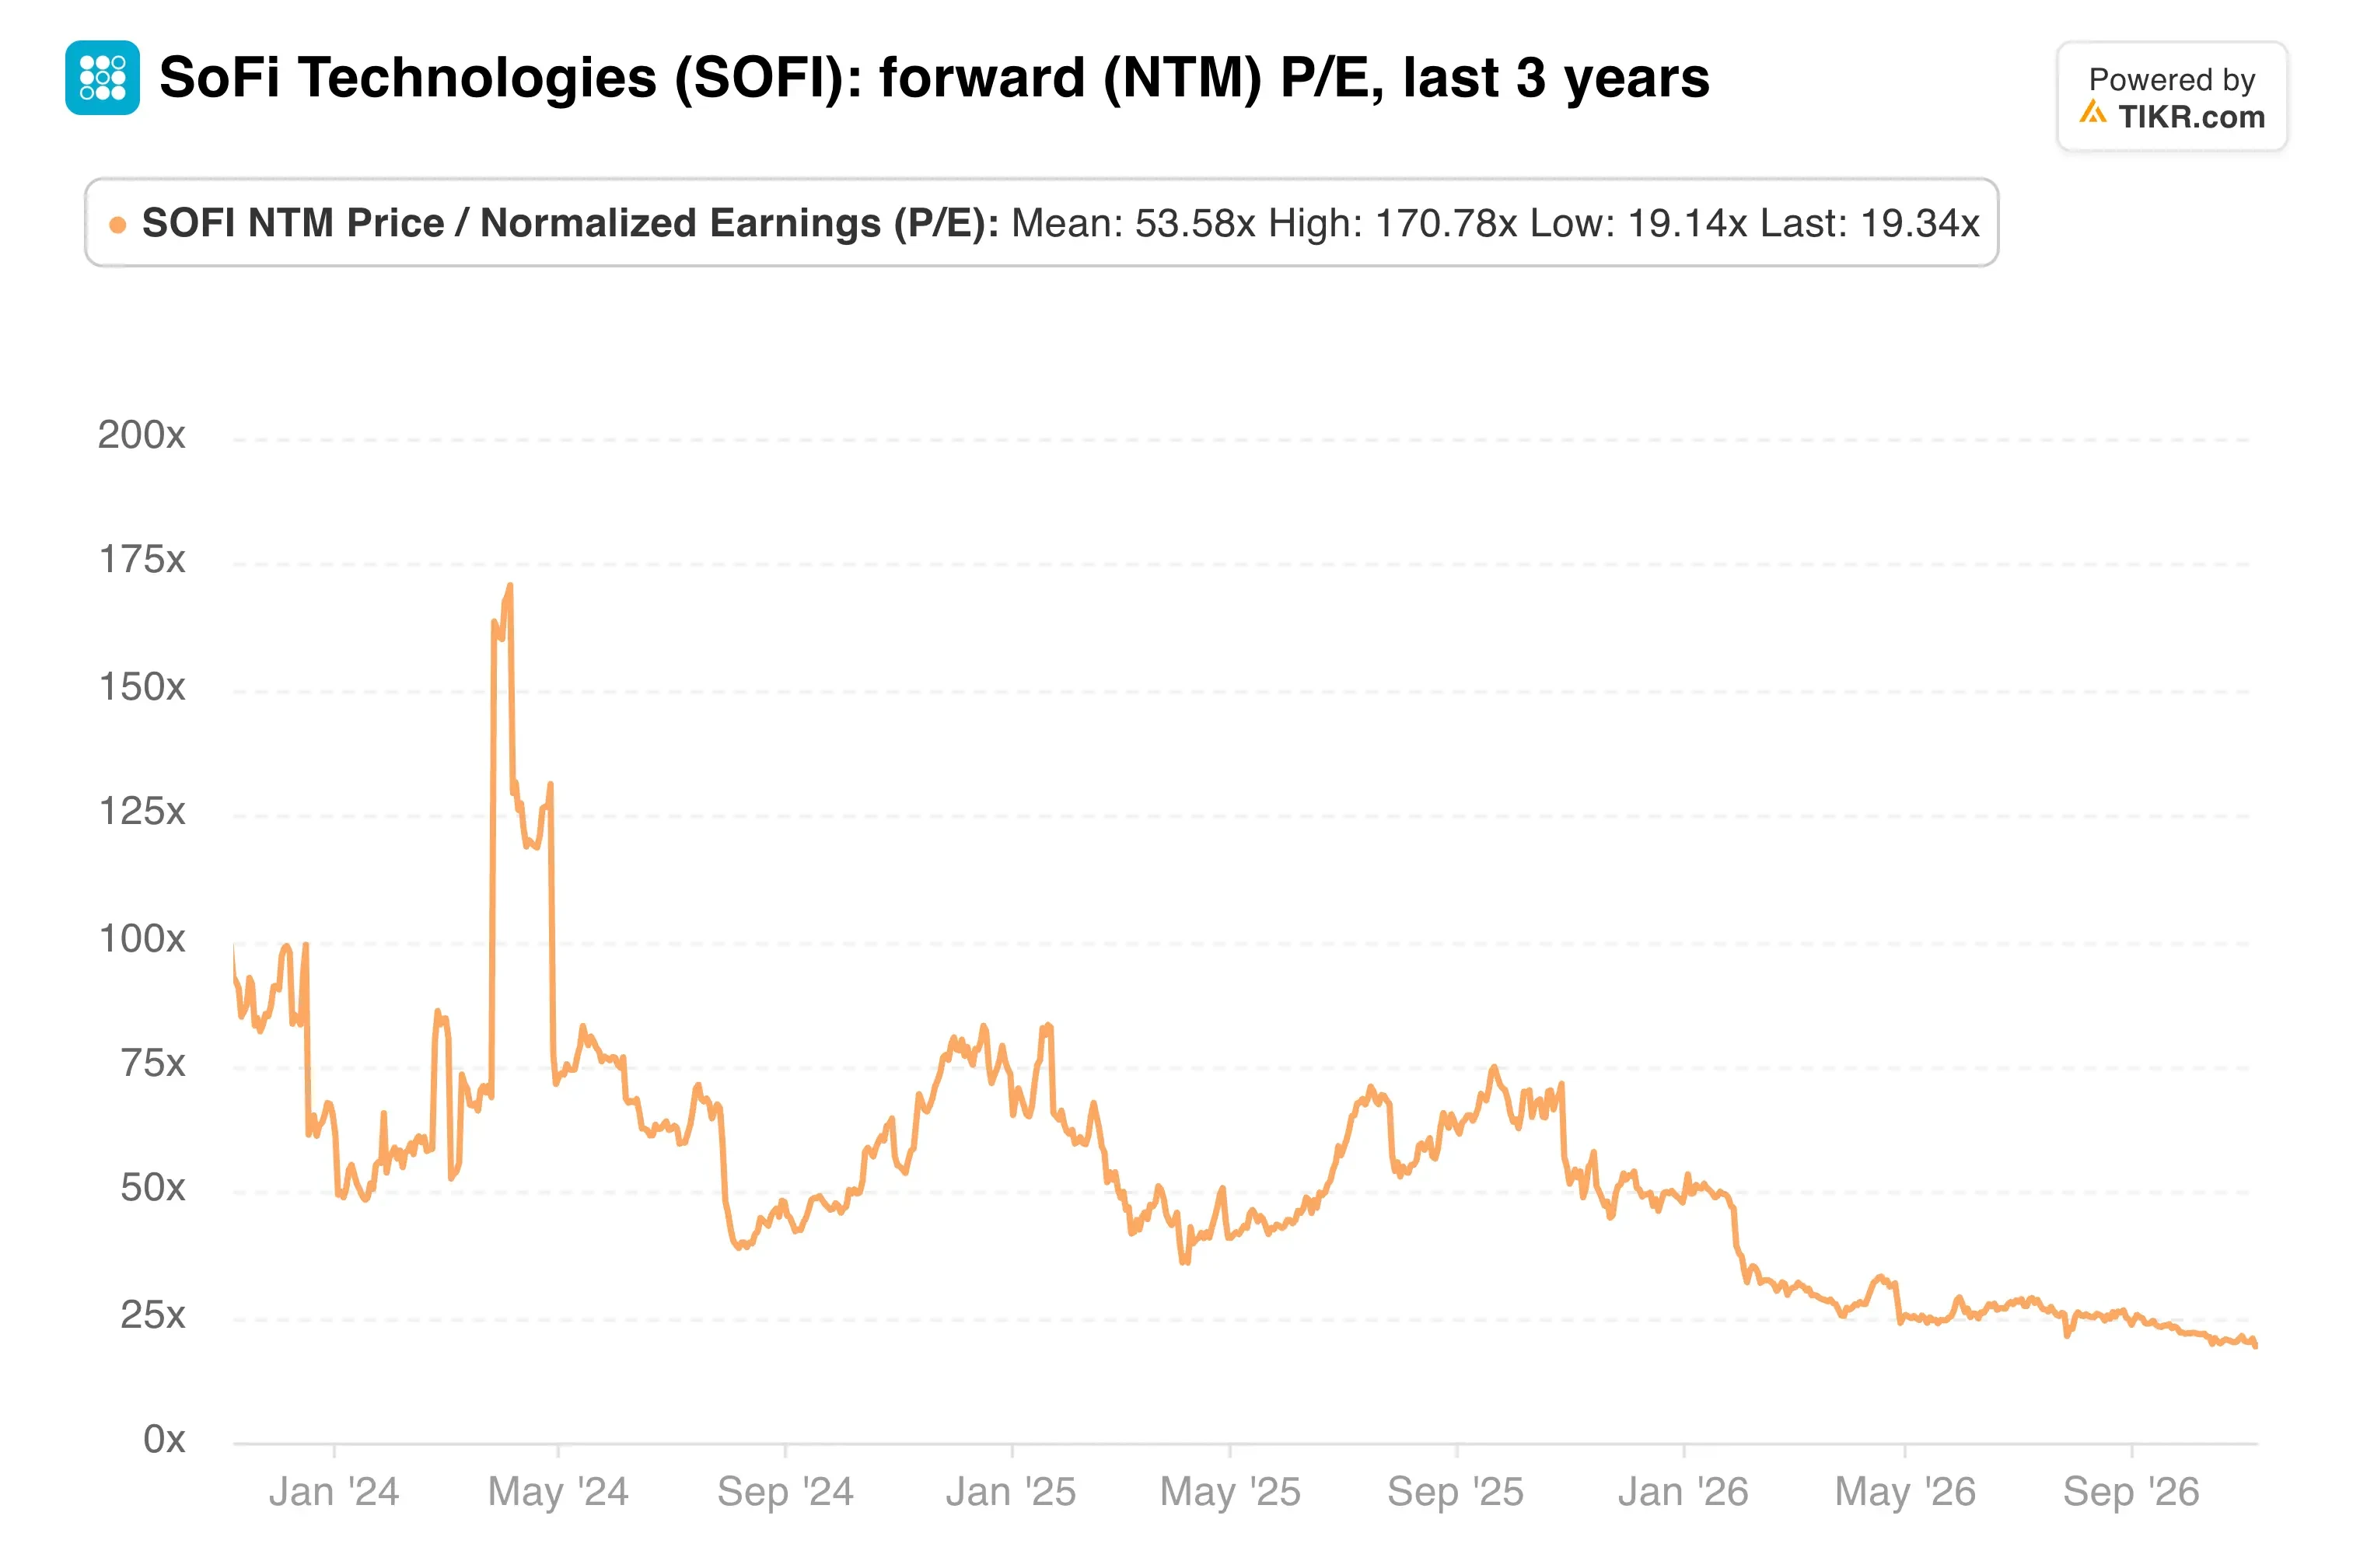
At $16, SoFi trades at about 18x its own 2027 EPS guide. Bank lenders like Ally Financial sit in the single digits on forward earnings, yet none of them is growing revenue at 40%.
On book value, tangible book rose 25% to $7.48 per share. So the stock trades at roughly 2.2x tangible book.
The multiple has already given back a lot:
Still, the doubts are easy to find. SoFi Plus growth fell short of internal plans after the company changed its processes to block what Noto called “nefarious actors.” Any lender growing this fast also gets stress-tested by bears on credit before the cycle does it for them.
My take: The market is pricing SoFi like a lender heading into a credit problem, while the company keeps reporting like a platform with operating leverage. I think the 2027 guide is credible, because management has now raised guidance off a quarter that beat on every major line. But this stock has shrugged off good news all year, so I’d expect the volatility to stay.
The next test is the fourth-quarter report, which analysts expect around January 25. It will show whether the member pace holds into the holidays and whether SoFi Plus growth has recovered.
So what is SoFi stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SoFi could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!