


Key Takeaways
- AppLovin’s third-quarter revenue rose 55% to $2.18 billion, and CEO Adam Foroughi said the business can grow about 30% a year over the long term.
- Analysts expected AppLovin’s revenue growth to slow to 21% by 2028, well below the pace Foroughi described.
- The 30% target is management’s own, and the second-quarter slowdown showed that model gains don’t arrive on a schedule.
- At 19x forward earnings against a three-year average of 30x, the stock is priced for far less growth than management or analysts expect.
AppLovin (APP) just reported a record quarter, and its CEO used the moment to set a target for the years ahead.
Third-quarter revenue rose 55% to $2.18 billion, well above the top of management’s guidance, and the stock soared on the report.
Then, on AppLovin’s third-quarter call, CEO Adam Foroughi looked past the quarter: “we believe this business can compound at roughly 30% annually over the long term.”
For a company growing 55% today, that almost sounds modest.
But 30% a year for the long term is a much higher bar than it looks, and analysts weren’t counting on it going into the report.
Analysts see growth slowing well below 30%
Analysts expected AppLovin’s revenue to more than double, from $5.48 billion in 2025 to $12.2 billion in 2028:
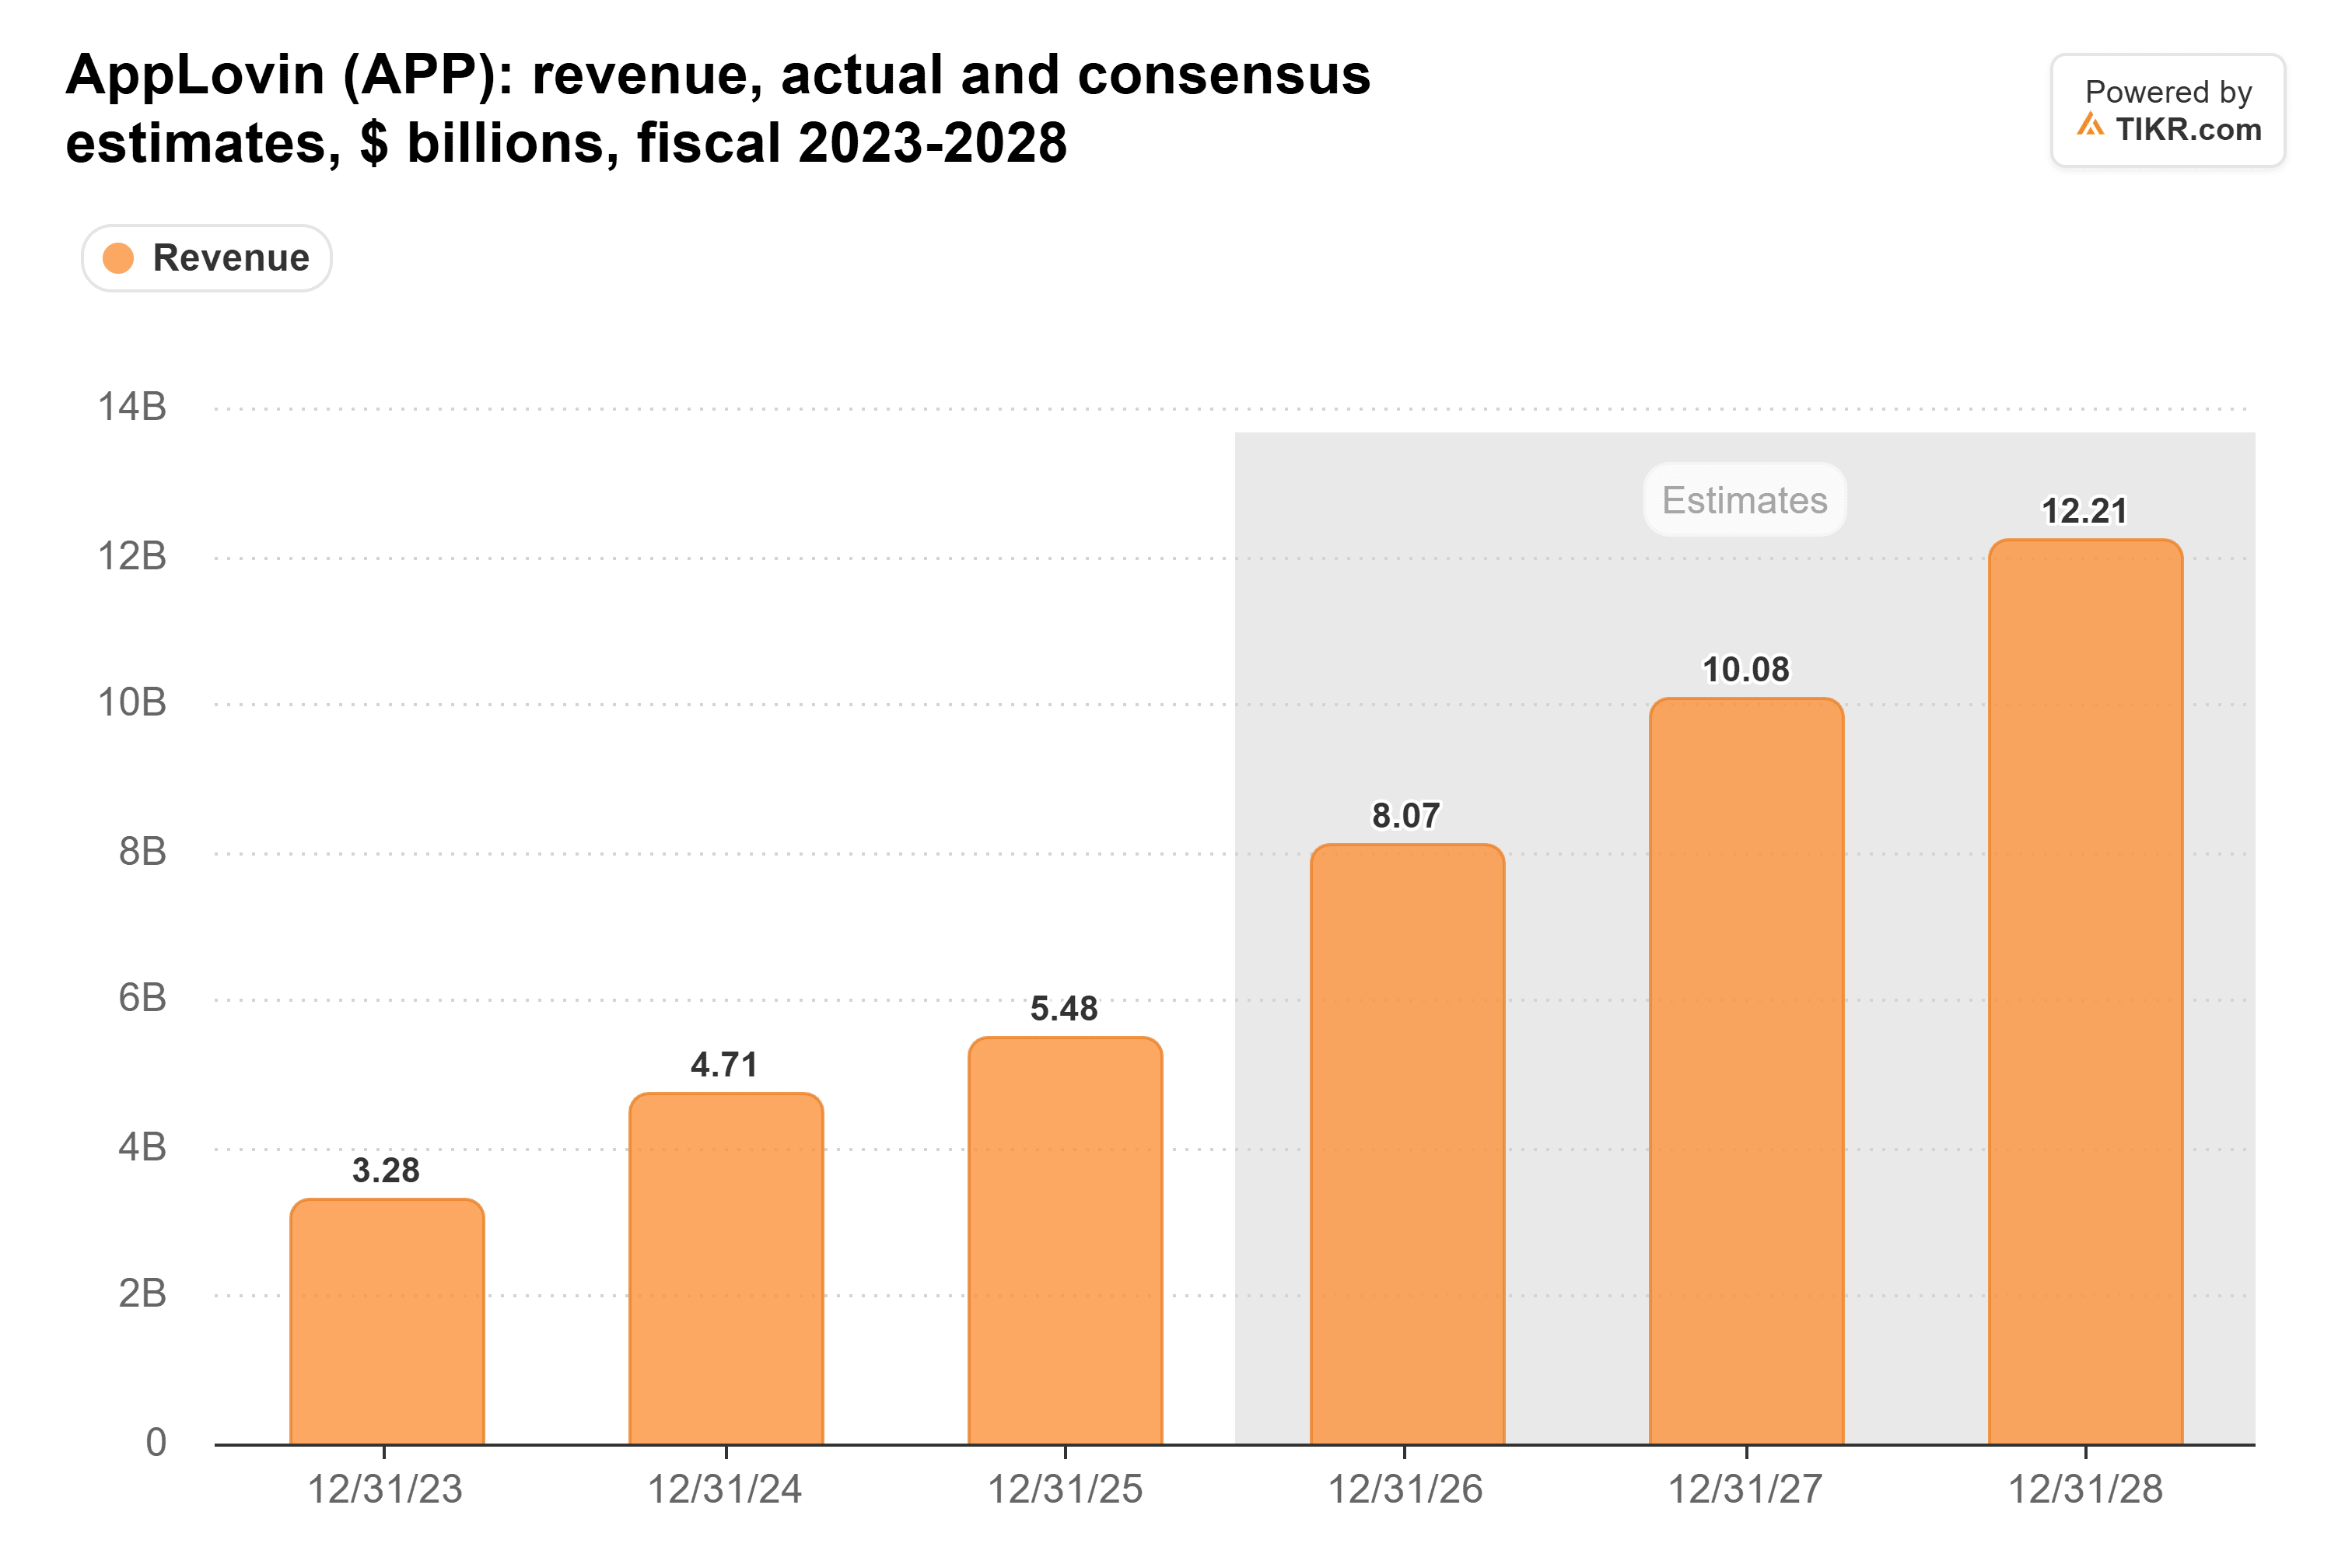
That’s about 31% a year, right on Foroughi’s number. But most of it comes from 2026, when the estimates have revenue up 47%. After that, they have growth slowing to 25% in 2027 and 21% in 2028.
If the $8.07 billion 2026 estimate grows 30% a year for two years instead, 2028 revenue comes to about $13.6 billion. That’s about $1.4 billion more than the consensus.
And I don’t see anything in this quarter’s report that should push those estimates lower. Management guided fourth-quarter revenue to $2.37 billion to $2.40 billion, above the roughly $2.25 billion analysts expected. CFO Matt Stumpf said the guidance implies full-year growth of more than 50%.
TIKR tracks 33 analysts on AppLovin. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AppLovin, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AppLovin’s Analyst Ratings
Growth this profitable is rare
Stumpf pointed out that the largest digital advertising platforms reported third-quarter revenue growth between roughly 10% and the mid-20s. “We grew 55%, several times faster than the market,” he said. “And we did it at margins well above all of our peers across the advertising space.”
AppLovin’s operating margin went from slightly negative in 2022 to 75.8% in 2025:

That matters for the 30% target, because AppLovin keeps nearly all of its new revenue. From 2024 to 2025, 99.3 cents of each added revenue dollar became operating income.
The margin held in the third quarter, too. The adjusted EBITDA margin was 84%, even as AppLovin spent more on computing power to train new models. AppLovin is also spending that cash on buybacks: it bought back and withheld 4.1 million shares for $1.4 billion in the quarter, and the board added $3.2 billion to its authorization.
Model gains don’t arrive on a schedule
Management set the 30% target itself, and the second quarter showed how quickly growth can stall. Revenue grew just 4.4% from the first quarter to the second, because the next step-up in model performance landed just after the quarter ended. In the third quarter, revenue grew 14% from the second.
Foroughi said openly that it could happen again. Model gains “won’t land on a perfect quarterly schedule and we won’t promise the cadence, but the headroom is real, and we’re still very early.”
He has reasons to be confident. The new models were only partly rolled out in the third quarter, and gaming still grew nearly 50% from a year earlier. Consumer advertisers’ spending grew by triple digits.
Consumer is the business to watch. Management has said gaming alone can grow 20% to 30% a year over the long term, so AppLovin needs consumer ads to keep growing fast to get the whole company to 30%.
The stock is priced for far less
Even after the jump, AppLovin trades at 19x forward earnings, well below its three-year average of 30x:
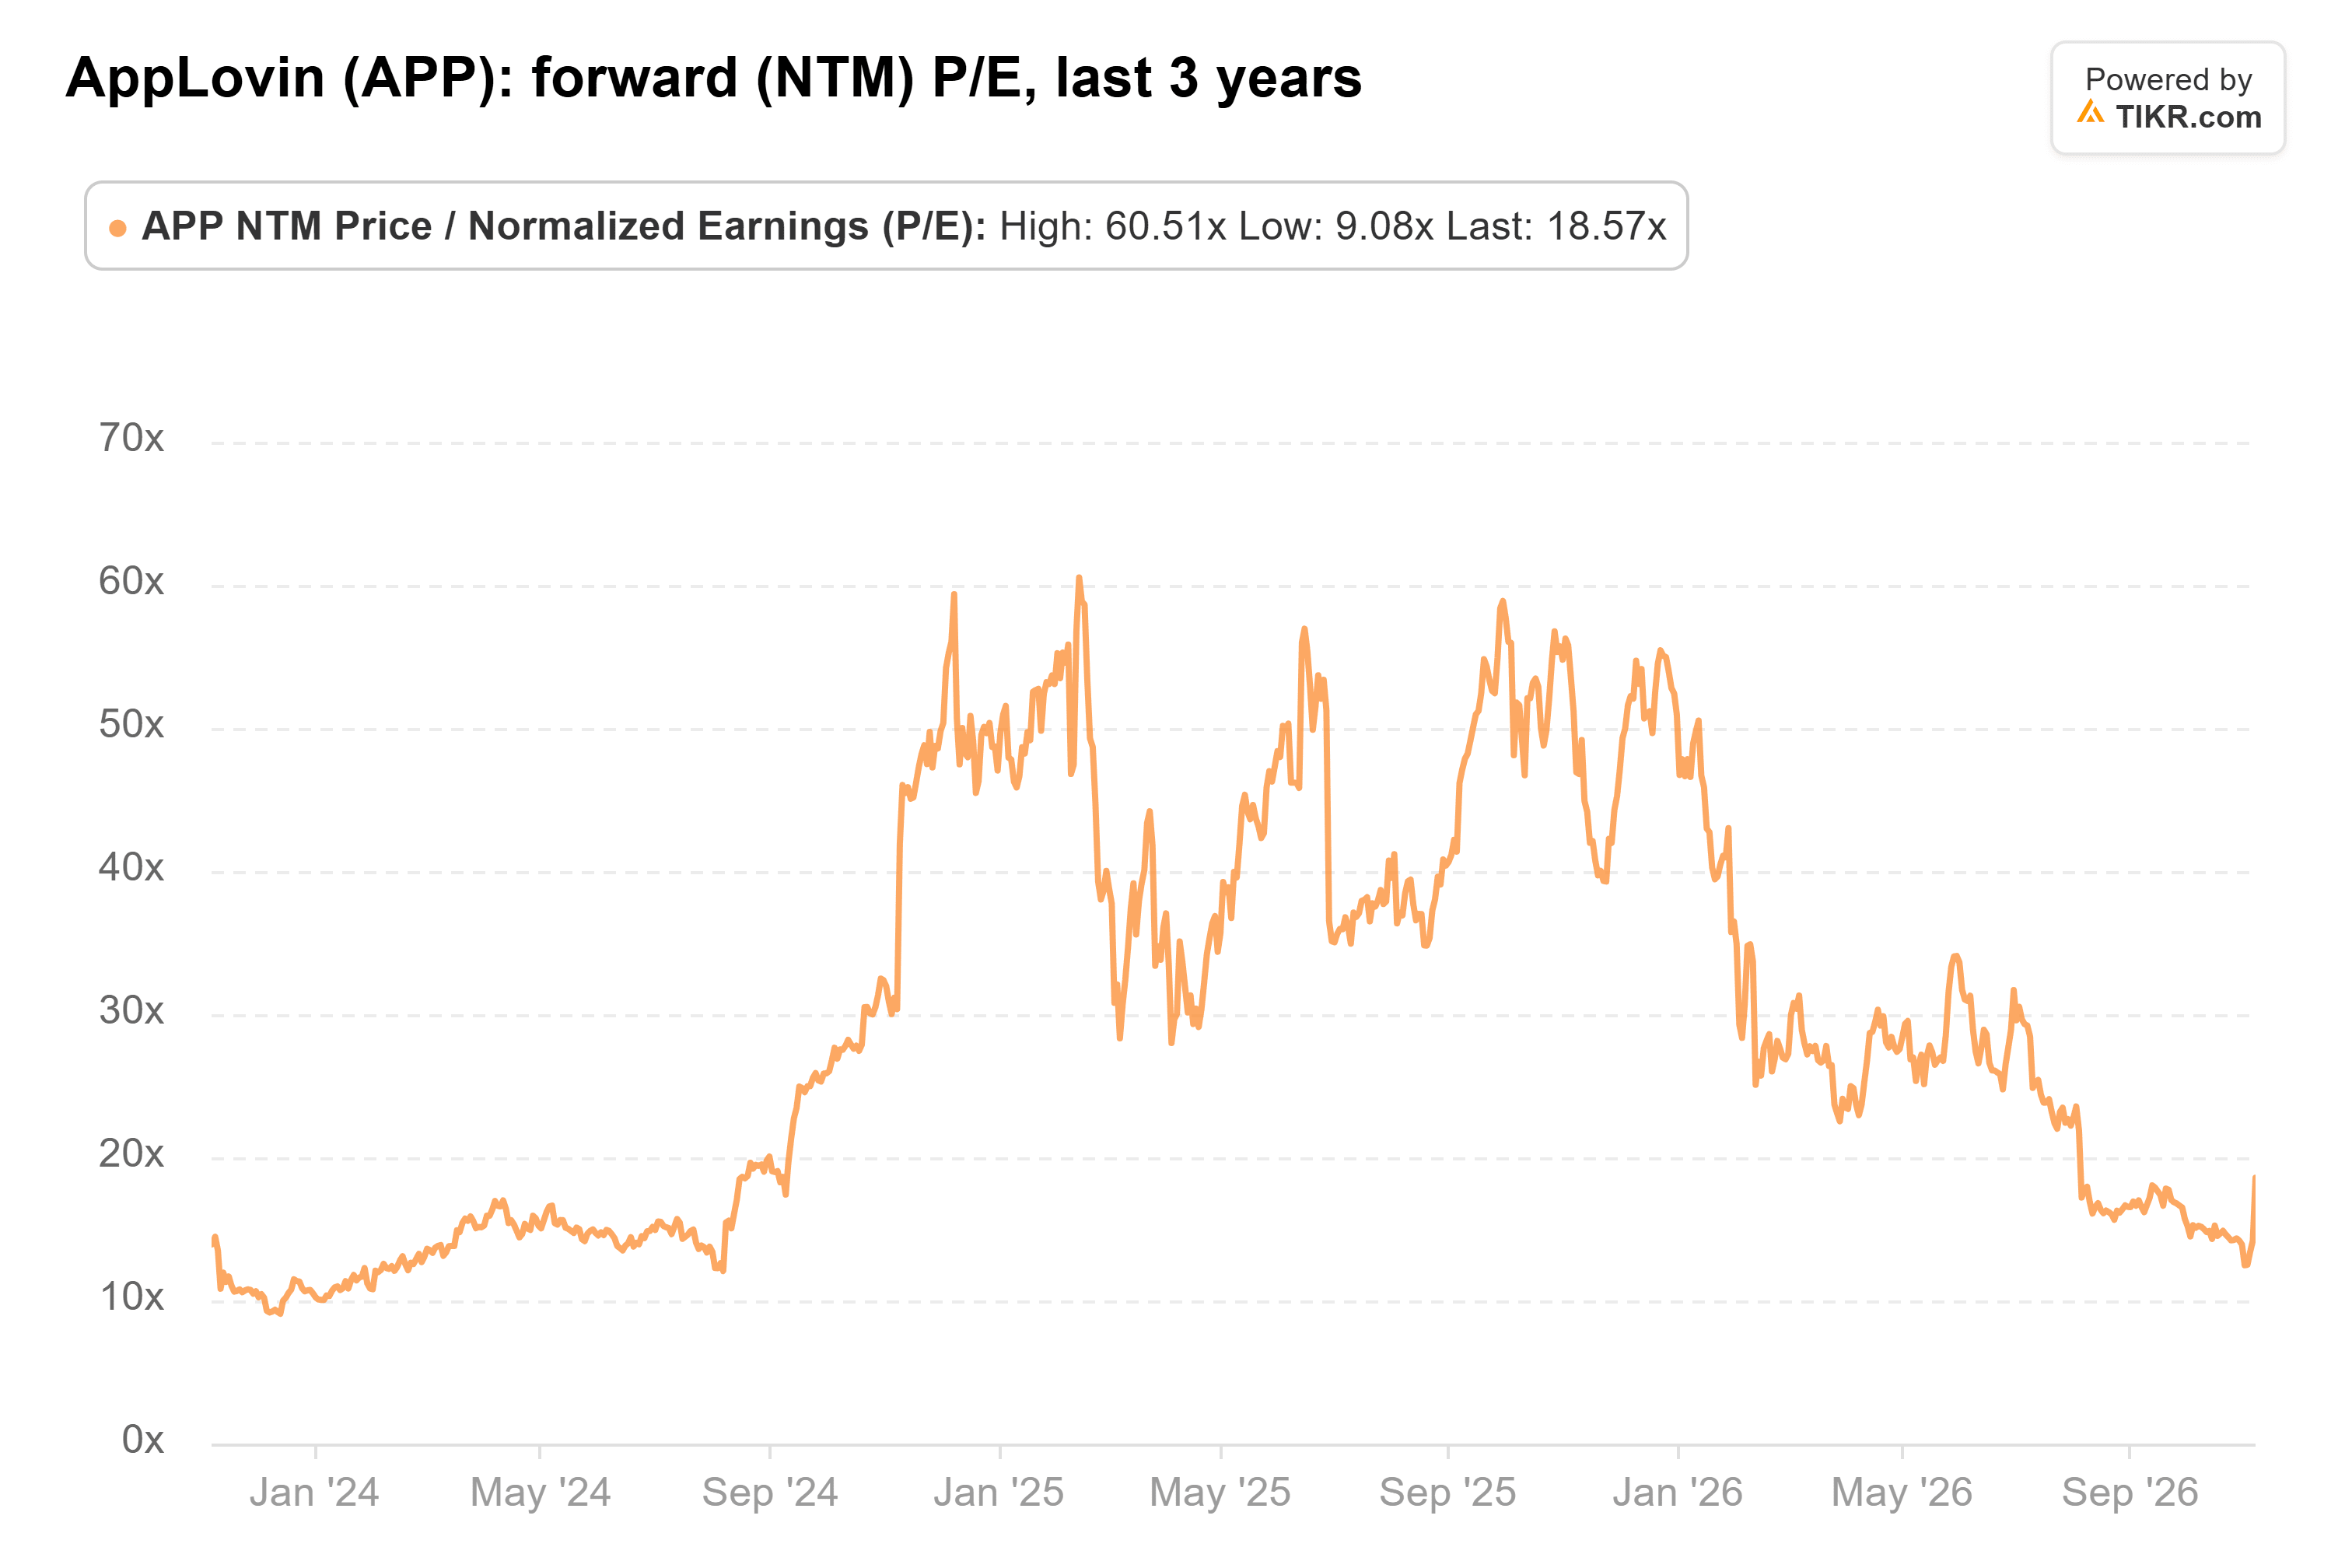
(In February 2025, it was over 60x!)
That’s a low multiple for a company analysts see growing normalized EPS from $16.59 in 2026 to $25.06 in 2028, about 23% a year.
The way I see it, AppLovin doesn’t need to hit 30% for the stock to work from here. At 19x, investors are paying for far less growth than analysts expect, let alone what Foroughi is aiming for.
Of course, the case depends on a model rollout that isn’t finished yet. AppLovin’s fourth-quarter report, likely in February, will show how far the transition has come and whether consumer spending held up through the holiday season.
So what is AppLovin stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AppLovin could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


