


Key Takeaways
- Altria Group yields 6.5% and Pfizer yields 6.3%, as of Oct. 7, 2026.
- Altria’s dividend used 78% of its free cash flow over the twelve months to June 30, 2026. Pfizer’s used 89% over the twelve months to June 28, 2026.
- Altria’s dividend per share grew 4.1% a year from fiscal 2020 to fiscal 2025, and Pfizer’s grew 2.5% a year.
- Pfizer’s CEO says its dividend will start growing again after the patent losses that weigh on revenue through 2028.
Pfizer (PFE) CEO Albert Bourla wanted to settle one question “once and for all” on the company’s Aug. 4 earnings call: its 6.3%-yielding dividend is staying put.
Income investors like to hear a promise like that, and they should still check it, especially against the other big yield on most of their screens. Altria Group (MO) pays 6.5% and narrowed its 2026 earnings guidance on July 30.
So if you put $10,000 into one of them today, which one pays you more over the next 10 years?
| Metric | Altria Group (MO) | Pfizer (PFE) |
|---|---|---|
| Dividend yield | 6.5% | 6.3% |
| Annual dividend | $4.44 | $1.72 |
| Dividend growth, fiscal 2020–2025 | 4.1% a year | 2.5% a year |
| Cash dividend payout ratio (TTM) | 78% | 89% |
| Net debt/EBITDA (LTM) | 1.41x | 1.97x |
| Interest coverage (LTM) | 13.27x | 6.98x |
| Forward P/E (NTM) | 11.9x | 9.9x |
Altria’s cash keeps outrunning its dividend
Altria’s core business is shrinking. Domestic cigarette and MST volumes are declining. Management attributes that to industry declines, pressure on adult nicotine consumers’ discretionary income, and a move to e-vapor.
The growth is in nicotine pouches. on! PLUS has expanded to 120,000 stores. Management says the industry’s cigarette decline has moderated for four straight quarters, and CEO Sal Mancuso pointed to the crackdown on illicit vapes: “We believe increased enforcement activity, including supply-related disruptions at the border, is helping slow demand for illicit products.”
Second-quarter 2026 net revenues were $6.11 billion, up 0.1% from a year earlier. Adjusted EPS rose 2.8% to $1.48. Management expects 2026 adjusted EPS of $5.61 to $5.72, up 3.5% to 5.5% from fiscal 2025’s $5.42.
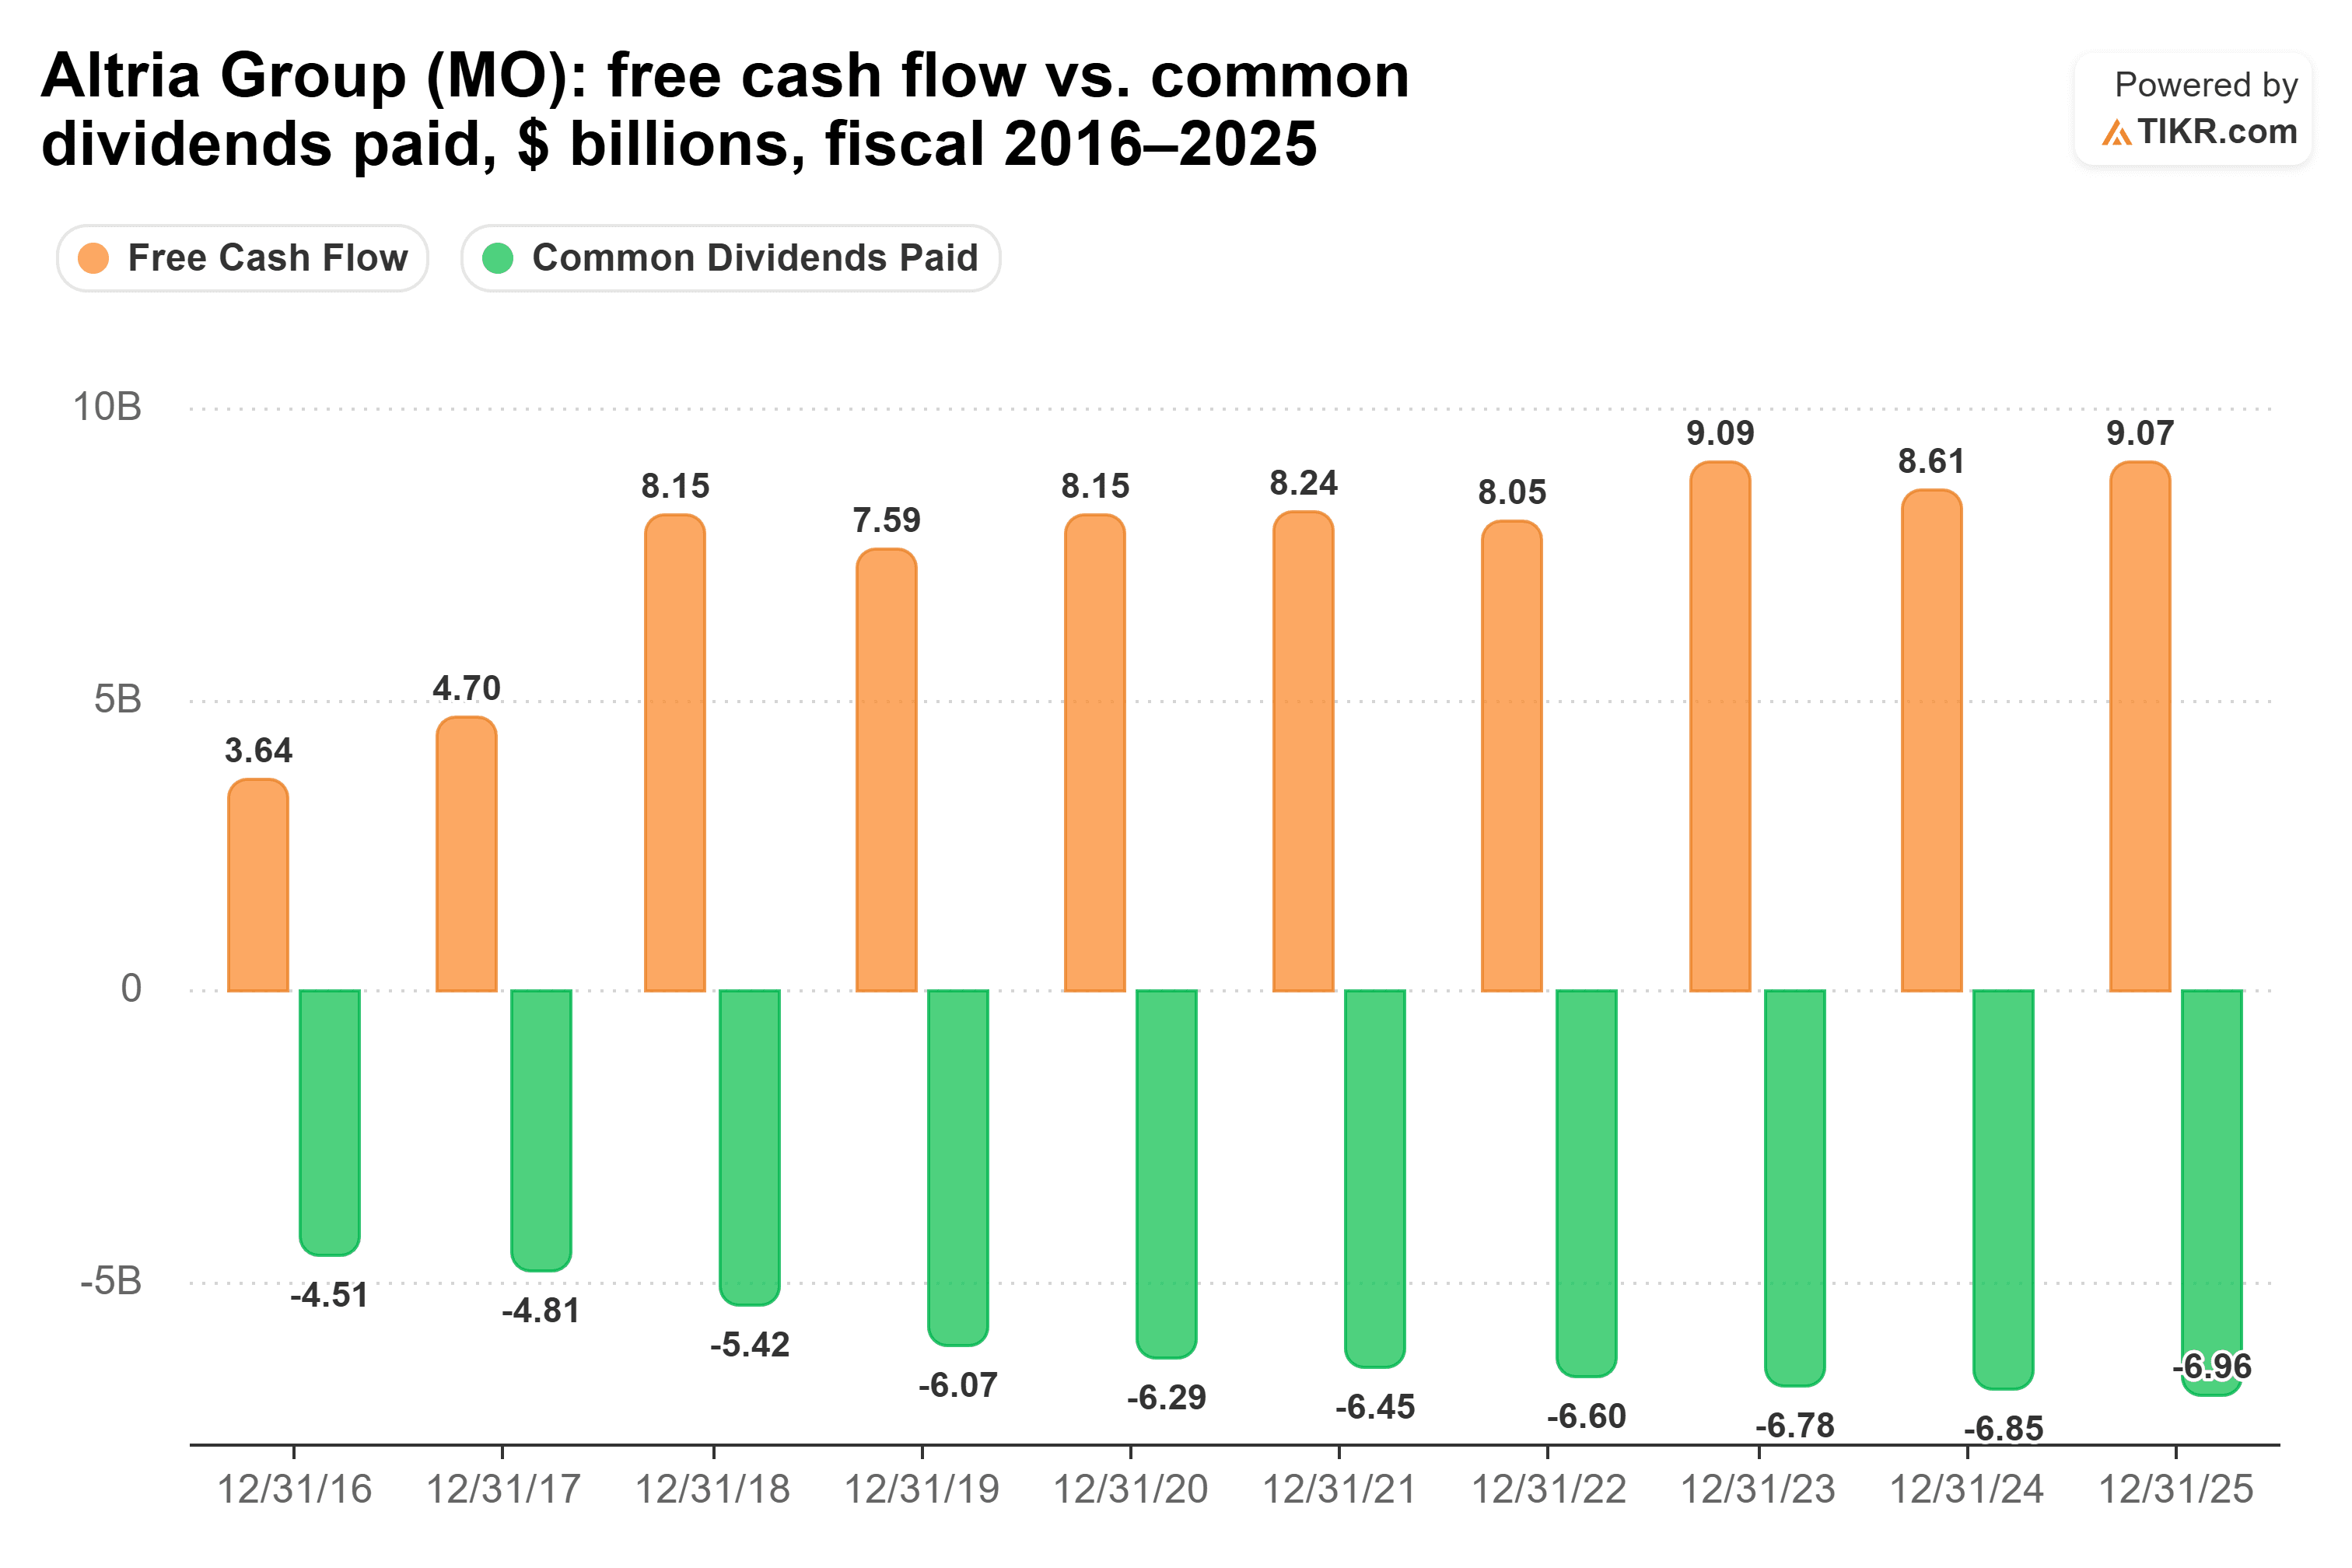
That’s plenty to pay the dividend. Over the twelve months to June 30, 2026, Altria’s dividend ate up a manageable 78% of free cash flow, in line with the 74.6% to 82.0% range from fiscal 2021 to fiscal 2025. Free cash flow has topped dividends paid every year since fiscal 2018.
The risk is that the cigarette decline speeds up again as the pressure on its customers’ discretionary income continues.
Pfizer’s dividend has less room to spare
Altria’s free cash flow has stayed above its dividend for years. Pfizer’s has swung hard, from $29.9 billion in fiscal 2021 to $4.79 billion in fiscal 2023. Meanwhile, its dividends paid rose from $8.04 billion in fiscal 2019 to $9.77 billion in fiscal 2025. Dividends outran free cash flow in fiscal 2023 and again in fiscal 2025, with cash dividend payout ratios of 192.9% and 107.7%.
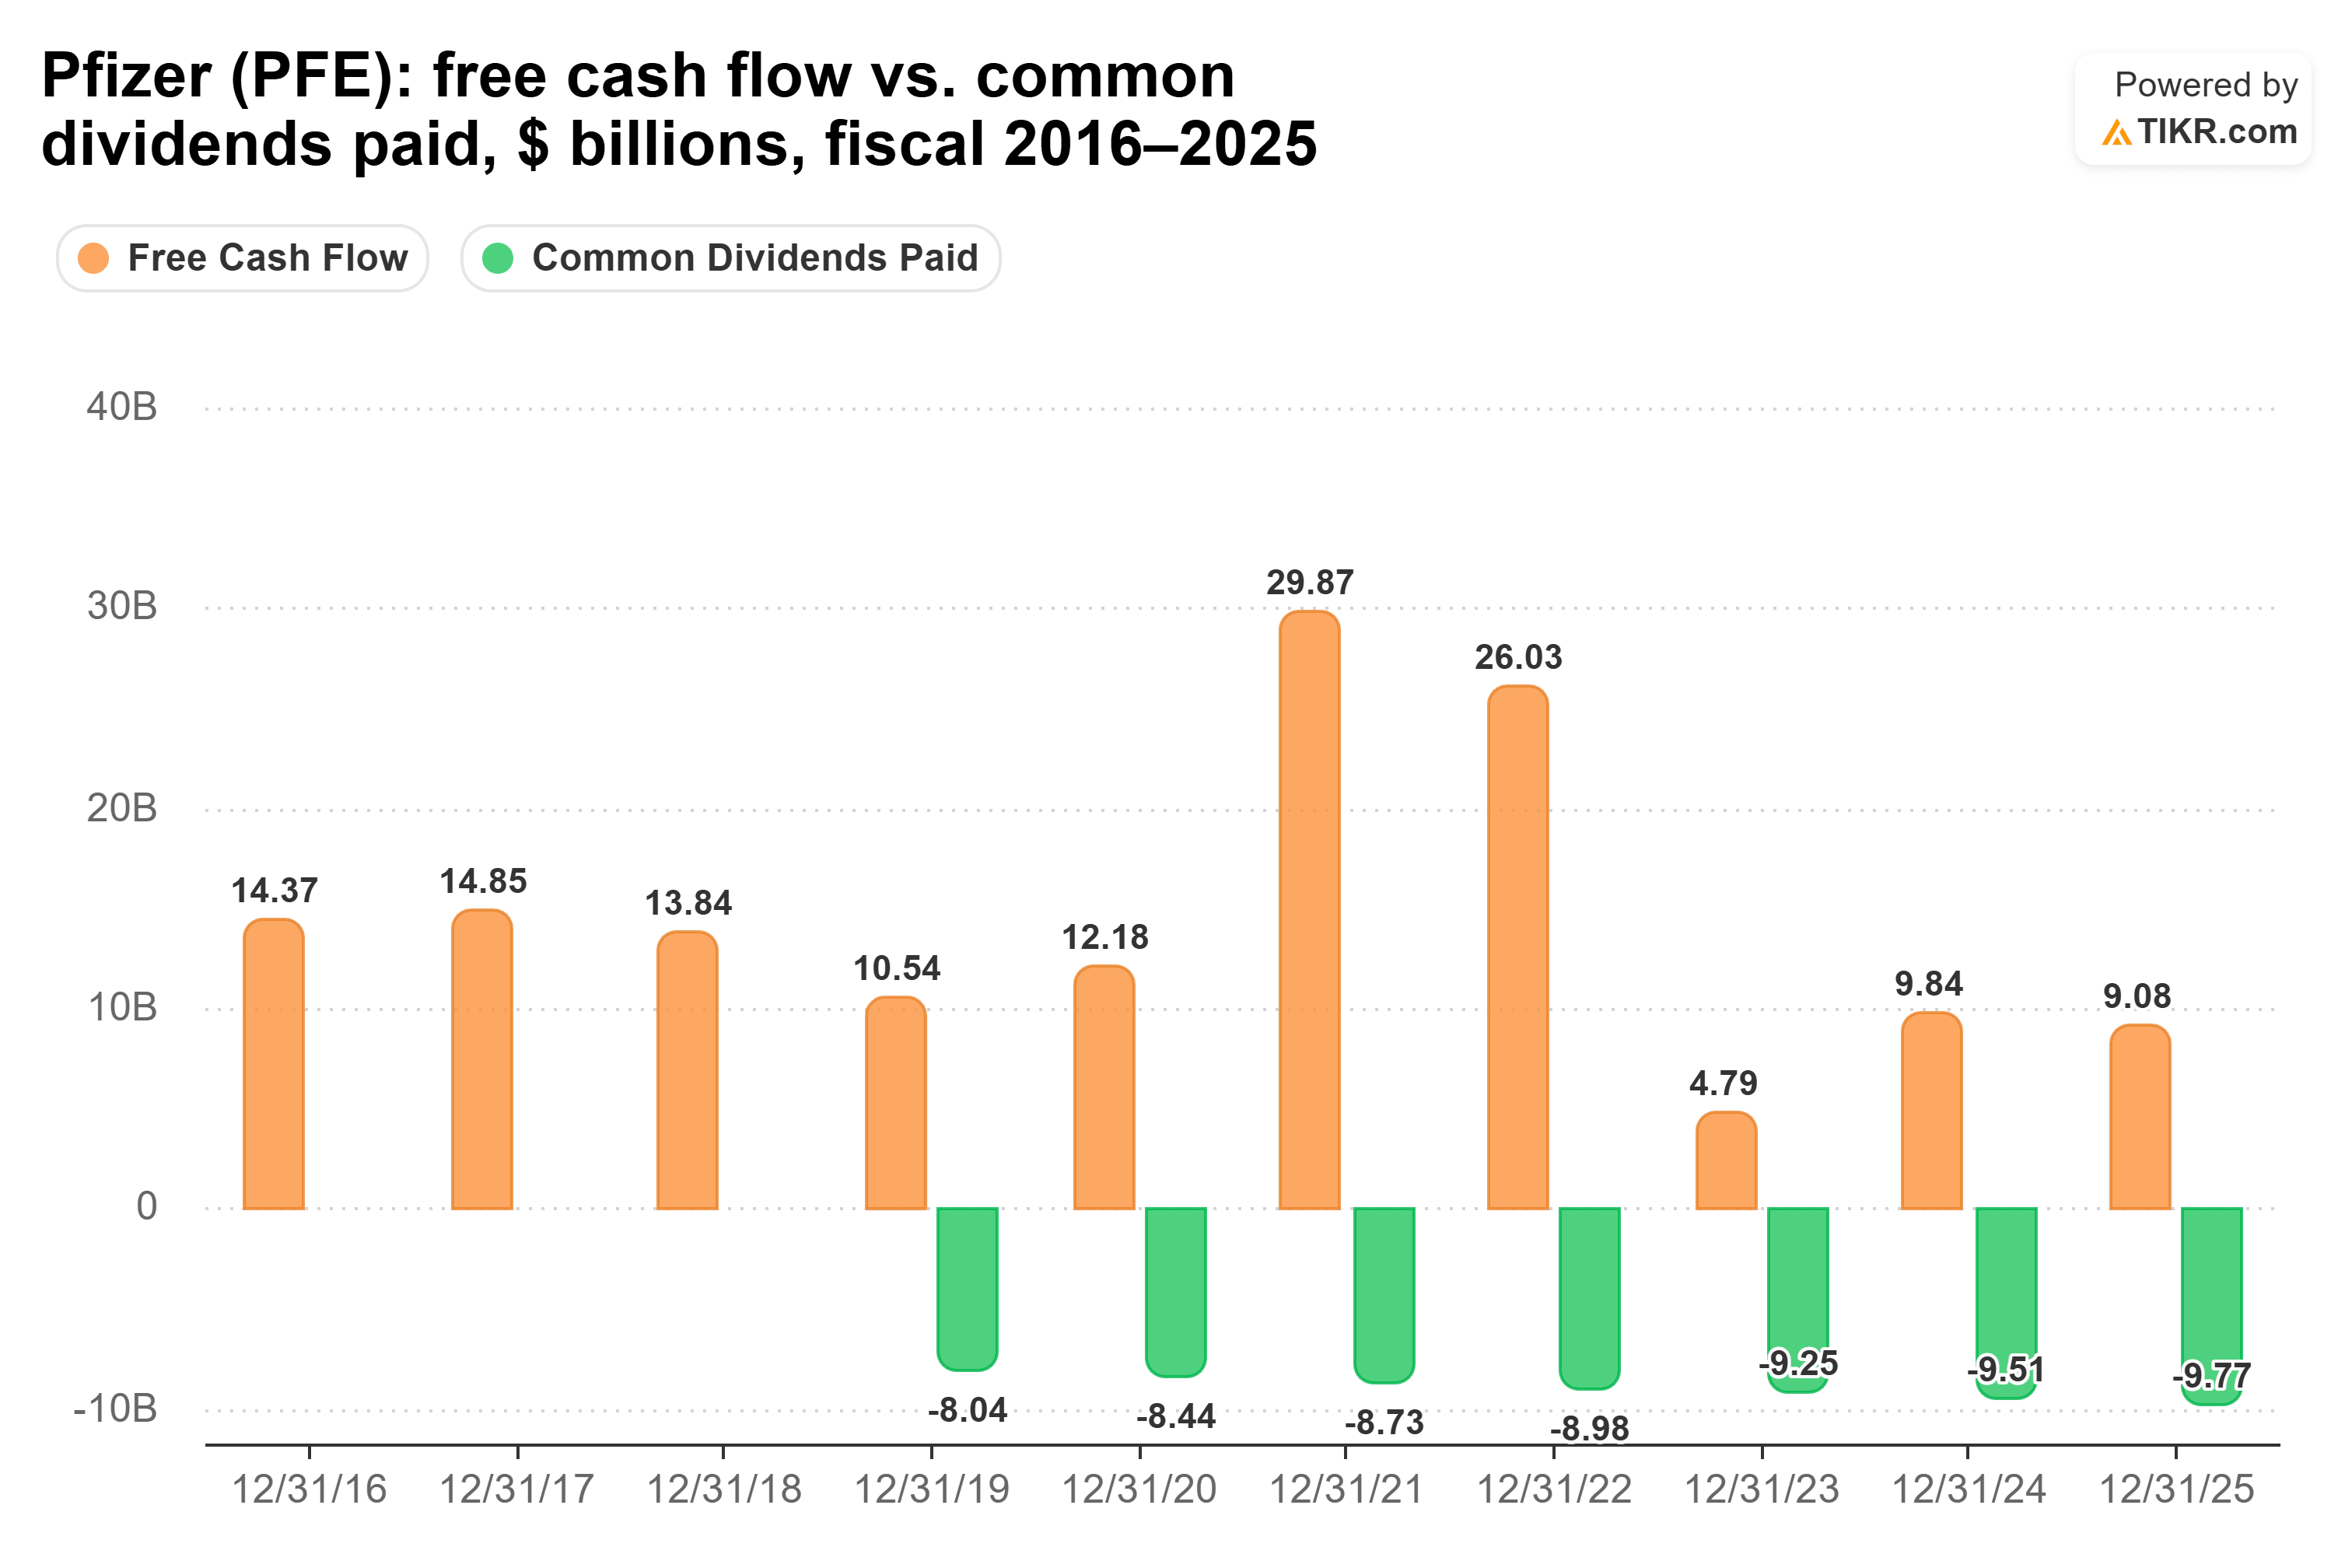
The twelve months to June 28, 2026 were better, at a tight 89%.
The business is mid-transition. Pfizer now expects about $4 billion of COVID-19 product revenue in 2026, down from about $5 billion. Patent losses will also weigh on revenue through 2028. On the other side, launched and acquired products grew 18% operationally in the second quarter, and Pfizer raised its 2026 revenue guidance to $60.5 billion to $62.5 billion. Second-quarter adjusted EPS was $0.77, against $0.78 a year earlier.
Bourla insists the payout is safe: “even the most stretched scenarios that we are running, we will be able to maintain our dividend.” He also said it would start growing again only after the patent losses. With net debt at 1.97x EBITDA, Pfizer plans no buybacks in 2026.
The risk is that new products don’t fill the gap from patent losses, and an 89% payout leaves little room if they don’t.
So which dividend wins?
Altria pays you more over the next 10 years. At each stock’s 5-year growth rate, $10,000 in Altria pays about $7,847 over the decade, against about $7,059 for Pfizer. That’s about $787 more. By year 10, Altria’s check would be about $935, a 9.3% yield on your original $10,000, and Pfizer’s would be about $787. At these rates, Pfizer never catches up.
Altria’s rate also looks more durable. A 78% payout and guidance for 3.5% to 5.5% adjusted EPS growth in 2026 leave room for raises near its 4.1% pace. Pfizer’s CEO says growth resumes only after its patent losses, so a 2.5% rate looks generous for the next few years.
This isn’t to say Pfizer’s dividend is in trouble. Management has said as plainly as it can that the payout is safe, revenue guidance went up in August, and new launches are growing fast. Pfizer also sees high single-digit revenue growth from year-end 2028 through 2033, and at 9.9x forward earnings against Altria’s 11.9x, the stock is cheaper. It’s just that Altria pays the bigger check today, with more cash behind it, and its dividend has grown faster.
Of course, that answer depends on Altria’s cigarette decline staying moderate. If it speeds up again, a 4.1% raise every year gets harder to fund.
So what is Altria Group stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Altria Group could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


