Key Takeaways
- Tempus AI shares jumped 10% after third-quarter revenue rose 23% to $411.5 million and the company raised its 2026 revenue guidance.
- Its higher-margin data business grew faster than testing, lifting adjusted EBITDA to $25.6 million from $1.5 million.
- Its cancer-recurrence tests rose 300%, but Natera and Guardant Health grew oncology test volumes faster in the second quarter.
- The stock already trades above its one-year average on forward sales, so the margin gains have to keep coming.
Tempus AI (TEM) stock is up 10% today after a third-quarter beat and a guidance raise.
Founder and CEO Eric Lefkofsky pointed to “accelerating unit growth” in oncology, where test volume rose 32%. Its minimal residual disease (MRD) tests, which look for cancer coming back, rose 300% to about 12,000. That puts Tempus right in the lane of Natera (NTRA) and Guardant Health (GH).
The details
- Revenue rose 23% to $411.5 million, ahead of the $409.3 million analysts expected.
- Adjusted EPS was $0.07, against a consensus loss of $0.08.
- Data and Applications revenue rose 33%, against 20% for Diagnostics.
Tempus now guides for $1.60 billion to $1.605 billion of 2026 revenue and still expects about $65 million of adjusted EBITDA. Analysts already had 2026 revenue at $1.60 billion going in:
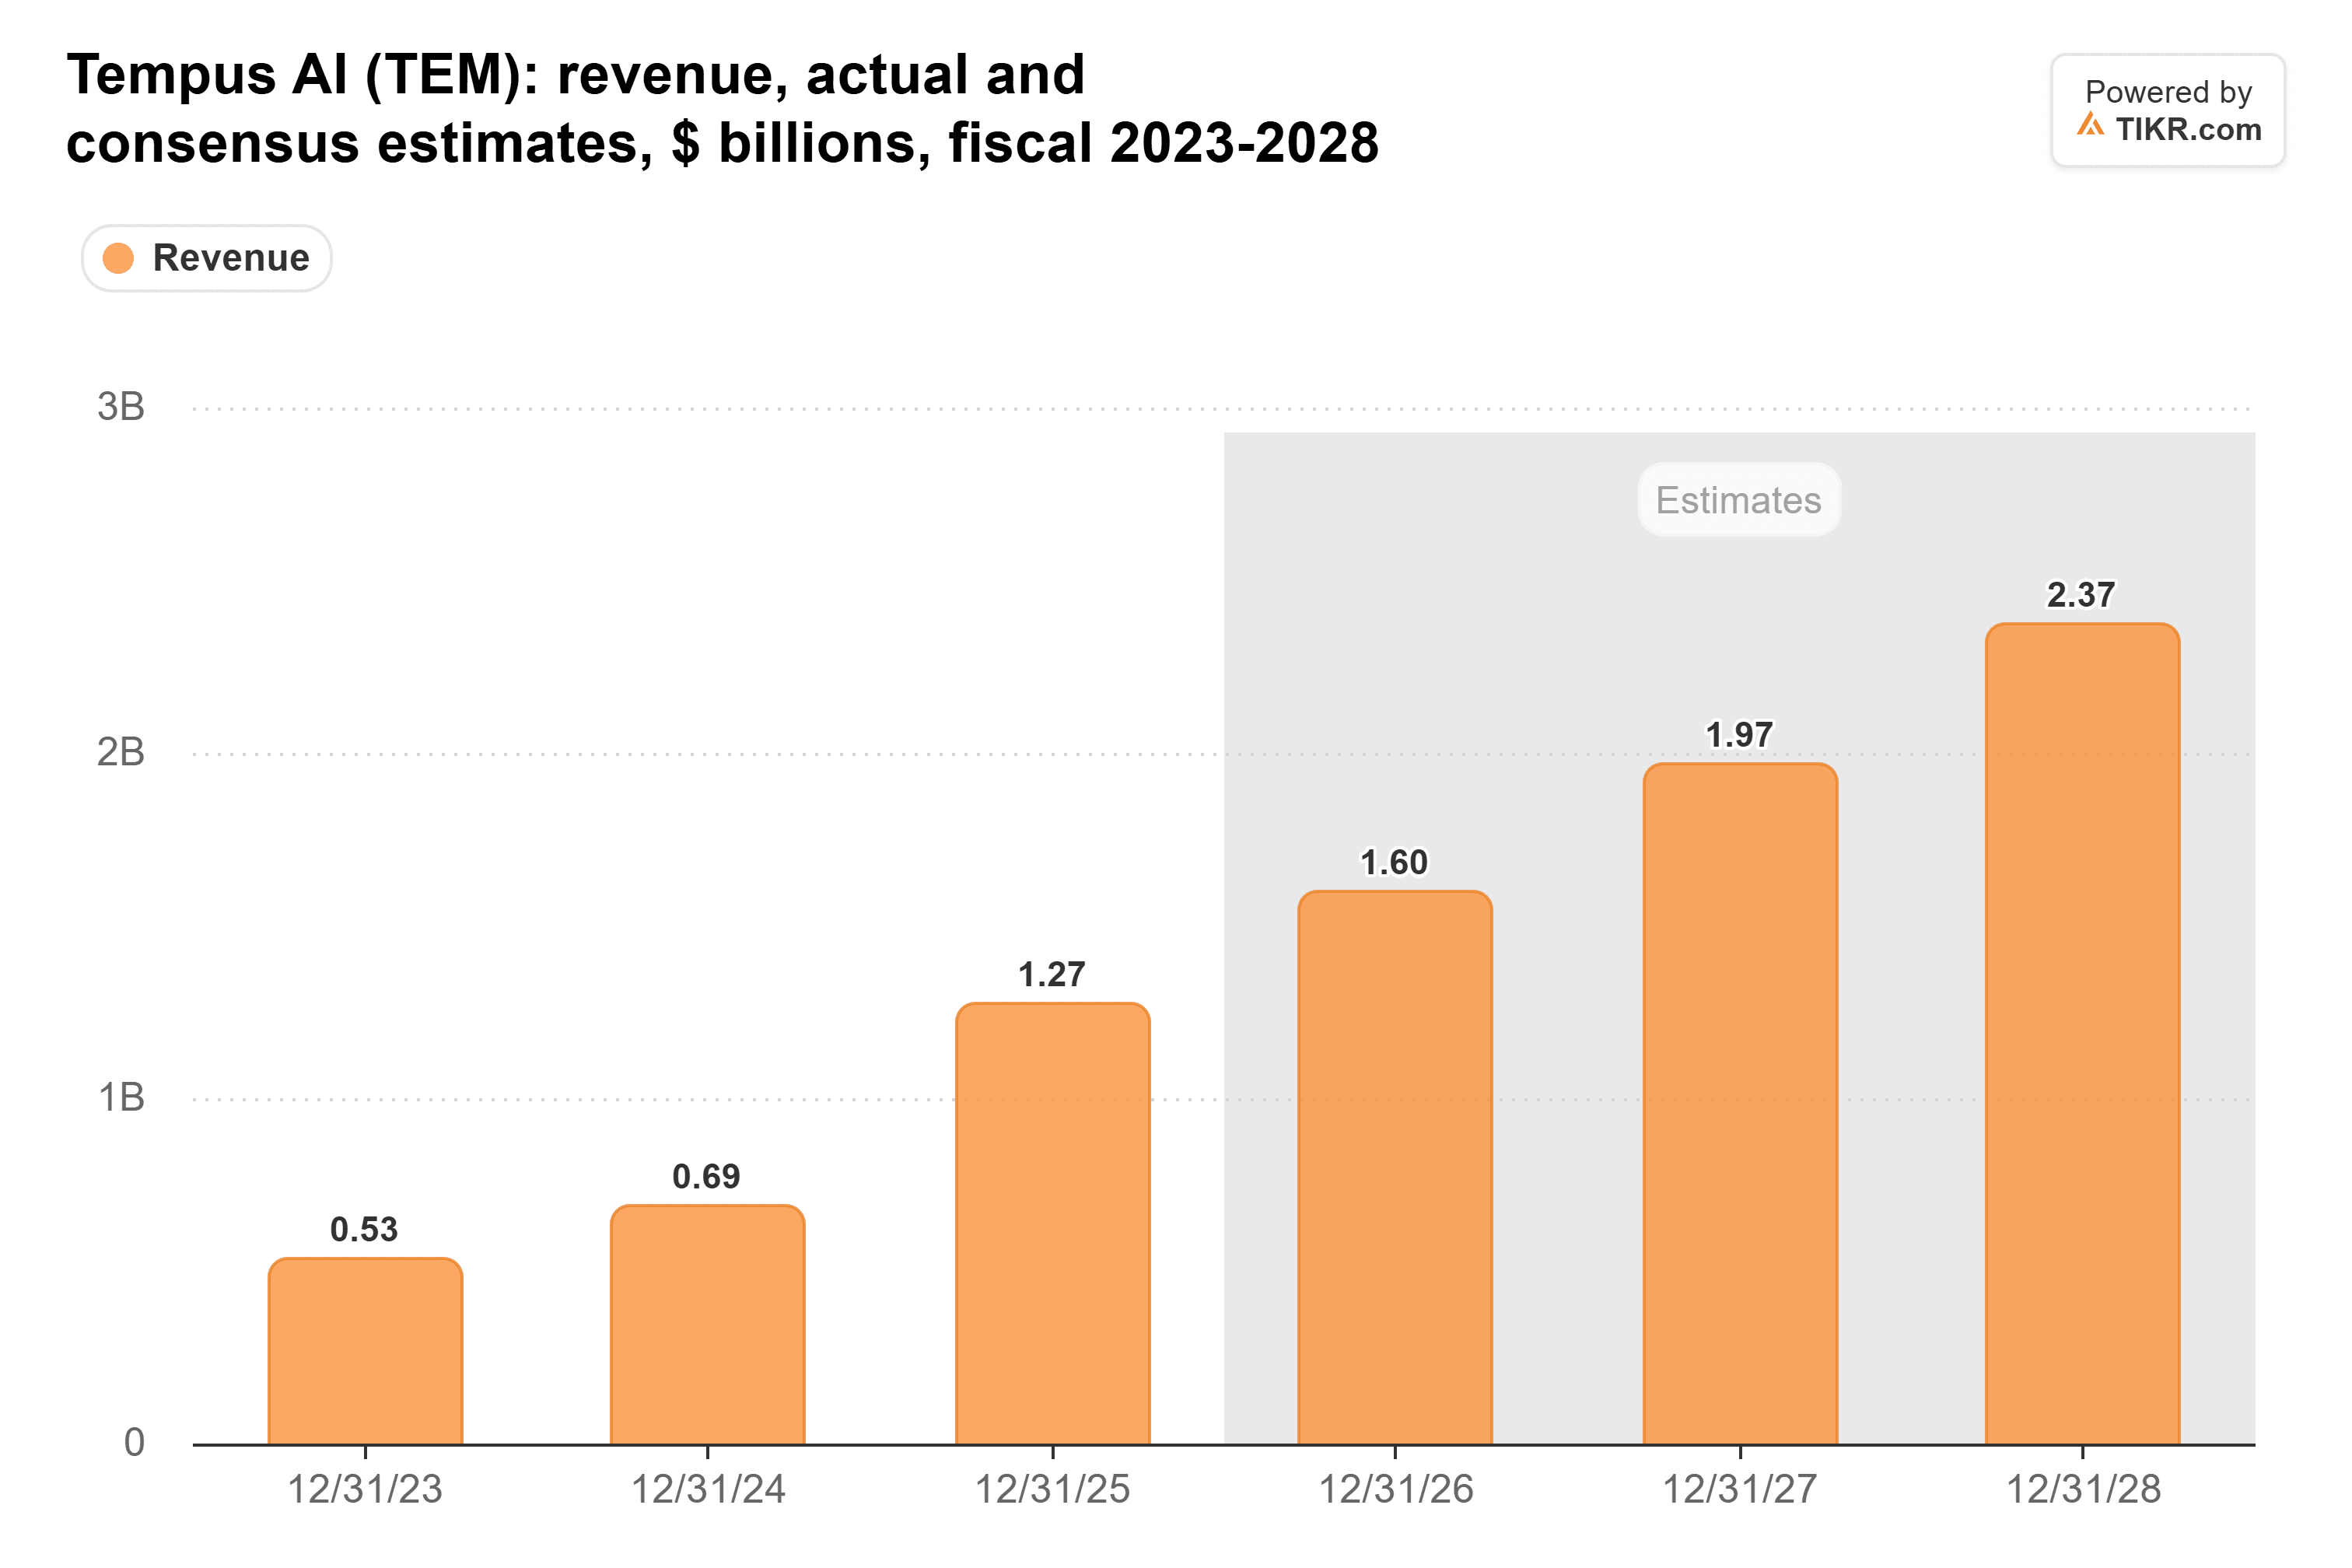
So I wouldn’t expect this report to move the revenue estimates much. The surprise was in the margins.
Data is doing the heavy lifting
Data and Applications earned a 71.5% gross margin in the quarter, against 62.4% for Diagnostics. So as data grows faster, the whole company’s margin widens:

It reached 64.8% in the third quarter.
Drugmakers are paying for that data, too. Tempus’s licensing bookings are above $550 million so far this year, including the oncology data it licensed to Bristol Myers Squibb in October.
TIKR tracks 20 analysts on Tempus AI. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Tempus AI, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Tempus AI’s Analyst Ratings
Natera and Guardant are still growing faster
Natera, down [7%] today, added 34,000 clinical MRD tests in the second quarter over the first. That one quarter’s gain is nearly three times Tempus’s entire third-quarter MRD volume, so Natera’s Signatera lead looks safe for now.
Guardant, down [5%], grew oncology test volume 63% in the second quarter and expects about 50% for the year, well ahead of Tempus’s 32%. So Tempus doesn’t look like it’s taking Guardant’s business yet. Both report later this week.
Investors are already paying up
Tempus traded at 7.3x forward sales at Friday’s close, above its one-year average of 6.6x. At today’s price, it’s even higher:

The way I see it, this was a genuinely strong quarter, and the data business is the reason to own Tempus. But at these prices, the stock needs the margin gains to keep coming.
To hit its $65 million EBITDA target, Tempus needs about $34 million in the fourth quarter, a clear step up. That’s the number to watch next.
So what is Tempus AI stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Tempus AI could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!