Key Takeaways
- Altria and British American Tobacco each paid out 78% of their free cash flow as dividends over the twelve months to June 30, 2026, and they yield 6.5% and 6.3%.
- Altria paid out between 75% and 82% of its free cash flow in every year from fiscal 2021 to fiscal 2025, with net debt at 1.4x EBITDA.
- British American Tobacco’s dividend took 91% of its free cash flow in fiscal 2025, after free cash flow fell from £9.6 billion to £5.8 billion, and its net debt is 2.9x EBITDA.
- British American Tobacco trades at 10.9x forward earnings, against 11.9x for Altria, and targets cash conversion above 95% for 2026.
Over the twelve months to June 30, 2026, Altria Group (MO) and British American Tobacco (BTI) each paid out 78% of their free cash flow as dividends, and both yield over 6% today.
They got to that 78% very differently, though. Altria has paid out a similar share of its cash for years. British American Tobacco’s payout ratio jumped from 54.7% in fiscal 2024 to 91.4% in fiscal 2025 before it settled back.
So which is the better dividend stock?
| Metric | Altria (MO) | British American Tobacco (BTI) |
|---|---|---|
| Dividend yield | 6.5% | 6.3% |
| Dividend growth, fiscal 2020–2025 | 4.1% a year | 2.2% a year |
| Cash dividend payout ratio (TTM) | 78% | 78% |
| Net debt/EBITDA | 1.41x | 2.88x |
| Interest coverage | 13.27x | 5.2x |
| Forward P/E | 11.9x | 10.9x |
Altria: pouches up, cigarettes down
Altria’s revenues net of excise taxes were $5.36 billion in the second quarter of 2026, up 1.2% from the same quarter a year before. Management points to declining domestic cigarette and moist smokeless tobacco volumes. Meanwhile, on! PLUS nicotine pouches are growing and are now in 120,000 stores.
CEO Salvatore Mancuso also sees help from the crackdown on illegal vapes: “We believe increased enforcement activity, including supply-related disruptions at the border, is helping slow demand for illicit products.”
Management guides to 2026 adjusted EPS of $5.61 to $5.72, up 3.5% to 5.5% from $5.42 in 2025. Free cash flow has topped dividends paid every year since fiscal 2018.
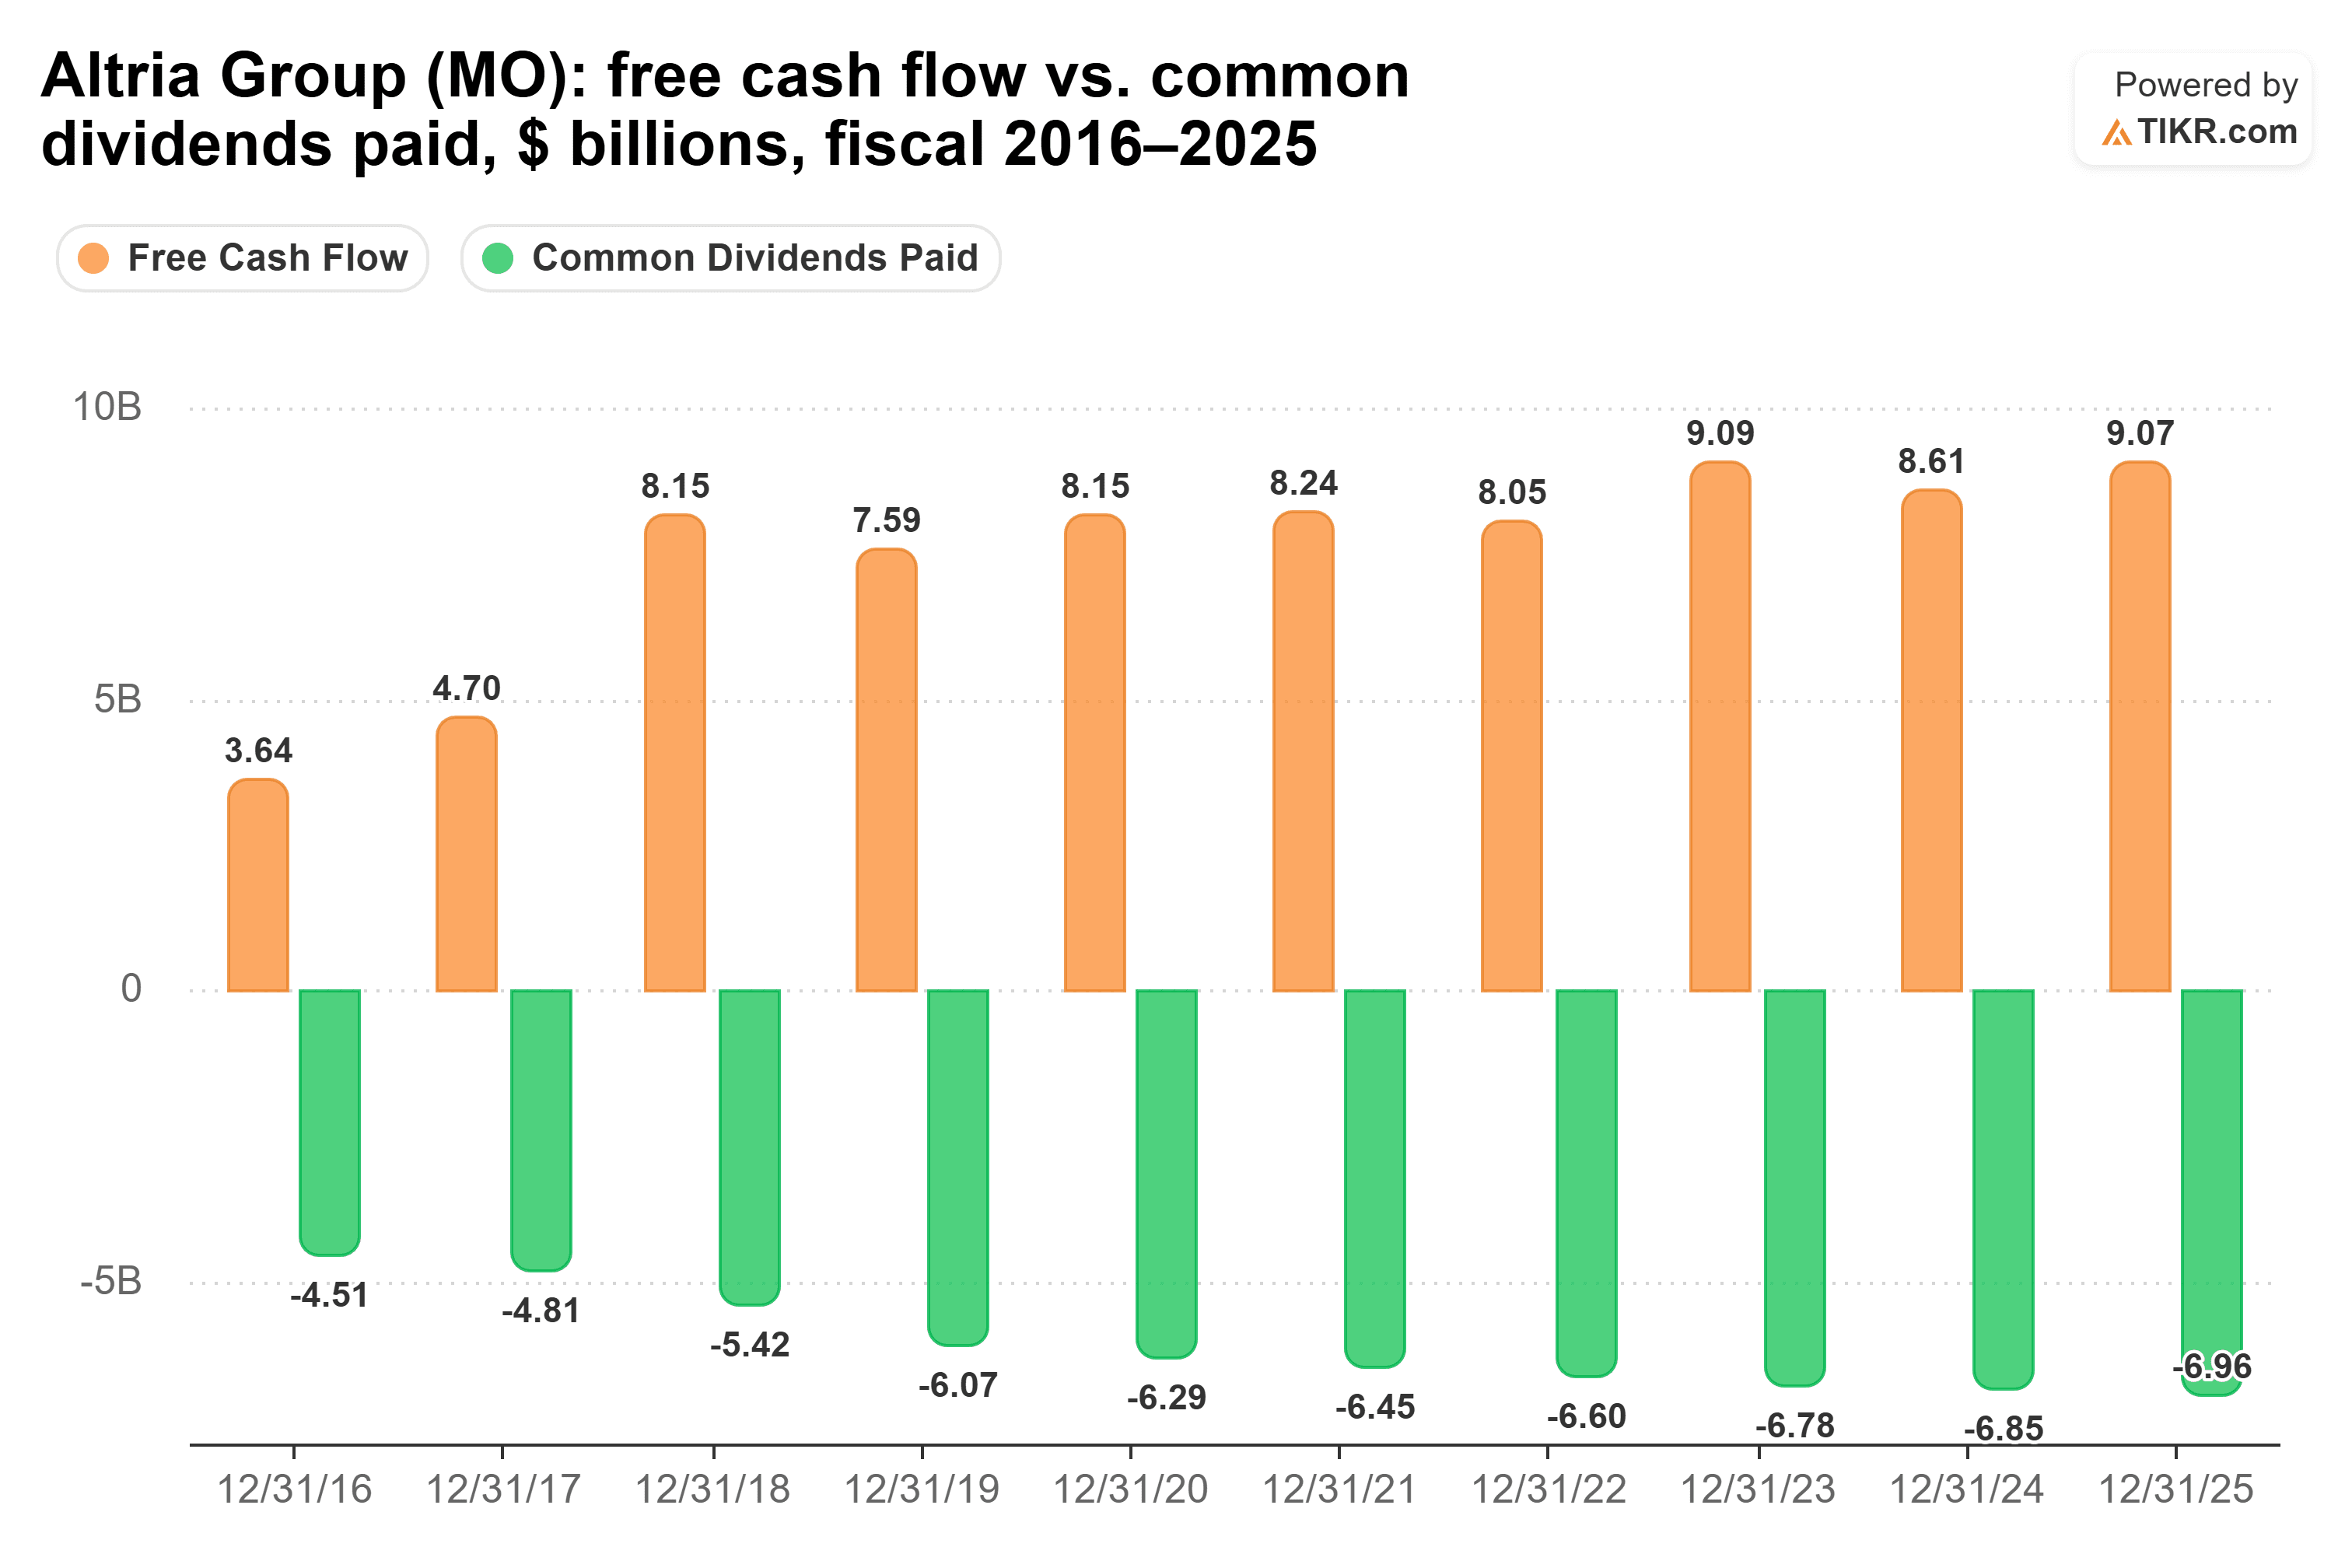
Altria paid out between 74.6% and 82.0% of its free cash flow each year from fiscal 2021 to fiscal 2025. That’s a high ratio, but a steady one. Net debt is a light 1.41x EBITDA, and EBIT covers interest 13.27x.
The main risk is the consumer. Management names continued pressure on adult nicotine consumers’ discretionary income, and a 78% payout ratio leaves limited slack if volumes fall faster.
British American Tobacco took the bumpier road
British American Tobacco reached the same 78% by a rockier route. Its EPS rose 5.5% in the first half of 2026, and New Categories grew 18%. Velo pouches are growing in the US, while Heated Products fell 12%. For the full year, management expects adjusted EPS growth of around 4% to 4.5% on a current basis.
Through fiscal 2024, its dividend was the better covered of the two, taking between 49.9% and 54.7% of free cash flow each year from fiscal 2021. Then free cash flow fell from £9.64 billion in fiscal 2024 to £5.79 billion in fiscal 2025…

…and the dividend ate a risky 91.4% of it. Free cash flow came back to £6.85 billion over the twelve months to June 30, 2026. CFO Syed Iqbal credited part of the first half’s cash strength to lower financing costs after the company repaid debt. Management targets cash conversion above 95% for the full year.
Through it all, CEO Tadeu Marroco has stuck to “our progressive dividend and sustainable share buyback.” Dividends per share rose 11.0% in fiscal 2025, even at that 91.4% payout.
The main risk is debt: net debt runs 2.88x EBITDA, and EBIT covers interest 5.2x. The dividend is also set in pounds, so the dollars US holders receive move with the exchange rate.
So which dividend wins?
Altria is the better dividend stock. It pays the bigger yield and has grown its dividend faster: 4.1% a year from fiscal 2020 to fiscal 2025, against 2.2%. It also backs that dividend with steadier cash and far less debt.
Put $10,000 into Altria, and it pays $650 a year now. At its 4.1% pace, that grows to about $935 in year 10, a 9.3% yield on your cash today. The same $10,000 in British American Tobacco pays $630 now and about $769 in year 10.
British American Tobacco’s case is a good one. It’s cheaper, at 10.9x forward earnings against 11.9x, and its dividend was better covered than Altria’s for years. At its fiscal 2025 pace of 11.0%, its income on $10,000 would pass Altria’s in 2027.
But that raise came in the year its dividend ate 91.4% of free cash flow, and 2026 adjusted EPS growth is guided at around 4% to 4.5%. I wouldn’t count on that pace lasting. For a 6%+ yield, I want the steadier cash and the lighter debt, and that’s Altria.
Of course, British American Tobacco could hit its cash conversion target and get free cash flow back to where it ran before fiscal 2025. If it does, its dividend would be the better covered of the two again.
So what is Altria stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Altria could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!