Key Takeaways
- A $3.2 billion fund opened new positions in Snowflake, TTM Technologies and Meta Platforms in the third quarter, its 13F shows.
- All three stocks have fallen since Sept. 30, from 23% for Meta to 52% for TTM.
- Analysts’ average price targets are 51% above Meta’s price and 216% above TTM’s.
- Snowflake is the one to buy first because its earnings estimates keep rising while its stock falls.
The third quarter’s 13Fs are in, and one of the more interesting ones comes from a fund most investors have never heard of.
Tremblant Capital Group’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows $3.24 billion of US stocks across 62 positions. Its three biggest new positions were Snowflake (SNOW), TTM Technologies (TTMI) and Meta Platforms (META).
All three have fallen since Sept. 30. (A 13F shows only what a fund held that day, so it can’t tell us what the fund paid or whether it still owns the shares.) So are they bargains now?
Snowflake’s estimates keep climbing
Snowflake is the biggest of the three: 351,240 shares worth $119 million on Sept. 30, 3.7% of the fund’s 13F and its third-largest holding. The stock has dropped 25% since then, even as the business keeps speeding up. Product revenue grew 37% to $1.49 billion in the quarter ended July 31, its third straight quarter of faster growth, and management credits AI products with about half of that acceleration.
Analysts have been raising their numbers all along. They expect normalized EPS to more than triple, from $1.25 in fiscal 2026 to $4.34 in fiscal 2029, and their average price target climbed from $271 a year ago to $432 now:
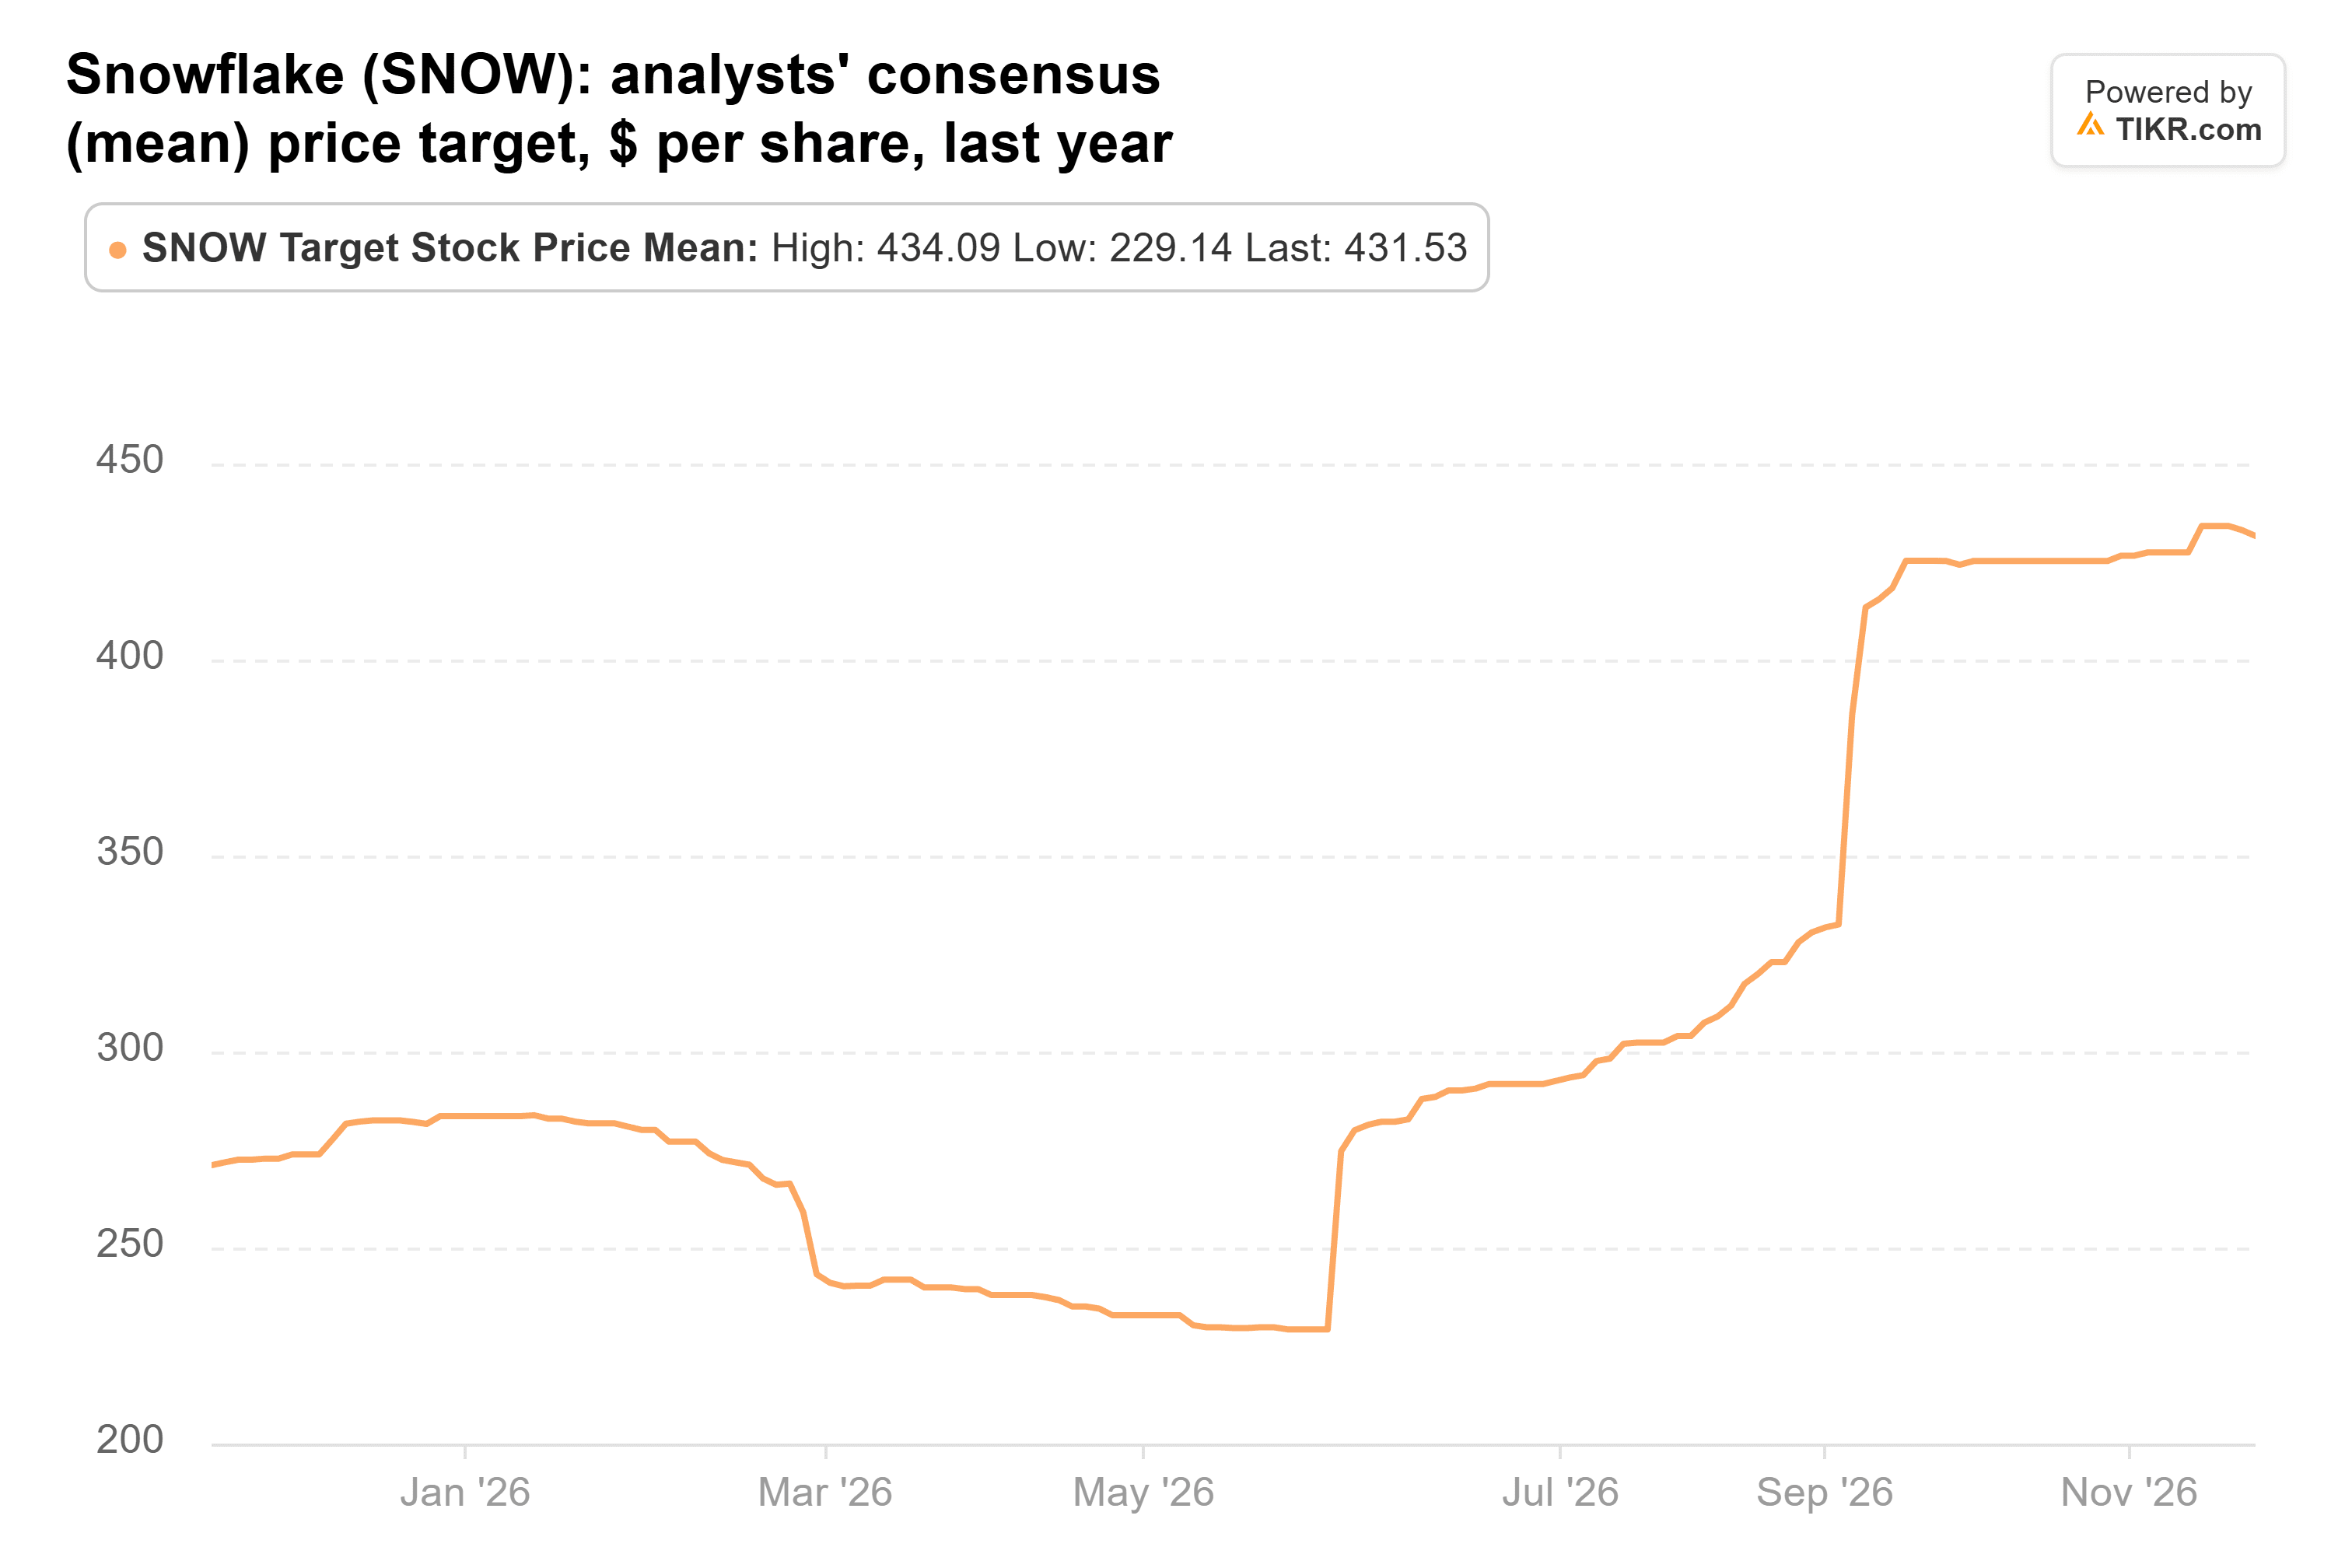
That’s 69% above the stock’s price, and the stock wouldn’t need a higher multiple to get there. On the fiscal 2029 estimate, $432 is about 99x earnings. That’s just under today’s forward P/E of about 101x and well below the 130x Snowflake has averaged over the past year.
TIKR tracks 53 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
The risk is that usage-based revenue can stall fast. Datadog, which also bills on usage, just guided to flat revenue from its third quarter to its fourth after its biggest customer cut back. AI work also costs Snowflake more to run: non-GAAP product gross margin slipped to 74.7% in its latest quarter from 76.4% a year earlier.
TTM sank on a record quarter
The fund held 825,377 shares of TTM worth $101 million on Sept. 30, 3.1% of its 13F. The stock is down 52% since, and it’s hard to blame the business. TTM said in its third-quarter release that net sales jumped 60% to a record $1.2 billion. Data center and networking sales rose 115% to 41% of the total, and the book-to-bill was 2.13.
The problem was the outlook. TTM’s fourth-quarter guide puts 2026 sales at $4.47 billion to $4.49 billion and adjusted EPS at $4.97 to $5.03. That only matched estimates, and the stock sank 28% after the report.
Analysts’ average target climbed from about $70 a year ago to a peak of $214 in August:

It’s still about $186, more than 3x the price, and the stock trades at about 8x forward earnings. My read: the market is treating TTM’s AI orders as a peak, and analysts aren’t. One side is badly wrong.
Meta’s spending is the whole debate
TTM sells into the AI build, and Meta is one of the companies paying for it. The fund’s 139,629 Meta shares were worth $101 million on Sept. 30, also 3.1% of its 13F, and the stock is down 23% since. The fund isn’t alone: Dan Loeb’s Third Point made Meta its biggest US holding in the same quarter.
The ad business is humming. Third-quarter revenue rose 26% to $64.6 billion, with price per ad up 14%, and management guides fourth-quarter revenue to $73 billion to $76 billion. But third-quarter capex of $34.9 billion topped operating cash flow of $32.8 billion. Consensus has free cash flow bottoming at negative $48.0 billion in 2027.
Through all of it, Wall Street’s average target has barely moved. It was $840 a year ago and is $848 now:

That’s 51% above the price. Meta trades at about 17x forward earnings, against a five-year average of about 21x. Analysts expect $40.42 of normalized EPS for 2028, and $848 is about 21x that. So the stock needs only Meta’s usual multiple to reach the target, but the estimates are drifting lower: analysts have cut their 2027 EPS estimate about 4% since June.
I’d start with Snowflake
All three cases rest on AI spending holding up, so a pullback in the buildout would hit them together. If I could only buy one right now, it’d be Snowflake. Its estimates are rising while its stock falls, and reaching its target takes a lower multiple than the stock usually gets. Meta is a close second at 17x, but I’d want to see its 2027 spending plan in late January first.
Snowflake reports in early December. Product revenue above the top of its $1.59 billion guide, with product gross margin at or above 74%, would back the case. A slim beat or a margin below 74% would weaken it. The fund’s next 13F, due by mid-February, will show whether it held on.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!