Key Takeaways
- Long Focus Capital Management, which manages $2.44 billion, sold all of its Pinterest and Apollo Global Management shares in the third quarter, its latest 13F shows.
- Pinterest is down 14% since Sept. 30, after third-quarter revenue came in below the company’s own guidance.
- Apollo’s stock has barely moved since Sept. 30, and its fee-related earnings hit a record $802 million in the third quarter, up 23% from a year earlier.
- Selling Pinterest looks like the right call, but Apollo is the one I’d have kept.
A $2.44 billion fund just sold out of two well-known stocks: Pinterest (PINS) and Apollo Global Management (APO).
Long Focus Capital Management filed its 13F for the quarter ended Sept. 30 on Nov. 16, and it shows no shares of either at the end of the quarter. Since then, the two stocks have gone in very different directions.
Two exits and two bigger bets
At June 30, the fund held 2.40 million Pinterest shares worth $51 million, or 2.1% of its 13F stocks. It also held 359,000 Apollo shares worth $42 million, or 1.7%. Neither was a big position, but selling every share is still a clear call.
The fund was busy elsewhere too. By Sept. 30, its 13F held $2.14 billion of US stocks across 64 positions. Rocket Companies was its No. 2 holding after the fund more than doubled its shares to 12.61 million, worth $145 million (6.8% of its 13F stocks). It also added 43% to its Microsoft stake, which ended the quarter at 243,200 shares worth $125 million, or 5.8%.
TIKR tracks 38 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Pinterest is cheap for a reason
Pinterest is down 14% from its Sept. 30 close. Since a 13F doesn’t show what the fund got for its shares, that’s only the stock’s move.
The business news has been rough. Pinterest’s third-quarter revenue rose 12% to $1.174 billion, which missed its own guidance of $1.19 billion to $1.21 billion. Revenue growth in the US and Canada, which bring in about three-quarters of sales, slowed to 14% from 18% in the second quarter. The average price per ad fell 4% after rising 1% the quarter before. The top of the new fourth-quarter guidance also points to about $4.84 billion of 2026 revenue, below the $4.91 billion analysts expected going in.
Analysts have been cutting their targets all year. The consensus target fell from $37.64 a year ago to $25.03:
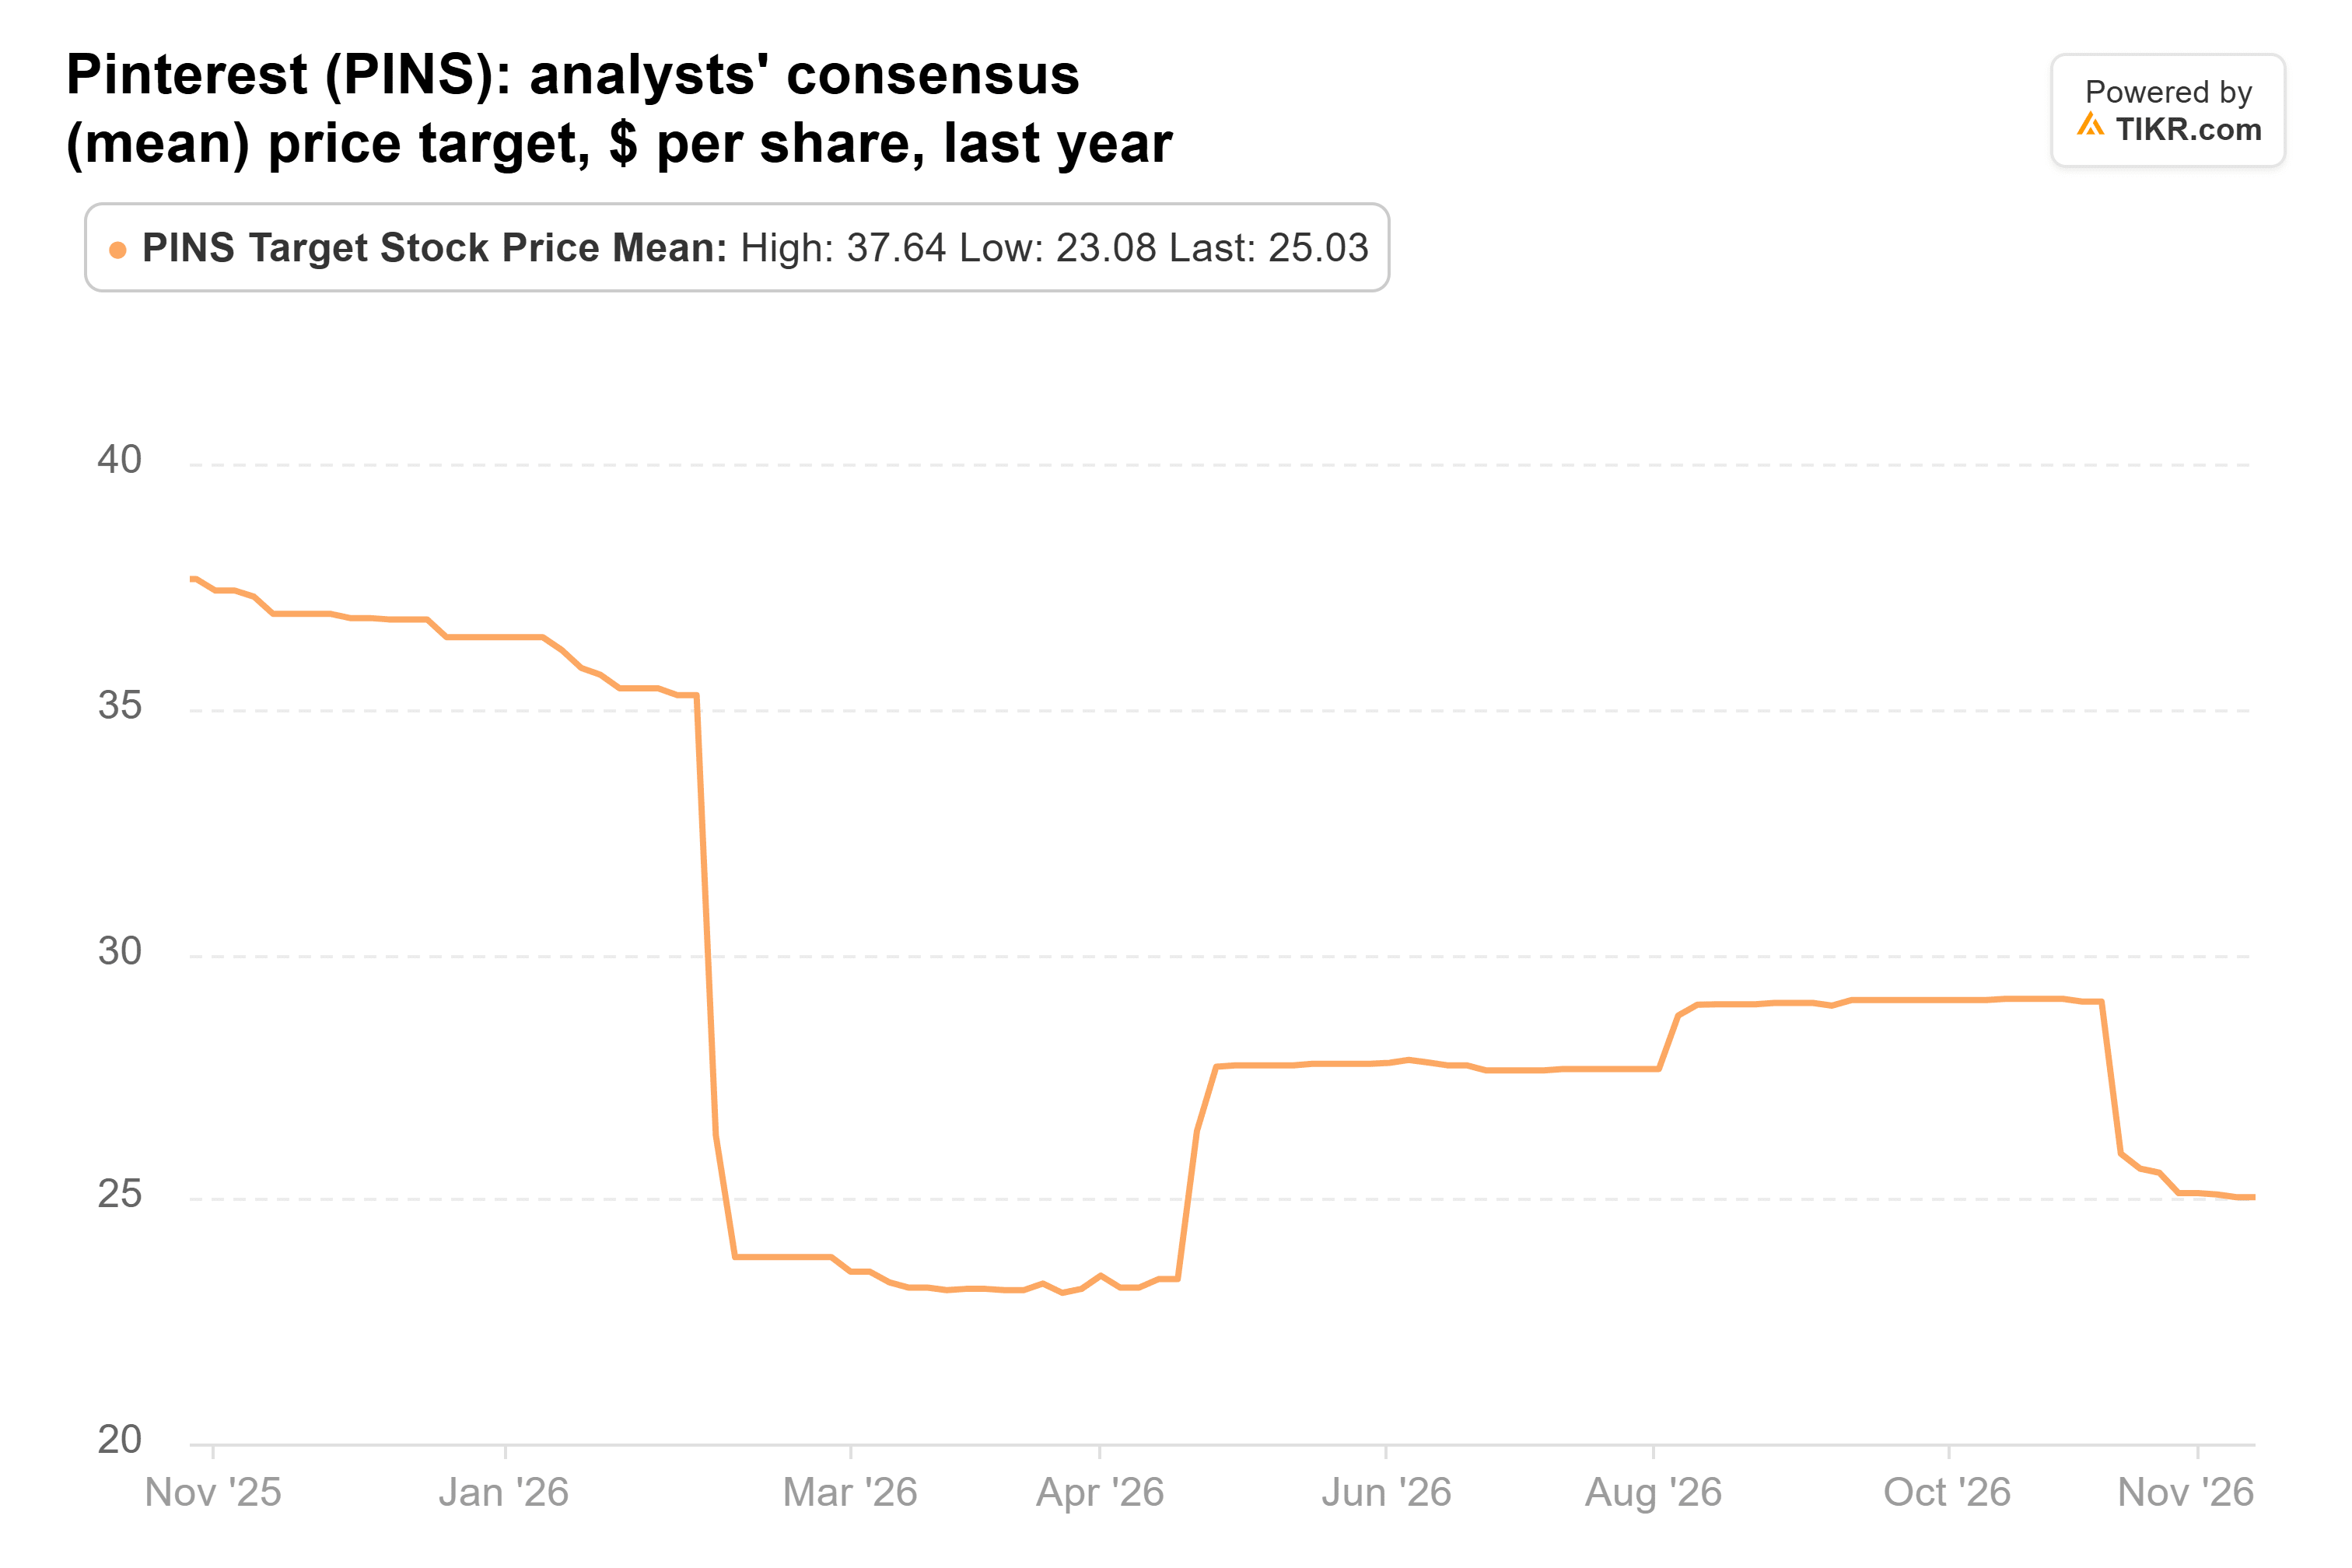
The cuts kept coming after the report. Wells Fargo cut its target to $23 from $31, Barclays to $24 from $31, and Mizuho to $25 from $32.
On valuation, the stock looks like a bargain. It trades at about 8x forward earnings, against a one-year average of about 12x and a five-year average of 24x. The $25.03 consensus target from 38 analysts is 39% above the price. But after the report, analysts cut their 2027 revenue estimate to $5.41 billion from $5.55 billion. Until those cuts stop, I’d expect the stock to stay cheap.
Apollo’s fee earnings hit a record
Apollo has had a much calmer run. The stock is down 0.4% from its Sept. 30 close.
Its third-quarter release on Nov. 3 showed record fee-related earnings of $802 million, up 23% from a year earlier. Assets under management reached $1.07 trillion, up 18%. Apollo did report a GAAP net loss of $1.1 billion. It blamed that mainly on unrealized mark-to-market losses on investments in its Retirement Services business as interest rates rose. Adjusted net income was $1.3 billion, or $2.07 a share.
Analysts have trimmed their targets too, but far less than on Pinterest. The consensus target is now $146.76, down from $158.51 a year ago:
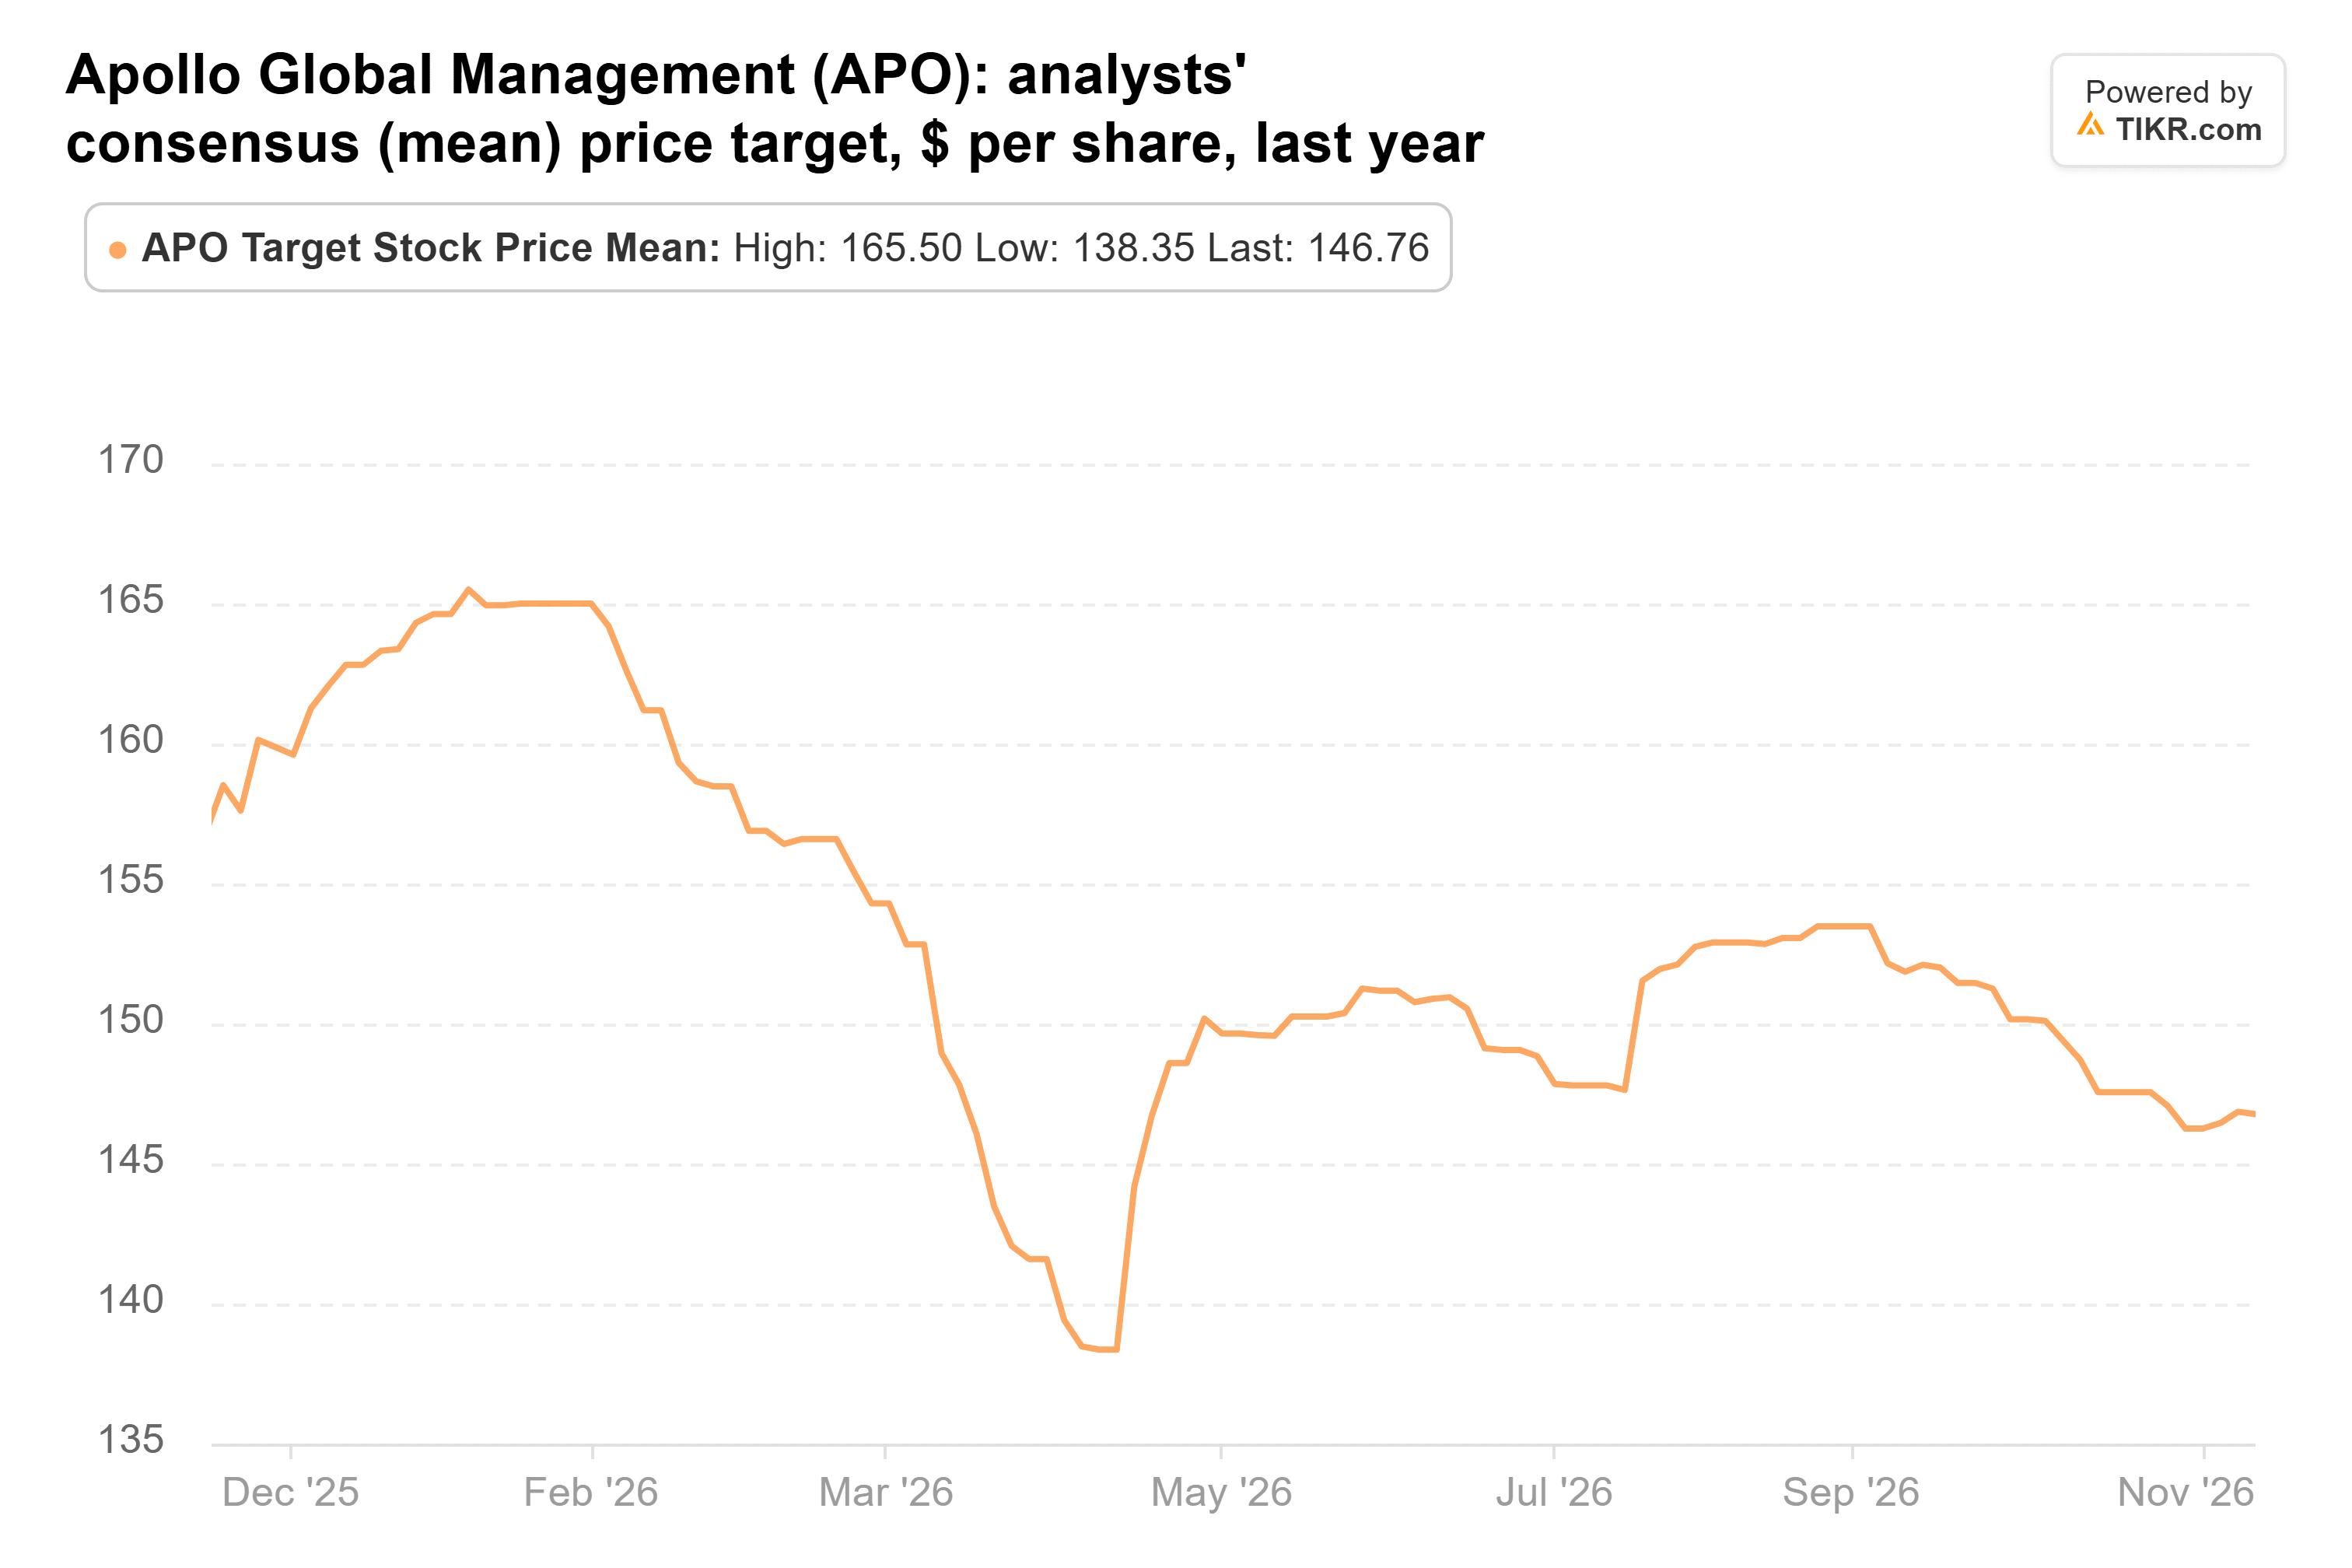
That target, from 23 analysts, is 24% above the price. The stock is 23% below its 52-week high and trades at about 12x forward earnings.
Only one of these exits makes sense to me
Selling Pinterest looks like the right call. Revenue growth slowed, ad prices fell, and analysts are still cutting their estimates. The best case for Pinterest is that at 8x earnings it doesn’t need much to go right, and a 39% gap to the consensus target is a lot of room if the estimates hold.
Apollo is the one I’d have kept. Its fee earnings are growing more than 20% a year, and at about 12x forward earnings, investors aren’t paying much for that growth. The risk is the retirement business, whose results swing with interest rates, as the third quarter’s $1.1 billion GAAP loss showed.
There are two tests ahead. Pinterest’s fourth-quarter report in early February should bring its 2027 outlook, which will be judged against the $5.41 billion of revenue analysts now expect. Apollo also reports early next year, and fee-related earnings growth near the third quarter’s 23% would back the bull case. The fund’s next 13F is due in mid-February and will show whether it bought back into either stock.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!