Key Takeaways
- Micron shares have fallen 30% in three months. RBC Capital Markets reiterated its Outperform rating and $1,500 price target, 114% above today’s price.
- Worries about NVIDIA’s leadership and NAND prices have hit memory stocks, Sandisk included. Over the same three months, analysts raised Micron’s fiscal 2028 earnings estimate by 23%.
- RBC’s target is 7.2x that fiscal 2028 estimate, below Micron’s usual multiple, though memory stocks have looked this cheap before at a cycle peak.
- RBC’s call looks right, and Micron’s fiscal first-quarter results in December are the next test.
Micron Technology (MU) has fallen 30% in three months. On Nov. 18, RBC Capital Markets analyst Srini Pajjuri reiterated his Outperform rating and $1,500 price target, 114% above today’s price.
The selling has hit the whole memory group. At the Nov. 17 close, Sandisk (SNDK) traded at 3.3x forward earnings, even lower than Micron’s 4.0x. Investors have also been selling on worries about NVIDIA (NVDA), whose next GPUs will use Micron’s custom HBM4E.
The worries keep piling up
On Oct. 16, Elon Musk said on X that a fast Chinese ramp of LP5 and LP6 memory would make 2028 “a different story.” By Nov. 16, Jensen Huang had left as NVIDIA’s CEO. On Nov. 17, GF Securities cut its NAND price forecasts and warned of a possible surplus in 2027.
RBC calls the pullback an opportunity
RBC raised its target to $1,500 from $1,200 in June and has kept it through the slide. It says Micron’s management still expects supply to be tighter in 2027 and 2028 than in 2026. RBC sees room for a higher multiple as the cycle’s length becomes clearer over the coming quarters.
TIKR tracks 49 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Does $1,500 add up?
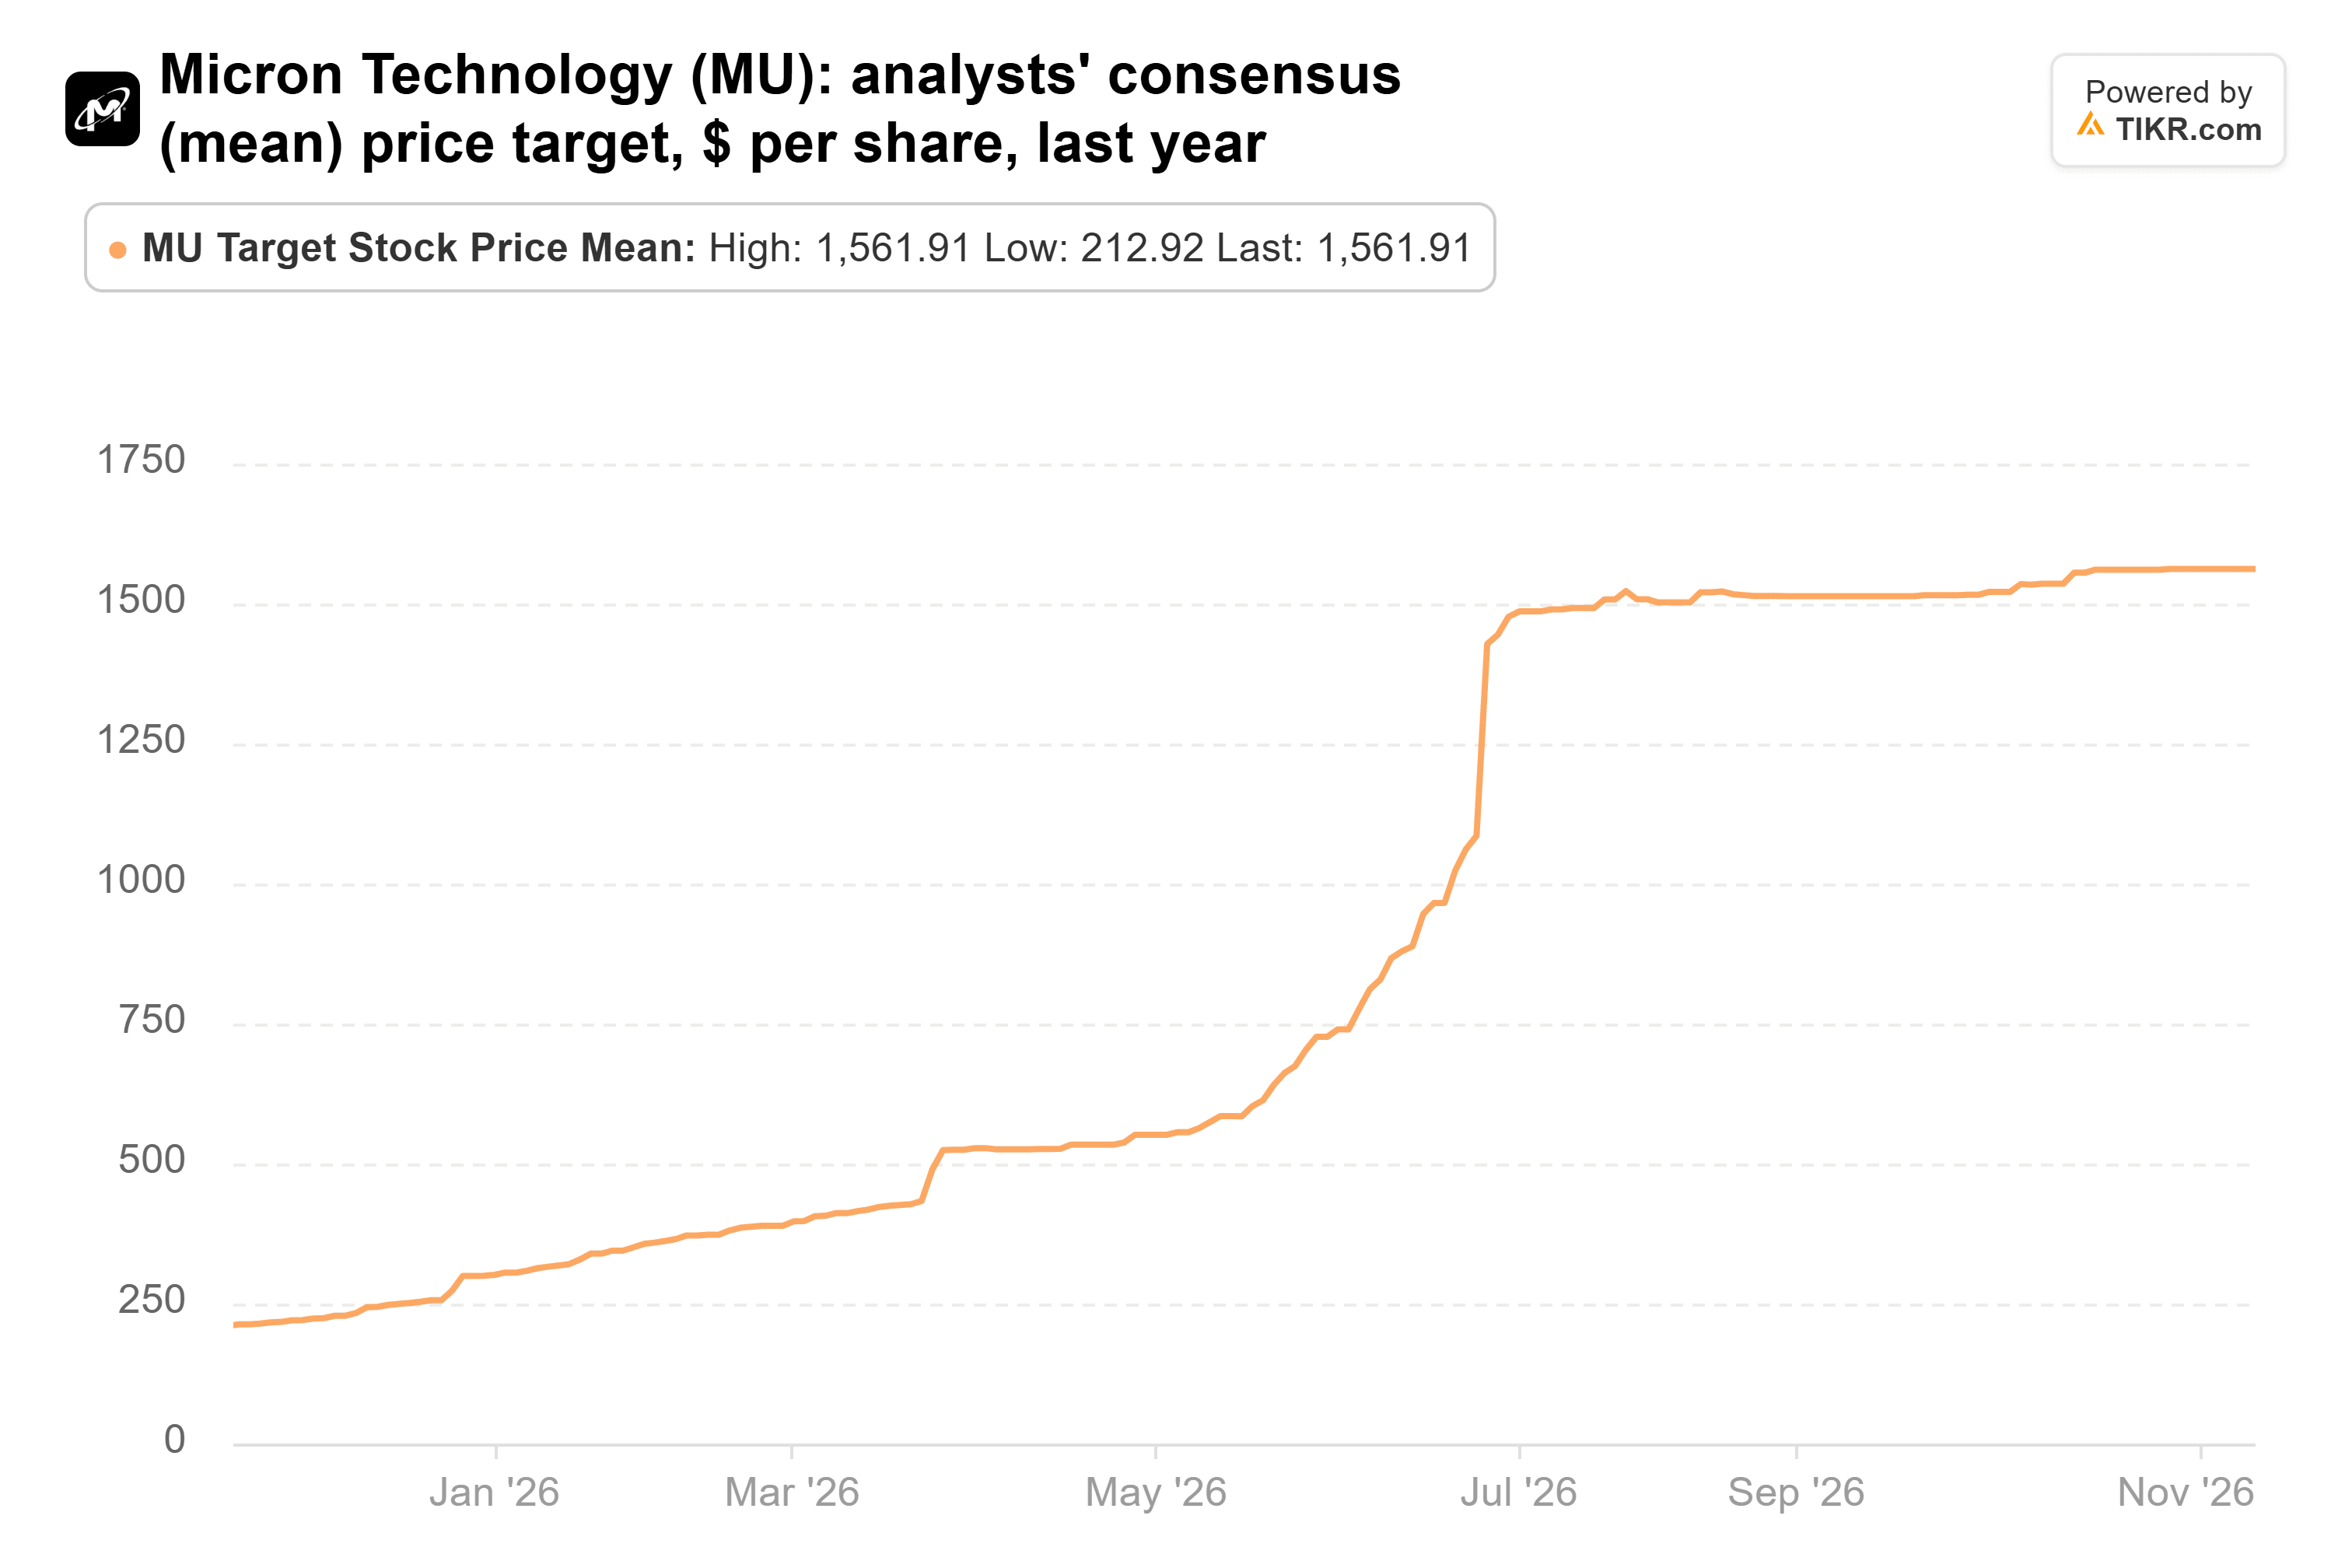
The consensus target rose more than 7x in a year, to $1,562 from $213:
Analysts expect normalized EPS of $176.50 in fiscal 2027 and $207.76 in fiscal 2028, up from $75.52 in fiscal 2026:

The fiscal 2028 estimate is up 23% in three months, while the stock fell 30%.
A year from now, investors will be pricing fiscal 2028. On that year’s estimate, $1,500 is 7.2x earnings. (RBC hasn’t published its method, so that math is ours.) Earnings growth would add about 18%. The rest needs a multiple 78% above the 4.0x the stock closed at on Nov. 17. That’s not much to ask: Micron’s forward P/E was 6.6x at the end of September, and its median at quarter-ends since 2014 is about 10x.
Why I’d side with RBC
Memory stocks often look cheapest at the peak: Micron’s forward P/E was between 3.7x and 5.3x in 2017 and 2018, and its GAAP EPS then fell 79% from fiscal 2018 to fiscal 2020.
RBC’s call still looks right to me. The target needs a multiple close to where Micron traded less than two months ago, and earnings estimates keep rising.
The next test is Micron’s fiscal first-quarter report in December. RBC’s case holds up if revenue comes in at or above the $61.5 billion guide and non-GAAP gross margin is at or above 86.25%, which management calls this fiscal year’s floor.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!