Key Takeaways
- RBC analyst Rishi Jaluria said Salesforce can’t shut off its customers’ access to whatever AI model they want, with Anthropic’s IPO expected this week.
- That lets AI labs compete for the work and the per-seat pricing behind Salesforce’s growth plan, a pressure ServiceNow faces too.
- Analysts still expect Salesforce’s revenue to grow from $41.5 billion to $55.7 billion over three fiscal years.
- At 15x forward earnings, about half its five-year average, the stock already prices in much of that threat, and the Dec. 2 report is the next test.
Salesforce (CRM) can’t keep its customers’ data away from the AI models they choose. With Anthropic’s IPO expected this week, that matters more than it sounds.
Rishi Jaluria, a software analyst at RBC Capital Markets, talked about it on this week’s episode of the RiskReversal Pod. Asked whether partnerships with the frontier labs could put a floor under software stocks, he said the ones on display at Salesforce’s Dreamforce conference start “to put a little bit of a damper in the, hey, you know, the AI companies are going to try to destroy Salesforce entirely, right?”
Then he made the point that matters more for shareholders:
“You can’t say we’re going to shut off Salesforce access to whatever AI model that our customers want to use. We have to have that integration.”
For the labs, that’s an open invitation.
TIKR tracks 56 analysts on Salesforce. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Salesforce, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Salesforce’s Analyst Ratings
Salesforce left the door open on purpose
Any customer that can point Claude at its Salesforce data now gets to choose where the work happens. And that customer is still looking for a payoff from what it’s already spent. Jaluria said enterprises are “still debating, okay, we’ve spent all this money, where are we getting the cost savings that are tangible in metrics?” A customer asking that, with its data a click away from Claude, has every reason to push back on paying for seats an agent is starting to fill.
Salesforce isn’t alone here. ServiceNow (NOW) runs IT workflows I’d expect the labs to want to build on too. And Salesforce is going after ServiceNow directly: more than 450 customers use its IT service management product, including some that switched over from ServiceNow, it said on its second-quarter call.
The seat is what’s at stake
Salesforce bills mostly per user, and its growth plan depends on those users paying more. Only 5% of the people using its sales and service products have upgraded to the higher-end editions, which carry a 60% to 80% premium, Chief Operating Officer Miguel Milano said on the second-quarter call. Each 1% of the base moved up is worth $100 million, Chief Revenue Officer Alexa Vignone said at September’s Investor Day. That lever only works if people keep logging in.
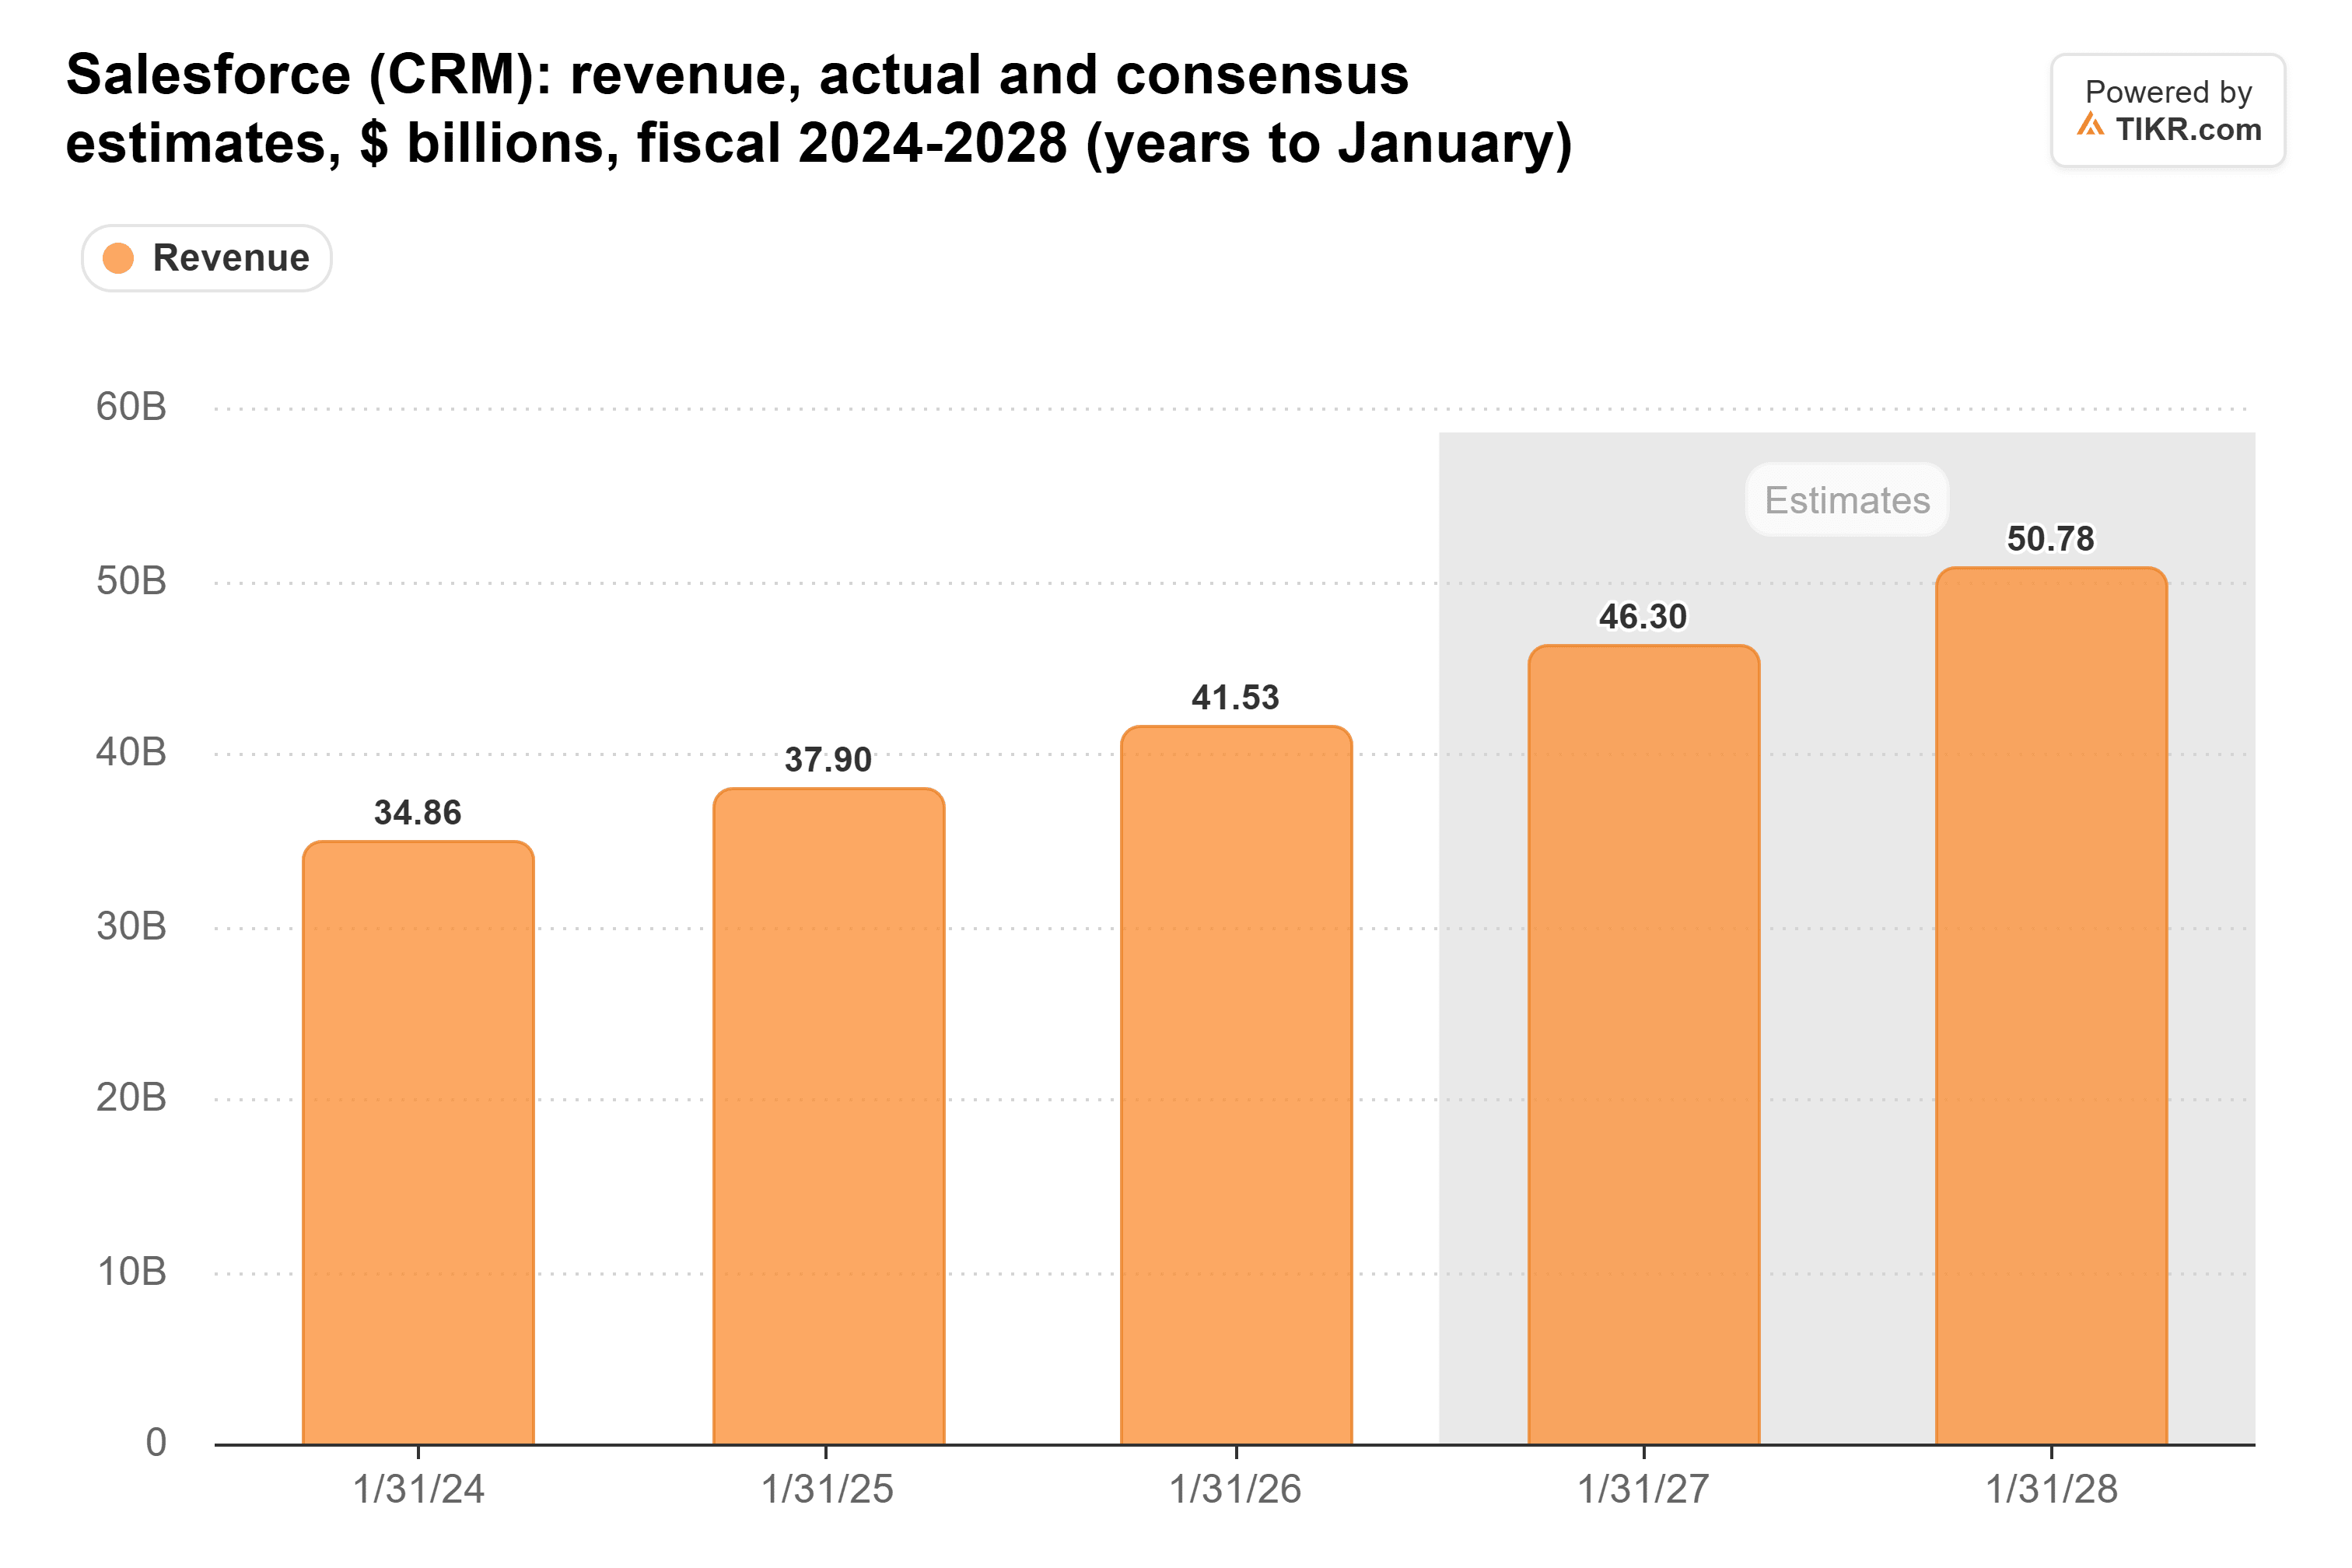
Analysts expect revenue to grow from $41.5 billion in the year ended January 2026 to $55.7 billion in the year ending January 2029.
A lot of money is riding on this. Salesforce’s free cash flow nearly tripled in four years, from $5.3 billion in the year ended January 2022 to $14.4 billion in the year ended January 2026.
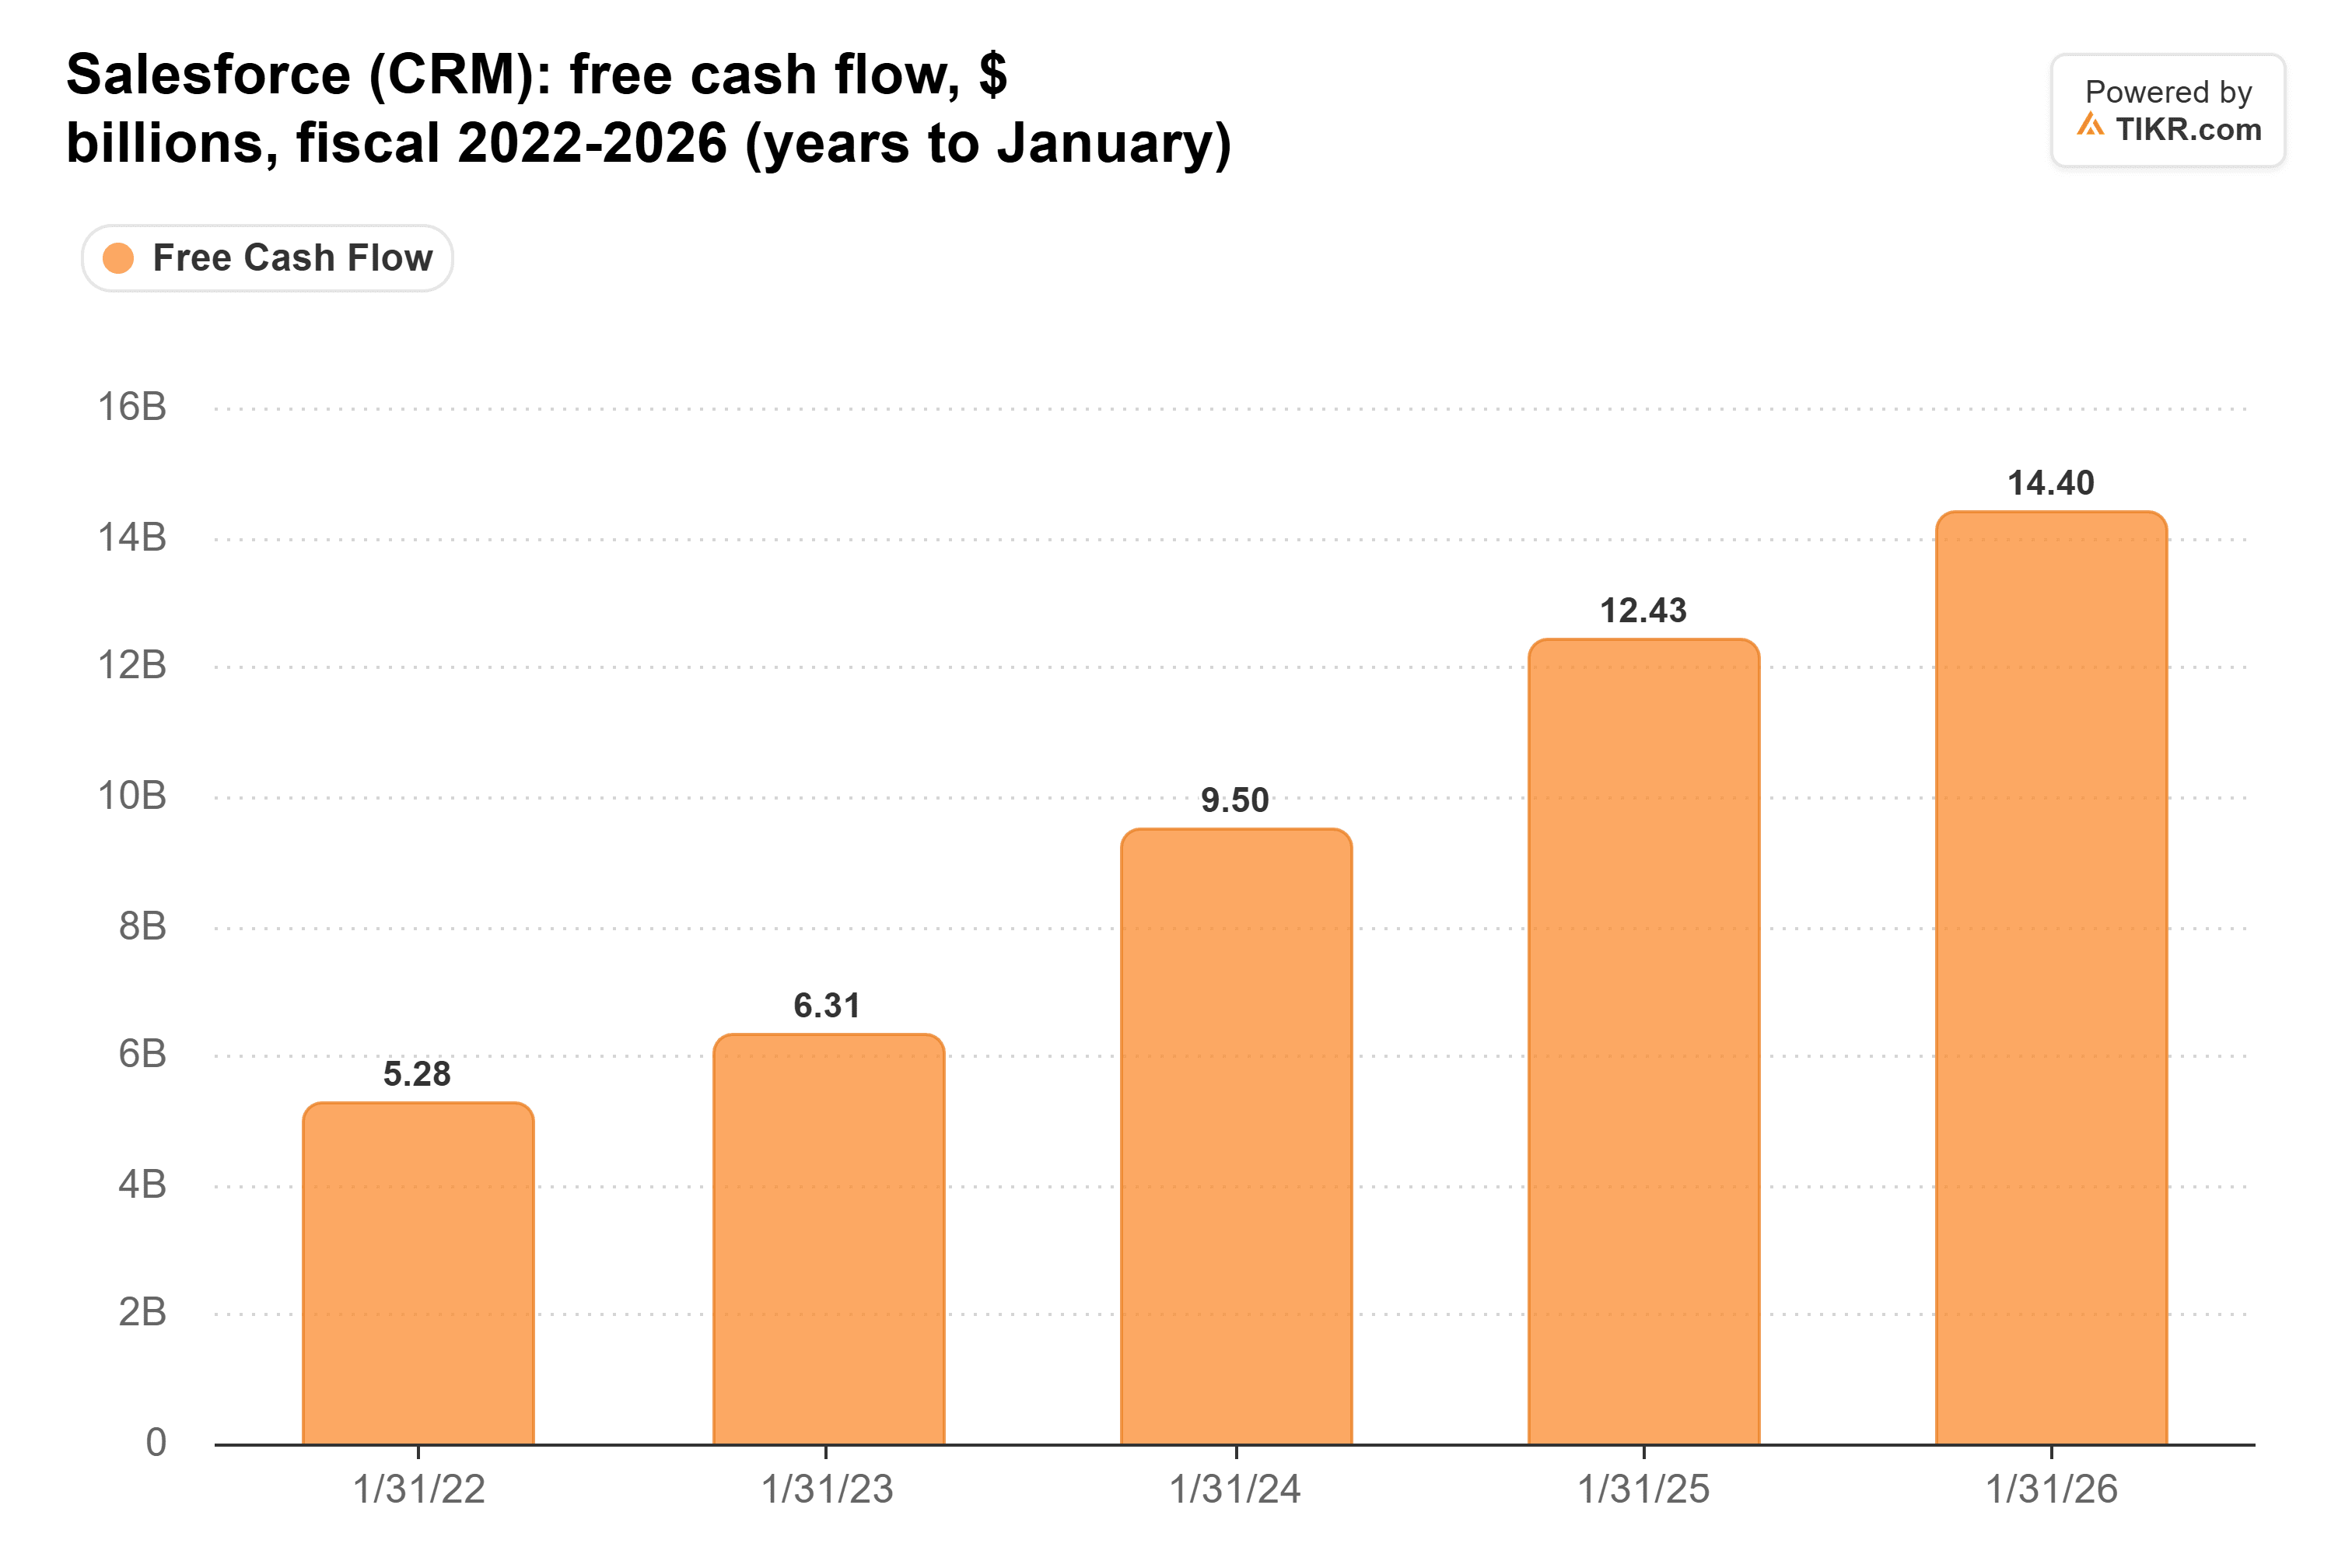
That’s the cash an agent doing the seat holder’s work would be competing for.
Salesforce still owns the records
Of course, the records live in Salesforce, and so do the contracts. On the second-quarter call, management said seats grew year over year in Sales, Service and Slack, and attrition is near its lowest level. Plus: Salesforce owns a piece of Anthropic, about 45% of its $11.3 billion portfolio of strategic investments at July 31. So when Anthropic wins, Salesforce shareholders get some of the upside.
The market already sees it
Salesforce trades at 15x forward earnings, about half its five-year average of 27x and not far above the 11x it hit in June.
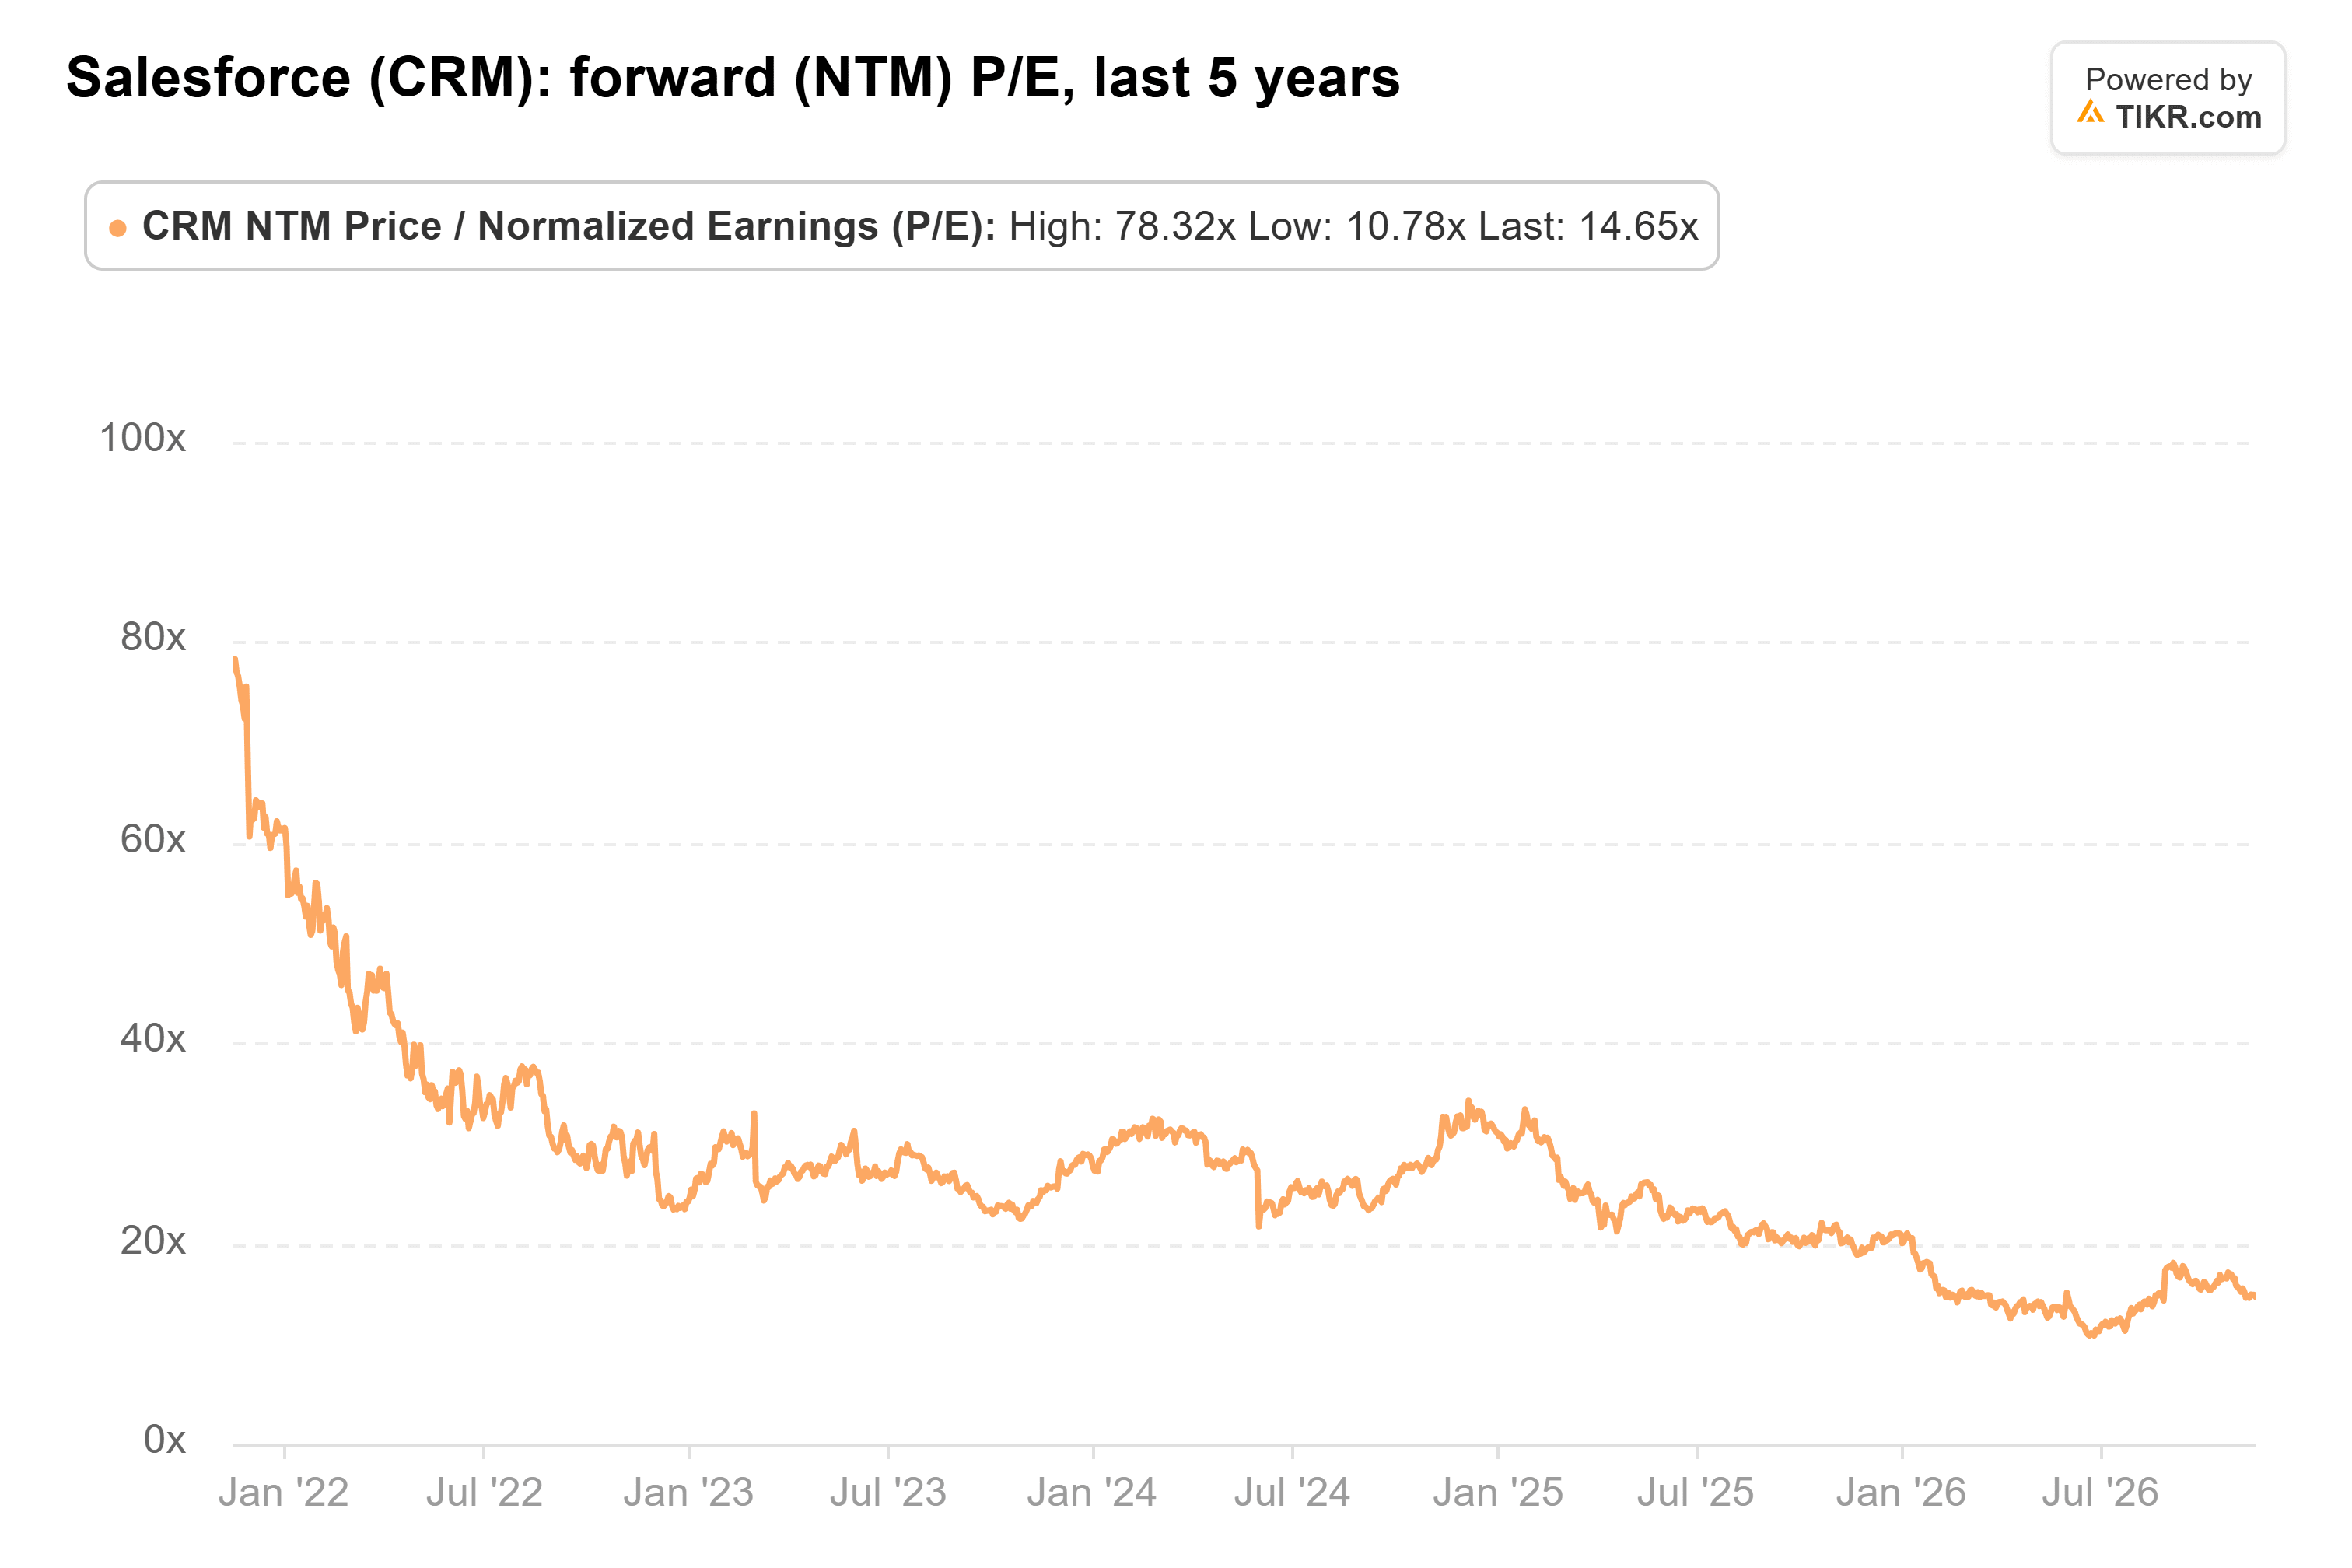
The labs don’t have to destroy Salesforce to hurt the stock. They only need a say in where the work happens, and so in what a seat is worth. I think that’s why it sits at 15x, and I wouldn’t count on a move back toward 27x until Salesforce shows it can charge for the open door.
The first test is the third-quarter report on Dec. 2. Revenue needs to land at or above the $11.42 billion low end of guidance, growth excluding the Informatica acquisition needs to be clearly above the second quarter’s 6%, and management needs to report seat growth again. If all three come through, 15x could look cheap quickly, since the earnings estimates behind it have been rising.
So what is Salesforce stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Salesforce could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!